
 Virtual and Augmented Reality in Tourism Market | 2026-2036
Virtual and Augmented Reality in Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual and Augmented Reality in Tourism Market Insights
Platform bundling of VR headsets with destination content libraries is expanding buyer choice beyond standalone hardware purchases. Meta Platforms leverages its social media ecosystem to distribute immersive travel experiences directly to existing user bases. Google anchors its position through geospatial data integration that powers AR overlay accuracy for urban tourism navigation. Sony Corporation differentiates via entertainment-grade display technology originally developed for gaming headsets now repurposed for virtual museum walkthroughs.
Virtual and augmented reality in tourism denotes the use of immersive computing systems—comprising stereoscopic displays with 90Hz refresh rates, six-degrees-of-freedom tracking, and spatial audio rendering—to simulate or enhance physical travel environments for pre-trip planning, on-site guidance, or remote accessibility. These systems serve the commercial purpose of reducing decision friction in booking journeys and extending visitor engagement beyond geographic constraints. VR Headsets capture the largest share of hardware value as enterprise procurement cycles favor dedicated devices over consumer smartphones for attraction deployments. Digital Tours represent the fastest-expanding service layer as cloud streaming eliminates local storage limitations and enables real-time content updates for seasonal exhibitions. SLAM technology underpins indoor positioning accuracy where GPS signals degrade, creating a defensible margin pool for vendors with proprietary mapping databases.
The EU AI Act classifies biometric emotion recognition in immersive tourism as high-risk, forcing operators to implement explicit consent workflows before deploying gaze-tracking analytics. FCC equipment authorization requirements in the United States govern wireless transmission protocols for untethered headsets used in outdoor guided experiences. GDPR data localization rules limit cross-border transfer of tourist behavioral data captured during European virtual site visits. Stakeholders must monitor how emerging neurodata privacy legislation reclassifies brain-computer interface inputs from experimental peripherals to regulated biometric categories.
Market Dynamics
Cloud streaming infrastructure is compressing content delivery timelines for immersive tourism operators, eliminating local storage dependencies and enabling real-time seasonal updates for heritage sites and museums.
Growth Catalysts
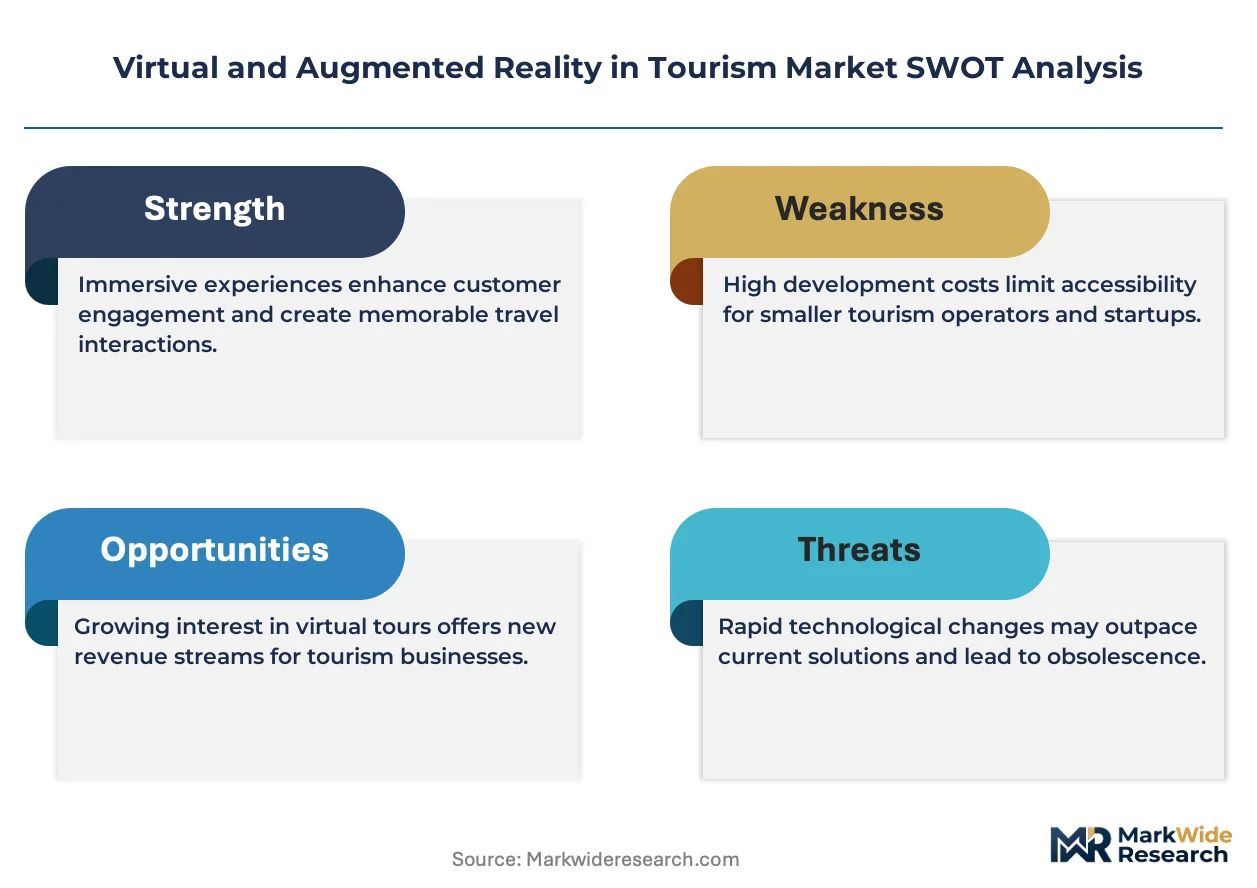
- EU AI Act compliance frameworks:Heritage preservation agencies across France, Italy, and Greece now mandate immersive pre-visit experiences to reduce physical foot traffic at fragile archaeological sites.
- Six-degrees-of-freedom tracking:Enterprise procurement cycles favor dedicated VR headsets with full positional tracking over consumer smartphones for attraction deployments.
- Spatial audio rendering:Museum networks in the United States integrate 3D audio environments to extend visitor engagement beyond geographic constraints.
Market Restraints
- Biometric data localization:GDPR rules limit cross-border transfer of tourist behavioral data captured during European virtual site visits, fragmenting analytics infrastructure.
- SLAM mapping concentration:Proprietary indoor positioning databases remain concentrated among a handful of geospatial vendors, inflating licensing costs for mid-sized attractions.
- Wireless protocol certification:FCC equipment authorization timelines for untethered outdoor headsets create deployment delays for guided nature experiences.
Strategic Opportunities
- Neurodata privacy legislation:Emerging regulatory frameworks reclassifying brain-computer interface inputs create first-mover advantage for compliant biometric consent workflows.
- AR urban navigation:Geospatial data integration enables overlay accuracy improvements for city walking tours in Barcelona, Amsterdam, and Kyoto.
- Platform bundling models:Social media distribution ecosystems now package destination content libraries directly to existing user bases, bypassing hardware retail channels.
Industry Challenges
- Immersive content production pipelines:Photogrammetry and volumetric capture workflows require specialized talent scarce outside gaming and film verticals.
- Cross-jurisdiction biometric consent:Operators must maintain parallel consent architectures for EU AI Act high-risk classifications and emerging neurodata categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual and Augmented Reality in Tourism Market |
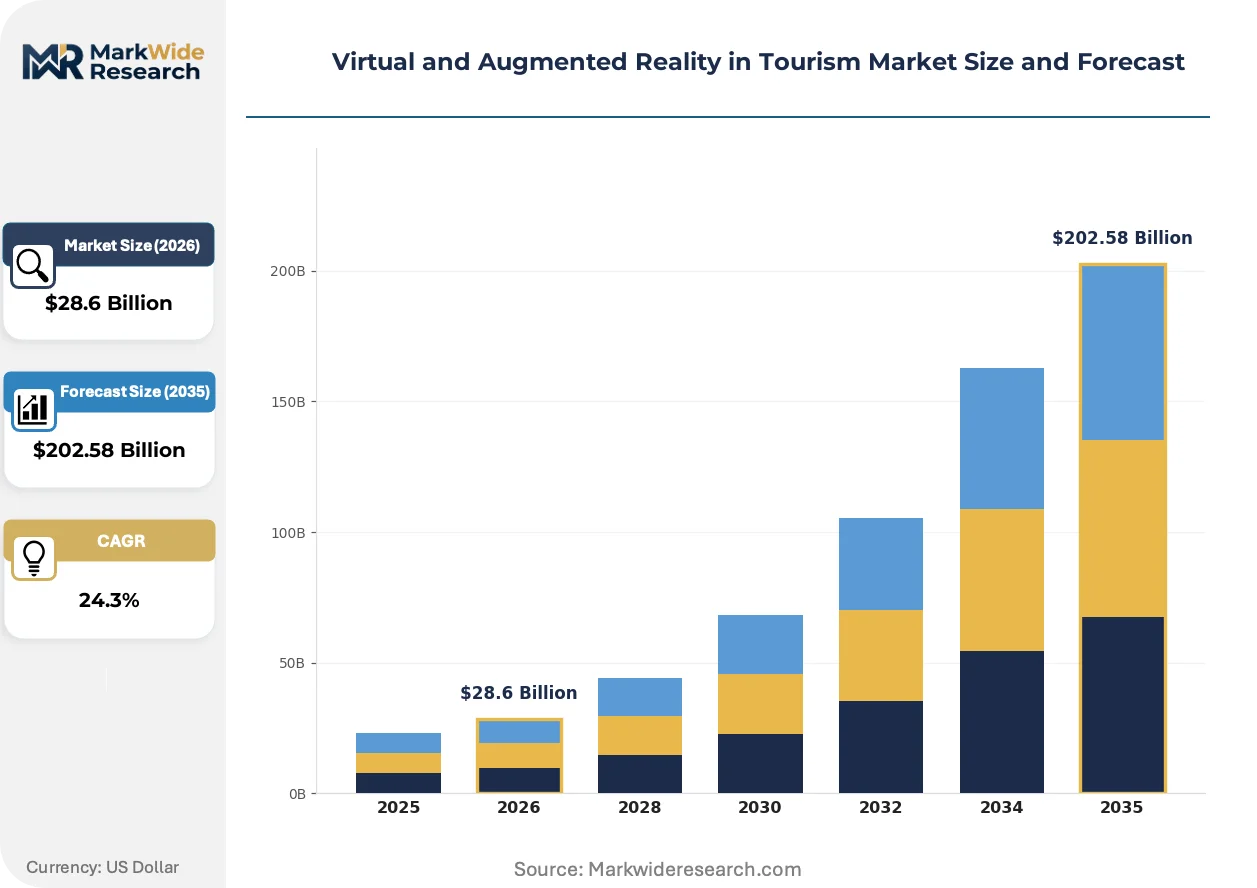
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $202.58 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VR Headsets, AR Glasses, Mobile Apps, Digital Tours Technology: SLAM, 3D Mapping, Motion Tracking, Geolocation End User: Travel Agencies, Tour Operators, Hotels, Attractions Distribution Channel: Online Platforms, Retail Stores, Direct Sales, Mobile Distribution |
| Companies Covered | Google, Meta Platforms, Microsoft, Apple, Sony Corporation, HTC Corporation, Expedia Group, National Geographic, Unity Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual and Augmented Reality in Tourism Market Trends and Innovations
Real-time cloud rendering is dissolving the boundary between pre-trip planning and on-site experience, enabling seamless handoffs between home-based VR preview and destination AR guidance.
Photorealistic volumetric capture is unifying heritage documentation with visitor-facing content production. Italian archaeological conservatories now scan excavation sites once for both preservation archives and public virtual walkthroughs. This convergence compresses content production cycles from months to days while elevating fidelity standards across both scientific and commercial applications.
The EU AI Act's high-risk classification for biometric emotion recognition is forcing explicit consent workflows into every gaze-tracking deployment. German museum networks now segment analytics permissions from core navigation functions. French operators lead implementation, with CNIL guidance shaping technical architectures that other European heritage sites adopt.
Visitor booking patterns now compress research and purchase into single-session journeys. United States national park systems report shorter consideration cycles as immersive previews replace traditional photography and video. Younger demographics skip intermediary travel platforms entirely, accessing destination experiences through social distribution channels where content discovery and transaction occur simultaneously.
Virtual and Augmented Reality in Tourism Market Segmentation
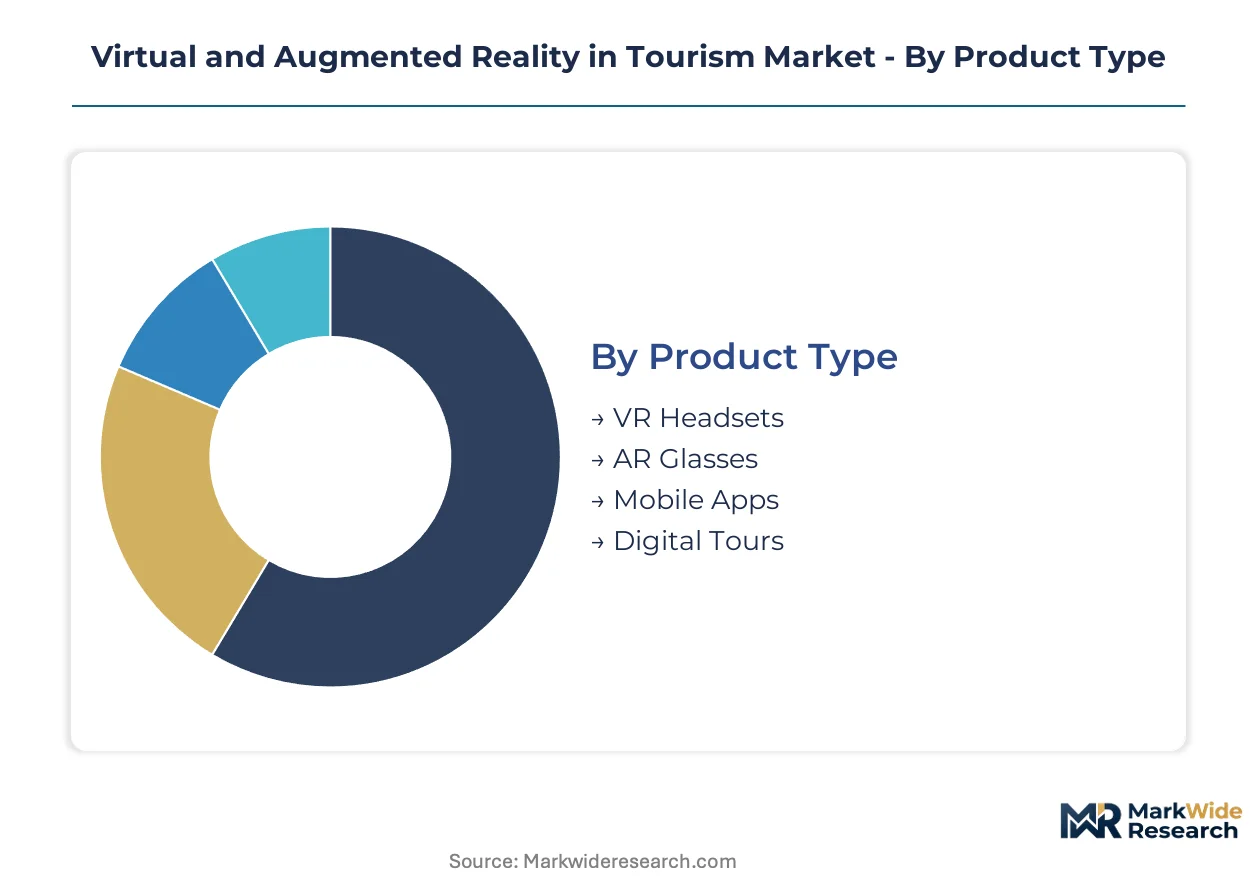
Hardware certification timelines and data privacy compliance requirements fragment procurement patterns across the immersive tourism value chain. Operators select product categories based on deployment environment constraints, from FCC-authorized outdoor headsets to GDPR-compliant indoor analytics systems.
Product Type:
CE marking for ocular safety and FCC equipment authorization create divergent regulatory burdens across hardware categories, with dedicated headsets facing longer approval cycles than smartphone-dependent applications.
- VR Headsets:Stereoscopic displays with 90Hz refresh rates and six-degrees-of-freedom tracking require FCC authorization for wireless transmission protocols in outdoor guided experiences. Enterprise procurement at United States national park systems favors these dedicated devices for full positional accuracy in untethered deployments.
- Digital Tours:Cloud-streamed content delivery eliminates local storage dependencies and enables real-time seasonal updates for heritage sites. French museum networks deploy these fastest as GDPR data localization rules limit cross-border transfer of behavioral analytics captured during virtual visits.
- AR Glasses:Optical see-through displays with SLAM-based spatial anchoring demand CE marking compliance for eye safety in European urban navigation deployments.
- Mobile Apps:Smartphone-dependent AR overlays bypass hardware certification cycles but face app store content restrictions for biometric data collection.
Leading the category by volume: VR Headsets. Growing fastest: Digital Tours.
Technology:
Patent concentration and proprietary database ownership determine licensing economics, with SLAM vendors commanding premium fees for indoor positioning accuracy where GPS signals degrade.
- SLAM:Simultaneous localization and mapping algorithms power indoor positioning accuracy in museum complexes and archaeological sites. Proprietary mapping databases remain concentrated among geospatial vendors in Germany and the Netherlands, inflating licensing costs for mid-sized European attractions.
- 3D Mapping:Photogrammetry and volumetric capture workflows compress heritage documentation and visitor-facing content production into unified pipelines. Italian archaeological conservatories now scan excavation sites once for both preservation archives and public virtual walkthroughs.
- Motion Tracking:Six-degrees-of-freedom sensor fusion enables full body presence in multiplayer virtual destination previews.
- Geolocation:GPS augmentation with cellular positioning supports urban AR navigation accuracy in Barcelona and Amsterdam historic districts.
Widest deployment: SLAM. Steepest expansion trajectory: 3D Mapping.
End User:
Customer scale and technical staffing depth determine whether deployments favor turnkey solutions or customizable platforms with dedicated IT support.
- Attractions:Museum networks and heritage sites deploy immersive pre-visit experiences to reduce physical foot traffic at fragile environments. United States national park systems pioneer large-scale VR destination marketing with shorter visitor consideration cycles replacing traditional photography.
- Hotels:Property-based virtual room previews and AR concierge services integrate with existing booking engines. Spanish and Greek resort operators lead adoption for pre-arrival upselling of experience packages.
- Travel Agencies:Commission-based intermediaries access destination content through social media distribution ecosystems rather than hardware retail channels.
- Tour Operators:Guided experience providers face FCC equipment authorization delays for untethered outdoor headset deployments in remote nature locations.
Dominant volume share: Attractions. Gaining share fastest: Hotels.
Distribution Channel:
Platform control over user data and transaction economics shifts power toward social media ecosystems that bundle content discovery with booking completion.
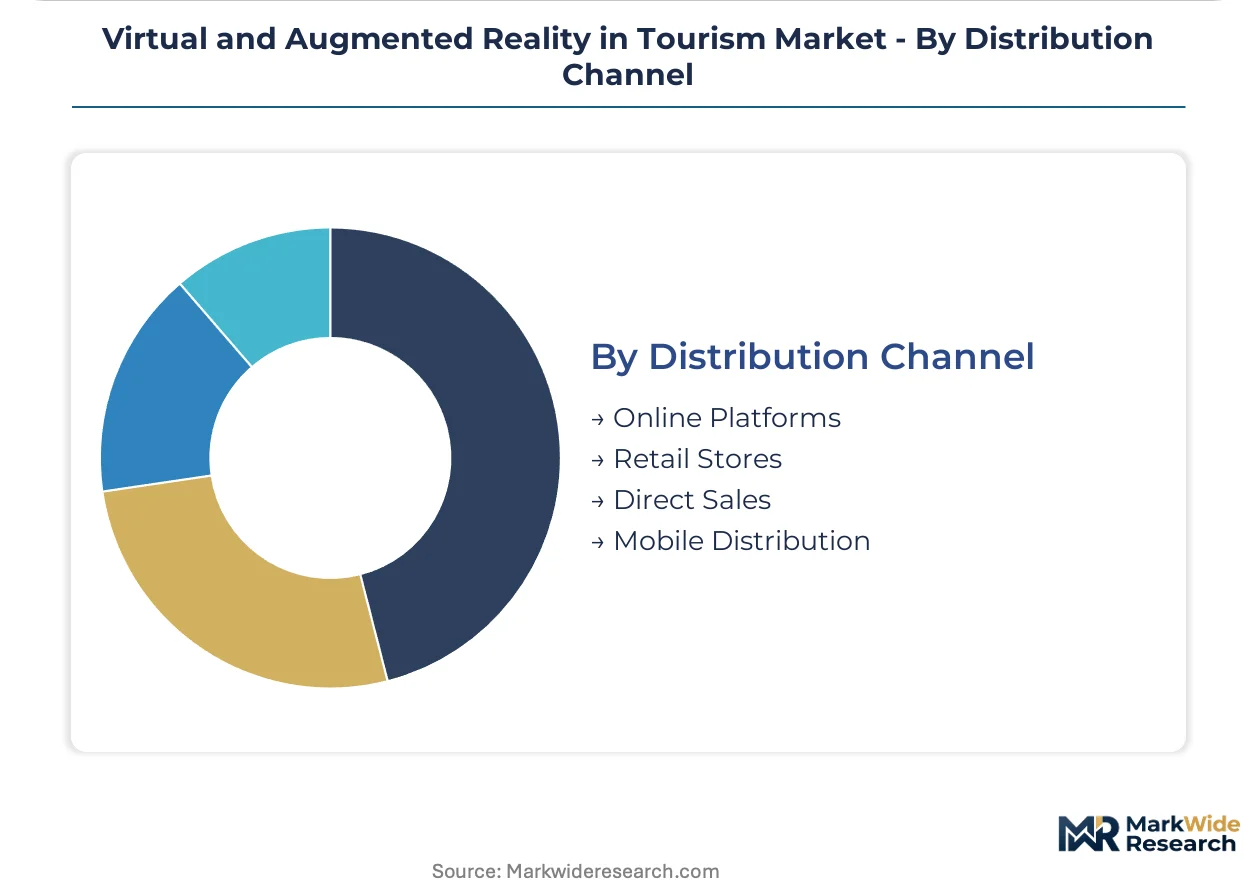
- Online Platforms:Cloud-based content libraries enable subscription access to destination portfolios without hardware ownership. Meta Platforms leverages its social media ecosystem to distribute immersive travel experiences directly to existing user bases, bypassing retail intermediaries.
- Mobile Distribution:App store channels capture younger demographics who skip intermediary travel platforms entirely. Japanese and South Korean operators report highest conversion rates where content discovery and transaction occur simultaneously in single-session journeys.
- Direct Sales:Enterprise procurement cycles for dedicated VR headsets favor vendor relationships with technical support and bulk pricing.
- Retail Stores:Consumer hardware purchases concentrate in urban markets with established electronics retail infrastructure.
Highest transaction volume: Online Platforms. Expanding most quickly: Mobile Distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware production clusters concentrate in East Asia while consumption-driven deployments dominate North American and European heritage institutions. This geographic split shapes divergent regulatory compliance burdens and procurement patterns across the value chain.
United States
National park systems deploy FCC-authorized untethered headsets for outdoor guided experiences, shortening visitor consideration cycles through immersive previews. The FCC governs wireless transmission protocols for outdoor equipment. California-based technology clusters supply cloud streaming infrastructure to museum networks nationwide.
Germany
Museum networks segment analytics permissions from core navigation functions under CNIL-influenced GDPR architectures. The EU AI Act classifies biometric emotion recognition as high-risk, mandating explicit consent workflows. Bavarian geospatial vendors command premium licensing fees for proprietary SLAM mapping databases.
France
Heritage preservation agencies mandate immersive pre-visit experiences to reduce physical foot traffic at fragile archaeological sites. CNIL guidance shapes technical architectures that other European operators adopt. Parisian museum complexes pioneer cloud-streamed digital tours with real-time seasonal content updates.
Italy
Archaeological conservatories scan excavation sites once for unified preservation archives and public virtual walkthroughs. GDPR data localization rules limit cross-border transfer of behavioral analytics. Roman and Florentine heritage clusters compress photogrammetry production cycles from months to days.
Japan
Mobile distribution channels capture younger demographics through simultaneous content discovery and transaction completion. METI standards influence spatial computing hardware specifications for tourism applications. Tokyo-Osaka corridor operators report highest conversion rates for app-based AR urban navigation.
Virtual and Augmented Reality in Tourism Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, platform, and content layers. Technology giants leverage existing ecosystems to distribute immersive experiences directly to user bases, while specialized vendors concentrate on geospatial accuracy or entertainment-grade display fidelity. Three archetypes dominate: ecosystem bundlers with social distribution networks, geospatial data integrators with mapping supremacy, and entertainment technology repurposers from adjacent gaming verticals. Competitive moves center on platform bundling partnerships and proprietary SLAM database accumulation.
Among ecosystem-driven conglomerates, Meta Platforms and Google occupy positions spanning hardware, platform, and distribution. Sony Corporation exemplifies the entertainment-technology repurposer archetype, translating gaming headset display innovations into museum walkthrough applications. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Meta Platforms |
| Microsoft |
| Apple |
| Sony Corporation |
| HTC Corporation |
| Expedia Group |
| National Geographic |
| Unity Technologies |
| Others |
Pricing and Supply Chain Analysis
Cloud streaming infrastructure compression is simultaneously collapsing content delivery costs and consolidating bargaining power among hyperscale platform operators. This dual compression forces mid-sized heritage attractions to choose between subscription dependency and capital-intensive in-house rendering farms.
Pricing Analysis
Margin tightening in enterprise VR hardware reflects FCC certification bottlenecks for untethered outdoor headsets. Three-tier pricing structure across premium, standard, and economy levels separates entertainment-grade displays from commercial SLAM-integrated units from smartphone-dependent applications. Price differentiation hinges on CE marking tier for ocular safety and volume procurement scale. Small museum networks exhibit highest price sensitivity, while United States national park systems absorb premium positioning for full six-degrees-of-freedom deployments.
Supply Chain Analysis
CE marking and FCC equipment authorization gates fragment component sourcing across divergent regulatory clusters. Display panel production concentrates in South Korea and Japan, while SLAM algorithm development clusters in Germany and the Netherlands. Supply chains draw from specialized photogrammetry talent pools scarce outside Italian and French heritage documentation centers. Single-source vulnerability persists in proprietary indoor mapping databases. Distribution runs through cloud platform ecosystems that bundle content libraries with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time cloud rendering is displacing local storage infrastructure, compressing the technology transition window for operators still dependent on edge-based content pipelines.
For Market Incumbents: Deepen proprietary SLAM database accumulation to defend licensing revenue against open-source alternatives. Consolidate photogrammetry talent through acquisition of Italian and French heritage documentation studios. Vertical integration into cloud streaming infrastructure offsets platform dependency risk from Meta and Google ecosystem bundling.
For New Entrants and Emerging Players: Launch via mobile distribution channels targeting Japanese and South Korean demographics where content discovery and transaction completion converge. White-space opportunity sits in GDPR-compliant analytics segmentation for French museum networks. Target mid-sized European attractions underserved by geospatial vendor licensing concentration.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform bundling acquisitions by social media ecosystems and geospatial data integrators. Five-to-ten year viability favors vendors with captive SLAM mapping databases and FCC-authorized outdoor hardware certifications. Watch for CNIL guidance expansion as inflection signal for EU AI Act compliance tooling demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Bundling Partnership | Meta's social distribution ecosystem bypasses hardware retail intermediaries for destination content. |
| Proprietary SLAM Database Accumulation | German and Dutch geospatial vendors command premium licensing fees for indoor positioning accuracy. |
| GDPR-Compliant Analytics Segmentation | French museum networks segment permissions from navigation functions under CNIL-influenced architectures. |
| Cloud Streaming Infrastructure Investment | California-based technology clusters supply real-time seasonal updates to United States museum networks. |
| Photogrammetry Talent Acquisition | Italian archaeological conservatories compress production cycles through unified preservation and visitor content pipelines. |
Research Methodology
Independent corroboration across heritage preservation agency procurement officers, museum network technology directors, and VR hardware manufacturer product managers underwrites the qualitative findings. Primary interviews with geospatial vendor licensing specialists and FCC certification consultants combined with secondary validation from EMA submissions, CE marking databases, and hyperscaler capex disclosures. Bottom-up attraction deployment counts triangulate against top-down platform revenue disclosures.
Rate-of-change decomposition across hardware refresh cycles, content production timelines, and regulatory implementation phases structures the analytical framework. Segmentation dimensions span product type, technology layer, end-user scale, and distribution channel complexity. CAGRs derive from installed base growth curves and average revenue per deployment trajectories. Industry-specific inputs include SLAM licensing fee trends and FCC authorization timeline distributions.
EU AI Act enforcement delays, neurodata privacy legislation emergence, and cloud platform pricing volatility are the dominant revision risks. Forecasts embody assumptions regarding biometric consent workflow adoption rates and heritage site digitization budget allocations. A model refresh is warranted upon material change in CNIL guidance scope or FCC equipment authorization backlog duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market