
 Virtual Visor Market | 2026-2036
Virtual Visor Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Visor Market Insights
NHTSA's updated glare-reduction standards for forward visibility is expanding compliance costs for conventional visor suppliers. Robert Bosch GmbH leverages its sensor-integration expertise to embed camera-driven adaptive shading into premium vehicle lines. Magna International Inc. anchors North American production through captive manufacturing of electrochromic assemblies. Kasai Kygo Co. Ltd. specializes in thin-film deposition techniques that enable curved-form-factor LCD visors for Asian OEM programs.
A virtual visor is an electronically modulated optical device that replaces or supplements traditional mechanical sun visors through pixel-level light attenuation, typically employing electrochromic, liquid-crystal, or micro-shutter arrays with response times under 50 milliseconds. The technology's primary purpose is to eliminate transient driver blindness from solar glare and oncoming headlamps while preserving forward road visibility. The adaptive visor product category leads current revenue contribution due to its integration feasibility within existing headliner architectures, while augmented reality glasses represent the fastest-growing segment as military and aviation end users demand helmet-mounted situational awareness overlays. OLED technology dominates prototype development for its contrast ratio and form-factor flexibility, though LCD sustains volume production because of established automotive supply chains and temperature resilience.
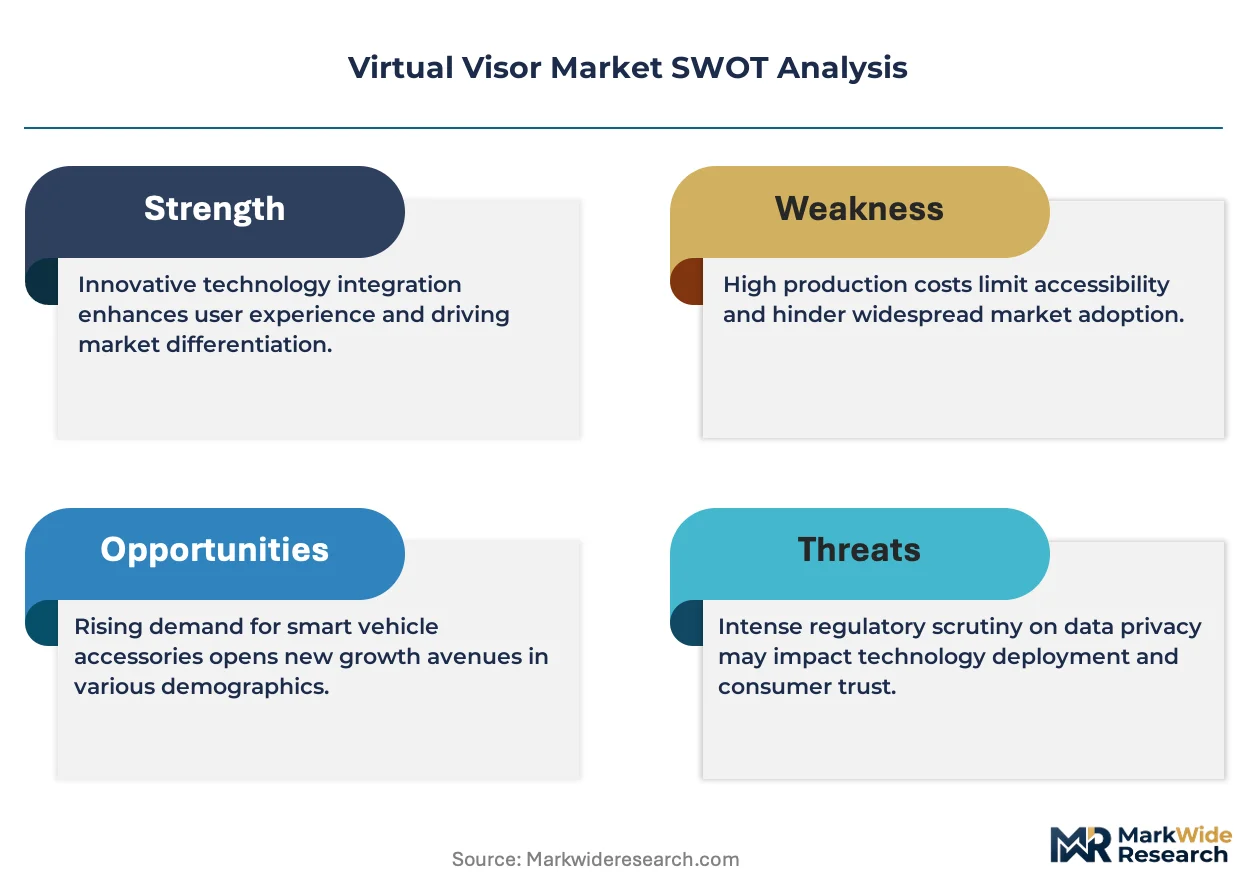
FDA scrutiny of optical-radiation exposure limits is shaping safety certification pathways for extended-wear AR visor variants in commercial aviation. ECHA REACH compliance is forcing reformulation of electrochromic gel chemistries to eliminate restricted substances from European-bound components. The EU AI Act's risk-classification framework will soon govern autonomous glare-prediction algorithms embedded in smart windshield systems. Stakeholders must monitor whether NHTSA, ECHA, and the EU AI Act create divergent testing protocols that fragment product development roadmaps.
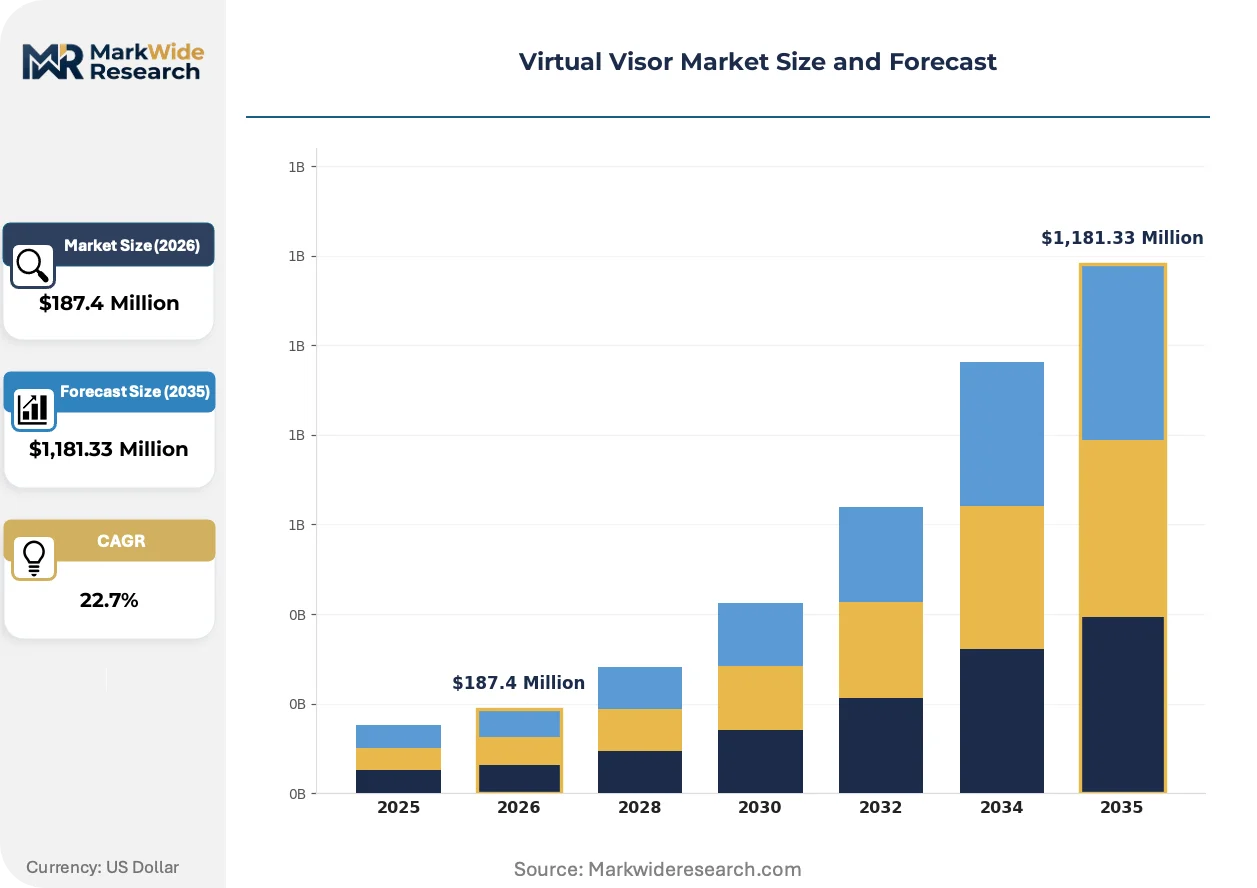
Market Dynamics
The automotive sector's pivot toward intelligent cabin systems is compressing development timelines for adaptive visor suppliers. Tier-1 integrators must now synchronize electrochromic and liquid-crystal roadmaps with OEM software-release cycles that previously operated on separate tracks.
Growth Catalysts
- NHTSA glare-reduction mandates:Updated forward-visibility standards are compelling OEMs to replace mechanical visors with electronically modulated alternatives that guarantee sub-50-millisecond response times.
- Electrochromic gel chemistry advances:Thin-film deposition breakthroughs enable curved-form-factor LCD visors that conform to windshield geometries previously unreachable by flat-panel designs.
- Military aviation procurement:Helmet-mounted situational awareness overlays are accelerating augmented-reality visor adoption for pilot training and combat operations.
Market Restraints
- Automotive-grade temperature resilience:Liquid-crystal matrices require reformulation to maintain optical performance across -40°C to 85°C operational envelopes, elevating qualification costs.
- ECHA REACH substance restrictions:Electrochromic gel chemistries containing restricted halogenated compounds face mandatory reformulation for European-bound components.
- Windshield-integrated HUD substitution:Head-up display projection systems that embed glare suppression algorithms threaten standalone visor attach rates in premium vehicle segments.
Strategic Opportunities
- Commercial aviation certification pathway:FDA optical-radiation exposure protocols for extended-wear AR visors create first-mover advantage for suppliers achieving commercial pilot program approval.
- EU AI Act algorithmic governance:Autonomous glare-prediction software embedded in smart windshield systems falls under emerging risk-classification frameworks that reward early compliance investment.
- Electrochromic-LCD convergence:Hybrid architectures combining electrochromic speed with LCD manufacturing scale offer entry into mid-market vehicle lines previously cost-prohibitive for adaptive visors.
Industry Challenges
- Optical-engineering talent scarcity:The intersection of thin-film physics, automotive qualification protocols, and real-time image processing commands premium compensation that strains mid-tier supplier budgets.
- Dual certification timelines:Simultaneous NHTSA safety validation and ECHA chemical compliance extends product launch windows by 18-24 months versus single-market introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Visor Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heads-Up Display, Adaptive Visor, Smart Windshield, Augmented Reality Glasses Technology: OLED, LCD, DLP, LCoS End User: Automotive OEMs, Tier-1 Suppliers, Aftermarket Providers, Commercial Fleets Application: Passenger Vehicles, Commercial Vehicles, Aviation, Military |
| Companies Covered | Atlas Holdings, Kasai Kygo Co. Ltd., Robert Bosch GmbH, KÖBO GmbH & Co. KG, Weetect, Magna International Inc., Sunvisors India Private Limited, Visor-AR, Irvine Automotive Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Visor Market Trends and Innovations
Pixel-level light modulation is migrating from premium automotive into adjacent mobility verticals. The convergence of electrochromic speed, LCD manufacturing maturity, and augmented-reality overlay capability is redefining supplier capability requirements.
Micro-shutter array technology is expanding into military aviation helmet systems. Defense procurement offices in the United States and select NATO members are field-testing visors that combine glare suppression with tactical data projection. The structural consequence is compressing the supplier base toward firms possessing both optical-modulation and defense-electronics pedigrees.
ECHA REACH substance restrictions are forcing electrochromic gel reformulation across European supply chains. Manufacturers dependent on legacy halogenated chemistries face qualification restart costs that disproportionately burden smaller component suppliers. The segment most affected is aftermarket replacement visors, where price sensitivity limits pass-through of reformulation expenses.
Buyer concentration among German premium OEMs is reshaping supplier negotiation leverage. Bosch and Magna now dictate electrochromic assembly specifications that cascade through tier-2 and tier-3 vendors. This pattern is most visible in Stuttgart and Munich supplier clusters, where captive manufacturing investments have consolidated volume allocation decisions.
Virtual Visor Market Segmentation
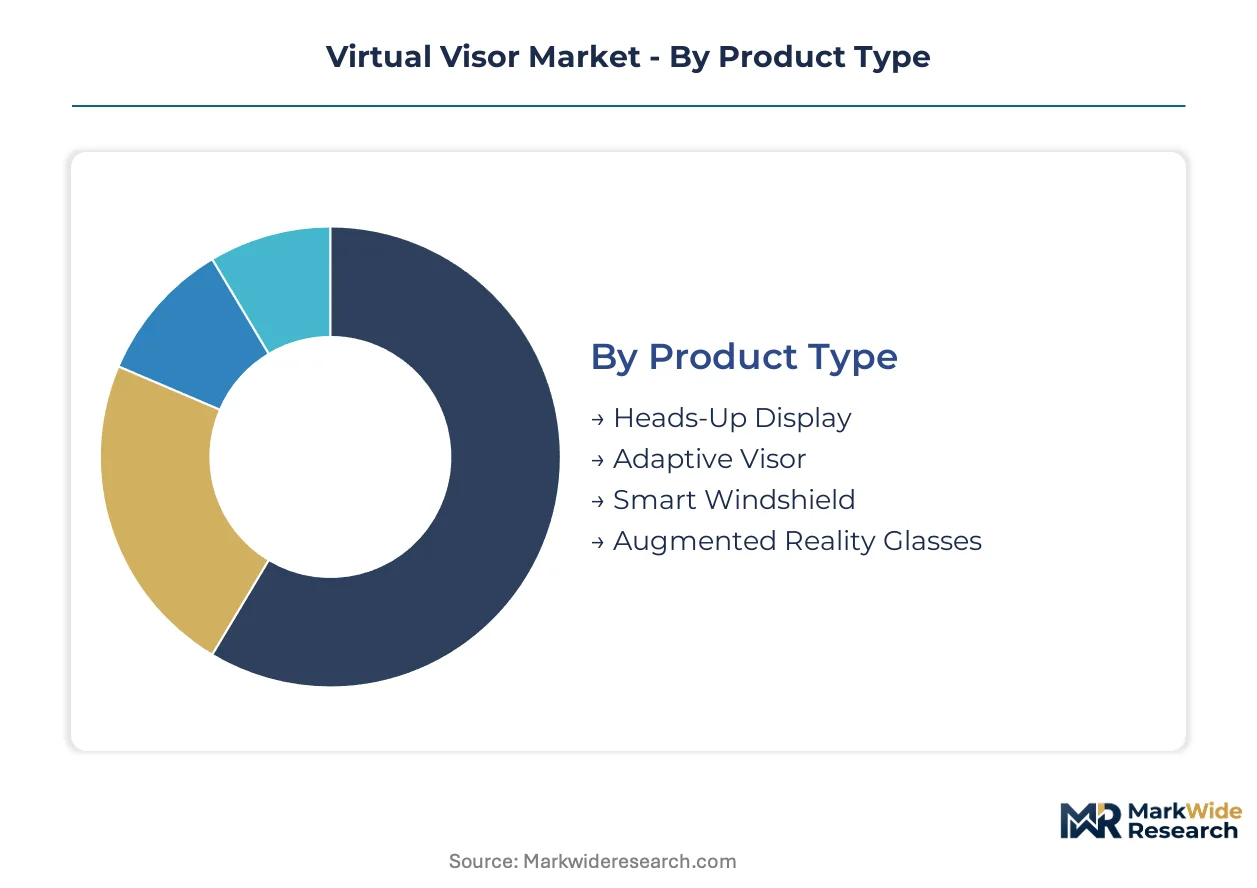
Virtual visor segmentation reveals divergent commercialization timelines across product architectures. Technology choices determine temperature resilience and form-factor constraints that lock suppliers into specific OEM qualification pathways.
Product Type:
Volume production concentrates in automotive-integrated systems while premium capture shifts toward helmet-mounted overlays for specialized operators.
- Adaptive Visor:Electrochromic and liquid-crystal matrices modulate pixel-level light attenuation through existing headliner mounting points. Automotive OEMs in Germany and Japan prioritize this format for its retrofit compatibility with legacy vehicle electrical architectures.
- Augmented Reality Glasses:Helmet-mounted waveguide displays overlay tactical data with glare suppression for military aviation and pilot training programs. Defense procurement offices in the United States and select NATO members are accelerating field-testing timelines for combined situational awareness systems.
- Heads-Up Display:Windshield-projected information layers reduce dependency on mechanical visor hardware in premium vehicle segments.
- Smart Windshield:Integrated electrochromic glazing eliminates separate visor components through full-field dimming across glass surfaces.
Mature deployment sits with Adaptive Visor. Newer deployment is concentrated in Augmented Reality Glasses.
Technology:
Manufacturing scale separates established automotive supply chains from emerging display formats seeking qualification.
- LCD:Established automotive-grade supply chains deliver temperature resilience from -40°C to 85°C through reformulated liquid-crystal matrices. Tier-1 integrators in North America and Germany anchor volume production for mid-market vehicle lines.
- OLED:Organic light-emitting diode stacks achieve superior contrast ratios and curved-form-factor flexibility for prototype development. Korean and Japanese display manufacturers dominate pilot programs targeting premium interior specifications.
- DLP:Digital micromirror projection enables high-brightness augmentation for aviation head-up applications.
- LCoS:Liquid-crystal-on-silicon microdisplays support compact helmet-mounted optics through reflective modulation architectures.
Volume leadership belongs to LCD. Technology transition pressure concentrates on OLED.
End User:
Procurement authority determines specification stringency and qualification timeline length.
- Automotive OEMs:Direct specification control over headliner integration, software-release synchronization, and glare-reduction performance mandates. German premium manufacturers in Stuttgart and Munich clusters dictate electrochromic assembly standards that cascade through captive supplier networks.
- Tier-1 Suppliers:Robert Bosch GmbH and Magna International Inc. consolidate electrochromic and liquid-crystal roadmaps under unified manufacturing investments.
- Aftermarket Providers:Price-sensitive replacement visor segments face disproportionate burden from ECHA REACH reformulation costs.
- Commercial Fleets:Fleet procurement offices prioritize durability and service-interval predictability over adaptive feature depth.
Specification control rests with Automotive OEMs. Margin compression targets Aftermarket Providers.
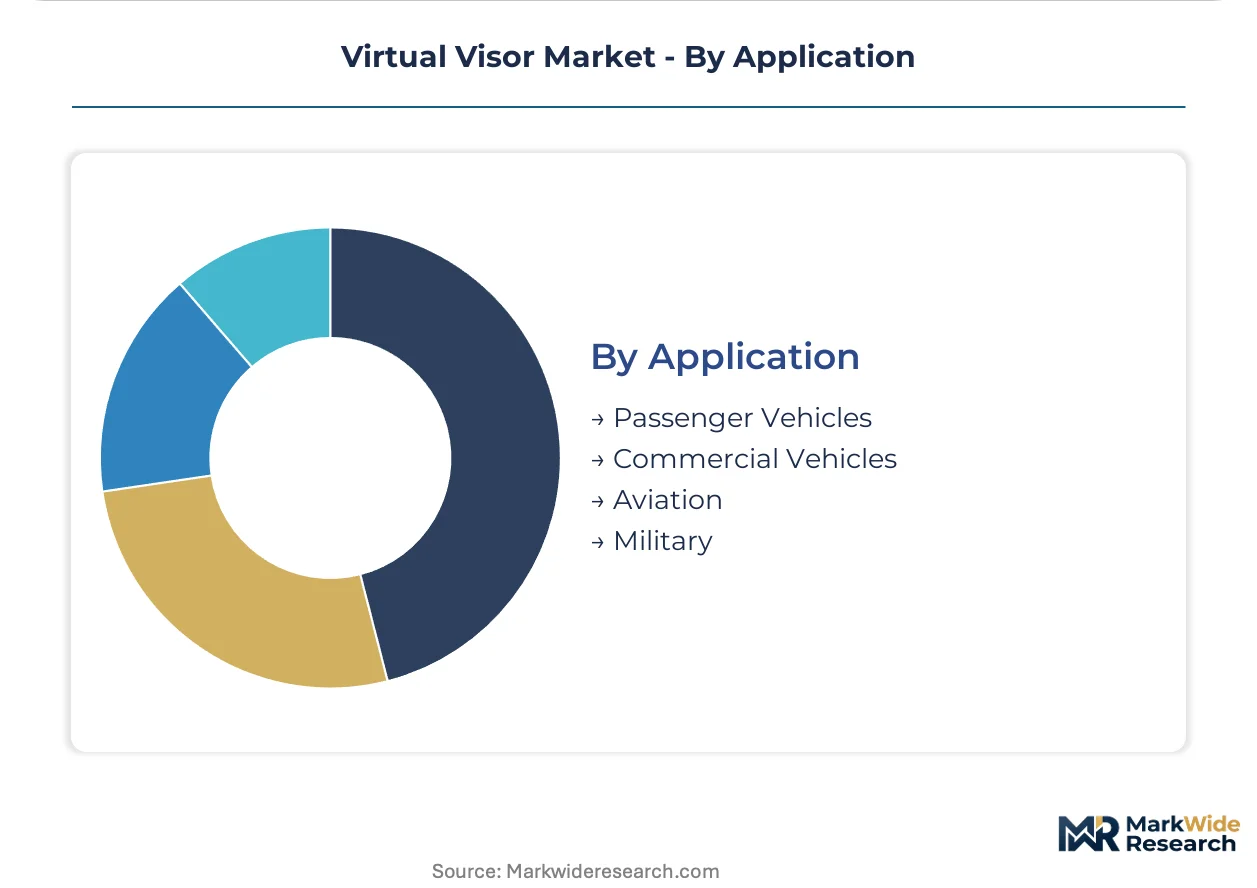
Application:
Operational environment dictates response-time requirements and certification pathway complexity.
- Passenger Vehicles:NHTSA glare-reduction mandates drive sub-50-millisecond response specifications for forward visibility compliance. US and European OEM integration programs dominate current revenue contribution.
- Military:Helmet-mounted tactical overlays combine glare suppression with real-time data projection for combat operations. Defense procurement offices demand dual-use optical-modulation and electronics capabilities that compress qualified supplier bases.
- Commercial Vehicles:Extended cab exposure hours elevate durability requirements for electrochromic gel longevity.
- Aviation:FDA optical-radiation exposure protocols for extended-wear AR visors create first-mover certification advantages for commercial pilot program approval.
Regulatory pressure concentrates in Passenger Vehicles. Steepest expansion trajectory is visible in Military applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in Germany, where Bosch and Magna anchor electrochromic visor development. Military aviation demand pulls toward US defense procurement offices. Asian display manufacturers in Japan and South Korea drive LCD and OLED technology roadmaps.
United States
NHTSA glare-reduction mandates compel OEMs to adopt sub-50-millisecond response visors for forward-visibility compliance. The FAA coordinates with FDA on optical-radiation exposure protocols for extended-wear AR visors in commercial aviation. Detroit-Warren-Dearborn automotive clusters host Tier-1 integration facilities for electrochromic assembly qualification.
Germany
Premium OEMs in Stuttgart and Munich dictate electrochromic assembly specifications that cascade through captive supplier networks. ECHA REACH compliance forces reformulation of electrochromic gel chemistries to eliminate restricted halogenated compounds from European-bound components. The EU AI Act's risk-classification framework governs autonomous glare-prediction algorithms embedded in smart windshield systems developed in Bavaria.
Japan
Kasai Kygo Co. Ltd. specializes in thin-film deposition techniques enabling curved-form-factor LCD visors for Asian OEM programs. METI standards guide automotive-grade temperature resilience requirements for liquid-crystal matrices. Nagoya-Toyota industrial corridors concentrate display manufacturing investments for mid-market vehicle line supply.
South Korea
Korean display manufacturers dominate OLED prototype development targeting premium interior specifications. The national automotive regulator enforces alignment with ECHA-equivalent substance restrictions for export-bound components. Seoul-Incheon metropolitan clusters anchor volume production of reformulated liquid-crystal matrices for -40°C to 85°C operational envelopes.
China
Domestic OEMs accelerate adoption of adaptive visor systems to meet evolving safety mandates in partnership with international Tier-1 suppliers. MIIT standards govern electromagnetic compatibility for electronically modulated optical devices. Yangtze River Delta manufacturing hubs concentrate thin-film deposition capacity for curved-form-factor visor exports.
Virtual Visor Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold curved-form-factor LCD expertise. The supplier base compresses toward firms possessing both optical-modulation capabilities and automotive qualification pedigrees. Three archetypes dominate: integrated Tier-1 electrochromic assemblers, thin-film deposition specialists, and defense-electronics dual-use operators. Strategic moves concentrate on captive manufacturing investments and electrochromic-LCD convergence partnerships.
Within the integrated Tier-1 tier, Robert Bosch GmbH exemplifies sensor-integration expertise applied to premium vehicle line supply, while Magna International Inc. occupies a position anchoring North American electrochromic assembly production. Kasai Kygo Co. Ltd. represents the thin-film deposition specialist archetype enabling curved-form-factor development for Asian OEM programs.
| Leading Market Players |
|---|
| Atlas Holdings |
| Kasai Kygo Co. Ltd. |
| Robert Bosch GmbH |
| KÖBO GmbH & Co. KG |
| Weetect |
| Magna International Inc. |
| Sunvisors India Private Limited |
| Visor-AR |
| Irvine Automotive Products |
| Others |
Pricing and Supply Chain Analysis
Electrochromic-LCD hybrid manufacturing scale-up simultaneously compresses unit economics and consolidates volume allocation toward German and South Korean production hubs. ECHA REACH reformulation mandates are elevating qualification costs that tier-2 suppliers struggle to absorb, amplifying pricing power asymmetry between integrated assemblers and component vendors.
Pricing Analysis
Volume leadership in mid-market adaptive visors trades at thinner margins than premium electrochromic assemblies for German OEM lines. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-certified automotive-grade units from aftermarket replacement segments and military aviation helmet systems. Price differentiation hinges on temperature resilience certification and software-release synchronization capability. Cost compression in aftermarket tiers is intensifying because ECHA compliance expenses cannot pass through to price-sensitive fleet buyers.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Munich automotive clusters, while tier-2 distributors serve aftermarket replacement segments. Geographic supply concentration centers on Germany for electrochromic assembly, Japan for thin-film deposition equipment, and South Korea for OLED prototype development. Raw material dependencies draw from indium tin oxide substrates, liquid-crystal matrix compounds, and reformulated electrochromic gel chemistries. Single-source vulnerability sits with halogen-free gel suppliers qualified for European-bound components. Distribution runs through captive manufacturing investments anchored by Bosch and Magna.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical-engineering talent scarcity props pricing for qualified suppliers across the analysis window. Thin-film physics expertise commands premium compensation that mid-tier vendors cannot match, entrenching incumbent advantage.
For Market Incumbents: Anticipate windshield-integrated HUD substitution by deepening software-defined vehicle integration partnerships that embed visor functionality into broader cockpit electronics architectures. Lock in electrochromic-LCD convergence roadmaps through captive R&D investments in Bavaria and Ontario to preempt margin erosion from hybrid technology commoditization. Prioritize ECHA pre-compliance certification to compress dual-market launch timelines versus competitors pursuing sequential NHTSA-then-REACH qualification. For New Entrants and Emerging Players: Micro-shutter array technology for military aviation helmet systems offers the most penetrable entry vector given defense procurement offices' explicit demand for dual-use optical-modulation and electronics capabilities. Target commercial aviation extended-wear AR visor segments where FDA optical-radiation exposure protocols create first-mover certification barriers for established automotive suppliers lacking aviation pedigree. Pursue partnership-based go-to-market models with Korean OLED manufacturers seeking curved-form-factor automotive qualification pathways. For Investors and Strategic Acquirers: Re-rating potential sits with thin-film deposition specialists given ECHA REACH reformulation catalysts forcing qualification restart costs upon legacy halogenated chemistry dependent competitors. Long-term viability over the next decade favors suppliers possessing both automotive-grade temperature resilience and defense-electronics dual-use capabilities. Monitor NHTSA software-release synchronization mandates as inflection indicator for which electrochromic assemblers secure platform-standardization wins with German premium OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochromic-LCD Convergence Partnership | Combines electrochromic response speed with LCD manufacturing scale for mid-market vehicle penetration. |
| ECHA Pre-Compliance Certification Investment | Eliminates 18-24 month dual-certification delays versus sequential NHTSA-then-REACH approaches. |
| Defense-Electronics Capability Acquisition | Compresses qualified supplier base for NATO military aviation helmet procurement programs. |
| Software-Defined Vehicle Integration | Embeds visor functionality into broader cockpit electronics to counter windshield-HUD substitution threat. |
| Curved-Form-Factor OLED Prototyping | Enables premium interior specifications demanded by Korean and Japanese display manufacturer pilot programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and thin-film deposition specialists combined with NHTSA safety validation databases, ECHA REACH substance restriction registries, and vehicle production databases. Bottom-up segment sizing triangulated against top-down automotive electronics spending patterns.
Data-stream reconciliation across electrochromic shipment volumes, liquid-crystal matrix procurement records, and OEM software-release timelines enabled forecast construction. Segmentation dimensions modeled include product architecture, display technology, end-user procurement authority, and application environment across the projection horizon. CAGRs derived from curve-fitting historical adoption patterns against regulatory mandate implementation schedules, with specific inputs from military aviation procurement acceleration and EU AI Act algorithmic governance timelines.
Several conditions sit outside the modeled scope, including potential NHTSA-EU AI Act testing protocol divergence, breakthrough solid-state electrochromic alternatives, and automotive OEM insourcing decisions. Forecasts reflect documented assumptions about regulatory implementation pacing and technology cost curves. Practitioners should monitor ECHA substance restriction list updates and German OEM captive manufacturing investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market