
 VR in Sports Market | 2026-2036
VR in Sports Market Size, Share, and Industry Trends Forecast 2026-2036
VR in Sports Market Insights
The VR in sports sector is restructuring around a widening gap between enterprise-grade training installations and mass-market fan entertainment headsets. Meta (Reality Labs) leverages its consumer hardware scale to dominate accessible price points for casual sports gaming. Varjo differentiates through retina-resolution displays that sustain premium pricing for professional athlete training environments. StatusPro anchors its position in NFL and MLB locker rooms by specializing in position-specific cognitive drills.
VR in sports encompasses immersive hardware and software systems that render three-dimensional athletic environments with sub-20ms motion-to-photon latency for real-time biomechanical feedback and tactical simulation. These systems serve commercial purposes spanning athlete skill acquisition, coach strategic planning, and spectator experiential marketing. Headsets capture the largest revenue pool among product types due to replacement cycles driven by display resolution upgrades. Training applications expand fastest within the application dimension as franchises replace physical repetitions with virtual ones to reduce injury exposure. Athletes represent the most concentrated end-user segment, though coaches and teams command higher per-account spending through institutional procurement.
The US Food and Drug Administration classifies certain VR rehabilitation systems as Class II medical devices, shaping product development pathways for injury recovery applications. The Federal Communications Commission governs wireless spectrum allocation for untethered headset operation in stadium and training facility deployments. ISO standards for eye-tracking safety and electromagnetic compatibility further constrain hardware design parameters. Stakeholders must monitor evolving classification boundaries between wellness-oriented training tools and regulated therapeutic devices.
Market Dynamics
Motion-to-photon latency compression below 20 milliseconds is bifurcating the VR in Sports market into tethered enterprise installations and untethered consumer headsets, forcing hardware vendors to choose between simulation fidelity and deployment flexibility.
Growth Catalysts
- Class II Medical Device Pathway:FDA clearance for VR rehabilitation systems expands reimbursable use cases beyond training into injury recovery, opening institutional procurement budgets previously restricted to wellness categories.
- Collegiate Athletic Investment:United States university athletic departments now allocate capital expenditure lines specifically for virtual preparation tools, creating a pipeline of demand that professionalizes before athletes reach commercial leagues.
- Haptic Feedback Glove Maturation:Advances in force-feedback exoskeleton gloves enable realistic bat-racket-ball sensation transfer, converting skeptical coaching staffs into system advocates through measurable reaction-time improvements.
Market Restraints
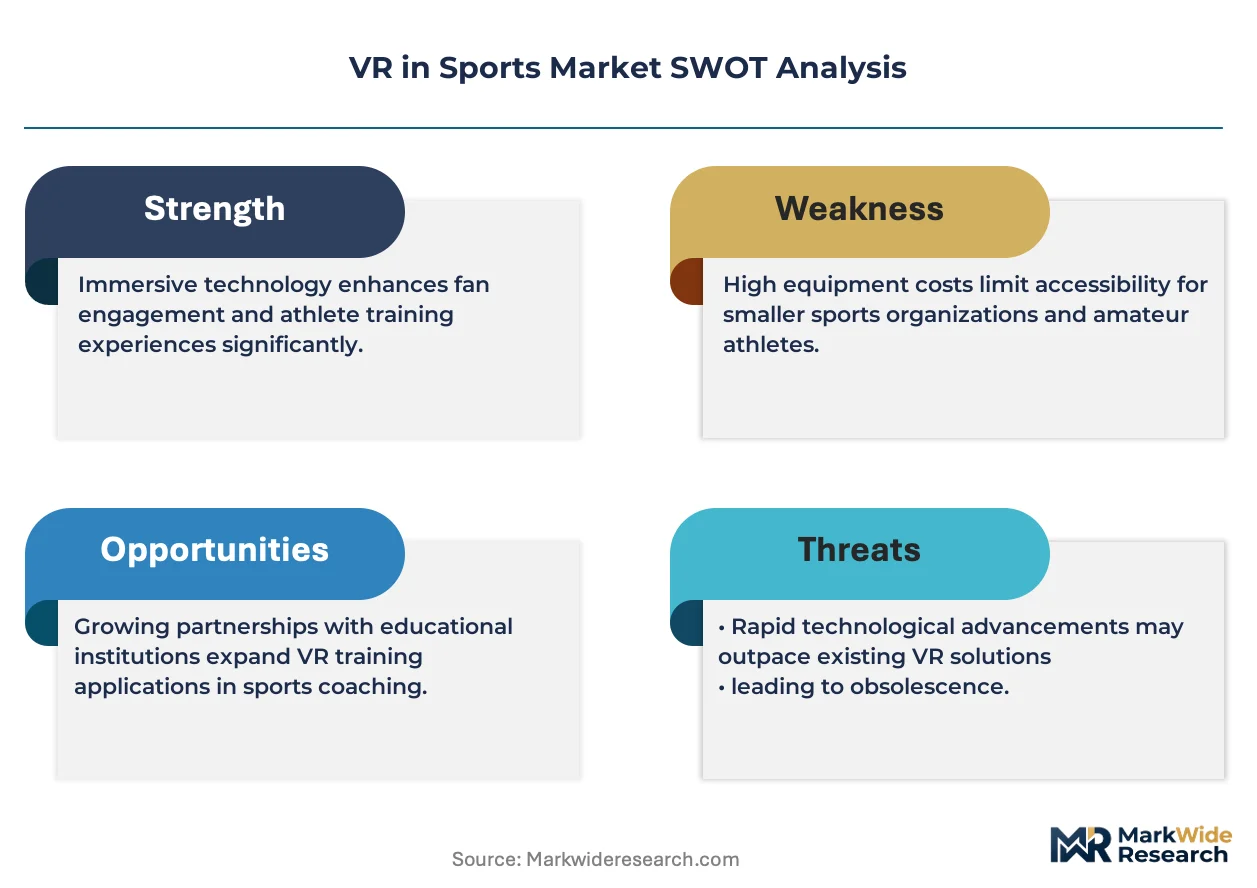
- Display Panel Supply Concentration:Retina-resolution micro-OLED manufacturing concentrates in East Asian foundries, creating single-source vulnerability for Varjo-tier headset producers seeking pixel densities above 60 PPD.
- Wireless Spectrum Scarcity:FCC allocation constraints for 6 GHz unlicensed operation limit simultaneous headset density in stadium training facilities, capping the number of athletes who can train synchronously.
- Motion Sickness Physiology:Vestibular mismatch between visual flow and inner-ear signaling persists as a hard biological constraint, excluding approximately fifteen percent of athlete populations from extended immersion protocols regardless of latency optimization.
Strategic Opportunities
- India Collegiate Penetration:The country's university sports infrastructure remains virtually unaddressed by immersive training vendors, presenting first-mover advantage for localized content development in cricket and field hockey simulations.
- ISO Eye-Tracking Safety Standardization:Emerging international guidelines for retinal exposure limits during extended VR sessions will favor vendors with pre-compliant hardware architectures, creating certification-based switching incentives.
- Biomechanical-AI Convergence:Integration of computer-vision pose estimation with haptic force vectors enables real-time injury-risk scoring, opening subscription revenue models tied to athlete health outcomes rather than hardware sales.
Industry Challenges
- Immersive Content Pipeline Bottleneck:Sports-specific scenario authoring requires motion-capture studios, professional athlete participation, and physics-engine tuning that stretches development timelines to eighteen months per position-specific module.
- Legacy Video System Integration:Coaching staffs demand seamless interoperability with existing Hudl and Synergy game-film platforms, forcing VR vendors to build and maintain costly API bridges rather than displace incumbent workflow tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR in Sports Market |
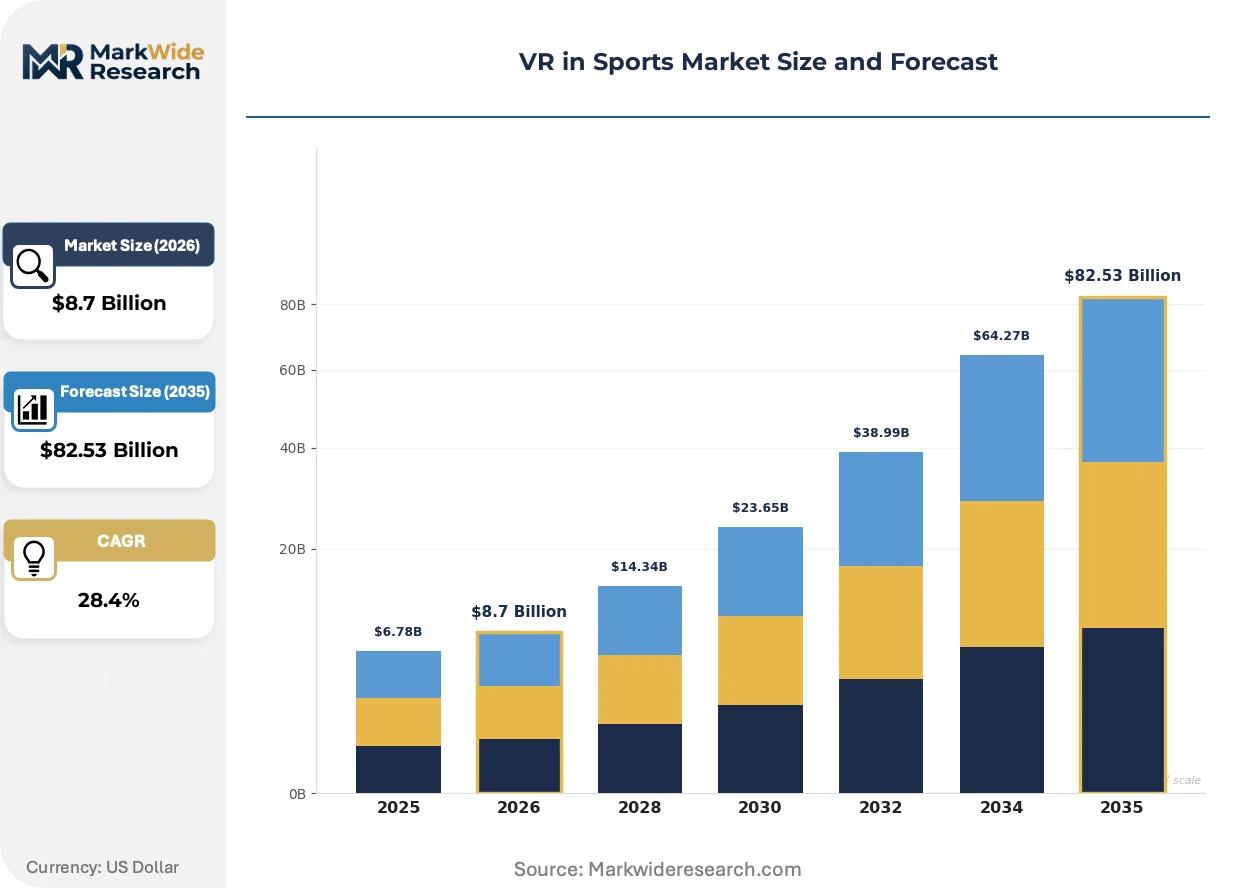
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Accessories, Content Application: Training, Fan Engagement, Performance Analysis, Injury Rehabilitation End User: Athletes, Coaches, Teams, Event Organizers Distribution Channel: Online Retail, Direct Sales, Partnerships, Events |
| Companies Covered | HTC, Varjo, Meta (Reality Labs), StatusPro, WIN Reality, Apple, Valve, Sense Arena, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR in Sports Market Trends and Innovations
Spatial computing architectures are compressing the hardware stack while expanding software serviceability, shifting value capture from device margins toward recurring content and analytics subscriptions.
Retina-resolution varifocal displays with dynamic depth planes are consolidating professional training system specifications, eliminating vergence-accommodation conflict that previously limited session duration. NFL and MLB franchises now mandate sub-arcminute angular resolution as a procurement threshold, compressing acceptable vendor pools to three qualified suppliers. This specification creep is consolidating purchasing power within athletic departments that can amortize five-figure unit costs across fifty-player rosters.
EU Medical Device Regulation reclassification discussions are pressuring rehabilitation VR developers to establish quality management systems compliant with Annex IX conformity assessment procedures. Manufacturers targeting European physiotherapy clinics must now budget for notified body engagement and post-market surveillance infrastructure previously unnecessary for wellness-oriented training tools. German and French national health technology assessment bodies are piloting reimbursement coding for stroke-recovery VR protocols, creating regulatory tailwinds for clinical-grade hardware differentiation.
Athletic departments are unbundling hardware procurement from content licensing, demanding à-la-carte sport-module subscriptions rather than bundled perpetual licenses. This purchasing behavior shift compresses upfront vendor revenue while extending customer lifetime value for content-specialized platforms. The United States collegiate market exhibits this pattern most acutely, where equipment managers negotiate separate headset leases from scenario libraries to optimize capital versus operational expenditure classification.
VR in Sports Market Segmentation
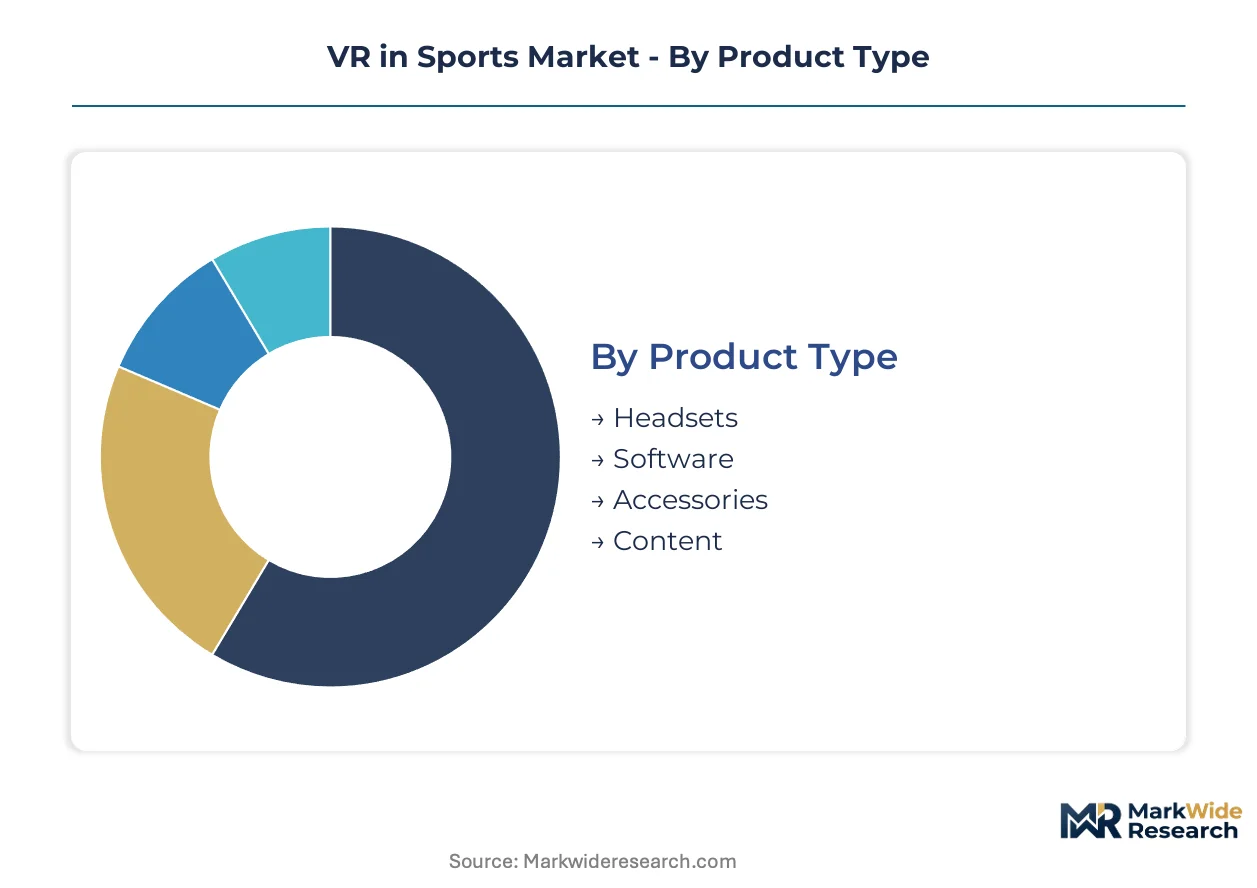
Segmentation in the VR in Sports market reveals divergent capital requirements across hardware, software, and service layers. Procurement patterns differ sharply between institutional athletic departments seeking enterprise installations and individual consumers purchasing mass-market headsets.
Product Type:
Capital intensity varies dramatically across this category, with hardware manufacturing demanding semiconductor fabrication partnerships while content development requires motion-capture infrastructure and athlete licensing agreements.
- Headsets:Tethered and untethered display units incorporating retina-resolution micro-OLED panels and sub-20ms motion-to-photon latency controllers. North American collegiate athletic programs and professional franchises drive replacement cycles through display specification upgrades, though East Asian foundry concentration for high-PPD panels creates supply vulnerability.
- Software:Scenario engines, physics simulations, and analytics platforms rendering three-dimensional athletic environments. Demand concentrates among coaching staffs requiring interoperability with existing game-film platforms such as Hudl and Synergy, forcing vendors to maintain costly API integration layers.
- Accessories:Haptic feedback gloves, force-feedback exoskeletons, and biometric sensors enabling realistic equipment sensation transfer. These peripherals convert skeptical coaching staffs through measurable reaction-time improvements in bat-racket-ball simulations.
- Content:Position-specific training modules, fan experiential marketing assets, and rehabilitation protocols requiring motion-capture studio production and professional athlete participation.
Headsets absorb the bulk of installed capacity; software is expanding most quickly as athletic departments unbundle hardware procurement from content licensing.
Application:
Functional deployment separates systems designed for athlete skill acquisition from those targeting spectator monetization or clinical recovery protocols.
- Training:Cognitive drill simulations for quarterback decision-making, batter pitch recognition, and tactical scenario repetition. NFL and MLB franchises now mandate sub-arcminute angular resolution as procurement thresholds, compressing qualified vendor pools.
- Fan Engagement:Stadium immersive experiences, virtual seat upgrades, and casual sports gaming applications accessible through consumer-grade hardware. Meta leverages consumer hardware scale to dominate accessible price points in this segment.
- Performance Analysis:Biomechanical pose estimation integrated with haptic force vectors for real-time injury-risk scoring. This convergence opens subscription revenue models tied to athlete health outcomes.
- Injury Rehabilitation:FDA Class II medical device pathways for reimbursable recovery protocols, requiring quality management systems compliant with EU Medical Device Regulation Annex IX procedures for European physiotherapy clinic deployment.
Training applications command the highest per-account spending through institutional procurement; injury rehabilitation carries the steepest regulatory compliance burden.
End User:
Spending concentration and decision-making authority diverge between individual practitioners and organizational purchasers with capital expenditure authority.
- Athletes:Individual professional and collegiate competitors using VR systems for skill maintenance and off-season preparation. Approximately fifteen percent of athlete populations experience vestibular mismatch excluding them from extended immersion regardless of latency optimization.
- Coaches:Tactical planners and player development staff demanding seamless workflow integration with legacy video systems. This group commands higher per-account spending than individual athletes through institutional procurement budgets.
- Teams:Athletic departments and franchise operations amortizing five-figure unit costs across fifty-player rosters. United States university programs now allocate specific capital expenditure lines for virtual preparation tools.
- Event Organizers:Stadium operators and league offices deploying spectator-facing experiential marketing installations.
Teams absorb the bulk of installed capacity; coaches represent the most concentrated decision-making influence over vendor selection.
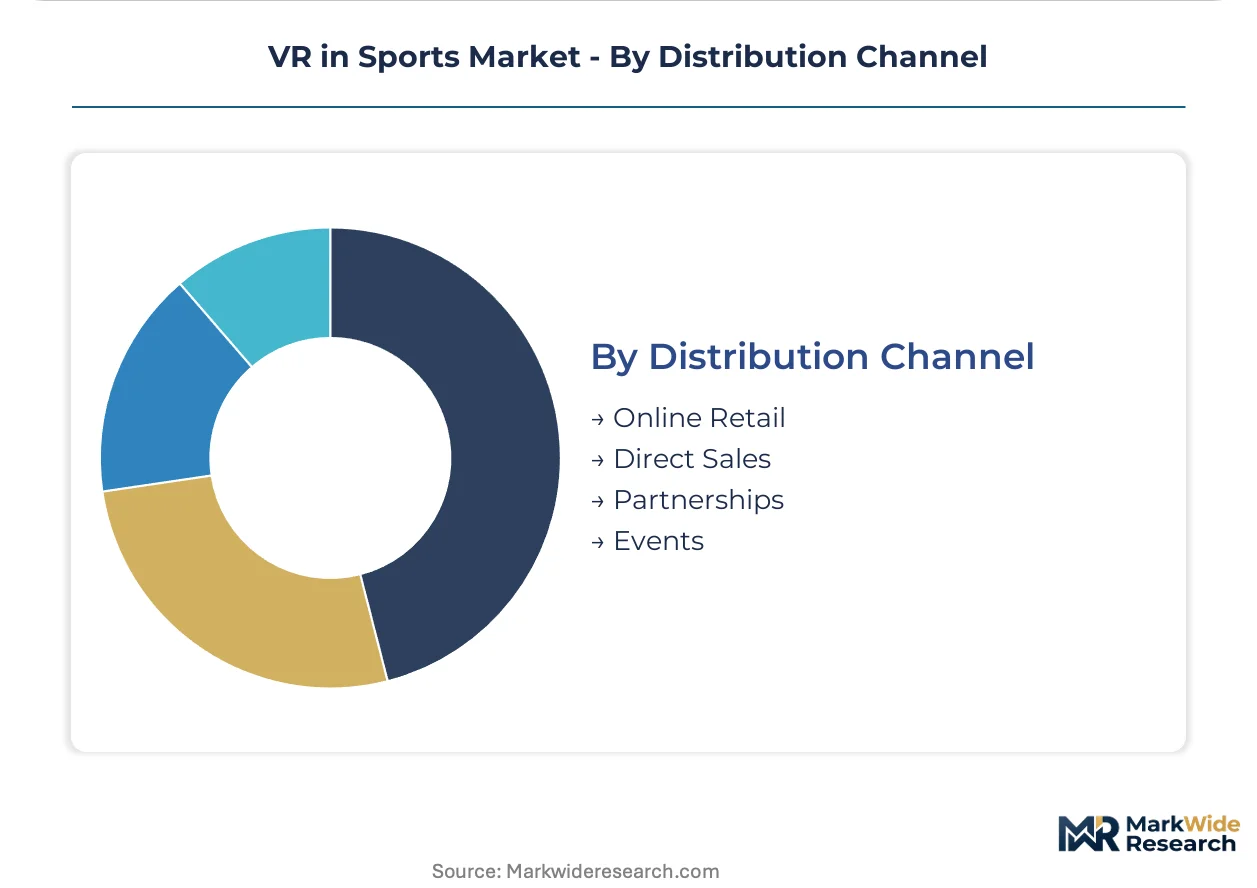
Distribution Channel:
Route-to-market strategies separate high-touch enterprise sales from scalable consumer access.
- Online Retail:Direct-to-consumer headset and accessory sales through e-commerce platforms. This channel serves mass-market fan entertainment demand.
- Direct Sales:Enterprise field teams engaging athletic departments, professional franchises, and rehabilitation clinics with customized installation and training protocols.
- Partnerships:Strategic alliances with equipment manufacturers, sports technology platforms, and league offices embedding VR offerings into broader ecosystem relationships.
- Events:Stadium deployments, trade show demonstrations, and training camp installations generating qualified enterprise leads.
Direct sales capture the highest-value enterprise contracts; online retail delivers the widest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the immersive sports training ecosystem through concentrated NFL and MLB franchise headquarters demanding enterprise-grade simulation fidelity. Collegiate athletic programs in Texas and Florida now replicate this procurement pattern. Professional teams in London and Sydney are importing these specifications into their facility upgrade cycles.
United States
Collegiate athletic departments allocate dedicated capital expenditure lines for virtual preparation tools, professionalizing demand before athletes reach commercial leagues. The FCC governs wireless spectrum allocation for untethered headset operation in stadium and training facilities. The Dallas-Fort Worth metroplex hosts concentrated NFL franchise deployments where haptic feedback glove maturation is converting skeptical coaching staffs.
Germany
Physiotherapy clinics pilot reimbursement coding for stroke-recovery VR protocols, creating regulatory tailwinds for clinical-grade hardware differentiation. The EU Medical Device Regulation Annex IX conformity assessment procedures now govern quality management systems for rehabilitation systems. The Munich-Stuttgart corridor concentrates sports technology development where varifocal display specifications are being stress-tested against procurement thresholds.
Japan
METI standards for electromagnetic compatibility constrain hardware design parameters for professional training environments. The Kanto region around Tokyo hosts motion-capture studios producing eighteen-month development cycle content for position-specific training modules. Professional baseball franchises here mandate sub-arcminute angular resolution, compressing qualified vendor pools to three suppliers.
India
University sports infrastructure remains virtually unaddressed by immersive training vendors, presenting first-mover advantage for localized cricket and field hockey simulations. The BIS eye-tracking safety guidelines are emerging alongside ISO standardization efforts. The Bangalore-Hyderabad technology corridor hosts software development centers building scenario engines for biomechanical-AI convergence applications.
United Kingdom
Premier League football clubs deploy spectator-facing experiential marketing installations through stadium operator partnerships. GDPR compliance requirements shape data handling protocols for biometric sensor integration in athlete monitoring systems. The London metropolitan area concentrates event organizer demand where spatial computing architectures are shifting value capture toward recurring subscriptions.
VR in Sports Market Competitive Landscape
Premium-margin players sit above commodity-margin players across display resolution and latency specification tiers, with retina-resolution micro-OLED sourcing separating enterprise installations from mass-market headsets. The market structures around three vendor archetypes: consumer hardware scale platforms, professional training specialists, and medical-grade rehabilitation developers. Consolidation pressure concentrates among headset manufacturers facing East Asian foundry supply vulnerability. Dominant competitive moves include hardware-content unbundling and API bridge construction for legacy video system interoperability.
Among technology platform incumbents, Meta (Reality Labs) and Apple occupy positions exemplifying consumer hardware scale strategies, while Varjo represents the premium-tier enterprise vector. StatusPro and Sense Arena sit within the professional training specialization archetype. HTC and Sony occupy intermediate positions spanning consumer and commercial applications. Valve exemplifies platform-agnostic software infrastructure development. These named entities anchor industry-level commentary without constraining strategic action specifics.
| Leading Market Players |
|---|
| HTC |
| Varjo |
| Meta (Reality Labs) |
| StatusPro |
| WIN Reality |
| Apple |
| Valve |
| Sense Arena |
| Sony |
| Others |
Pricing and Supply Chain Analysis
Micro-OLED panel pricing indices cascade through VR headset manufacturing tiers, compressing margins for retina-resolution vendors while sustaining premium positioning for sub-arcminute angular resolution systems procured by NFL and MLB franchises.
Pricing Analysis
Outcome-based pricing tied to measurable reaction-time improvements anchors professional training system valuations. Three-tier pricing structure across premium, standard, and economy levels separates FDA Class II medical device rehabilitation platforms from collegiate athletic department bundles and mass-market fan entertainment headsets. Cost compression in consumer-tier hardware intensifies because Meta's Reality Labs scale advantages force component cost absorption. Individual athletes exhibit highest price sensitivity; institutional procurement teams at United States university athletic programs demonstrate lowest sensitivity due to dedicated capital expenditure lines.
Supply Chain Analysis
Refurbishment flows for haptic feedback gloves and force-feedback exoskeletons extend peripheral lifecycle value while feeding secondary markets in emerging geographies. Manufacturing concentrates in Taiwan, South Korea, and Japan for micro-OLED panels above 60 PPD pixel density. Component sourcing draws from East Asian foundries for display controllers, German precision optics for varifocal lenses, and United States semiconductor designers for motion-to-photon latency processors. Single-source vulnerability for retina-resolution panels creates supply chain risk. Distribution runs through direct enterprise sales teams for institutional athletic departments alongside online retail for consumer headset penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial computing architectures are displacing legacy video-based preparation tools across professional and collegiate athletic programs, compressing procurement timelines for immersive training system adoption.
For Market Incumbents: Anchor defensive positioning through backward integration into micro-OLED supply partnerships that mitigate East Asian foundry concentration risk. Deepen API bridge investments for Hudl and Synergy interoperability to entrench workflow dependency among coaching staffs. The haptic feedback glove maturation wave threatens hardware commoditization; certification pre-compliance with emerging ISO eye-tracking safety standards offers margin protection. For New Entrants and Emerging Players: India's university sports infrastructure represents the most penetrable white-space target, with cricket and field hockey simulations demanding localized content development. Biomechanical-AI convergence applications for real-time injury-risk scoring offer subscription revenue models detached from hardware margin competition. A partnerships-based go-to-market angle through equipment manufacturer alliances accelerates access to collegiate athletic department procurement committees. For Investors and Strategic Acquirers: The window for entry favors content-specialized platforms with scenario engine capabilities over hardware-dependent vendors facing display panel supply vulnerability. Long-term viability hinges on recurring subscription revenue attachment rates rather than perpetual license dependence. The signal to watch as inflection indicator is FDA Class II medical device clearance velocity for rehabilitation applications, which expands reimbursable addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API bridge construction for Hudl and Synergy interoperability locks in coaching staff workflow dependency. |
| Regulatory Approval Pathway | FDA Class II medical device clearance for rehabilitation systems unlocks institutional procurement budgets. |
| Backward Integration | Captive supply agreements for micro-OLED panels above 60 PPD mitigate East Asian foundry concentration risk. |
| Geographic Expansion | India collegiate penetration for cricket and field hockey simulations captures first-mover advantage in unaddressed infrastructure. |
| Strategic Partnership | Equipment manufacturer alliances embed VR offerings into broader athletic department ecosystem relationships. |
Research Methodology
Independent corroboration across headset procurement managers at collegiate athletic departments, coaching staff technology directors, and rehabilitation clinic equipment specialists underwrites the qualitative findings. Primary interviews with VR content developers, haptic hardware engineers, and sports league technology officers combined with secondary validation against FCC spectrum allocation filings, FDA 510(k) device clearance databases, and ISO standardization committee records. Bottom-up triangulation across product type, application, and end-user segmentation dimensions converged with top-down macroeconomic scenario testing.
Rate-of-change decomposition across hardware replacement cycles, content development timelines, and regulatory approval pathways structured the analytical framework. Segmentation dimensions modeled include product type tier, application function, end-user procurement authority, and geographic regulatory cluster throughout the forecast period. CAGRs derived from installed base growth rates and average selling price trajectory assumptions. Industry-specific inputs incorporated motion-to-photon latency specification thresholds and collegiate athletic department capital expenditure survey data.
Revisions become necessary when FDA medical device reclassification, FCC spectrum reallocation, or East Asian foundry supply disruption materialize. Forecasts reflect assumptions regarding haptic feedback glove adoption velocity and ISO eye-tracking safety standard implementation timelines. Practitioners should monitor FDA 510(k) clearance announcements, collegiate athletic department budget appropriations, and micro-OLED panel foundry capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market