
 Mobile Virtualization Market | 2026-2036
Mobile Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Virtualization Market Intelligence
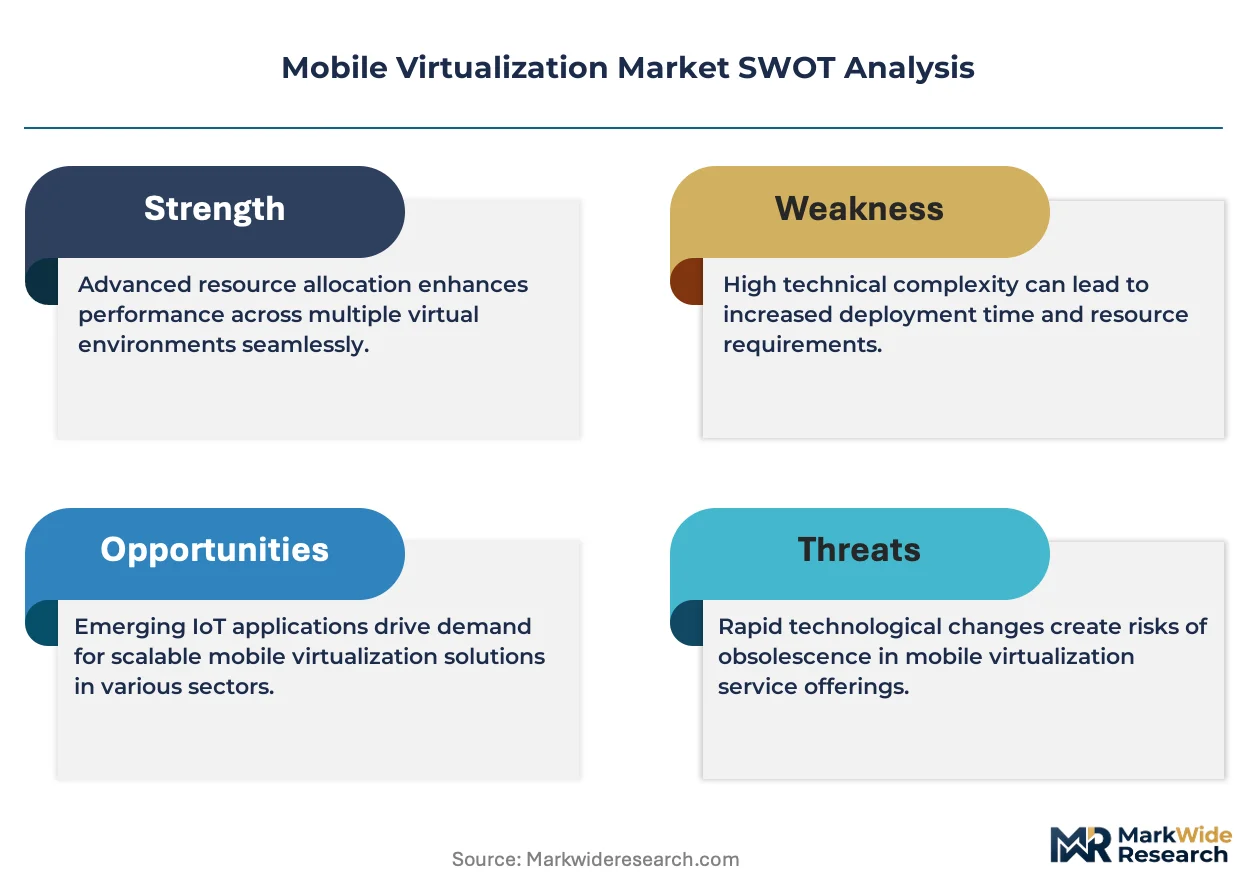
Enterprise-grade security certification is reorganizing competitive hierarchies in mobile virtualization. VMware Inc. leverages its hypervisor heritage to anchor multi-tenant enterprise deployments. Citrix Systems Inc. specializes in application virtualization layers that differentiate its workspace delivery stack. Microsoft Corporation extends Azure-based endpoint management to compete directly with independent platform vendors.
Mobile virtualization partitions hardware resources through Type-1 or Type-2 hypervisors to run multiple isolated operating system instances on a single device, typically achieving sub-50-millisecond context switching latency for secure enterprise containers. The technology enables BYOD policies without compromising corporate data integrity through hardware-backed trusted execution environments. Cloud-based deployment models capture the fastest expansion as enterprises abandon capital-intensive on-premises infrastructure. Platform solutions concentrate margin pools where vendors bundle hypervisor kernels with management orchestration, while SME end users represent the highest volume growth segment as managed service providers democratize access.
The U.S. Federal Communications Commission and National Institute of Standards and Technology frame encryption standards for federal mobile deployments, while the EU AI Act and GDPR impose algorithmic transparency and data residency requirements on European enterprise mobility stacks. Compliance with these overlapping regimes directly shapes product roadmaps and geographic availability of containerization features. Stakeholders must evaluate whether vendor consolidation around Broadcom's VMware acquisition alters long-term platform support commitments before committing to multi-year enterprise licensing structures.
Market Dynamics
Container-based isolation architectures are forcing wholesale replacement of legacy mobile device management stacks as financial services institutions mandate hardware-backed trusted execution environments for BYOD deployments. This architectural pivot rewrites procurement criteria and vendor selection hierarchies across enterprise mobility.
Growth Catalysts
- FCC Encryption Mandates:Federal agencies in the United States must deploy NIST-compliant mobile virtualization for classified data access, creating institutional demand for certified hypervisor platforms.
- Zero-Trust Security Frameworks:Financial services institutions in Germany and India are mandating container isolation to satisfy internal risk committees and cyber insurance underwriters.
- Cloud-Native Orchestration:Kubernetes-based workspace delivery is displacing on-premises endpoint management, enabling managed service providers to serve SME segments at scale.
Market Restraints
- Silicon Supply Concentration:Hardware-backed trusted execution environments depend on ARM TrustZone and Intel SGX components sourced from concentrated semiconductor foundries in Taiwan and South Korea.
- GDPR Data Residency Friction:European enterprises face architectural constraints when deploying cross-border container synchronization, complicating multi-national workspace platforms.
- Hypervisor Licensing Cost Burden:Per-device subscription models for Type-1 hypervisor stacks impose recurring opex loads that deter mid-market manufacturing and logistics adopters.
Strategic Opportunities
- India SME Democratization:Managed service providers are bundling hypervisor-enabled workspaces with 5G connectivity packages for unpenetrated small and medium enterprises in Mumbai and Bangalore.
- EU AI Act Algorithmic Transparency:Container isolation for machine learning inference on mobile endpoints creates compliance-ready deployment paths for European healthcare and automotive developers.
- Edge-Cloud Convergence:5G network slicing combined with mobile virtualization enables deterministic latency for industrial field service applications in German automotive plants.
Industry Challenges
- Embedded Systems Integration Complexity:Manufacturing equipment with proprietary real-time operating systems requires custom hypervisor porting that stretches deployment timelines.
- Multi-Tenant Certification Gaps:Common Criteria and FIPS 140-2 validation processes for containerized environments lag behind product development cycles, freezing federal procurement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Virtualization Market |
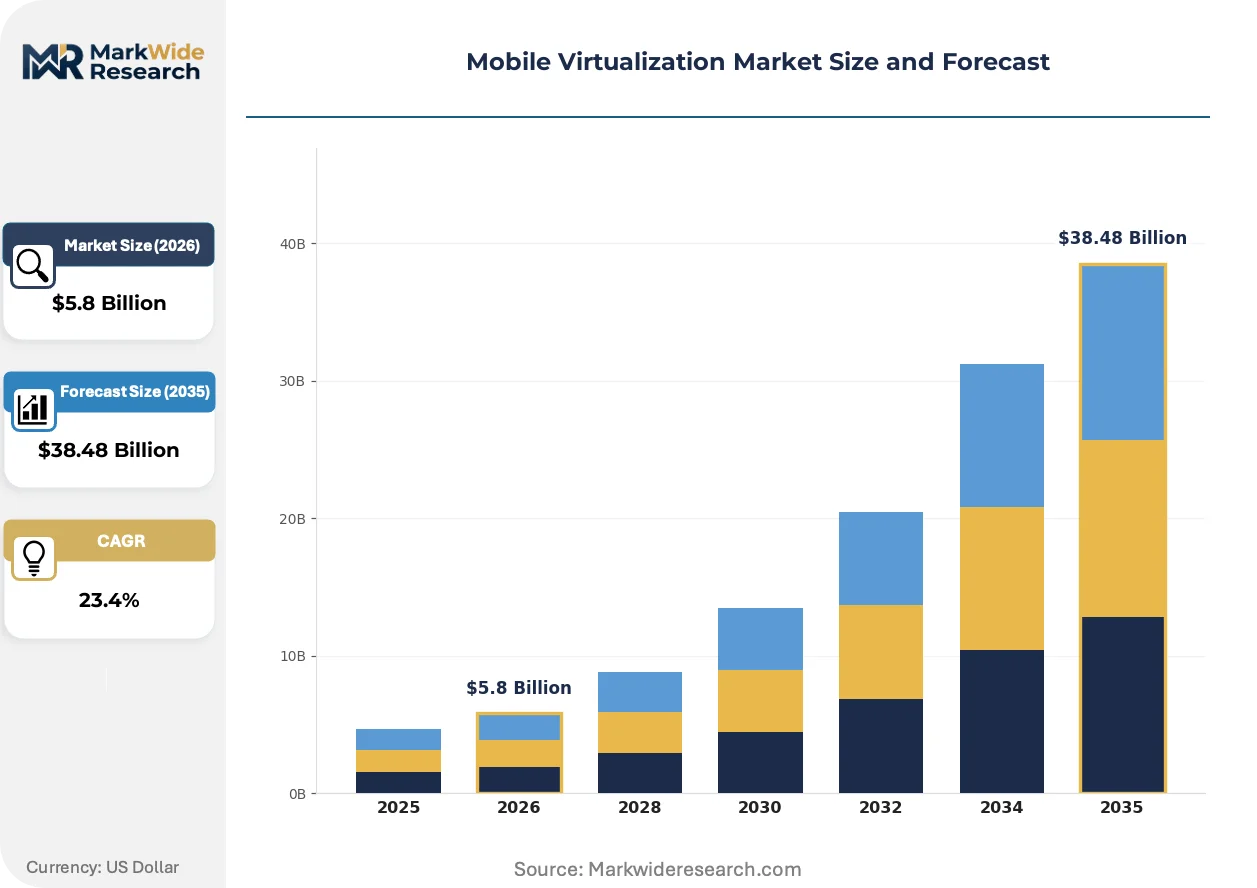
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $38.48 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Platform, Software, Service, Infrastructure Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual Private End User: Corporates, SMEs, Educational Institutions, Government Device Type: Smartphones, Tablets, Laptops, Wearables |
| Companies Covered | VMware Inc., Citrix Systems Inc., Microsoft Corporation, IBM Corporation, Oracle Corporation, Blackberry Limited, Broadcom Inc., Samsung Electronics Co. Ltd., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Virtualization Market Strategic Shifts & Innovations
Type-2 hypervisor architectures with sub-50-millisecond context switching are compressing the performance gap with bare-metal alternatives, enabling new use cases in latency-sensitive enterprise applications. This technical maturation coincides with regulatory pressure and procurement model evolution across North America, Western Europe, and Asia-Pacific.
Hardware-assisted virtualization extensions in ARMv9 and Intel Alder Lake processors are displacing software-only container approaches in enterprise mobility stacks. Financial services institutions in the United States and Germany are standardizing on these silicon-rooted isolation layers for trader mobility and executive BYOD programs. The displacement is compressing margins for legacy mobile application management vendors while elevating platform providers with direct silicon partnerships.
The EU AI Act's risk classification framework for algorithmic decision systems is mandating audit trails and explainability for mobile-deployed machine learning models. European healthcare providers and automotive manufacturers must now document data lineage across container boundaries, forcing virtualization vendors to embed telemetry and governance hooks. German medical device developers are responding by selecting platforms with pre-certified compliance modules rather than building custom stacks.
Outcome-based workspace contracts are replacing perpetual licensing in North American enterprise procurement. Chief information officers at US-based logistics and professional services firms now pay per active user-hour rather than device count, shifting vendor revenue recognition and customer success metrics. This model is most visible in Fortune 500 pilots where mobility teams report directly to finance operations rather than traditional IT infrastructure functions.
Mobile Virtualization Market Segmentation
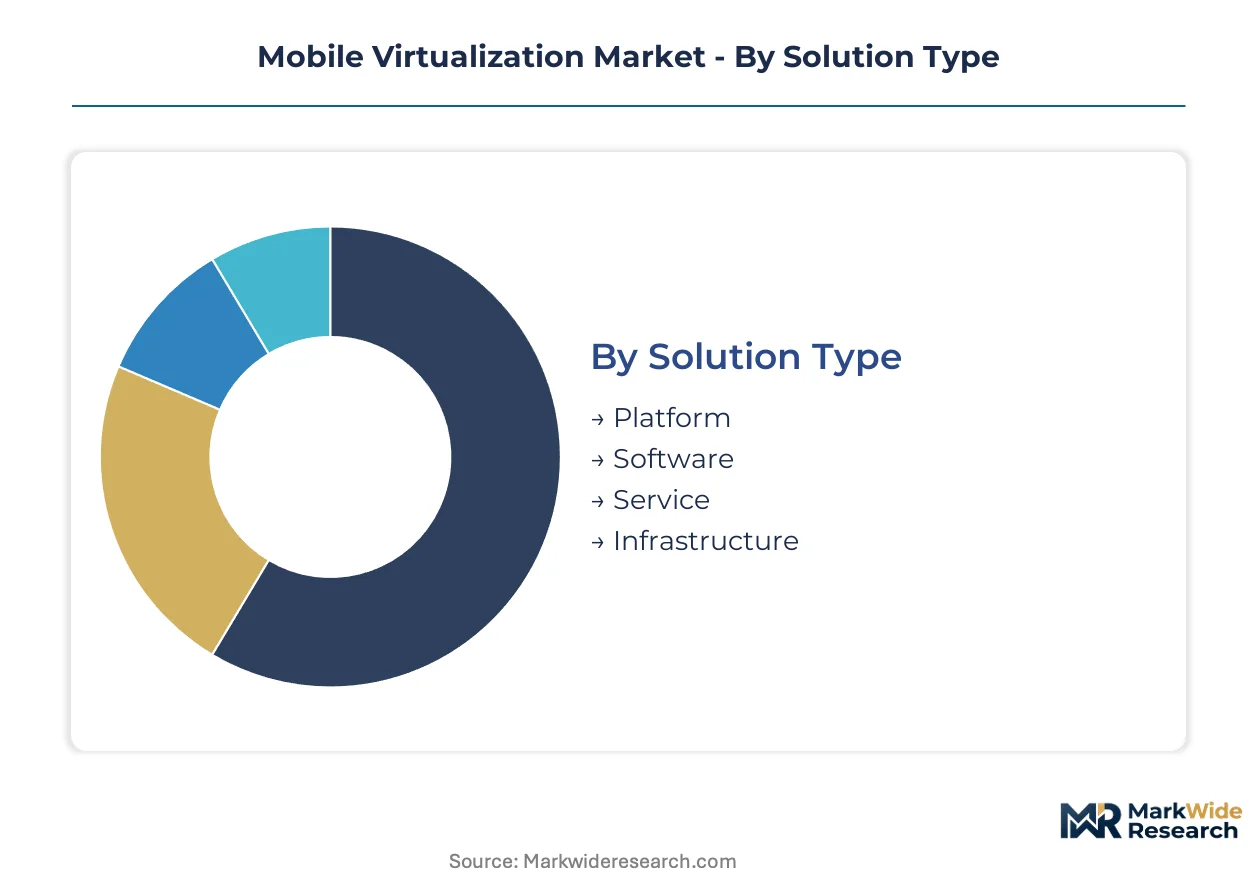
Mobile virtualization procurement patterns diverge sharply across solution architectures and deployment modalities. Enterprise buyers prioritize certified hypervisor platforms while SME segments drive volume through managed service bundles. Understanding these segment-channel relationships illuminates where vendor investments concentrate and where margin compression threatens.
Solution Type:
Platform solutions flow through direct enterprise sales channels with multi-year licensing, while software and service components distribute via cloud marketplaces and MSP aggregators. Infrastructure hardware concentrates in systems integrator partnerships for federal and financial services deployments.
- Platform:Bundled hypervisor kernels with orchestration layers anchor enterprise mobility stacks. Financial services institutions in the United States and Germany standardize on these integrated offerings for trader BYOD and executive secure containers, driven by Common Criteria certification requirements.
- Service:Managed workspace delivery and hypervisor tuning expertise accelerates SME adoption in India and Southeast Asia. MSPs in Mumbai and Bangalore bundle these services with 5G connectivity packages, displacing capital-intensive on-premises builds for unpenetrated mid-market manufacturers.
- Software:Standalone containerization agents and policy enforcement modules.
- Infrastructure:Hardware-backed trusted execution environment components and edge gateway appliances.
By volume, Service leads through MSP channel expansion. By growth pace, Platform is ahead as federal certification mandates harden procurement criteria.
Deployment Model:
Cloud-based configurations minimize upfront infrastructure spend and align with outcome-based contracting trends reshaping North American procurement. On-premises and hybrid alternatives retain traction where data residency constraints or air-gapped security requirements dominate.
- Cloud-Based:Kubernetes-orchestrated workspace delivery eliminates capital expenditure and enables per-user-hour pricing. US logistics and professional services firms now pilot these models with mobility teams reporting to finance operations rather than traditional IT infrastructure functions.
- Hybrid:Split architectures keep sensitive containers on-premises while pushing non-critical workloads to public cloud. German automotive manufacturers deploy these configurations for industrial field service applications requiring deterministic latency through 5G network slicing.
- On-Premises:Fully captive hypervisor stacks for classified federal environments.
- Virtual Private:Single-tenant cloud instances with dedicated infrastructure isolation.
Cloud-Based deployments dominate new contract value. Hybrid architectures are climbing the fastest as European data residency friction complicates pure public cloud strategies.
End User:
Corporate and government buyers command premium pricing through certified platform procurement, while educational institutions and SMEs access virtualization through volume-discounted service tiers. Channel specialization separates these segments.
- Corporates:Fortune 500 mobility programs mandate hardware-backed isolation for executive devices and trader workstations. These buyers negotiate outcome-based contracts tied to active user-hours, shifting vendor revenue recognition models and customer success metrics.
- SMEs:Small and medium enterprises in India and Brazil access hypervisor-enabled workspaces through telecom-managed service bundles. 5G carriers in São Paulo and Bangalore white-label container platforms, democratizing access without internal virtualization expertise.
- Government:Federal agencies require FIPS 140-2 and Common Criteria validated stacks.
- Educational Institutions:Universities and K-12 districts deploy container isolation for BYOD student device management.
SMEs generate the highest unit volume through carrier bundling. Corporates capture the steepest expansion trajectory as zero-trust mandates rewrite procurement criteria.
Device Type:
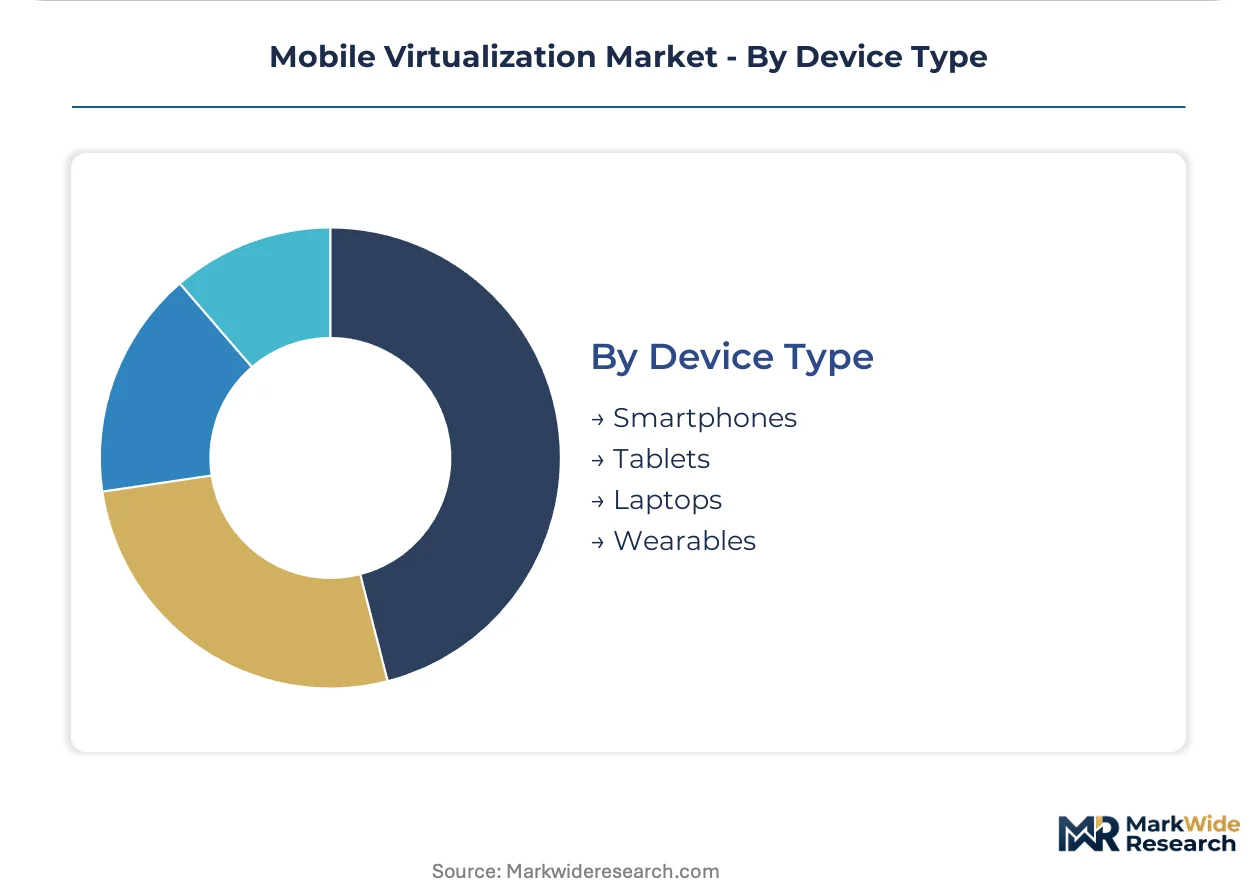
Smartphones and tablets concentrate demand through enterprise mobility management replacement cycles, while laptops and wearables represent emerging attach points for extended workspace platforms. Semiconductor availability shapes segment economics.
- Smartphones:ARM TrustZone-enabled handsets dominate enterprise BYOD deployments. Financial services institutions in Germany and India standardize on these devices for hardware-rooted container isolation satisfying cyber insurance underwriters.
- Tablets:Larger form factors support field service and clinical workflows requiring split-screen corporate-personal container visibility. German medical device developers select pre-certified tablet platforms with embedded telemetry for EU AI Act compliance.
- Laptops:Intel SGX and AMD SEV extensions enable secure enterprise containers on x86 mobile workstations.
- Wearables:Smartwatches and augmented reality glasses for industrial hands-free applications.
Smartphones lead by installed base. Tablets are gaining share fastest as healthcare and automotive developers deploy mobile machine learning inference with audit trail requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication for trusted execution environments concentrates in Taiwan and South Korea, while enterprise deployment demand clusters in North America, Western Europe, and South Asia. This geographic split between silicon supply and software consumption shapes regional procurement strategies and compliance frameworks.
United States
Federal agencies drive institutional demand through FCC and NIST encryption mandates for classified data access. The National Institute of Standards and Technology validates hypervisor platforms for government procurement, freezing pipelines where Common Criteria certification lags. Financial services clusters in New York and Chicago mandate hardware-backed containers for trader mobility and executive BYOD programs.
Germany
Automotive manufacturers and medical device developers anchor European demand for EU AI Act-compliant container platforms. The KBA and federal data protection authorities enforce algorithmic transparency requirements that force embedded telemetry in virtualization stacks. Industrial field service deployments in Bavaria and Baden-Württemberg combine 5G network slicing with deterministic latency requirements.
India
Managed service providers in Mumbai and Bangalore democratize access through telecom-bundled workspace packages for unpenetrated SMEs. TRAI frameworks for 5G spectrum allocation enable carrier white-labeling of container platforms. Manufacturing and logistics hubs in Maharashtra and Karnataka adopt hypervisor-enabled devices as cyber insurance underwriters mandate hardware isolation.
United Kingdom
Professional services firms in London pilot outcome-based workspace contracts tied to active user-hours rather than device counts. GDPR alignment post-Brexit preserves data residency constraints on cross-border container synchronization. Fintech clusters in the City and Canary Wharf standardize on silicon-rooted isolation for regulatory compliance.
South Korea
Semiconductor foundries supply ARM TrustZone and Intel SGX components that underpin global trusted execution environments. Domestic enterprise adoption concentrates in Samsung Electronics' vertical integration of handset and hypervisor stack. Government cloud migration programs in Seoul accelerate public sector container deployment.
Mobile Virtualization Market Key Industry Players
Concentration sits with platform vendors bundling hypervisor kernels with orchestration layers, while specialist service providers fragment the mid-market through MSP channels. Three archetypes dominate: silicon-integrated platform providers with direct hardware partnerships, independent software vendors with workspace delivery specialization, and telecom-coupled service aggregators targeting SME democratization. Competitive moves center on federal certification acquisition and outcome-based contracting model adoption.
Within the platform tier, VMware Inc. and Citrix Systems Inc. anchor enterprise mobility stacks through hypervisor heritage and application virtualization specialization respectively. Microsoft Corporation occupies a position spanning cloud-native orchestration and endpoint management convergence. These three exemplify the strategic pivot toward Kubernetes-based workspace delivery and per-user-hour revenue recognition that is displacing perpetual licensing structures in North American procurement.
| Leading Market Players |
|---|
| VMware Inc. |
| Citrix Systems Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Blackberry Limited |
| Broadcom Inc. |
| Samsung Electronics Co. Ltd. |
| Google LLC |
| Others |
Cost & Logistics Intelligence
Outcome-based workspace contracts lock in multi-year supply access for certified hypervisor platforms while anchoring price visibility to active user-hour metrics rather than capital-intensive perpetual licenses. This contracting pattern concentrates procurement leverage with Fortune 500 mobility teams and federal agencies that mandate NIST-validated stacks, compressing margins for vendors unable to meet Common Criteria certification thresholds.
Pricing Analysis
FCC encryption mandates dictate the pricing tier structure across federal and financial services procurement, separating FIPS 140-2 validated platform subscriptions from uncertified software-only alternatives. Three-tier pricing structure across premium certified, standard enterprise, and economy MSP-bundled levels reflects the cost of compliance documentation and silicon partnership investments. Pricing pressure stems from carrier white-labeling in India and Brazil, where 5G bundling collapses per-device margins. Mid-market manufacturing adopters exhibit highest price sensitivity, while classified federal buyers accept premium tiers for validated supply continuity.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for ARM TrustZone and Intel SGX components that enable hardware-backed trusted execution environments. Hypervisor kernel development draws from concentrated semiconductor foundries, while orchestration software layers source from cloud infrastructure providers in the United States and Western Europe. Single-source vulnerability in Taiwan Strait logistics threatens component availability for German automotive and Indian SME deployments. Distribution runs through direct enterprise sales for certified platforms and telecom MSP aggregators for volume-democratized segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as zero-trust mandates splinter procurement criteria across federal certification, cyber insurance compliance, and outcome-based contracting archetypes. Container isolation architectures enable specialist positioning without full-stack platform investments.
For Market Incumbents: Consolidate federal certification pipelines against Common Criteria lag that freezes procurement decisions. Acquire Kubernetes-native workspace specialists to displace legacy mobile device management vendors. Prioritize silicon partnerships with ARM and Intel to secure hardware-assisted virtualization roadmap access before mid-market competitors replicate integration capabilities. For New Entrants and Emerging Players: Differentiate on EU AI Act compliance modules for German healthcare and automotive developers seeking pre-certified audit trail capabilities. Target India SME democratization through telecom channel partnerships in Mumbai and Bangalore, where cyber insurance mandates create first-mover advantages for hardware-isolated workspace bundles. Lead with 5G network slicing integration for industrial field service latency requirements. For Investors and Strategic Acquirers: Capital is best deployed toward Kubernetes-orchestrated workspace specialists with existing federal certification pipelines and outcome-based contract portfolios. Long-term viability hinges on silicon partnership depth and multi-tenant Common Criteria validation velocity. Watch for Broadcom's VMware platform support commitments as inflection signal for enterprise licensing stability.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria Certification Investment | Federal procurement pipelines remain frozen where validation lags product development cycles. |
| Silicon Partnership Deepening | ARMv9 and Intel Alder Lake extensions displace software-only container approaches in financial services. |
| Kubernetes-Native Workspace Integration | Cloud-native orchestration displaces on-premises endpoint management in North American logistics pilots. |
| Telecom MSP Channel Aggregation | 5G carriers in São Paulo and Bangalore white-label container platforms for unpenetrated SME segments. |
| EU AI Act Compliance Module Development | German medical device developers select pre-certified platforms with embedded telemetry over custom builds. |
Research Approach
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, hyperscaler partnership announcements, and federal procurement databases. Interviews with enterprise mobility architects, federal IT procurement officers, cyber insurance underwriters, and telecom MSP channel managers informed demand-side segmentation. SEC 10-K filings and NIST validation records provided vendor-side validation. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate enterprise mobility spend estimates anchored market sizing.
Segmentation dimensions modeled include solution architecture, deployment modality, organization size tier, vertical industry, and geographic regulatory cluster across the projection horizon. CAGRs derive from fitted adoption curves for container-based isolation against legacy mobile device management replacement cycles. Forecast inputs incorporate 5G network slicing deployment timelines, federal certification pipeline velocities, and EU AI Act implementation trajectories for algorithmic transparency requirements.
Forecasts assume regulatory continuity in FCC encryption mandates, GDPR data residency frameworks, and EU AI Act risk classification regimes; material policy shifts would require re-modeling. Semiconductor supply concentration in Taiwan and South Korea represents primary exogenous risk factor alongside vendor consolidation outcomes. Recalibration cycles align with material shifts in federal procurement pipeline unfreezing and Common Criteria validation completion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market