
 Extended Reality Display Market | 2026-2036
Extended Reality Display Market Size, Share, and Industry Trends Forecast 2026-2036
Extended Reality Display Market Foresight
Capital-intensity divergence between micro-OLED specialists and LCD-legacy panel makers is rotating competitive momentum toward dedicated XR fabs. Sony Corporation leverages its semiconductor-grade deposition expertise to sustain premium positioning in near-eye displays. Samsung Electronics Co., Ltd. anchors supply security through in-house material sourcing for high-resolution panels. BOE Technology Group Co., Ltd. competes aggressively on wafer-scale manufacturing cost for mainstream VR headsets.
Extended Reality Display denotes optoelectronic panels engineered for immersive visualization, typically featuring pixel densities exceeding 2,000 pixels per inch and sub-10-millisecond motion-to-photon latency to eliminate vestibular discomfort in head-worn devices. These displays serve industrial and consumer applications requiring persistent spatial computing interfaces. VR Headsets occupy the dominant volume position as gaming and enterprise training platforms drive panel procurement at scale. Smart Glasses represent the fastest-expanding category, with waveguide and micro-LED architectures enabling all-day wearable form factors. AR Headsets concentrate margin pools where military and surgical applications demand sunlight-readable luminance and precision optical alignment.
FDA scrutiny of XR devices for clinical decision support is elevating validation requirements for healthcare-facing panels in the United States. EMA coordination with notified bodies under the EU MDR is harmonizing biocompatibility and electromagnetic exposure standards for wearable displays across Europe. China's NMPA and MIIT are jointly issuing GB standards for near-eye display optical safety and data transmission security. Stakeholders must monitor which regulatory jurisdiction certifies first, as mutual recognition gaps will fragment go-to-market sequencing for next-generation headsets.
Market Dynamics
Micro-OLED deposition throughput constraints are compressing supply elasticity for near-eye displays, forcing procurement teams to secure capacity eighteen months ahead of volume ramps while LCD-legacy fabs struggle to retool for pixel-density requirements.
Growth Catalysts
- Surgical Visualization Demand:Healthcare systems in Germany and the United States are integrating head-worn displays into operating theater workflows, with hospitals in Bavaria and Texas piloting AR overlays for minimally invasive procedures.
- EU AI Act Compliance Pathways:CE marking harmonization for wearable electronics is creating predictable certification timelines, reducing regulatory friction for device manufacturers targeting European clinical and industrial deployments.
- Micro-LED Epitaxy Advances:GaN-on-sapphire wafer processing breakthroughs are extending luminance ceilings for outdoor-readable AR glasses, opening military and field-service applications previously blocked by sunlight visibility failures.
Market Restraints
- Organic Emitter Material Concentration:Precursor chemical supply for phosphorescent OLED emitters concentrates among Japanese and South Korean specialty chemical houses, exposing panel makers to single-source risk.
- Wafer-Scale Cost Barriers:Silicon backplane fabrication at semiconductor-grade node density requires 300mm CMOS foundry access, pricing out mid-tier VR headset manufacturers from micro-OLED supply.
- Biocompatibility Testing Burden:FDA 510(k) and EU MDR skin-contact certification for extended-wear devices adds fourteen-to-eighteen month validation timelines before commercial distribution.
Strategic Opportunities
- Remote Diagnostics Infrastructure:Telemedicine platforms in rural India and Southeast Asia are procuring low-latency VR headsets for specialist consultation, creating volume demand outside gaming-centric markets.
- Waveguide Manufacturing Localization:Diffractive optical element fabrication is shifting from contract optics houses to captive lines within display panel facilities, compressing bill-of-material costs for smart glasses.
- NMPA Optical Safety Fast-Track:China's streamlined GB standards certification for near-eye displays is accelerating domestic product launches ahead of Western regulatory timelines.
Industry Challenges
- Deposition Equipment Bottleneck:Canon Tokki and Sunic System evaporation tool order backlogs extend to thirty-six months, constraining micro-OLED capacity expansion regardless of capital availability.
- Optical Stack Integration Complexity:Waveguide bonding with micro-display engines requires sub-micron alignment precision that existing contract manufacturers cannot consistently achieve at volume scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extended Reality Display Market |
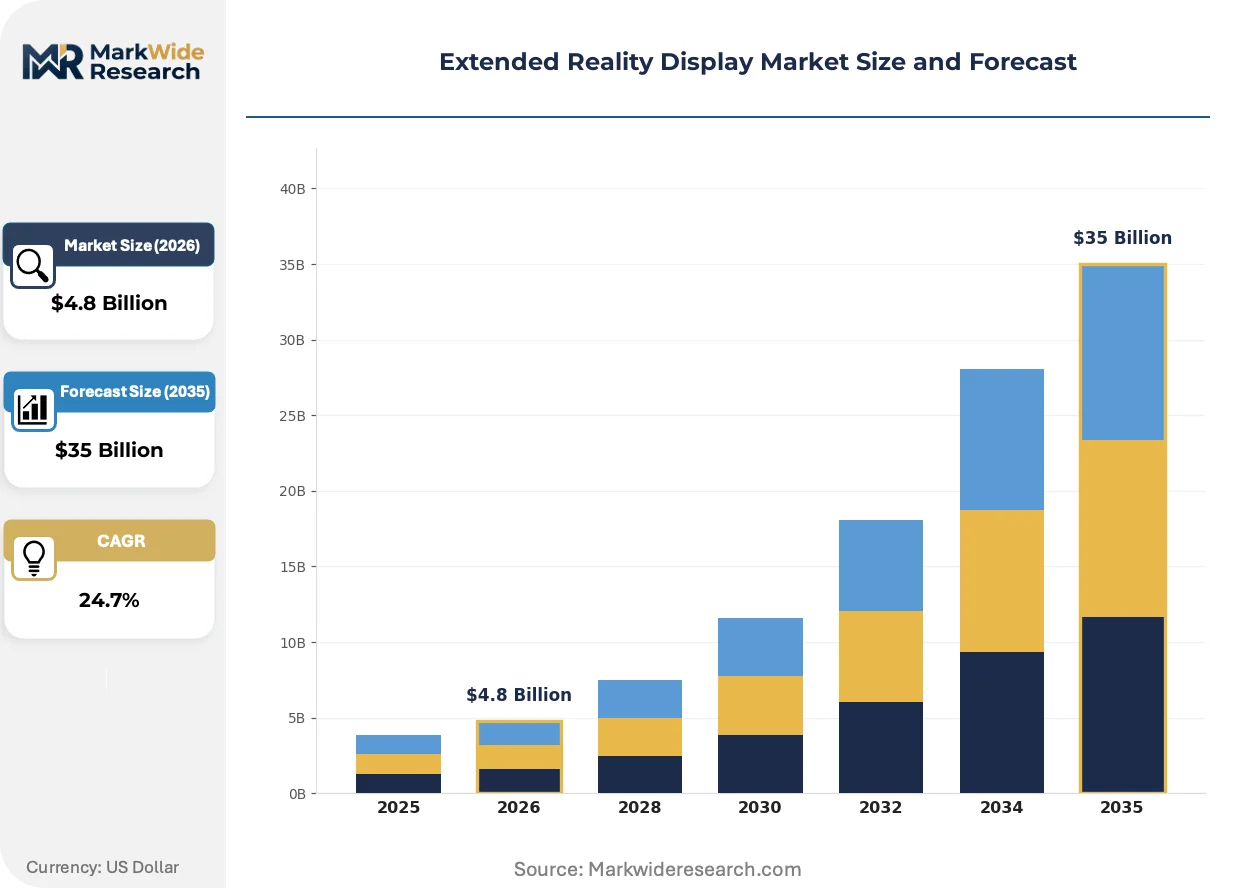
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AR Headsets, VR Headsets, Smart Glasses, Display Screens Technology: Motion Tracking, Stereoscopic 3D, Haptic Feedback, Spatial Audio Application: Entertainment, Education, Healthcare, Military Training End User: Consumers, Enterprises, Healthcare Professionals, Educational Institutions |
| Companies Covered | Sony Corporation, Samsung Electronics Co., Ltd., Kopin Corporation, Japan Display, Inc., Lumus, Ltd., LG Display Co., Ltd., eMagin Corporation, Seiko Epson Corporation, BOE Technology Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extended Reality Display Market Shifts & Advancements
Display architecture decisions are polarizing around luminance-per-watt efficiency and form-factor miniaturization, with technology choices made today locking in competitive positioning for the 2027-2030 product generation.
Micro-LED is supplanting OLED in sunlight-readable AR applications where luminance requirements exceed three thousand nits. Military procurement offices in the United States and Germany are specifying micro-LED engines for dismounted soldier programs, while surgical device manufacturers in Switzerland evaluate the technology for overhead-lighting-independent visualization. This displacement is compressing development timelines for OLED-legacy suppliers unable to bridge the luminance gap through tandem stack architectures.
The EU AI Act's risk-classification framework for biometric inference systems is mandating conformity assessment procedures for gaze-tracking displays before CE marking. Device manufacturers targeting European enterprise markets must now document algorithmic transparency for eye-data processing, adding documentation burden but creating competitive moats against non-compliant imports. Smart glasses with embedded biometric sensors face the steepest compliance gradients under this regime.
Healthcare procurement departments are consolidating vendor relationships around vertically integrated display-engine suppliers capable of delivering FDA-validated optical safety documentation. Hospital systems in California and Massachusetts now require pre-submission meeting records with the FDA's Center for Devices and Radiological Health as a qualification criterion, displacing component-only vendors lacking regulatory affairs infrastructure. This concentration is visible most acutely in academic medical center purchasing consortia.
Extended Reality Display Market Segmentation
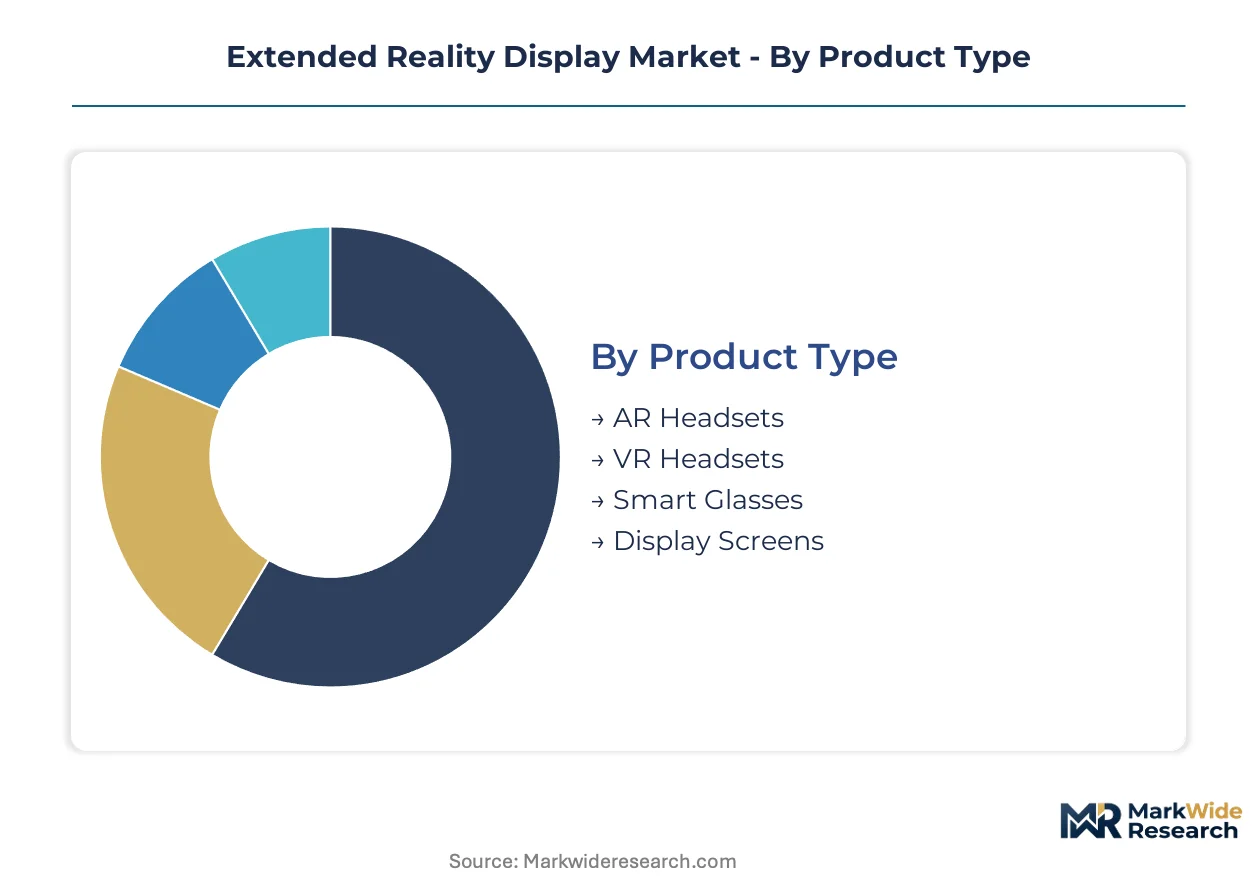
Extended Reality Display market segmentation reveals how technical specifications and use-case requirements fragment procurement patterns. Product architecture choices lock manufacturers into multi-year supply commitments, while end-user certification needs create divergent go-to-market pathways.
Product Type:
VR Headsets face the strongest substitution pressure from micro-LED enabled AR form factors that promise comparable immersion without isolation from physical environments.
- VR Headsets:Fully immersive displays utilizing dual high-density micro-OLED or LCD panels with 90-120Hz refresh rates and sub-20ms motion-to-photon latency. Gaming studios in Bavaria and enterprise training centers in Texas are consolidating procurement around semiconductor-grade panel suppliers capable of FDA pre-submission documentation.
- Smart Glasses:Waveguide-coupled micro-displays enabling see-through augmentation with sub-10 gram optical engines. Optical waveguide manufacturing is localizing to captive display fab lines in China, compressing bill-of-material costs for all-day wearable devices.
- AR Headsets:Sunlight-readable luminance engines exceeding three thousand nits for military and surgical visualization. Military procurement offices in Germany and the United States specify micro-LED architectures for dismounted soldier programs.
- Display Screens:Panel-only supply for integration into custom head-worn devices by third-party OEMs. Foundry access at 300mm CMOS node density restricts supply to vertically integrated semiconductor houses.
VR Headsets anchors the volume base while Smart Glasses gains share at the steepest rate.
Technology:
Cost tier separation is most pronounced between deposition-intensive emitter technologies and software-defined spatial computing layers.
- Motion Tracking:Inertial measurement unit fusion with computer vision for six-degrees-of-freedom positioning. Surgical device manufacturers in Switzerland evaluate sub-millimeter precision for instrument guidance overlays.
- Stereoscopic 3D:Dual-panel parallax rendering with vergence-accommodation conflict mitigation through varifocal optics. Healthcare systems in Massachusetts require pre-submission meeting records with FDA's Center for Devices and Radiological Health as qualification criteria.
- Haptic Feedback:Electromagnetic and piezoelectric actuators providing tactile response in enterprise training simulations. Industrial safety regulators in Germany mandate electromagnetic exposure certification under EU MDR biocompatibility frameworks.
- Spatial Audio:Head-related transfer function modeling for directional sound field reconstruction. Gaming platforms in rural India and Southeast Asia procure low-latency implementations for specialist telemedicine consultation.
Stereoscopic 3D commands premium pricing in healthcare-certified deployments while Spatial Audio expands most quickly in cost-sensitive education markets.
Application:
Volume concentration varies sharply between entertainment-driven consumer procurement and validation-intensive clinical deployments.
- Entertainment:Gaming and immersive media consumption driving panel procurement at scale. Content studios in California anchor demand for 4K-per-eye resolution targets.
- Healthcare:Surgical visualization and remote diagnostic platforms requiring FDA 510(k) or EU MDR certification. Hospital purchasing consortia in academic medical centers now require vertically integrated display-engine suppliers with regulatory affairs infrastructure.
- Military Training:Sunlight-readable AR for dismounted soldier programs and simulator-based skill acquisition. Procurement offices specify micro-LED luminance thresholds exceeding legacy OLED capabilities.
- Education:Institutional VR labs and remote collaboration platforms for technical training. Volume demand is concentrating in China's domestic OEM ecosystem under NMPA optical safety fast-track pathways.
Entertainment anchors the volume base while Healthcare commands the steepest margin expansion trajectory.
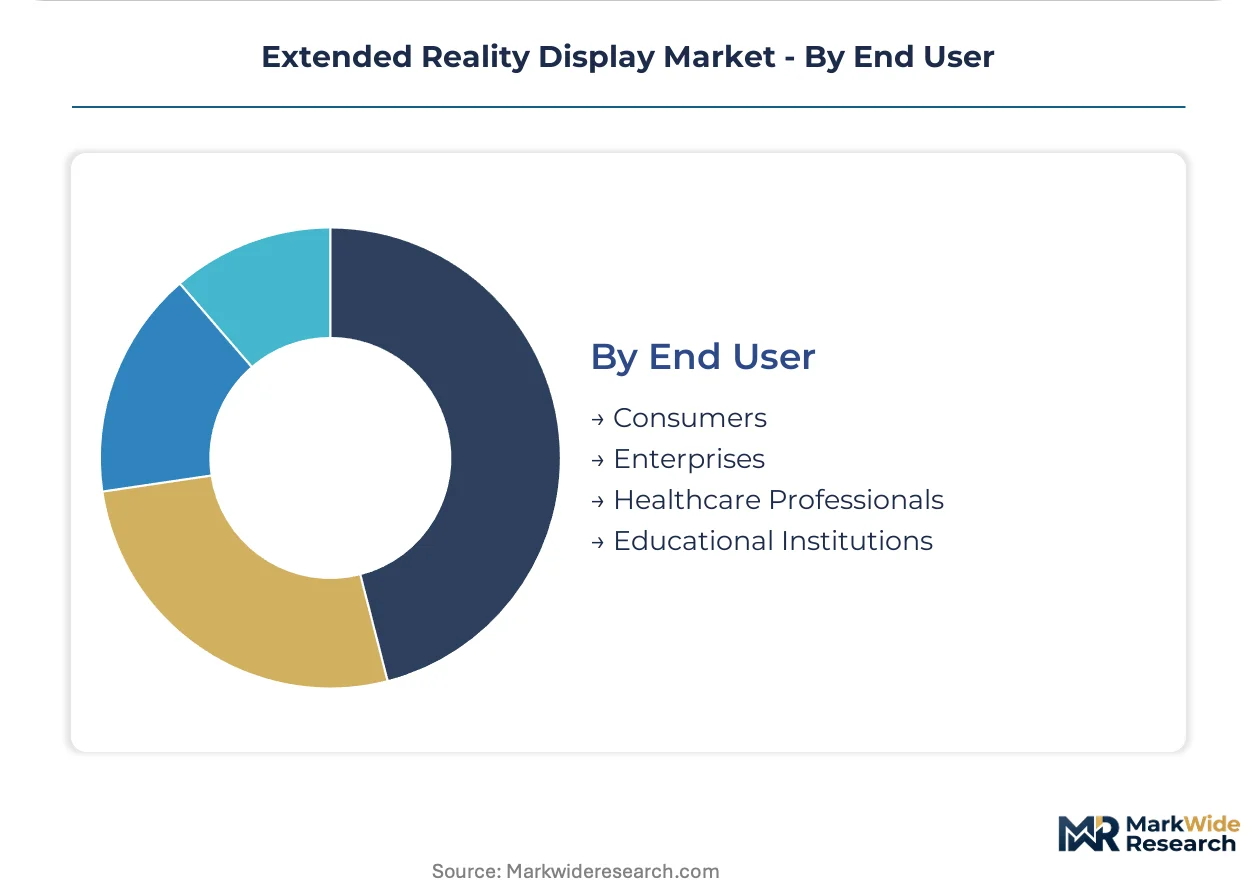
End User:
Customer type determines whether procurement prioritizes unit cost minimization or regulatory documentation depth.
- Healthcare Professionals:Surgeons and diagnostic specialists requiring FDA-validated optical safety documentation. EMA coordination with notified bodies under EU MDR harmonizes biocompatibility standards for wearable displays across Europe.
- Enterprises:Industrial training and field-service deployment with durability and service-life specifications. Manufacturing clusters in Germany integrate head-worn displays into operating theater workflows with CE marking harmonization.
- Consumers:Gaming and personal entertainment with price sensitivity and content ecosystem lock-in. BOE Technology and domestic OEMs in China are building dedicated microdisplay fabs for mainstream VR headset supply.
- Educational Institutions:Volume procurement for classroom and laboratory deployment with total-cost-of-ownership constraints. Telemedicine platforms in rural India source low-latency headsets for specialist consultation outside gaming-centric markets.
Consumers anchors the volume base while Healthcare Professionals gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for micro-OLED deposition equipment tilts trade balances toward East Asian fabrication hubs while Western markets absorb finished display engines for healthcare and defense applications.
United States
Military procurement offices in Arlington and surgical device manufacturers in Massachusetts drive demand for sunlight-readable micro-LED engines. FDA 510(k) pre-submission requirements for near-eye displays used in clinical decision support extend validation timelines. Boston-area academic medical centers consolidate purchasing around vertically integrated suppliers with regulatory affairs infrastructure.
Germany
Bavarian hospital systems pilot AR overlays for minimally invasive procedures while industrial training centers in North Rhine-Westphalia procure VR headsets for workforce certification. EU AI Act conformity assessment for biometric gaze-tracking adds documentation burden before CE marking. Stuttgart and Munich clusters concentrate waveguide integration capabilities for enterprise smart glasses.
China
Domestic OEMs and BOE Technology anchor capacity expansion through dedicated microdisplay fabs in the Yangtze River Delta. NMPA and MIIT joint GB standards for optical safety and data transmission security accelerate domestic product launches. Beijing-Tianjin-Hebei corridor concentrates silicon backplane foundry access for 300mm CMOS node production.
Japan
Specialty chemical houses concentrate precursor supply for phosphorescent OLED emitters, creating single-source exposure for panel makers globally. METI coordinates national project funding for micro-LED epitaxy equipment development. Tokyo-Osaka industrial corridor hosts precision deposition tool manufacturers with thirty-six month order backlogs.
South Korea
Samsung Electronics anchors in-house material sourcing for high-resolution panels, reducing import dependence for organic emitter chemicals. MFDS harmonizes electromagnetic exposure standards with EU MDR frameworks for wearable display exports. Gyeonggi-do cluster concentrates semiconductor-grade deposition expertise for premium near-eye display supply.
Extended Reality Display Market Competitive Landscape
Concentration sits with semiconductor-grade deposition specialists and LCD-legacy panel makers pursuing divergent capacity strategies. Micro-OLED throughput constraints compress supply elasticity, forcing procurement teams to secure fab capacity eighteen months ahead of volume ramps. Two archetypes dominate: vertically integrated display-engine suppliers with regulatory documentation depth, and wafer-scale cost competitors serving mainstream VR volume. Competitive moves center on captive waveguide manufacturing localization and backward integration into silicon backplane foundry access.
Among East Asian fabricators, Sony Corporation exemplifies the deposition-technology archetype leveraging semiconductor-grade expertise, Samsung Electronics Co., Ltd. occupies a position defined by in-house material sourcing security, and BOE Technology Group Co., Ltd. anchors the wafer-scale cost tier for mainstream headset supply.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics Co., Ltd. |
| Kopin Corporation |
| Japan Display, Inc. |
| Lumus, Ltd. |
| LG Display Co., Ltd. |
| eMagin Corporation |
| Seiko Epson Corporation |
| BOE Technology Group Co., Ltd. |
| Others |
Supply & Pricing Matrix
300mm CMOS foundry utilization rates above ninety percent are compressing supply elasticity for micro-OLED backplanes while simultaneously elevating price floors for near-eye display procurement. This scale-concentration dynamic rewards panel makers with captive silicon access and pressures mid-tier VR headset manufacturers toward LCD-legacy alternatives or extended supplier lead times.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Extended Reality Display market. Healthcare-certified panels with FDA pre-submission documentation command substantial premiums over gaming-tier alternatives, while volume scale and semiconductor-grade deposition expertise serve as the primary price differentiation drivers. Cost compression in mainstream VR headset tiers is intensifying because BOE Technology and domestic Chinese OEMs are aggressively expanding wafer-scale manufacturing capacity. Educational institutions and rural telemedicine platforms in Southeast Asia exhibit the highest price sensitivity, whereas military procurement offices and academic medical centers demonstrate minimal elasticity due to stringent validation requirements.
Supply Chain Analysis
Japan and South Korea anchor precursor chemical production for phosphorescent OLED emitters, while Taiwan and China concentrate silicon backplane fabrication at advanced CMOS nodes. The supply chain draws from specialty chemical houses for organic emitter materials, 300mm foundry capacity for backplane wafers, and precision evaporation tools from Canon Tokki and Sunic System. Single-source vulnerability concentrates in deposition equipment order backlogs extending thirty-six months, constraining capacity expansion regardless of capital availability. Distribution runs through vertically integrated display-engine suppliers serving healthcare and defense OEMs directly, with component-only vendors increasingly displaced from certified procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Extended Reality Display market is approaching a platform-economics inflection where interoperability between spatial computing engines and healthcare IT systems will determine competitive survival. Apple's Vision Pro and Meta's Quest ecosystem investments are accelerating this shift toward integrated hardware-software-validation stacks.
For Market Incumbents: Consolidate regulatory affairs infrastructure around FDA 510(k) and EU MDR pre-certification pathways to defend against emerging Chinese competitors leveraging NMPA fast-track advantages. Prioritize backward integration into silicon backplane foundry access or binding capacity agreements with TSMC and Samsung Foundry to secure semiconductor-grade supply. Micro-LED epitaxy capabilities represent the critical R&D lever for maintaining premium positioning in sunlight-readable AR applications.
For New Entrants and Emerging Players: Anchor in remote diagnostics infrastructure for rural India and Southeast Asia, where telemedicine platforms are procuring low-latency VR headsets outside gaming-centric markets with reduced certification burdens. Waveguide manufacturing localization presents the most penetrable white-space opportunity, as diffractive optical element fabrication shifts from contract optics houses to captive display fab lines. A software-defined spatial audio and haptic feedback go-to-market angle bypasses the deposition equipment bottleneck constraining micro-OLED specialists.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated display-engine suppliers with regulatory documentation depth over component-only vendors lacking FDA validation infrastructure. Long-term viability across the projection horizon rests on securing silicon backplane foundry access and micro-LED epitaxy capabilities before the 2027-2030 product generation locks in competitive positioning. The signal to watch is NMPA certification timelines relative to FDA and EMA pathways, as mutual recognition gaps will fragment go-to-market sequencing and reward first-movers in streamlined jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-LED Epitaxy Investment | Military procurement offices in Germany and the United States specify luminance thresholds exceeding legacy OLED capabilities for dismounted soldier programs. |
| Waveguide Manufacturing Localization | Captive diffractive optical element fabrication in Chinese display fabs compresses bill-of-material costs for all-day wearable smart glasses. |
| FDA Pre-Submission Documentation | Hospital purchasing consortia in Massachusetts and California now require meeting records with the Center for Devices and Radiological Health as qualification criteria. |
| Silicon Backplane Foundry Access | 300mm CMOS node density requirements restrict micro-OLED supply to vertically integrated semiconductor houses, pricing out mid-tier competitors. |
| EU AI Act Conformity Assessment | CE marking harmonization for biometric gaze-tracking displays creates competitive moats against non-compliant imports in European enterprise markets. |
Research Methodology
Operator-level perspectives from display panel procurement managers, surgical visualization system architects, military program office engineers, and waveguide integration specialists anchored the qualitative base for this study. Primary interviews with deposition equipment vendors, specialty chemical suppliers, and healthcare GPO contracts managers combined with secondary validation against SEC 10-K filings, FDA 510(k) submission databases, NMPA registration records, and EU MDR notified body documentation. Bottom-up triangulation across fab capacity announcements and top-down reconciliation against OEM headset shipment estimates ensured cross-verified demand quantification.
Sensitivity analysis across technology adoption curves, regulatory pathway timelines, and foundry capacity expansion schedules informed the analytical framework. Segmentation dimensions modeled include product architecture, emitter technology, application certification tier, and regional regulatory cluster throughout the forecast period. CAGRs were derived from installed base growth, replacement cycle compression, and penetration rate assumptions across healthcare, military, and enterprise training verticals. Industry-specific inputs incorporated micro-OLED deposition throughput constraints, waveguide yield learning curves, and biocompatibility validation timeline distributions.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor-grade foundry access concentration and stable regulatory harmonization trajectories; material deviation in equipment order backlogs or mutual recognition agreement progress would warrant model refresh. Specific risk factors include tariff exposure for precursor chemical imports, single-source vulnerability in evaporation tool supply, and divergence in NMPA-FDA-EMA certification sequencing. Recalibration cycles align with material shifts in deposition equipment delivery schedules, micro-LED epitaxy yield breakthroughs, and healthcare procurement consortium vendor consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market