
 VR Ski Machines Market | 2026-2036
VR Ski Machines Market Size, Share, and Industry Trends Forecast 2026-2036
VR Ski Machines Market Insights
VR motion-capture engineering talent is bifurcating between entertainment and sports-science applications, tightening the labor pool for ski-simulator developers. SkyTechSport leverages its Los Angeles manufacturing base to sustain North American supply of Olympic-grade training rigs. ICAROS GmbH differentiates through German-engineered haptic platforms that anchor European commercial fitness demand. Guangzhou Zhuoyuan Virtual Reality Tech competes on production scale, occupying the mid-market rental and arcade channel across Asia.
VR ski machines integrate electromechanical motion bases with head-mounted displays and force-feedback controllers to replicate alpine kinematics, typically achieving ±25 degrees of pitch and roll deflection for slope-angle simulation. The apparatus serves commercial fitness operators, military training programs, and entertainment venues requiring repeatable snow-sport exposure without geographic or seasonal dependency. Simulator rigs command the premium tier due to full six-degree-of-freedom motion platforms and integrated avalanche-safety training modules, while mobile platforms represent the fastest-expanding segment as pop-up installations penetrate secondary cities lacking permanent ski infrastructure. Hybrid trainers concentrate margin pools at the home-user boundary, blending compact storage with resort-branded content libraries.
FCC electromagnetic emissions certification governs US market access for wireless VR headsets and motion-base controllers, while CE marking under the EU Machinery Directive mandates emergency-stop protocols and structural load testing for public installations. Japan's METI oversees electrical appliance safety standards that constrain import pathways for non-JIS-compliant power systems. Stakeholders must monitor evolving liability frameworks around motion-sickness claims and biometric data collection as usage expands from entertainment into rehabilitation and military readiness applications.
Market Dynamics
Climate-driven season compression across alpine regions is forcing ski resorts and fitness operators toward indoor simulation infrastructure, redirecting capital from lift upgrades to electromechanical motion platforms and resort-branded content libraries.
Growth Catalysts
- EU Machinery Directive compliance:CE marking mandates for emergency-stop protocols and structural load testing are accelerating replacement cycles in European commercial fitness centers.
- Japan's aging resort infrastructure:METI-supervised electrical appliance standards are channeling investment toward year-round experiential attractions as natural snowfall declines.
- Force-feedback controller miniaturization:Advances in haptic engineering are reducing platform footprint requirements for mid-market arcade and rental deployments.
Market Restraints
- Motion platform supply concentration:German and Japanese electromechanical component suppliers dominate six-degree-of-freedom base production, creating import dependency for North American assemblers.
- Biometric data liability exposure:Expanding usage into rehabilitation and military readiness applications is generating unresolved legal frameworks around physiological monitoring and motion-sickness claims.
- High-fidelity VR headset cost structure:Wireless HMD electromagnetic certification requirements under FCC Part 15 constrain hardware sourcing flexibility and inflate unit economics for pop-up installations.
Strategic Opportunities
- Military readiness applications:Avalanche-safety training modules integrated into simulator rigs are opening procurement channels with defense ministries seeking repeatable alpine exposure without deployment logistics.
- Secondary city pop-up channels:Mobile platform configurations are penetrating municipalities lacking permanent ski infrastructure, creating first-mover positioning in unserved geographic clusters.
- Rehabilitation therapy convergence:Physical therapy clinics are adopting pitch-and-roll deflection systems for proprioceptive training, extending addressable market beyond entertainment and fitness verticals.
Industry Challenges
- VR motion-capture engineering scarcity:Talent bifurcation between entertainment and sports-science applications is tightening recruitment pipelines for ski-simulator developers.
- Cross-jurisdiction certification timelines:Simultaneous FCC, CE, and METI compliance processes extend product launch cycles by 8-14 months for multi-region distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Ski Machines Market |
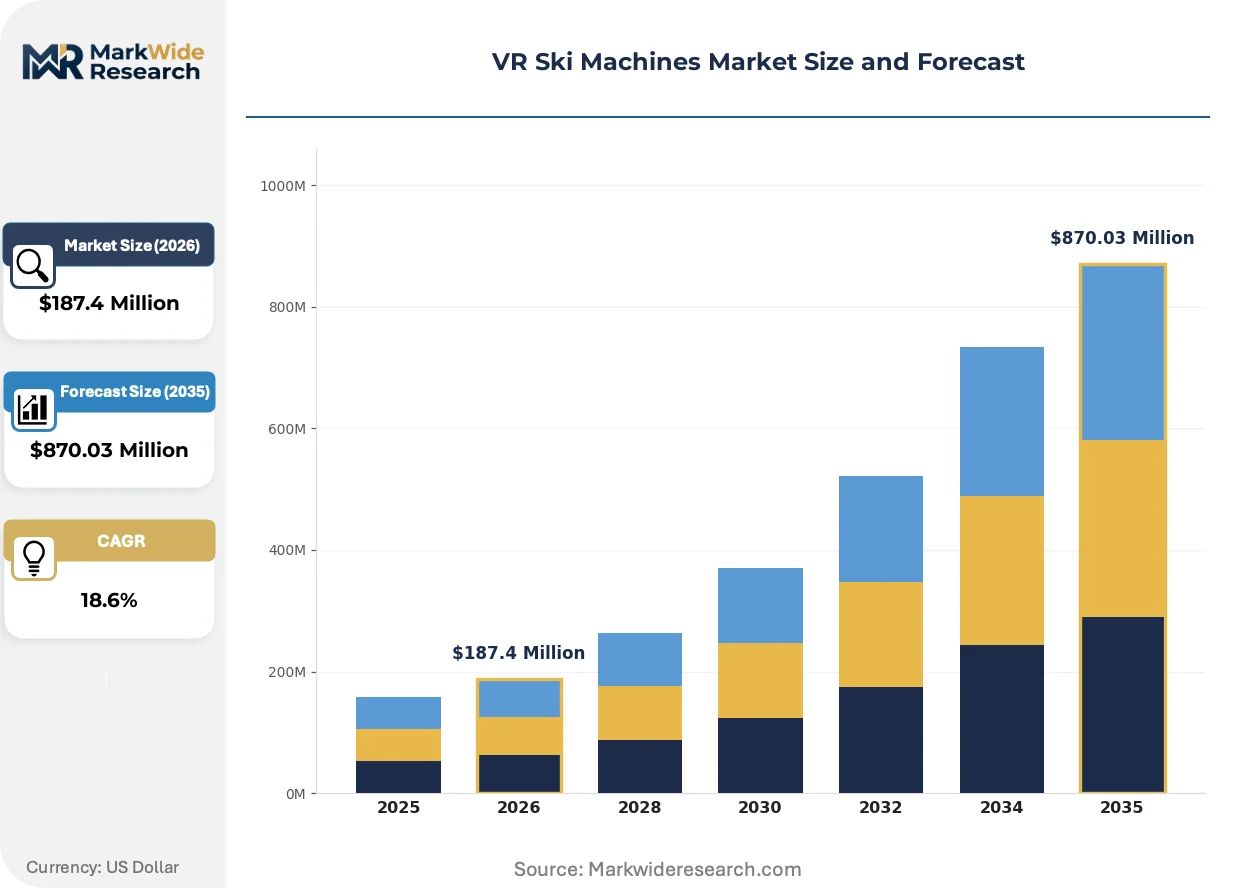
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Machines, Simulator Rigs, Mobile Platforms, Hybrid Trainers Technology: Motion Tracking, VR Headsets, Haptic Feedback, Augmented Reality End User: Fitness Centers, Home Users, Ski Resorts, Military Training Distribution Channel: Online Stores, Specialty Retailers, Direct Sales, Rental Services |
| Companies Covered | VART VR, Aeroski, SkyTechSport, Urban Slopes, Holodia, Xindy Animation, Guangzhou Zhuoyuan Virtual Reality Tech, Guangzhou EPARK Electronic Technology, ICAROS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Ski Machines Market Trends and Innovations
Electromechanical motion base architectures are diverging between Olympic-grade precision rigs and cost-optimized rental platforms, reshaping how manufacturers configure supply chains and content partnerships.
Force-feedback haptic systems are fragmenting the premium tier as German-engineered platforms with ±25-degree pitch and roll deflection anchor European commercial demand while simplified two-degree-of-freedom bases capture Asian arcade volume. Ski resorts in Austria and Switzerland are prioritizing full kinematic replication for training authenticity. This divergence is compressing margin pools at the mid-market boundary as buyers polarize toward either performance or accessibility.
CE marking under the EU Machinery Directive is tightening emergency-stop and structural load protocols for public installations, forcing manufacturers toward certified motion platform suppliers. German fitness center operators are absorbing compliance costs through longer depreciation schedules. The regulatory friction is disadvantaging non-EU assemblers lacking in-house testing facilities.
Resort-branded content libraries are displacing generic slope simulations as procurement criteria shift toward experiential differentiation. Japanese ski operators are commissioning proprietary digital terrain models of their physical runs to maintain guest relationships during off-season months. This behavioral pivot is visible most acutely in Hokkaido and Nagano prefectures where aging lift infrastructure investment has stalled.
VR Ski Machines Market Segmentation
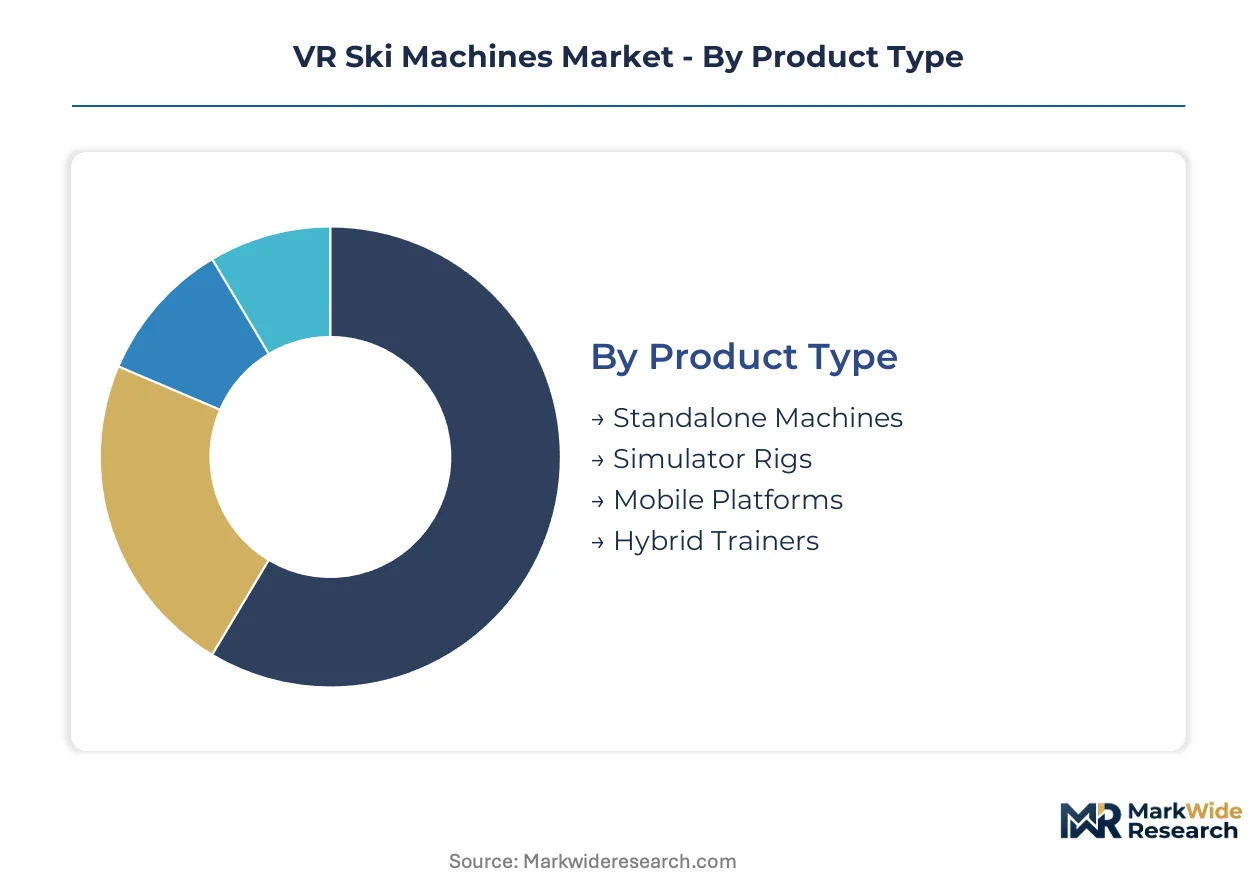
VR ski machine manufacturers configure product portfolios around distinct motion-platform architectures and procurement pathways. Channel strategy varies sharply between permanent commercial installations and transient rental deployments.
Product Type:
Standalone machines flow through specialty fitness retailers, while simulator rigs and mobile platforms concentrate in direct sales and rental channels respectively.
- Simulator Rigs:Full six-degree-of-freedom electromechanical platforms achieve ±25 degrees of pitch and roll deflection for alpine kinematic replication. Austrian and Swiss ski resorts prioritize these systems for training authenticity, absorbing premium pricing through longer depreciation schedules mandated by CE marking compliance.
- Mobile Platforms:Two-degree-of-freedom bases with compact footprints enable pop-up installations in secondary cities lacking permanent ski infrastructure. Japanese arcade operators and Asian rental channels drive volume procurement, trading fidelity for deployment flexibility.
- Standalone Machines:Self-contained units with integrated displays serve home users and small fitness centers requiring minimal installation support.
- Hybrid Trainers:Compact storage designs with resort-branded content libraries target the home-user boundary, blending accessibility with experiential differentiation.
By volume, mobile platforms lead. By growth pace, hybrid trainers are climbing the fastest.
Technology:
Technology selection correlates with end-use sophistication: fitness centers demand full haptic stacks, while home users prioritize headset accessibility.
- Haptic Feedback:Force-feedback controllers with miniaturized actuators replicate snow-surface texture and edge grip. German-engineered platforms anchor European commercial demand, while simplified systems capture Asian arcade volume.
- VR Headsets:Wireless HMDs require FCC Part 15 electromagnetic certification, constraining hardware sourcing flexibility for North American assemblers and inflating unit economics.
- Motion Tracking:Electromechanical sensor arrays capture lower-body kinematics for Olympic-grade training applications.
- Augmented Reality:Overlay systems project terrain data onto physical training environments, serving rehabilitation and military readiness verticals.
By installed base, VR headsets dominate. By expansion trajectory, haptic feedback is gaining share fastest.
End User:
Procurement authority concentrates in commercial operators with capital allocation flexibility, while home users remain price-sensitive and specification-constrained.
- Fitness Centers:German operators are expanding VR ski installations as climate-driven season compression redirects capital from traditional equipment. CE marking mandates accelerate replacement cycles for public installations.
- Ski Resorts:Japanese operators in Hokkaido and Nagano prefectures commission proprietary digital terrain models to maintain guest relationships during off-season months, offsetting stalled lift infrastructure investment.
- Military Training:Defense ministries procure simulator rigs with integrated avalanche-safety modules, seeking repeatable alpine exposure without deployment logistics.
- Home Users:Compact hybrid trainers with resort-branded content libraries address storage constraints and experiential expectations.
By revenue concentration, fitness centers lead. By procurement momentum, military training is expanding most quickly.
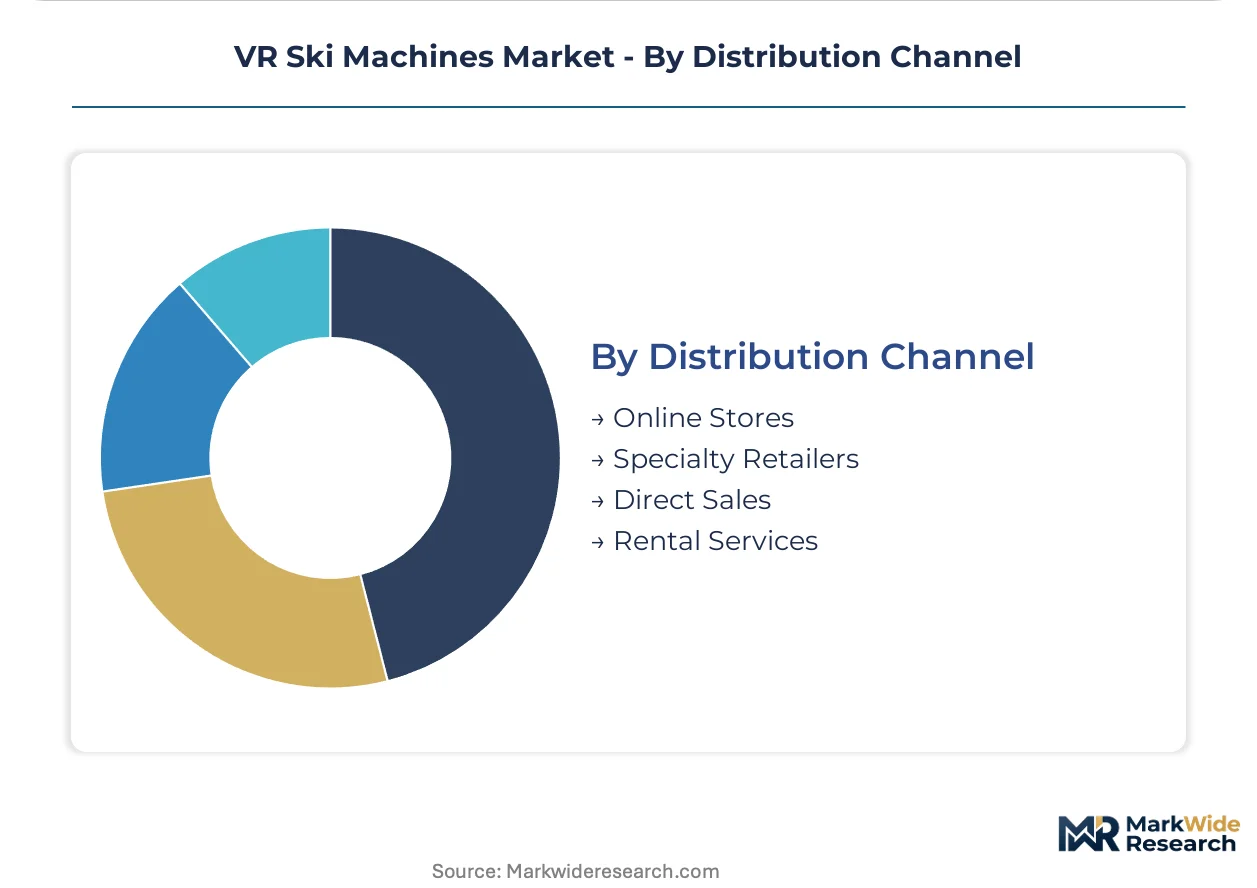
Distribution Channel:
Channel selection reflects asset permanence: capital equipment flows direct, while transient demand activates rental networks.
- Direct Sales:Simulator rigs and full-motion platforms move through manufacturer-direct relationships with ski resorts and defense ministries, bypassing retail margin extraction.
- Rental Services:Mobile platforms penetrate secondary cities and event circuits, creating first-mover positioning in unserved geographic clusters without permanent infrastructure commitment.
- Specialty Retailers:Standalone machines and hybrid trainers reach home users through fitness equipment dealers with installation and service capabilities.
- Online Stores:Entry-level headsets and accessory sales serve price-sensitive segments with minimal technical support requirements.
By transaction volume, rental services lead. By margin retention, direct sales is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys VR ski machines for commercial fitness certification, while Japan channels investment toward resort experiential attractions and the United States concentrates procurement in military training programs. This tripartite consumption split shapes divergent regulatory compliance pathways across major demand centers.
Germany
CE marking under the EU Machinery Directive mandates emergency-stop protocols and structural load testing for public fitness installations. German fitness center operators absorb compliance costs through extended depreciation schedules. The Baden-Württemberg industrial corridor hosts certified motion-platform suppliers serving domestic and cross-border commercial demand.
Japan
Aging ski resorts in Hokkaido and Nagano prefectures commission proprietary digital terrain models to maintain year-round guest engagement. METI electrical appliance safety standards constrain import pathways for non-JIS-compliant power systems. Tokyo-based arcade operators drive volume procurement of compact two-degree-of-freedom platforms for metropolitan entertainment circuits.
United States
Defense ministries procure simulator rigs with integrated avalanche-safety modules for repeatable alpine exposure without deployment logistics. FCC Part 15 electromagnetic emissions certification governs wireless VR headset market access. Los Angeles anchors North American assembly capacity for Olympic-grade training equipment.
China
Guangzhou and Shenzhen manufacturing clusters compete on production scale for mid-market rental and arcade channels across Asia. GB standards and MIIT oversight shape domestic product certification timelines. Pearl River Delta assemblers supply cost-optimized mobile platforms penetrating secondary cities lacking permanent ski infrastructure.
Switzerland
Austrian and Swiss alpine resorts prioritize full six-degree-of-freedom kinematic replication for training authenticity. Swissmedic and federal labor safety frameworks govern commercial installation standards. Zurich and Geneva metropolitan fitness operators represent concentrated premium-tier demand for German-engineered haptic platforms.
VR Ski Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Olympic-grade precision fabricators commanding premium pricing against scale-focused rental equipment suppliers. The market structures around capability differentiation in motion-platform engineering rather than brand recognition or distribution reach. Two strategic archetypes dominate: vertically integrated precision manufacturers with captive electromechanical component production, and modular assemblers sourcing standardized bases for cost-sensitive deployment. Competitive moves concentrate on geographic certification pre-positioning and content-library exclusivity arrangements with ski resort operators.
Among Los Angeles-based precision manufacturers, SkyTechSport occupies a position exemplifying the integrated-leader archetype for North American Olympic-grade supply. ICAROS GmbH represents German-engineered haptic platform specialization anchoring European commercial fitness demand. Guangzhou Zhuoyuan Virtual Reality Tech sits within the scale-driven assembler tier, supplying mid-market rental channels across Asian arcade and pop-up installation networks.
| Leading Market Players |
|---|
| VART VR |
| Aeroski |
| SkyTechSport |
| Urban Slopes |
| Holodia |
| Xindy Animation |
| Guangzhou Zhuoyuan Virtual Reality Tech |
| Guangzhou EPARK Electronic Technology |
| ICAROS GmbH |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Machinery Directive gates supply qualification and price differentiation simultaneously, as emergency-stop protocol certification and structural load testing separate certified motion-platform suppliers from uncertified assemblers while commanding premium positioning in German fitness center procurement.
Pricing Analysis
Long-term offtake contracts dominate simulator rig procurement by defense ministries and alpine resorts, while spot rentals capture mobile platform demand in Asian arcade channels. Price differentiation rests on CE certification tier and six-degree-of-freedom kinematic fidelity, with German-engineered haptic platforms anchoring premium positioning against Guangzhou-scale production. Cost compression in mid-market two-degree-of-freedom bases is intensifying because force-feedback controller miniaturization erodes footprint-based pricing power. Home users exhibit highest price sensitivity; military training programs show least.
Supply Chain Analysis
Inventory lead times for electromechanical motion bases extend from German and Japanese component suppliers, constraining North American assembler flexibility. Production concentrates in Germany, Japan, and China. Supply draws from precision-machined actuators, wireless VR headsets, and force-feedback controller arrays. Single-source vulnerability concentrates in six-degree-of-freedom base manufacturing. Distribution runs through direct sales for permanent installations and rental networks for transient deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resort-branded content libraries represent a service-attach opportunity expanding faster than hardware, as Japanese ski operators commission proprietary digital terrain models to sustain year-round guest engagement.
For Market Incumbents: Secure exclusive content partnerships with Hokkaido and Nagano prefecture resorts before competitor replication. Deepen backward integration into electromechanical motion-base production to reduce dependency on German and Japanese component suppliers. CE marking compliance investment creates switching costs against non-EU assemblers lacking in-house testing facilities.
For New Entrants and Emerging Players: Differentiate on avalanche-safety training module integration for defense ministry procurement channels. Target secondary city pop-up installations across Asian municipalities lacking permanent ski infrastructure. Pursue licensing arrangements with existing arcade rental networks rather than building captive distribution.
For Investors and Strategic Acquirers: METI electrical appliance safety standard revisions reshape the acquisition landscape by channeling Japanese investment toward JIS-compliant power system suppliers. Five-to-ten year viability favors vertically integrated precision manufacturers over modular assemblers exposed to margin compression. Monitor military readiness application contract awards as inflection signal for simulator rig demand acceleration.
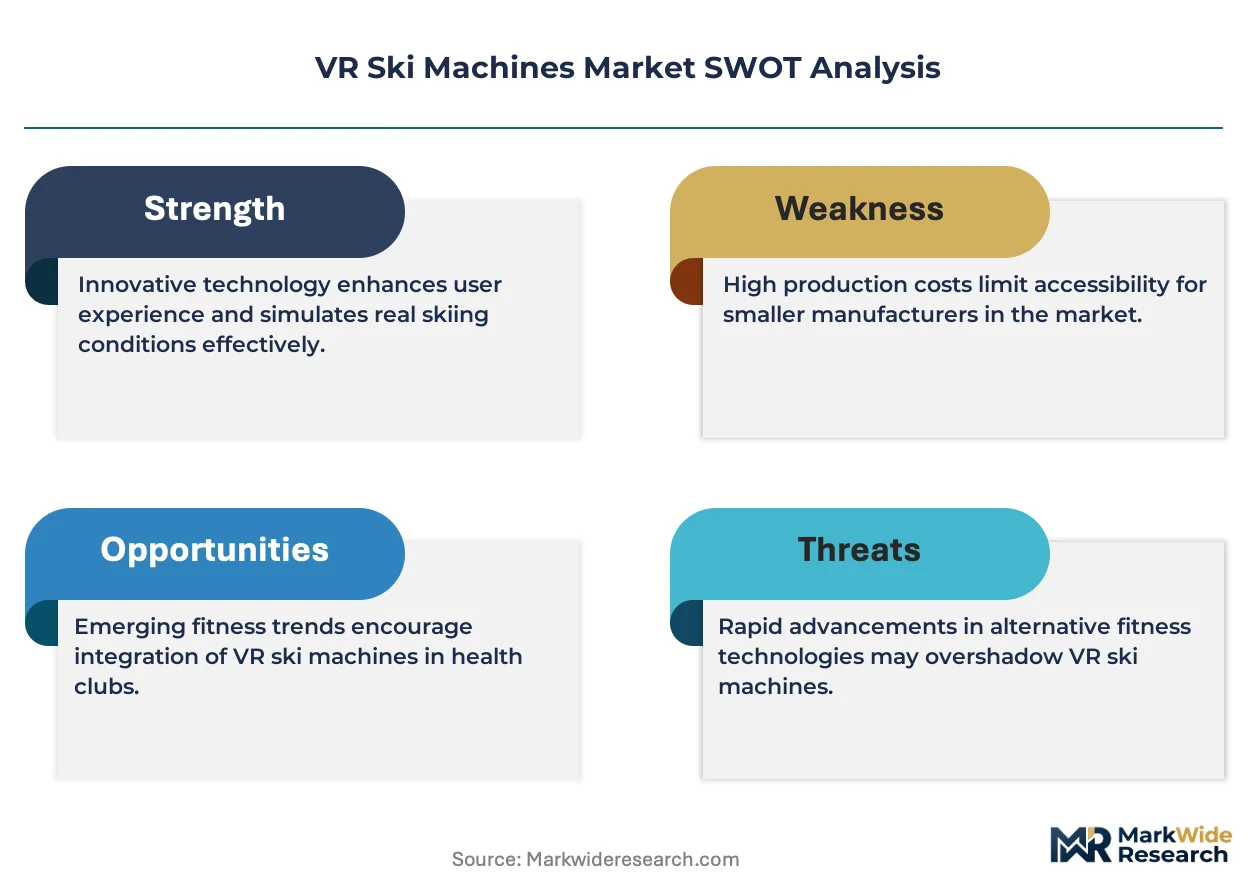
| Strategic Initiative | Industry Significance |
|---|---|
| Resort Content Library Exclusivity | Proprietary digital terrain models from Hokkaido operators lock in year-round guest relationships. |
| CE Marking Certification Investment | Emergency-stop protocol compliance creates regulatory moats against non-EU component assemblers. |
| Military Training Partnership | Avalanche-safety module integration opens defense ministry procurement without deployment logistics. |
| Secondary City Rental Expansion | Mobile platform penetration captures first-mover positioning in Asian municipalities lacking ski infrastructure. |
| Haptic Platform Miniaturization R&D | Reduced footprint requirements enable mid-market arcade volume without sacrificing force-feedback fidelity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with fitness center procurement directors, ski resort operations managers, defense ministry training coordinators, electromechanical component suppliers, and arcade rental network operators. Secondary validation drew from FCC Part 15 electromagnetic emissions filings, EU Machinery Directive compliance registries, METI electrical appliance safety standards, customs trade data for motion-platform components, and SEC disclosures from publicly traded fitness equipment manufacturers. Bottom-up installation counts triangulated against top-down addressable market sizing.
Across the projection horizon, the analytical framework modeled segmentation by motion-platform architecture, end-use vertical, distribution channel permanence, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical penetration rates. Forecast inputs incorporated climate-driven alpine season compression indices and military readiness training budget allocations.
The analysis sits within stated boundaries; outcomes outside sustained defense procurement commitment or accelerated CE marking enforcement would require recalibration. Forecasts reflect documented assumptions around force-feedback controller cost decline curves and wireless VR headset certification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market