
 Virtual Reality All-In-One Headset Market | 2026-2036
Virtual Reality All-In-One Headset Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality All-In-One Headset Market Insights
Asset-light leasing models for enterprise VR fleets is rewriting competitive economics in the all-in-one headset space. Meta leverages its captive content ecosystem to sustain hardware subsidy strategies that lower customer acquisition costs. Sony anchors its position through optical-engine specialization drawn from camera-sensor manufacturing depth. PICO competes aggressively on manufacturing scale out of Chinese production bases.
A virtual reality all-in-one headset integrates display panels, motion processors, battery systems, and tracking sensors into a single untethered wearable unit, typically employing pancake optics or Fresnel lenses to achieve sub-20ms motion-to-photon latency for nausea reduction. Its primary commercial purpose is delivering spatial computing experiences without external computers or base stations. Standalone headsets dominate volume shipments as wireless freedom becomes the default enterprise expectation, while eye-tracking technology captures the fastest upgrade cycle as foveated rendering demands grow. Gaming applications still occupy the largest installed base, though corporate training segments now generate the strongest margin pools per unit through software-subscription attach rates.
FCC equipment authorization and FDA digital therapeutics oversight in the United States, alongside EU GDPR biometric-data restrictions and CE marking under the MDR, collectively raise compliance costs for eye-tracking and haptic-enabled models. These frameworks fragment market access, as manufacturers must maintain parallel firmware and data-residency architectures to serve both jurisdictions. Stakeholders should monitor how regulatory divergence in biometric consent protocols reshapes product roadmaps and geographic rollout sequencing.
Market Dynamics
Foveated rendering architectures are compressing GPU requirements while biometric eye-tracking pipelines trigger GDPR and EU AI Act redesigns across firmware stacks.
Growth Catalysts
- FDA digital therapeutics pathway:Rehabilitation clinics in the United States now procure headsets as Class II medical devices for stroke recovery protocols.
- Pancake optics maturation:Thinner optical stacks reduce headset weight below 300 grams, extending session duration for enterprise training deployments.
- Defense simulation budgets:Military procurement offices in the United States anchor volume through multi-year immersive training contracts.
Market Restraints
- Compound semiconductor supply:Gallium nitride power ICs for compact thermal management concentrate among Taiwanese foundries.
- GDPR biometric friction:EU data residency mandates force parallel cloud architectures, raising per-unit compliance overhead.
- Smartphone VR substitution:Cardboard-style mobile viewers satisfy price-sensitive education segments in emerging markets.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for electronics assembly attract final-assembly relocation from coastal China.
- Haptic-feedback convergence:Integration of force-feedback gloves with standalone headsets opens surgical simulation workflows.
- Leasing model innovation:Asset-light fleet subscriptions reduce enterprise customer acquisition friction.
Industry Challenges
- Optomechanical talent scarcity:Precision lens alignment engineers remain concentrated in Japanese camera-sensor supply chains.
- CE-MDR certification timelines:Biometric-enabled therapeutic models face 18-month conformity assessment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality All-In-One Headset Market |
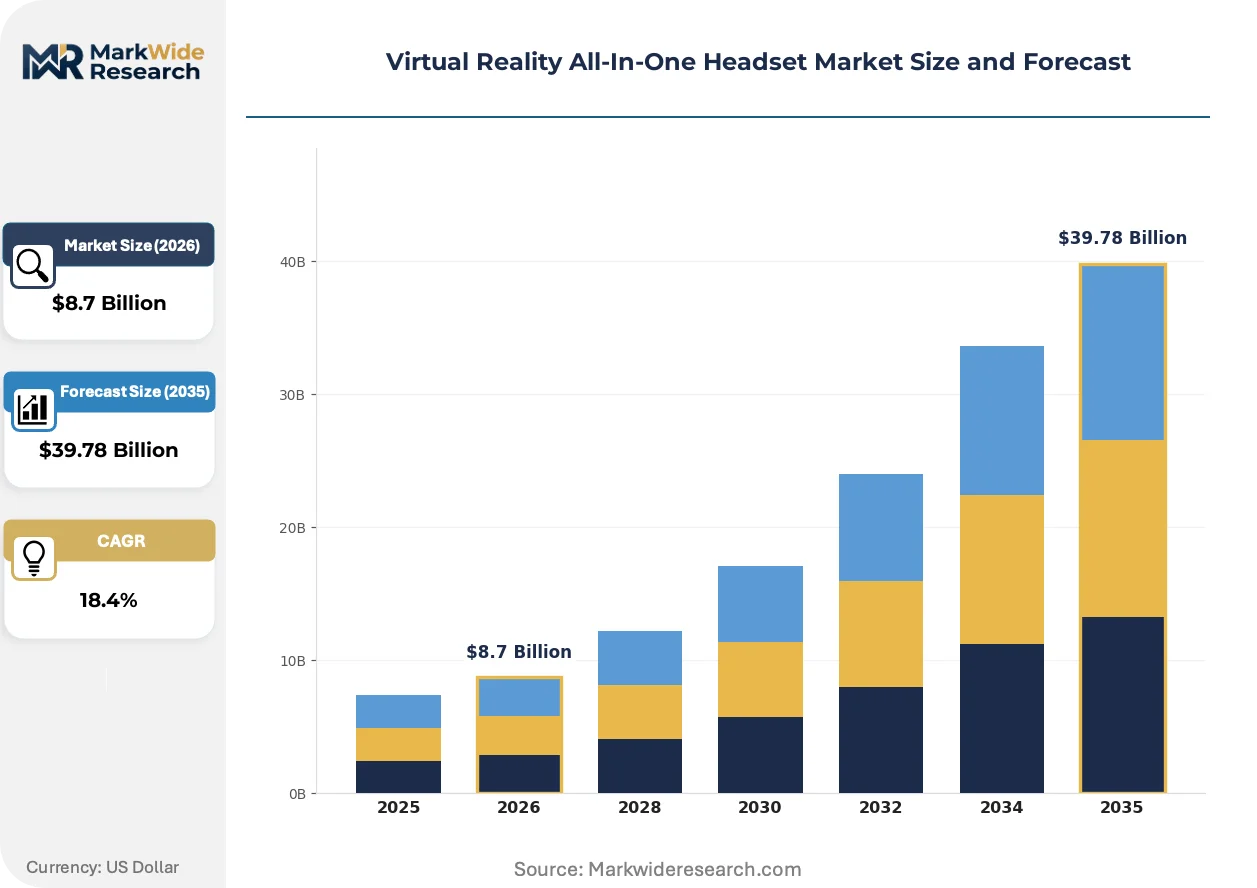
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Mobile, Augmented Reality Technology: Optical, Motion Sensors, Haptic Feedback, Eye Tracking Application: Gaming, Education, Training, Therapy End User: Entertainers, Educators, Therapists, Corporate Trainers |
| Companies Covered | Meta, Sony, Apple, HTC, Samsung Electronics, PICO, Valve, Varjo, DPVR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality All-In-One Headset Market Trends and Innovations
Optical engine miniaturization and biometric sensor fusion are rewriting hardware roadmaps while regulatory fragmentation splits firmware development tracks.
Pancake lens assemblies employing polarization-based light folding are rendering obsolete bulky Fresnel stacks in sub-300-gram enterprise headsets. Healthcare therapy providers in Germany and the United States now specify pancake optics as mandatory for patient comfort during 45-minute rehabilitation sessions. The shift compresses bill-of-materials variance between premium and mid-tier SKUs.
EU AI Act risk-classification rules for biometric inference systems force manufacturers to maintain separate firmware branches for European and non-European markets. Eye-tracking data pipelines must implement on-device processing to avoid prohibited cross-border transfers. Therapeutic headset vendors face the steepest redesign costs as their products fall under both MDR medical device and AI Act high-risk system classifications.
Enterprise buyers now unbundle hardware procurement from software licensing, demanding month-to-month SaaS attachments rather than perpetual training content purchases. Systems integrators in the United States and United Kingdom are displacing direct OEM relationships as the primary contract negotiation layer. This channel shift concentrates margin capture among vertical-specialist software vendors rather than hardware manufacturers.
Virtual Reality All-In-One Headset Market Segmentation
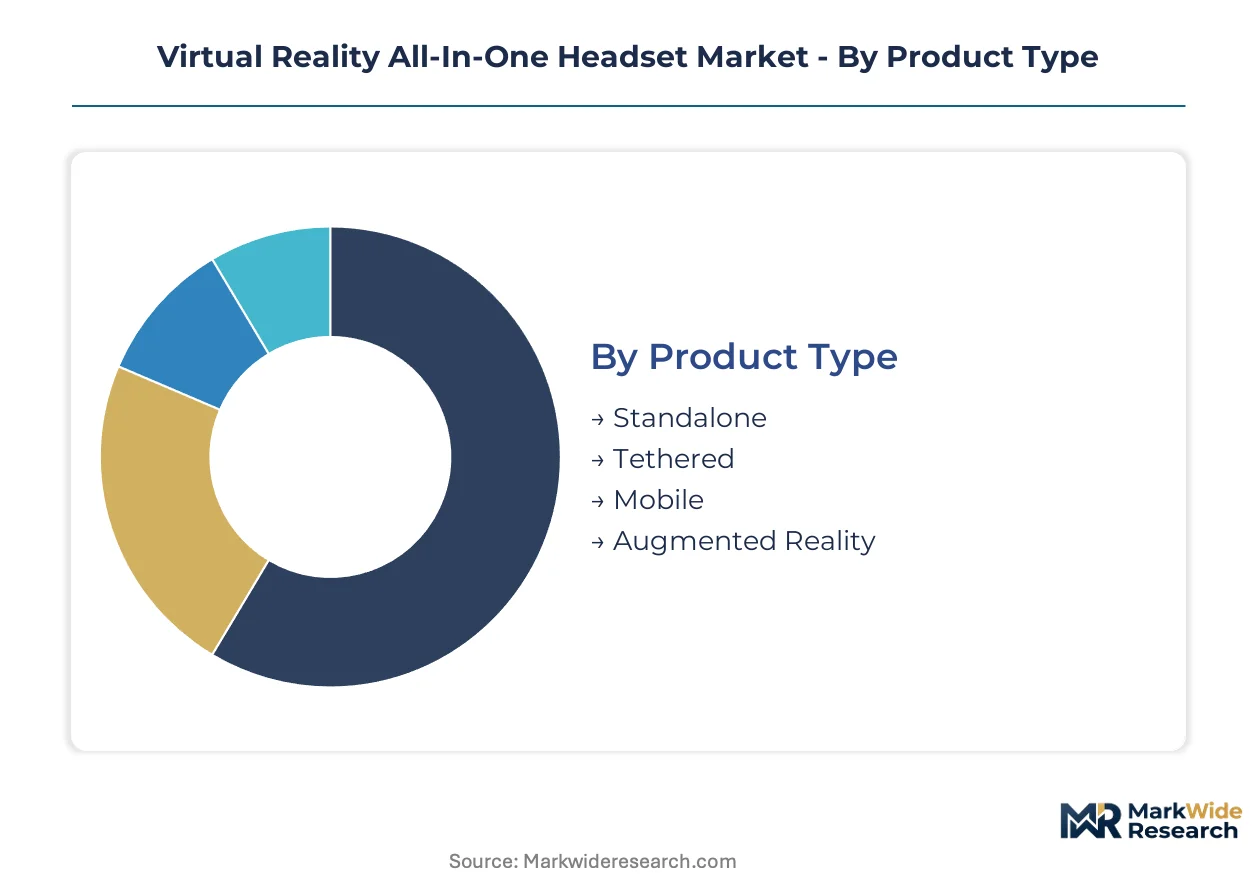
Segmentation in the VR all-in-one headset market reveals divergent hardware specifications and service requirements across use cases. Rehabilitation clinics demand biometric calibration support that gaming retailers rarely provide. Enterprise training fleets require swap-out logistics fundamentally different from education bulk purchases.
Product Type:
After-sales service intensity varies dramatically across form factors, with enterprise standalone deployments demanding 24-hour replacement SLAs that consumer mobile viewers never require.
- Standalone:Integrated compute, battery, and display modules in a single wireless unit. United States defense training contracts specify these for untethered squad simulation exercises where base stations create tactical vulnerabilities. Pancake optics and gallium nitride power management enable sub-300-gram weights critical for 45-minute clinical rehabilitation sessions.
- Tethered:Headsets relying on external PCs or consoles for rendering horsepower. German automotive design studios maintain these for high-fidelity CAD visualization where latency tolerance approaches zero. Cable management and PC compatibility troubleshooting dominate post-purchase support costs.
- Mobile:Smartphone-dependent viewers using handheld device displays and processing. Indian education procurement favors these for cost-sensitive district rollouts where device refresh cycles follow phone replacement patterns rather than dedicated hardware timelines.
- Augmented Reality:See-through optical systems overlaying digital content on physical environments. Japanese manufacturing maintenance workflows deploy these for hands-free assembly guidance requiring environmental spatial mapping.
Standalone holds the largest share; momentum sits with Augmented Reality as industrial maintenance applications expand.
Technology:
Component-level segmentation tracks which sensor modules drive procurement premiums and regulatory exposure.
- Optical:Pancake lens assemblies employing polarization-based light folding. German healthcare providers now mandate these for patient comfort during extended therapeutic sessions, compressing bill-of-materials variance between premium and mid-tier SKUs.
- Motion Sensors:Inertial measurement units and accelerometer arrays tracking head position. United States military simulation contracts require 6DoF precision for disorientation-free combat training scenarios.
- Haptic Feedback:Vibration motors and force-feedback actuators creating tactile response. Surgical training programs in the United Kingdom integrate these with standalone headsets for instrument resistance simulation.
- Eye Tracking:Biometric infrared cameras measuring pupil position and gaze vectors. EU GDPR and AI Act compliance forces on-device processing architectures that raise firmware development costs for European market variants.
Optical systems dominate unit economics; eye tracking is expanding most quickly as foveated rendering reduces GPU requirements.
Application:
Software attach rates and replacement cycles fragment dramatically across use cases, with therapy applications generating subscription revenue streams absent in gaming.
- Gaming:Consumer entertainment experiences driving volume shipments through retail channels. Meta's captive content ecosystem sustains hardware subsidy strategies that lower customer acquisition costs in this segment.
- Education:Classroom deployments for immersive history, science, and vocational instruction. Indian PLI scheme subsidies attract final-assembly relocation for government tender participation.
- Training:Corporate skill development and safety certification programs. United States enterprise buyers now unbundle hardware from SaaS licensing, demanding month-to-month attachments rather than perpetual purchases.
- Therapy:Clinical rehabilitation for stroke recovery, pain management, and cognitive therapy. FDA digital therapeutics pathway classification in the United States positions these as reimbursable Class II medical devices.
Therapy commands the steepest margin pools per unit; training shows the steepest expansion trajectory as fleet leasing models reduce enterprise friction.
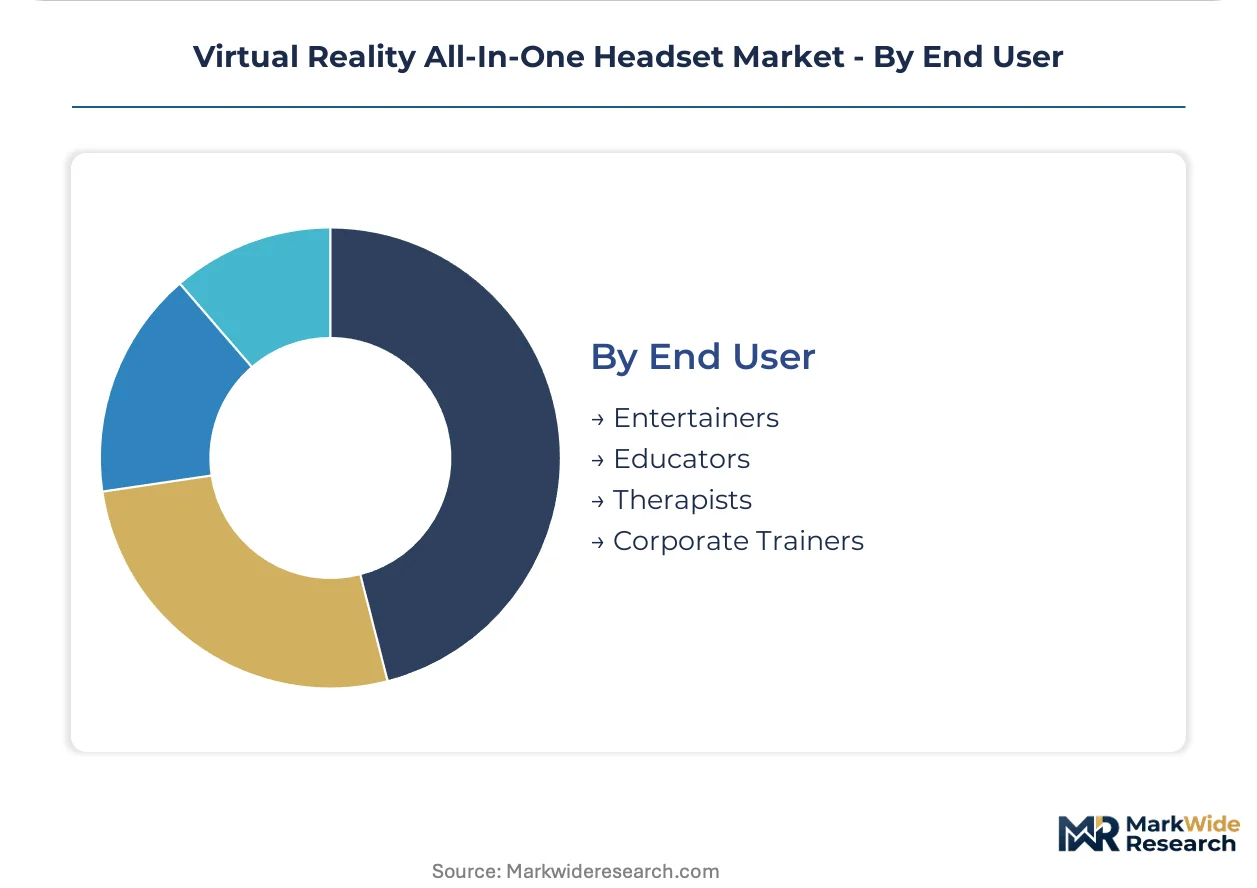
End User:
Procurement authority and budget cycles determine whether sales flow through retail, direct OEM, or systems integrator channels.
- Entertainers:Individual consumers and location-based entertainment venues. Content ecosystem lock-in drives repeat hardware purchases within platform families.
- Educators:K-12 districts and university immersive learning labs. Bulk purchasing consortia concentrate negotiating leverage against vendor list pricing.
- Therapists:Rehabilitation clinics and hospital outpatient departments. CE-MDR certification timelines in Europe extend conformity assessment to 18 months for biometric-enabled therapeutic models.
- Corporate Trainers:Enterprise L&D departments and safety compliance officers. United States and United Kingdom systems integrators displace direct OEM relationships as primary contract negotiation layers.
Corporate trainers represent the largest addressable spend; therapists are gaining share fastest as reimbursement pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of VR all-in-one headsets concentrate in Chinese final-assembly hubs, while import demand clusters in United States enterprise training budgets and German clinical rehabilitation procurement. Trade balances reflect divergent regulatory compliance costs across jurisdictions.
United States
Defense simulation contracts and FDA digital therapeutics pathways drive procurement volume. FCC equipment authorization governs wireless transmission protocols for untethered headsets. Austin and Seattle host systems integrators displacing direct OEM relationships in enterprise fleet negotiations.
Germany
Automotive design studios and rehabilitation clinics anchor demand for high-fidelity visualization. CE marking under MDR and GDPR biometric restrictions impose parallel firmware requirements. Bavarian optical engineering clusters supply precision lens alignment talent for pancake optics manufacturing.
China
Manufacturing scale advantages concentrate final assembly in coastal production bases. MIIT certification and GB standards regulate wireless equipment and data processing architectures. Shenzhen and Dongguan integrate gallium nitride power IC supply chains for compact thermal management.
India
Education procurement and PLI scheme subsidies attract electronics assembly relocation from coastal China. BIS certification and DGFT import duties structure competitive access for foreign OEMs. Karnataka and Tamil Nadu host emerging final-assembly facilities for government tender participation.
Japan
Industrial maintenance workflows and location-based entertainment venues sustain niche demand. METI standards and PMDA oversight govern therapeutic device classifications. Nagoya and Osaka camera-sensor supply chains retain optomechanical engineering concentration for optical engine miniaturization.
Virtual Reality All-In-One Headset Market Competitive Landscape
On the supply side, the industry is consolidating around platform ecosystems while fragmenting across hardware manufacturing tiers. Meta and Sony anchor distinct strategic positions through content lock-in versus optical specialization. Three archetypes dominate: ecosystem-integrated platform holders, component-specialist hardware fabricators, and scale-driven contract manufacturers. Competitive moves concentrate on captive content development and manufacturing relocation to capture subsidy regimes.
Among ecosystem-integrated platform holders, Meta exemplifies hardware subsidy strategies sustained by content ecosystem lock-in. Sony occupies a position anchored through optical-engine specialization drawn from camera-sensor manufacturing depth. PICO represents scale-driven manufacturing competition leveraging Chinese production base advantages. These three entities collectively illustrate how vertical control over content, components, or manufacturing scale determines competitive positioning in procurement negotiations.
| Leading Market Players |
|---|
| Meta |
| Sony |
| Apple |
| HTC |
| Samsung Electronics |
| PICO |
| Valve |
| Varjo |
| DPVR |
| Others |
Pricing and Supply Chain Analysis
The Shenzhen-Los Angeles maritime corridor shapes cost dynamics for VR all-in-one headsets, concentrating supply in Chinese coastal production bases while downstream price differentiation separates enterprise fleet buyers from education procurement segments. Freight rate volatility feeds directly into margin compression for mid-tier SKUs, forcing manufacturers to absorb logistics spikes or sacrifice volume share.
Pricing Analysis
Industrial OEM buyers anchor a SaaS-tiered pricing structure where hardware procurement unbundles from software licensing. Price differentiation rests on certification grade—FDA Class II medical device tiers command premiums against FCC-authorized consumer models—and volume scale for enterprise fleet deployments. Pricing pressure stems from smartphone VR substitution in emerging markets, compressing entry-level margins. Education procurement committees exhibit highest price sensitivity, while defense simulation contracts show lowest elasticity.
Supply Chain Analysis
Export-control restrictions on compound semiconductor manufacturing equipment limit gallium nitride power IC flows from Taiwanese foundries. Supply concentrates in China, Taiwan, and Japan, drawing from gallium nitride substrates, pancake lens glass, and biometric infrared sensor modules. Single-source vulnerability concentrates in Taiwanese GaN foundry capacity. Distribution runs through systems integrators in the United States and United Kingdom, displacing direct OEM relationships for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
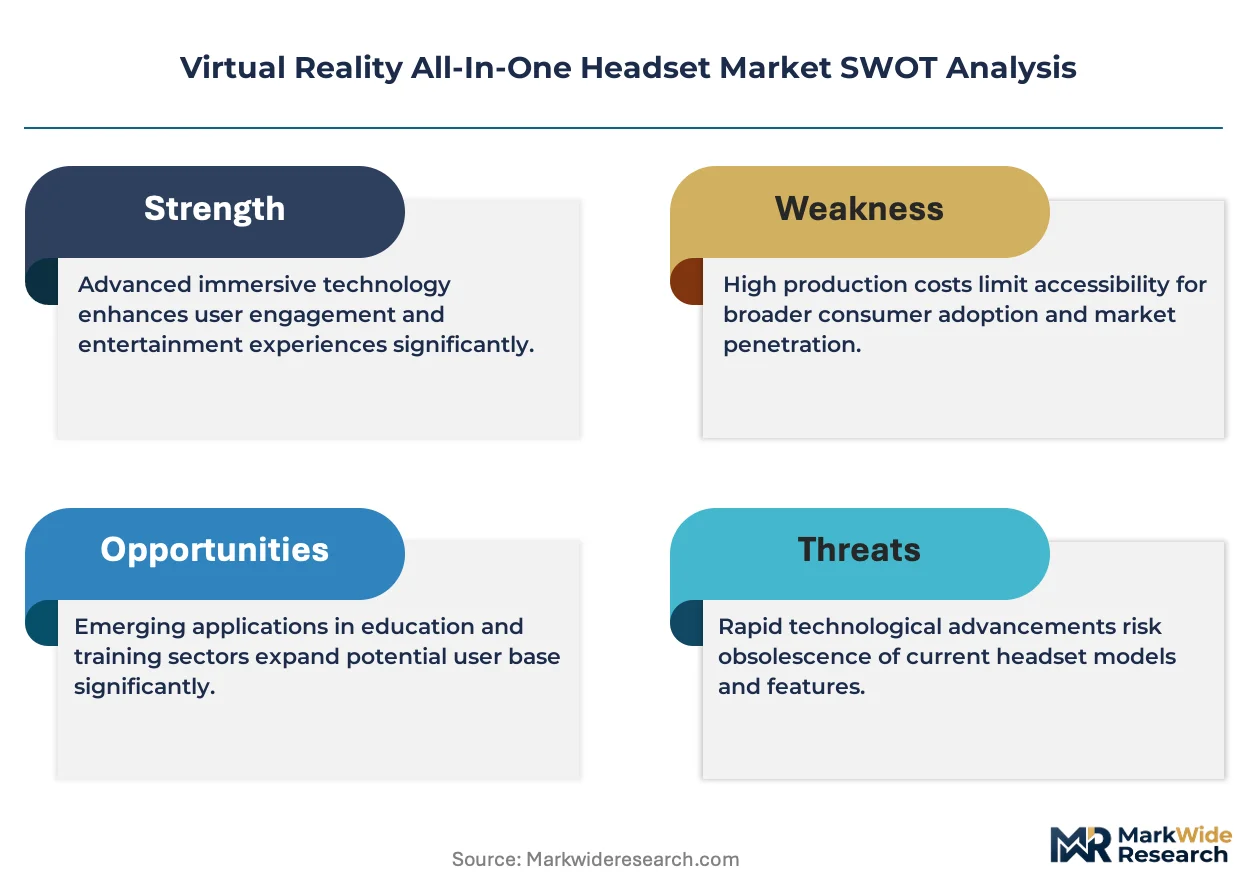
Enterprise buyer consolidation through systems integrators concentrates negotiating leverage, fragmenting vendor pricing power across hardware manufacturers. This buyer-power shift rewards ecosystem-integrated platform holders while squeezing component-specialist margins.
For Market Incumbents: Harden firmware architectures against EU AI Act biometric inference rules by implementing on-device eye-tracking processing. Deepen backward integration into gallium nitride power management to offset Taiwanese foundry concentration. Secure CE-MDR certification pipelines early to preempt 18-month conformity delays for therapeutic models.
For New Entrants and Emerging Players: Establish a beachhead in Indian education procurement by leveraging PLI scheme subsidies for final-assembly relocation from coastal China. Target cost-sensitive district rollouts where smartphone VR substitution has created hardware upgrade gaps. Deploy government tender participation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Optical-engine specialists with precision lens alignment capabilities represent the most defensible acquisition archetype as pancake optics maturation compresses SKU variance. Long-term viability hinges on content ecosystem lock-in or manufacturing scale advantages rather than hardware differentiation alone. Watch FDA digital therapeutics reimbursement pathway expansion as the inflection signal for therapy segment margin pools.
| Strategic Initiative | Industry Significance |
|---|---|
| On-Device Biometric Processing Architecture | EU AI Act compliance forces firmware redesigns that raise European market entry costs. |
| Pancake Optics Manufacturing Scale-Up | German healthcare providers now mandate thin optical stacks for patient comfort protocols. |
| Asset-Light Fleet Subscription Launch | United States enterprise buyers demand month-to-month SaaS attachments over perpetual licenses. |
| CE-MDR Certification Pathway Investment | Eighteen-month conformity timelines delay biometric-enabled therapeutic model revenue recognition. |
| Indian PLI Scheme Manufacturing Relocation | Karnataka and Tamil Nadu facilities capture government education tender participation advantages. |
Research Methodology
A spread of perspectives from VR hardware engineering leads, enterprise L&D procurement officers, rehabilitation clinic technology directors, and optical component sourcing managers converged on the working assumptions. Primary interview insights combined with secondary validation against SEC filings, customs trade databases, FDA 510(k) submissions, and hospital procurement records. Bottom-up unit shipment estimates and top-down market sizing triangulated across the analysis window.
Demand-supply balance modeling tracked standalone, tethered, mobile, and augmented reality form factors against gaming, education, training, and therapy applications. Deployment scale, content attach rates, and regional regulatory clusters shaped segmentation dimensions. CAGRs derived from fitted growth curves incorporating defense simulation budget trajectories, FDA digital therapeutics pathway maturation, and EU AI Act implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in freight rate indices, semiconductor capital expenditure cycles, or clinical reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions about foveated rendering adoption curves and biometric sensor fusion roadmaps. Cross-checking against hyperscaler VR headset procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market