
 AR in Education Market | 2026-2036
AR in Education Market Size, Share, and Industry Trends Forecast 2026-2036
AR in Education Market Analysis
Fragmentation across K-12 buyers and vocational training centers is realigning vendor go-to-market strategies toward district-level procurement frameworks. Microsoft Corporation leverages its HoloLens ecosystem and institutional licensing infrastructure to anchor enterprise-grade deployments across higher education laboratories. EON Reality, Inc. specializes in turnkey curriculum platforms that compete directly with legacy learning management systems. Google LLC extends its Chromebook dominance into AR-compatible classroom hardware through integrated Web AR content delivery.
Augmented reality in education overlays digital information onto physical environments through spatial computing interfaces, typically requiring sub-20-millisecond motion-to-photon latency to prevent user disorientation during prolonged instructional sessions. The technology serves to transform static curriculum into interactive three-dimensional experiences that improve knowledge retention in STEM and medical training disciplines. Mobile AR currently leads volume deployment due to minimal hardware barriers, while head-mounted displays command premium pricing in surgical and engineering simulation programs where hand-free operation proves essential. Simulation software within the content type dimension captures disproportionate margin pools as institutions prioritize experiential learning over digitized textbooks.
FCC guidelines in the United States govern wireless spectrum allocation for classroom AR devices, while the EU AI Act imposes risk-classification obligations on algorithmic tutoring systems deployed to European students. GDPR compliance further constrains how biometric gaze-tracking data from head-mounted displays may be stored or processed by educational content providers. Stakeholders must monitor evolving interoperability standards between hardware ecosystems and assess whether centralized procurement mandates from national education ministries will favor open-content formats over proprietary platforms.
Market Dynamics
District-level procurement frameworks are consolidating purchasing power across K-12 systems, compressing vendor margins while favoring platform providers with established institutional licensing infrastructure. This structural concentration is accelerating competitive exits among point-solution developers.
Growth Catalysts
- EU AI Act classification requirements:Risk-tiered algorithmic standards are creating procurement clarity for European educational institutions, reducing vendor qualification friction.
- STEM curriculum mandates:State-level science standards in Texas and California are embedding experiential learning requirements that favor spatial computing deployments.
- Sub-20-millisecond motion-to-photon latency:Hardware performance thresholds now prevent user disorientation, enabling prolonged instructional sessions without physiological barriers.
Market Restraints
- Head-mounted display cost structures:Premium surgical and engineering simulation hardware remains inaccessible to mass K-12 deployment, capping volume expansion.
- Biometric data storage constraints:GDPR compliance requirements for gaze-tracking information limit cloud-based personalization features in European deployments.
- Wireless spectrum allocation:FCC classroom device guidelines create bandwidth contention during concurrent multi-user AR sessions.
Strategic Opportunities
- Vocational training center penetration:Turnkey curriculum platforms are displacing legacy learning management systems in technical institutes across Germany and South Korea.
- Web AR content delivery:Browser-based spatial computing eliminates app-store friction, opening Chromebook-dominant classrooms to immersive experiences.
- Medical simulation premium segments:Hand-free operation requirements in surgical training programs sustain pricing power unavailable in consumer-facing education.
Industry Challenges
- Interoperability standardization delays:Fragmented hardware ecosystems force content developers to maintain multiple rendering pipelines, inflating production costs.
- Instructional design capability gaps:Curriculum developers lack spatial computing expertise, creating bottlenecks in pedagogically effective three-dimensional content creation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR in Education Market |
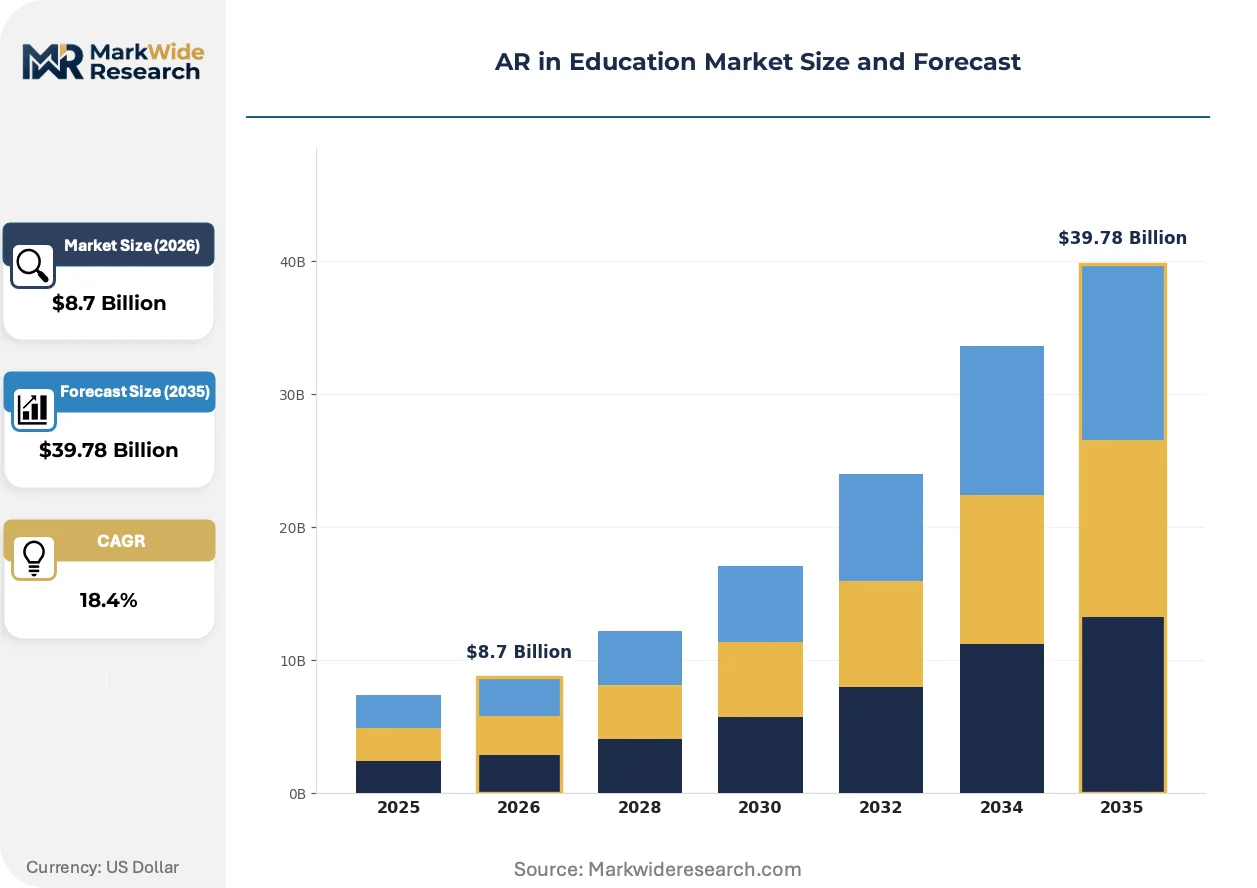
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
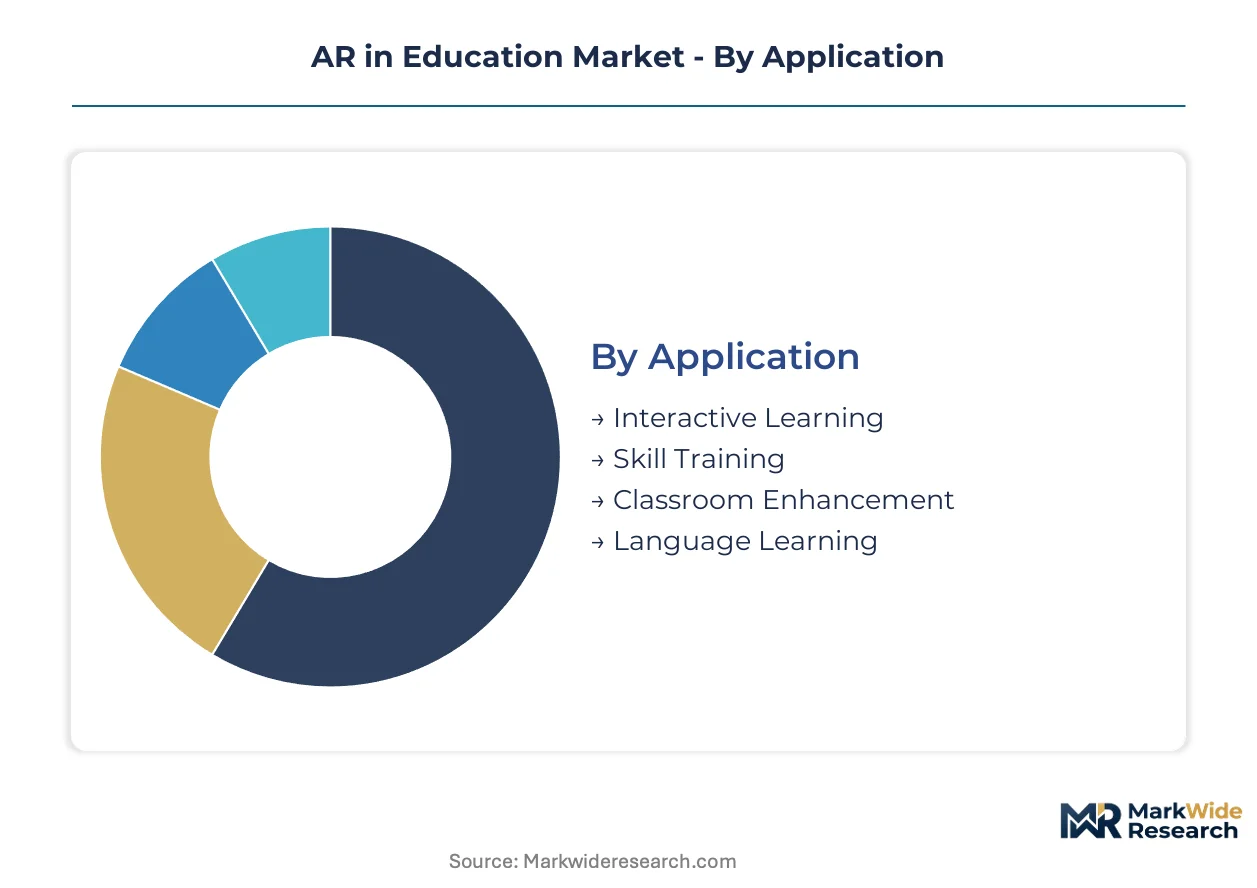
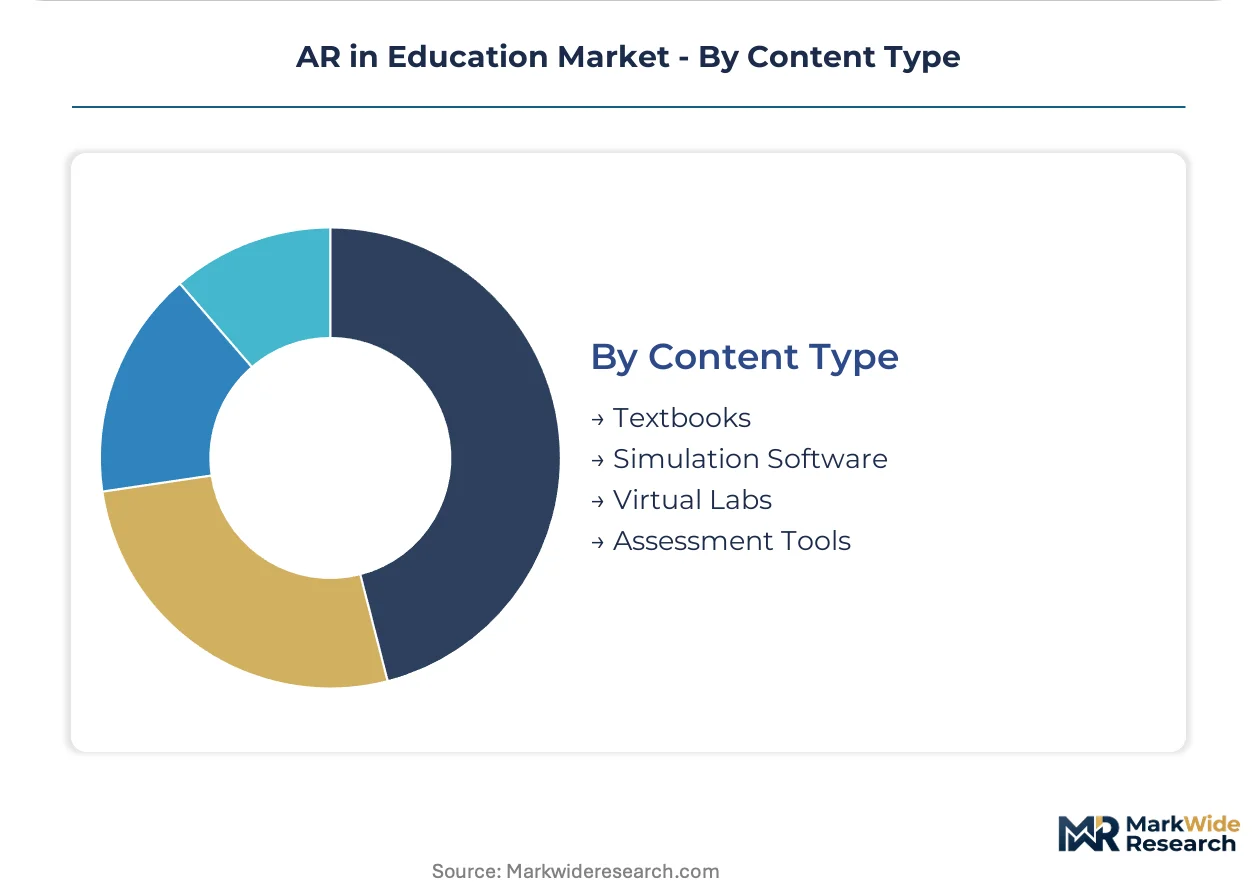
| Segmentation | Application: Interactive Learning, Skill Training, Classroom Enhancement, Language Learning Technology: Mobile AR, Head-Mounted Displays, Web AR, Marker-Based AR End User: K-12 Schools, Higher Education Institutions, Vocational Training Centers, Educational Content Providers Content Type: Textbooks, Simulation Software, Virtual Labs, Assessment Tools |
| Companies Covered | Microsoft Corporation, Meta Platforms, Inc., Google LLC, Sony Group Corporation, HTC Corporation, EON Reality, Inc., zSpace, Inc., Lenovo Group Ltd., Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR in Education Market Emerging Trajectories
Spatial computing architectures are fragmenting control over educational content creation, distributing authoring capabilities from centralized studios toward individual instructors and subject-matter experts. This democratization is compressing development cycles and diversifying pedagogical approaches.
Mobile AR rendering engines are decentralizing immersive content production by enabling browser-based authoring tools that run on existing institutional hardware. K-12 instructors in California and Texas public systems are adopting these platforms faster than centralized IT procurement cycles permit. The shift is compressing vendor control over content distribution channels.
The EU AI Act risk-classification framework is imposing algorithmic transparency obligations on adaptive tutoring systems deployed to European students. Educational software vendors must now document training data provenance and decision logic for high-risk applications. Medical training simulations face the most stringent compliance timelines, with German and French regulators leading enforcement.
District-level consortium purchasing is consolidating buyer power across American public school systems, displacing individual school autonomy in technology acquisition. Volume aggregation is favoring platform providers with multi-year institutional contracts over point-solution vendors. Texas Education Agency procurement frameworks exemplify this concentration, with California following through regional cooperative agreements.
AR in Education Market Segmentation
Educational procurement frameworks prioritize interoperability and total cost of ownership over isolated feature performance. Segmentation reveals where vendor margin pools concentrate and which deployment modes scale across institutional budgets.
Application:
Budget cycles and curriculum mandates determine which use cases secure district-level funding versus pilot-program status.
- Interactive Learning:Spatial overlays transform static STEM materials into manipulable three-dimensional models. California and Texas public systems embed these tools in state science standards, driving volume procurement through centralized frameworks.
- Skill Training:Hands-free simulations in surgical and technical disciplines require sub-20-millisecond latency thresholds. German vocational institutes and South Korean technical colleges prioritize these deployments for workforce credentialing programs.
- Classroom Enhancement:Supplementary AR layers augment traditional instruction without curriculum replacement. Browser-based delivery reduces IT deployment friction in under-resourced districts.
- Language Learning:Immersive conversation simulations overlay contextual cues onto physical environments. Mobile-first deployment suits individual practice outside institutional settings.
Interactive Learning leads on scale; Skill Training leads on momentum.
Technology:
Hardware cost tiers and institutional refresh cycles segment adoption velocity across education budgets.
- Mobile AR:Smartphone and tablet-based rendering eliminates capital expenditure barriers. K-12 districts in Texas deploy these solutions at district scale through existing Chromebook infrastructure.
- Head-Mounted Displays:Premium surgical and engineering simulations demand hand-free operation. Medical training programs in France and Germany sustain pricing power unavailable in mass education markets.
- Web AR:Browser-based spatial computing bypasses app-store gatekeeping and IT approval workflows. California public school systems accelerate deployment through this friction reduction.
- Marker-Based AR:Printed trigger images anchor digital content to physical textbooks. Legacy publishers integrate these features to extend print asset lifecycles.
Mobile AR dominates installed base; Web AR climbs the fastest on new deployment velocity.
End User:
Procurement centralization versus institutional autonomy shapes vendor route-to-market economics.
- K-12 Schools:District-level purchasing aggregates thousands of individual schools into single contract vehicles. Texas Education Agency frameworks exemplify this concentration, compressing vendor margins while favoring platform-scale providers.
- Higher Education Institutions:Laboratory and research deployments command premium pricing for enterprise-grade hardware. University procurement offices maintain independent evaluation criteria distinct from K-12 standardization.
- Vocational Training Centers:Workforce-aligned credentials drive experiential learning investment. German technical institutes and South Korean polytechnics displace legacy learning management systems with turnkey immersive platforms.
- Educational Content Providers:Curriculum developers and publishers license AR capabilities to extend distribution reach. GDPR compliance requirements constrain biometric data handling for European student populations.
K-12 Schools anchor volume demand; Vocational Training Centers gain share fastest on policy tailwinds.
Content Type:
Margin concentration follows pedagogical differentiation and replacement risk for existing instructional materials.
- Simulation Software:Experiential learning modules capture disproportionate margin pools as institutions prioritize competency demonstration over content consumption. Medical and engineering disciplines sustain premium pricing through accreditation requirements.
- Virtual Labs:Remote laboratory access reduces capital infrastructure requirements for resource-constrained institutions. Higher education systems deploy these tools to expand enrollment capacity without physical facility expansion.
- Textbooks:Digitized print materials with AR overlays extend legacy publishing revenue streams. District procurement cycles treat these as incremental upgrades rather than transformational investments.
- Assessment Tools:Spatial evaluation formats measure procedural competency through performance capture. EU AI Act risk-classification requirements impose algorithmic transparency obligations on adaptive testing systems.
Simulation Software leads on margin capture; Virtual Labs expand most quickly on infrastructure substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement frameworks favor platform-scale providers while German technical institutes prioritize workforce-aligned simulation systems, revealing divergent institutional pathways for spatial computing adoption.
United States
District-level consortium purchasing across Texas and California aggregates thousands of schools into centralized contract vehicles. FCC guidelines govern wireless spectrum allocation for concurrent classroom AR sessions. The Texas Education Agency procurement framework exemplifies this concentration, compressing vendor margins while favoring established institutional licensing infrastructure.
Germany
Vocational training centers drive experiential learning investment for workforce credentialing programs. The EU AI Act imposes risk-classification obligations on algorithmic tutoring systems deployed to German students. Technical institutes in Bavaria and North Rhine-Westphalia displace legacy learning management systems with turnkey immersive platforms.
South Korea
Technical colleges prioritize hands-free simulations with sub-20-millisecond latency thresholds for engineering disciplines. The country's national education ministry mandates interoperability standards for classroom hardware procurement. Polytechnics in the Seoul Capital Area and Busan-Ulsan region accelerate deployment of medical training simulations through centralized budget allocation.
France
Higher education laboratories command premium pricing for enterprise-grade head-mounted displays in surgical training programs. GDPR compliance requirements constrain biometric gaze-tracking data storage for student populations. Medical schools in Île-de-France and university hospitals in Auvergne-Rhône-Alpes sustain pricing power unavailable in mass education markets.
India
State-level science standards in Maharashtra and Karnataka embed experiential learning requirements favoring mobile AR deployment. The country's central education regulator establishes content classification guidelines for digital curriculum tools. Engineering institutes in Bangalore and Hyderabad expand Chromebook-compatible Web AR content delivery to reduce IT deployment friction.
AR in Education Market Vendor Landscape
United States technology conglomerates anchor one tier; specialized curriculum developers and hardware fabricators from East Asia hold differentiated positions in premium simulation segments. The vendor base concentrates around platform providers with multi-year institutional contracts, displacing point-solution developers through district-level procurement consolidation. Three strategic archetypes dominate: enterprise technology ecosystems, turnkey curriculum platforms, and precision hardware specialists. Competitive moves center on institutional licensing infrastructure expansion and browser-based content delivery friction reduction.
Among platform-scale providers, Microsoft Corporation exemplifies the enterprise technology archetype through HoloLens ecosystem integration and institutional licensing infrastructure. EON Reality, Inc. occupies a position within the turnkey curriculum tier, competing directly with legacy learning management systems through spatial computing specialization. Google LLC anchors the browser-based delivery vector, extending Chromebook dominance into AR-compatible classroom hardware through integrated Web AR content platforms.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms, Inc. |
| Google LLC |
| Sony Group Corporation |
| HTC Corporation |
| EON Reality, Inc. |
| zSpace, Inc. |
| Lenovo Group Ltd. |
| Panasonic Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Optical waveguide fabrication costs cascade through head-mounted display tiers, compressing margin structures at the economy end while premium surgical simulators sustain pricing power through German and French accreditation requirements.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for microdisplay components, enabling three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on latency certification grade and institutional volume scale. Cost compression in K-12 mobile AR deployments is intensifying because district-level procurement aggregates thousands of schools into single contract vehicles. Vocational training centers in Germany exhibit lowest price sensitivity due to workforce credentialing mandates.
Supply Chain Analysis
Dual-sourcing requirements from Texas Education Agency and California regional cooperatives mandate multi-supplier qualification for classroom hardware procurement. Component manufacturing concentrates in Taiwan, South Korea, and China. Raw material dependencies span rare-earth phosphors for microLEDs, precision optics substrates, and lithium-polymer cells. Single-source vulnerability around Taiwanese semiconductor foundries threatens display controller availability. Distribution runs through institutional licensing infrastructure rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where Web AR delivery eliminates app-store gatekeeping costs and district-level procurement favors platform-scale providers with captive content libraries.
For Market Incumbents: Extend institutional licensing infrastructure into vocational training centers before turnkey curriculum platforms displace legacy learning management systems. Deepen backward integration into optical component supply to defend against emerging hardware specialists from East Asia. Prioritize EU AI Act compliance documentation as procurement qualification leverage across German technical institutes. For New Entrants and Emerging Players: Launch via browser-based Web AR distribution to bypass IT approval workflows in California and Texas public school systems. Target under-resourced districts with Chromebook-compatible content where centralized procurement cycles lag instructor adoption velocity. Penetrate language learning segments through mobile-first individual practice models outside institutional procurement frameworks. For Investors and Strategic Acquirers: Consolidation pressure builds where district-level purchasing aggregates thousands of schools into single contract vehicles, compressing point-solution vendor margins toward exit thresholds. Long-term viability favors platform providers with multi-year institutional contracts and proprietary content libraries. Acquisition target archetype: specialized simulation developers with medical accreditation relationships. Signal to watch: interoperability standardization mandates from national education ministries favoring open-content formats over proprietary platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft HoloLens ecosystem anchors enterprise-grade laboratory deployments through institutional licensing infrastructure. |
| Geographic Expansion | EON Reality penetrates German vocational institutes with turnkey curriculum platforms displacing legacy learning management systems. |
| Product Launch | Google Web AR content delivery extends Chromebook dominance into AR-compatible classroom hardware across California public systems. |
| Strategic Partnership | Content developers align with Texas Education Agency procurement frameworks to secure multi-year district-level contracts. |
| Acquisition of Specialist Firm | Precision hardware specialists with sub-20-millisecond latency certification capture premium pricing in surgical simulation segments. |
Methodological Framework
Bottom-up K-12 and higher education institution modeling reconciled against top-down hardware shipment and content licensing tracking forms the analytical core. Primary interviews with district technology officers, curriculum directors at vocational training centers, university laboratory managers, and educational content developers combined with secondary validation from FCC spectrum allocation filings, EU AI Act regulatory documentation, SEC 10-K disclosures from platform providers, and state-level procurement databases. Triangulation across these sources anchors volume estimates.
Input-output matrices map hardware cost structures through content development pipelines across the projection horizon. Segmentation dimensions modeled include application type, technology tier, end-user institution category, and content format. CAGRs derive from enrollment growth projections, curriculum mandate adoption curves, and hardware refresh cycle analysis. Specific forecast inputs include district-level procurement cycle timing and EU AI Act compliance timeline enforcement.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or FCC spectrum reallocation decisions. Deviation in interoperability standardization adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality in Therapy Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market