
 Breast Localization System Market | 2026-2036
Breast Localization System Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Localization System Market Outlook
A widening capital-intensity gap between integrated imaging-device manufacturers and standalone localization specialists is redrawing competitive boundaries in breast localization. Hologic leverages its mammography-installed base to bundle localization systems with imaging hardware, capturing hospital procurement budgets. Merit Medical Systems anchors its position through dedicated interventional oncology distribution, sustaining pull-through from breast biopsy into localization. Sirius Medical competes on compact magnetic seed platforms, differentiating via outpatient surgical center compatibility.
Breast localization systems are preoperative guidance devices that mark non-palpable breast lesions using implanted or surface-applied markers, with magnetic seed variants containing iron oxide cores detectable by handheld probes at sub-millimeter resolution. Their commercial purpose is to replace wire localization with same-day implantation, reducing scheduling complexity and patient discomfort while improving surgical margin accuracy. Wire localization still occupies the largest installed base among product type segments, though magnetic seed localization is capturing fastest-growing status as hospitals phase out radioactive isotope dependency. Ultrasound guidance technology dominates procedure volume due to real-time visualization and lower capital requirements, while MRI guidance leads margin pools by serving high-risk patient screening protocols.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern device safety and electromagnetic compatibility for breast localization systems, with the EU AI Act beginning to shape algorithm-enabled guidance software. Japan's PMDA reviews localization devices under pharmaceutical-affiliated medical equipment frameworks, creating distinct documentation requirements for magnetic materials. Stakeholders must monitor evolving reimbursement codes for same-day seed localization versus wire procedures across Medicare, NHS England, and Japan's MHLW fee schedules.
Market Dynamics
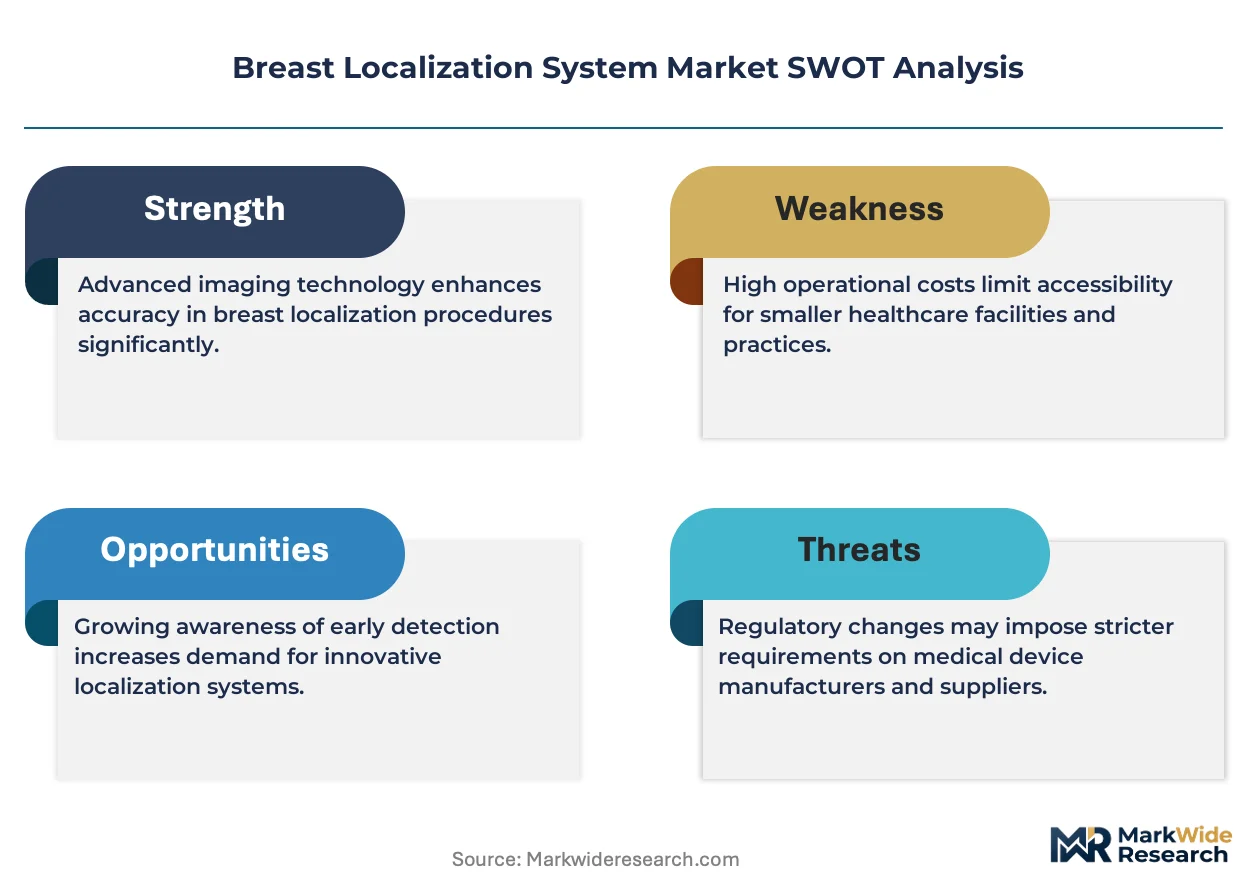
Hospitals are phasing out radioactive wire localization in favor of magnetic seed systems, driven by FDA tightening of isotope handling protocols and same-day scheduling economics. This technology substitution is compressing capital planning cycles and redrawing vendor procurement criteria across surgical oncology departments.
Growth Catalysts
- EU MDR electromagnetic compatibility mandates:CE marking under revised medical device regulations is accelerating hospital replacement of legacy wire systems with validated magnetic seed platforms.
- Outpatient surgical centers:Compact handheld probe designs are enabling same-day implantation-to-resection workflows outside traditional hospital settings.
- Iron oxide core detection resolution:Sub-millimeter spatial accuracy from improved magnetic materials is reducing positive margin rates and re-excision procedures.
Market Restraints
- Neodymium supply concentration:Rare earth magnet sourcing from limited Asian refiners creates input cost volatility for seed manufacturers.
- MRI compatibility validation:Electromagnetic interference testing requirements under FDA 510(k) pathways extend clearance timelines for multi-modal imaging environments.
- Wire localization installed base:Sunk capital in radioactive isotope infrastructure and radiologist training creates switching friction at budget-constrained institutions.
Strategic Opportunities
- Japan's MHLW fee schedule expansion:Reimbursement code development for same-day seed localization creates payment parity opportunity versus wire procedures.
- Ultrasound-MRI convergence:Dual-modality guidance systems integrating real-time visualization with high-risk screening protocols open premium tier positioning.
- Interventional radiology suites:Dedicated breast biopsy-to-localization workflow units in community hospitals represent underserved channel expansion.
Industry Challenges
- PMDA pharmaceutical-affiliated documentation:Japan's magnetic material review framework demands distinct clinical evidence packages, fragmenting regulatory strategy.
- Electromagnetic probe calibration standardization:Absence of unified IEC performance benchmarks complicates multi-vendor hospital system integration.
- Surgical oncologist retraining:Handheld probe navigation skills require dedicated simulation curriculum, slowing adoption at teaching hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Localization System Market |
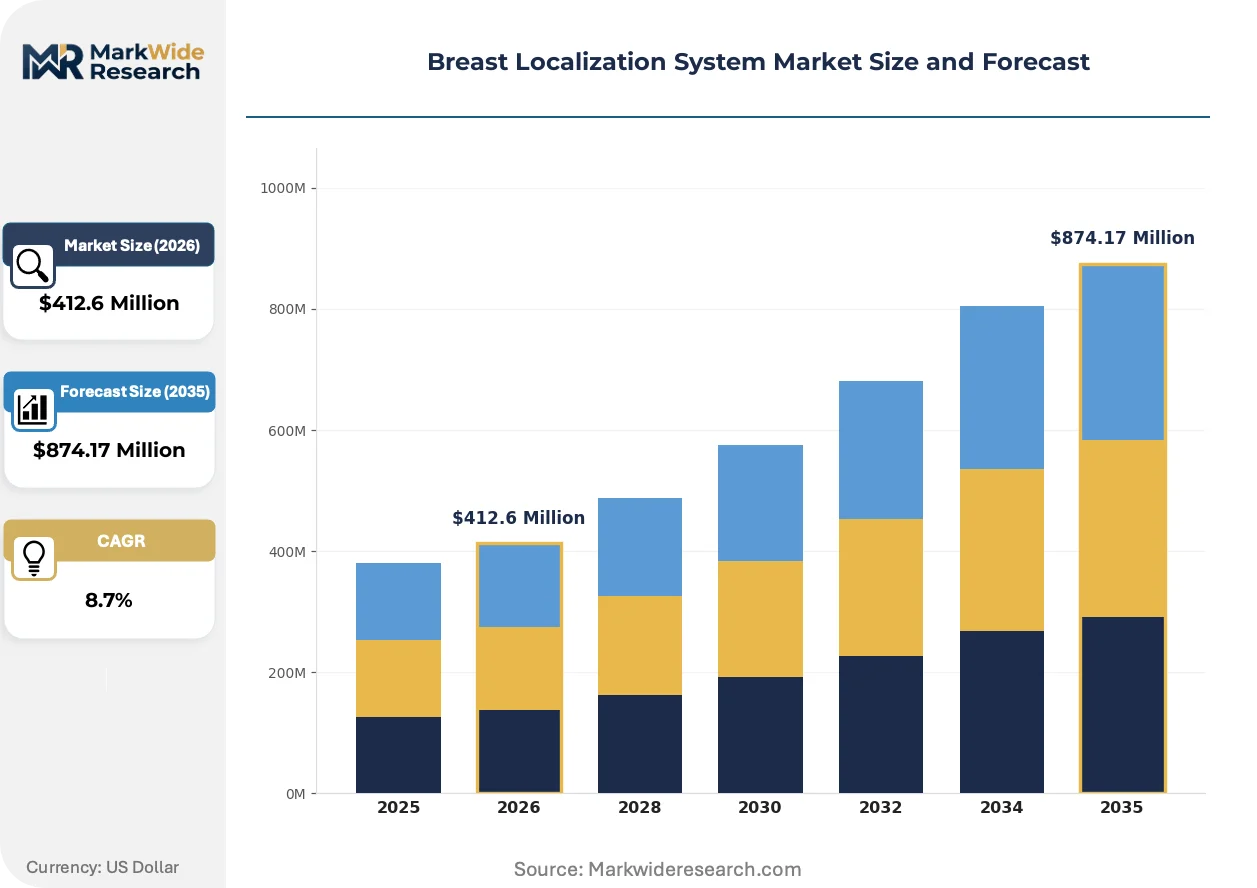
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Localization, Radioactive Seed Localization, Magnetic Seed Localization, Ultrasonic Localization End User: Hospitals, Clinics, Diagnostic Centers, Outpatient Surgical Centers Technology: Ultrasound Guidance, MRI Guidance, X-ray Guidance, Electromagnetic Guidance Delivery Mode: Invasive Procedures, Non-invasive Procedures, Laparoscopic Procedures, Robotic-assisted Procedures |
| Companies Covered | Hologic, Merit Medical Systems, BD, Argon Medical Devices, Cook Medical, STERLAB, Theragenics Corporation, Sirius Medical, SOMATEX Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Localization System Market Strategic Shifts
Magnetic seed localization is actively fragmenting procedural workflows across hospital systems, with technology vendors racing to capture the transition from wire-based protocols. Three distinct movements are reshaping competitive positioning and buyer expectations.
Magnetic seed platforms containing iron oxide cores detectable by handheld probes are bifurcating the market between premium integrated systems and compact standalone units. Academic medical centers are adopting full imaging-probe bundles for complex cases, while ambulatory surgery centers prioritize portable single-probe configurations for straightforward excisions. This split is compressing mid-tier product viability and forcing vendors to choose specialization lanes.
EU AI Act algorithm governance is beginning to shape electromagnetic guidance software development, with automated lesion mapping tools facing new transparency and validation requirements. Device manufacturers must document training data provenance and performance drift monitoring, adding compliance layers to firmware updates. MRI-guided localization systems with embedded AI assistance are most exposed, particularly in German and French hospital procurement evaluations.
Hospital purchasing committees are unbundling after-sales service contracts from hardware acquisition, treating probe calibration and software maintenance as separate line items. This disaggregation favors third-party service specialists and pressures original equipment margins. The pattern is most pronounced in United States integrated delivery networks, where procurement centralization is stripping bundled service premiums from localization system vendors.
Breast Localization System Market Segmentation
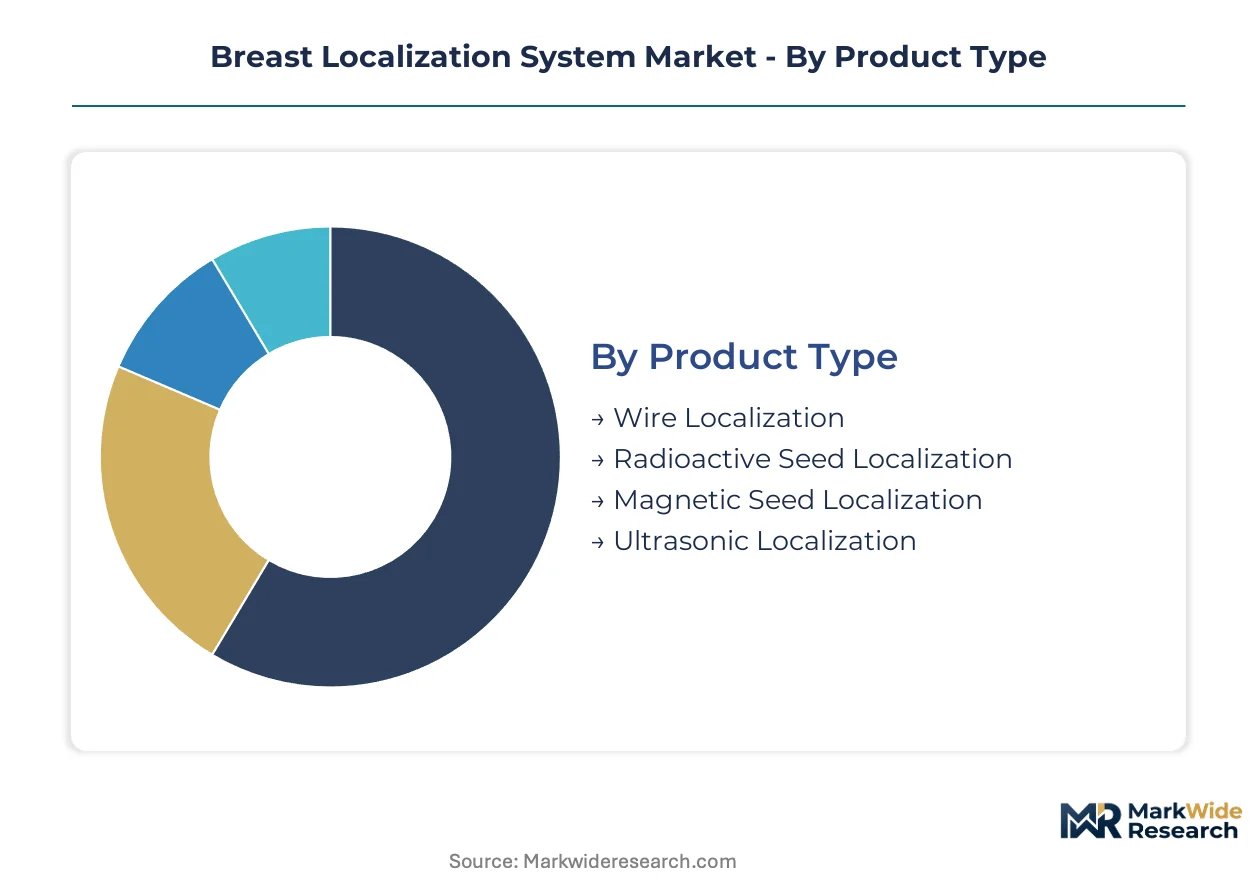
Segmentation in breast localization systems determines procurement pathways and margin capture. Technology choices drive reimbursement rates, while end-user settings dictate capital intensity and service contract structures.
Product Type:
Magnetic seed platforms command premium pricing through iron oxide core detectability, while wire localization retains volume dominance from radioactive isotope infrastructure.
- Magnetic Seed Localization:Iron oxide cores enable sub-millimeter detection resolution via handheld probes. Academic medical centers in the United States and Germany are consolidating procurement around these platforms to eliminate same-day scheduling constraints and isotope handling protocols.
- Wire Localization:Radioactive wire systems maintain the largest installed base through sunk capital in gamma probe infrastructure and radiologist training programs. Budget-constrained community hospitals in Japan continue standardizing on wire protocols despite magnetic seed availability.
- Radioactive Seed Localization:Iodine-125 and palladium-103 seeds face tightening FDA isotope handling regulations.
- Ultrasonic Localization:Surface-applied acoustic reflectors serve niche outpatient applications with minimal capital requirements.
Wire localization holds installed capacity. Magnetic seed localization is rotating up the share rankings.
End User:
Hospital procurement committees dominate capital allocation, though outpatient migration is fragmenting purchasing authority across settings.
- Hospitals:Integrated delivery networks bundle localization systems with mammography hardware through multi-year capital planning cycles. Surgical oncology departments in the United States drive replacement demand as they phase out radioactive wire protocols under tightening EPA isotope disposal mandates.
- Outpatient Surgical Centers:Compact single-probe configurations enable same-day implantation-to-resection workflows outside traditional hospital infrastructure. German ambulatory surgery centers are expanding magnetic seed adoption fastest due to EU MDR electromagnetic compatibility validation requirements.
- Clinics:Community breast imaging centers concentrate on ultrasound-guided wire procedures for cost containment.
- Diagnostic Centers:Standalone imaging facilities refer localization procedures to affiliated hospitals.
Hospitals retain capital budget control. Outpatient surgical centers are climbing the fastest as procurement decentralizes.
Technology:
Ultrasound guidance captures procedure volume through lower capital thresholds, while MRI guidance concentrates margin pools in high-risk screening protocols.
- Ultrasound Guidance:Real-time visualization with portable probe systems dominates community hospital and clinic settings. Japanese diagnostic centers standardize on ultrasound-guided wire localization for its minimal training requirements and immediate availability.
- MRI Guidance:Multi-parametric imaging integration serves high-risk patient screening and dense breast tissue protocols. German university hospitals are consolidating procurement around MRI-compatible magnetic seed systems to support neoadjuvant therapy monitoring workflows.
- X-ray Guidance:Stereotactic mammography platforms retain installed base for calcification targeting.
- Electromagnetic Guidance:Handheld probe detection systems are gaining procedural share in outpatient settings.
Ultrasound guidance maintains procedure volume leadership. MRI guidance is ascending the value chain fastest.
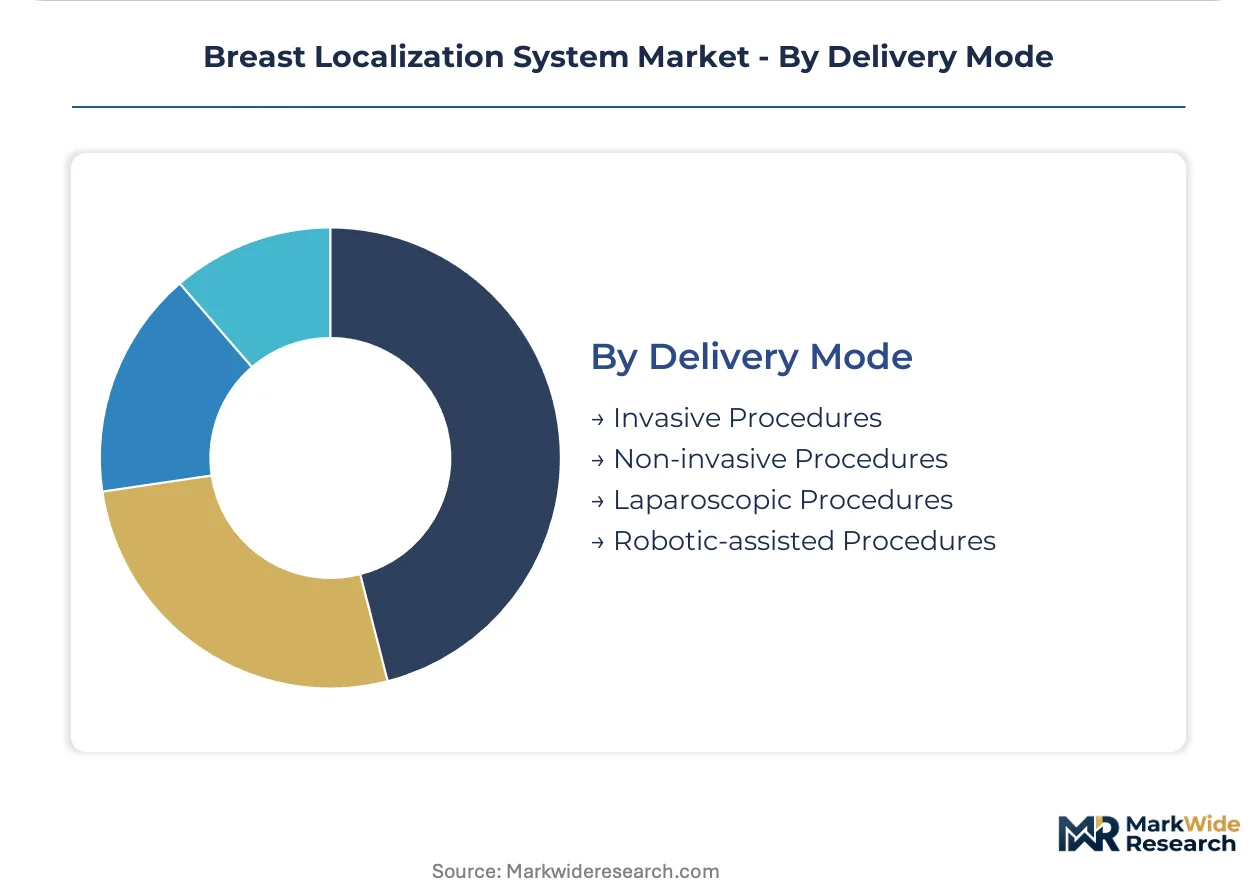
Delivery Mode:
Invasive implantation dominates lesion marking, though minimally invasive alternatives are capturing share in specific patient populations.
- Invasive Procedures:Percutaneous seed and wire implantation under image guidance constitutes the standard workflow. United States hospitals are consolidating procurement around same-day invasive magnetic seed protocols to replace two-day wire localization schedules.
- Non-invasive Procedures:Surface marker placement and electromagnetic surface coils serve select superficial lesions. Japanese outpatient clinics are piloting non-invasive electromagnetic localization for patients contraindicated for percutaneous implantation.
- Laparoscopic Procedures:Minimally invasive access routes serve concurrent diagnostic and therapeutic interventions.
- Robotic-assisted Procedures:Automated needle guidance systems are entering validation for complex lesion geometries.
Invasive procedures anchor clinical workflow. Non-invasive alternatives are expanding most quickly in specialized patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy magnetic seed systems for same-day scheduling efficiency, while Japanese institutions retain wire localization due to distinct reimbursement pacing and radiologist training investments.
United States
Integrated delivery networks in Texas and California are consolidating procurement around magnetic seed platforms to eliminate radioactive isotope handling under tightening EPA disposal mandates. FDA 510(k) clearance pathways for electromagnetic guidance systems are accelerating hospital replacement cycles. The Greater Boston surgical oncology cluster is pioneering outpatient migration of localization procedures to ambulatory surgery centers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are standardizing on MRI-compatible magnetic seed systems for neoadjuvant therapy monitoring workflows. EU MDR electromagnetic compatibility validation requirements are compressing vendor qualification timelines. The Munich medical technology corridor is concentrating procurement authority for dual-modality guidance systems serving dense breast tissue protocols.
Japan
Diagnostic centers in Tokyo and Osaka maintain wire localization dominance due to MHLW fee schedule structures that lag magnetic seed reimbursement parity. PMDA pharmaceutical-affiliated documentation requirements for magnetic materials are fragmenting regulatory strategy for foreign device manufacturers. The Kansai region's radiologist training infrastructure creates switching friction at budget-constrained community hospitals.
United Kingdom
NHS England procurement frameworks are driving magnetic seed adoption in London and Manchester to reduce two-day wire localization scheduling backlogs. MHRA post-Brexit device regulations are aligning with EU MDR electromagnetic compatibility standards. The Cambridge-Oxford medical research triangle is validating automated lesion mapping tools under emerging EU AI Act governance requirements.
France
Paris and Lyon university hospitals are capturing premium positioning for MRI-guided localization systems serving high-risk patient screening protocols. ANSM national health product safety agency reviews are tightening electromagnetic interference testing requirements for multi-modal imaging environments. The Île-de-France region is consolidating interventional radiology suite investments to integrate biopsy-to-localization workflows.
Breast Localization System Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with mammography-hardware bundlers commanding hospital capital budgets and interventional oncology distributors sustaining pull-through from adjacent biopsy markets. The competitive terrain splits between imaging-device integrators leveraging installed base relationships and compact-platform specialists targeting outpatient surgical center compatibility. Dominant moves include strategic bundling of localization systems with mammography hardware and dedicated distribution channel construction for interventional oncology workflows.
Within the integrated imaging tier, Hologic exemplifies mammography-installed base leverage through bundled hardware procurement, while Merit Medical Systems anchors interventional oncology distribution specialization. Sirius Medical occupies a position among compact magnetic seed platform specialists, differentiating via outpatient surgical center compatibility and same-day implantation-to-resection workflow design.
| Leading Market Players |
|---|
| Hologic |
| Merit Medical Systems |
| BD |
| Argon Medical Devices |
| Cook Medical |
| STERLAB |
| Theragenics Corporation |
| Sirius Medical |
| SOMATEX Medical Technologies |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for neodymium-iron-boron magnetic cores concentrate procurement leverage among three Asian refiners, translating directly into tiered pricing power for seed manufacturers and forcing hospital buyers into multi-year offtake commitments to secure supply allocation.
Pricing Analysis
Long-term offtake contracts dominate magnetic seed procurement, with United States integrated delivery networks locking three-year pricing bands to hedge neodymium cost volatility. Premium-mid-economy pricing differentiation separates MRI-compatible validated systems from standard ultrasound-guided configurations, with FDA 510(k) clearance tier commanding brand premiums. Cost compression in standard magnetic seed tiers is intensifying because outpatient surgical centers are consolidating procurement volume and stripping after-sales service bundles. Community hospitals in Japan exhibit highest price sensitivity due to MHLW fee schedule constraints, while German university hospitals show lowest sensitivity when purchasing dual-modality integrated systems.
Supply Chain Analysis
China and Japan anchor rare earth magnet refining for iron oxide cores, with South Korea supplying precision electromagnetic probe components. Seed assembly draws from Taiwanese semiconductor packaging expertise for probe miniaturization, while German sensor manufacturers provide calibration subsystems. Single-source vulnerability concentrates in neodymium oxide processing, where environmental licensing restrictions have consolidated refining capacity. Distribution runs through dedicated interventional oncology distributors in North America and direct hospital contracts in European Union markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks consolidating procurement across mammography and localization systems, fragmenting vendor pricing autonomy as hospitals unbundle hardware from service contracts.
For Market Incumbents: Consolidate imaging-hardware bundling relationships to defend against standalone magnetic seed specialists capturing outpatient surgical center volume. Deepen backward integration into magnetic material sourcing to offset neodymium price volatility, while accelerating FDA 510(k) clearance pipelines for MRI-compatible platforms to maintain premium tier positioning against compact-probe entrants. For New Entrants and Emerging Players: Anchor in Japanese outpatient clinics where MHLW reimbursement lag creates white-space opportunity for non-invasive electromagnetic surface coil alternatives. Target German ambulatory surgery centers seeking EU MDR-validated compact systems with same-day workflow certification. Pursue GPO contract penetration through interventional radiology suite channel partnerships rather than direct hospital capital committee engagement. For Investors and Strategic Acquirers: Long-term, this sits as a substitution-cycle play because radioactive wire localization installed base replacement will sustain demand across two equipment refresh cycles. Acquisition targets should display dual-modality imaging compatibility and established CE marking under EU MDR electromagnetic standards. Monitor PMDA magnetic material documentation pathway streamlining as inflection signal for Japan market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR electromagnetic compatibility validation accelerates hospital replacement cycles in Germany and France. |
| Hospital System Partnership | Integrated delivery network bundling with mammography hardware captures multi-year capital planning budgets. |
| Software Companion Development | AI-enabled lesion mapping tools face EU AI Act transparency requirements reshaping firmware architecture. |
| Reimbursement Strategy | MHLW fee schedule expansion for same-day seed localization creates payment parity opportunity in Japan. |
| FDA Submission | 510(k) clearance for MRI-compatible electromagnetic guidance opens premium positioning in academic medical centers. |
Study Parameters
Initial hypotheses were tested against primary input from surgical oncologists, hospital purchasing committee directors, interventional radiologists, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and Japanese MHLW fee schedule bulletins. Bottom-up demand modeling from hospital procedural volumes was triangulated with top-down market sizing from device manufacturer revenue disclosures.
Variance decomposition across the projection horizon isolates technology substitution effects, regulatory clearance timeline impacts, and reimbursement policy shifts as primary uncertainty sources. Segmentation dimensions modeled include product type, end-user setting, guidance technology, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and procedural volume elasticity to reimbursement parity events. Forecast inputs incorporated neodymium price trajectory assumptions and EPA isotope handling protocol enforcement intensity.
Material uncertainties — PMDA documentation pathway revisions, EU AI Act algorithm governance enforcement timing, and MHLW fee schedule update cadence — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these regulatory and supply chain drivers. Recalibration cycles align with material shifts in electromagnetic compatibility standards and rare earth magnet sourcing concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Embolization Plugs Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market