
 Global Pathological Microscopes Market | 2026-2036
Global Pathological Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pathological Microscopes Market Foresight
Pathologist workforce shortages in developed healthcare systems is collapsing diagnostic throughput capacity, forcing laboratories to invest in automated and digital microscopy platforms. Carl Zeiss AG leverages its optical engineering heritage to sustain premium positioning in research-grade instruments. Nikon Corporation anchors its competitive stance through deep vertical integration in lens manufacturing. Olympus Corporation dominates the Asia-Pacific installed base with service networks that extend equipment lifecycles.
Pathological microscopes are precision optical instruments engineered to resolve cellular and tissue structures at magnifications typically spanning 40x to 1000x, employing achromatic or apochromatic objective lenses with numerical apertures calibrated for histopathological examination. These systems serve primary commercial purpose in clinical diagnostics where pathologists render disease classifications from stained biopsy specimens. Digital microscopes command expanding share as laboratories pursue remote consultation capabilities and AI-assisted diagnostic workflows. Electron microscopes occupy specialized niches in ultrastructural pathology where subcellular detail determines rare disease identification. Optical microscopes remain the volume foundation across diagnostic centers and academic institutions where cost constraints limit technology migration.
FDA regulates digital pathology systems as Class II medical devices under 21 CFR requirements, while the EU MDR imposes conformity assessment burdens that extend market access timelines for fluorescence and confocal platforms. ISO 15189 accreditation standards for medical laboratories drive instrument validation protocols that shape procurement specifications. WHO pathology guidelines influence national health system equipment standards across emerging markets. Stakeholders must monitor evolving AI diagnostic algorithms that promise to redefine pathologist workflow economics and instrument feature requirements.
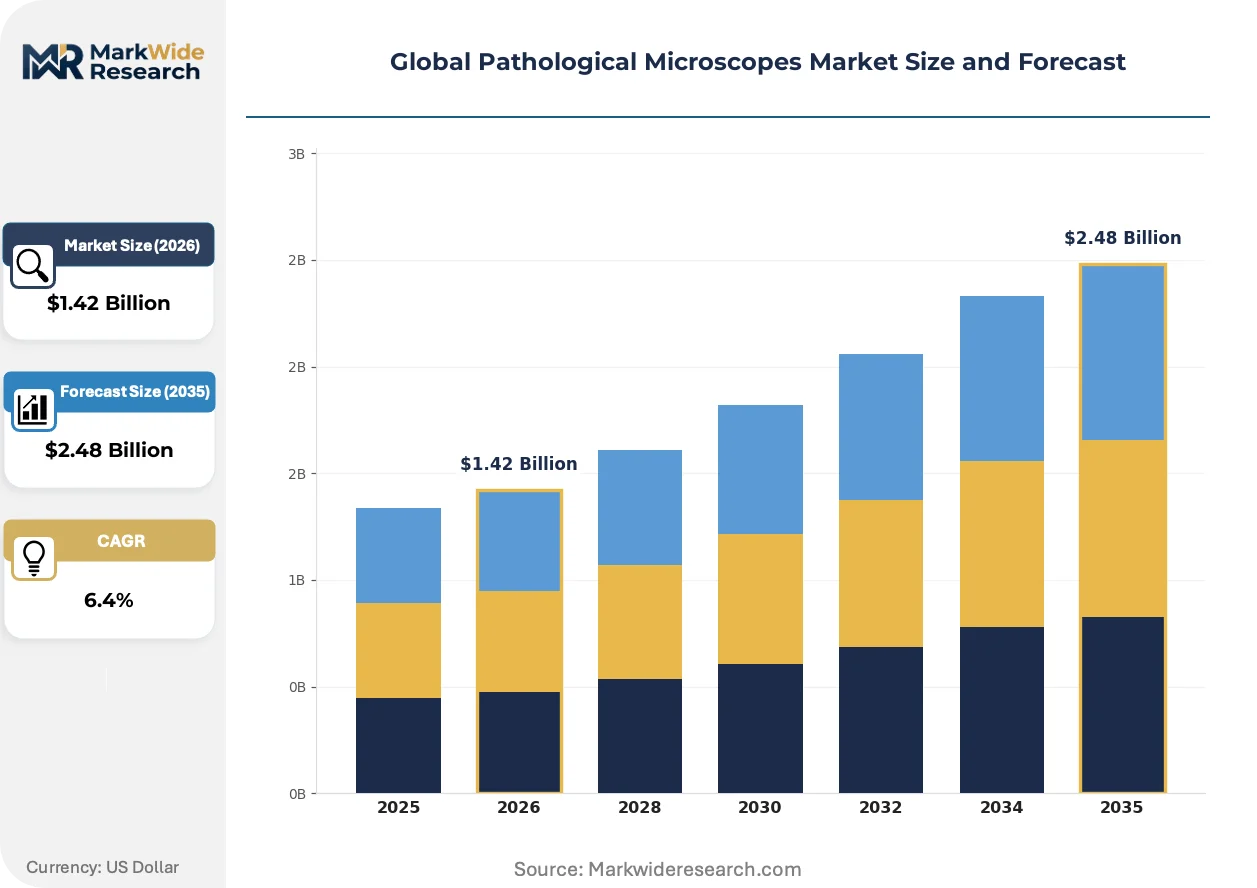
Market Dynamics
Digital pathology platform adoption is fragmenting traditional optical microscope procurement patterns as laboratories reallocate capital toward whole-slide imaging systems and AI-integrated workflows.
Growth Catalysts
- FDA 510(k) clearance pathway for digital pathology:De novo and 510(k) submissions for whole-slide imaging systems are compressing commercialization timelines, accelerating hospital laboratory adoption of remote diagnostic capabilities.
- Histopathology laboratory automation:Automated slide scanning and staining integration is reducing pathologist touch-time per specimen, expanding throughput capacity in high-volume cancer centers.
- Japan's super-aging society:Geriatric oncology screening expansion is driving instrument procurement in prefectural hospital networks, with METI industrial policy supporting domestic microscopy manufacturing.
Market Restraints
- Objective lens supply concentration:German and Japanese optical component specialists control achromatic and apochromatic objective manufacturing, creating procurement bottlenecks for mid-tier instrument assemblers.
- EU MDR conformity assessment burden:Extended notified body review timelines for fluorescence microscopy systems are delaying product launches and freezing R&D budgets for European manufacturers.
- Computational pathology substitution:Cloud-based AI diagnostic algorithms are reducing reliance on high-magnification optical resolution for certain cancer subtyping applications.
Strategic Opportunities
- India's district hospital network expansion:Ayushman Bharat health infrastructure investment is creating first-time microscope procurement demand in tier-2 and tier-3 cities previously served by referral centers.
- Telepathology service integration:Remote consultation platforms are enabling centralized diagnostic hubs to serve dispersed clinical sites, opening subscription-based revenue models for instrument vendors.
- ISO 15189 accreditation mandate:Medical laboratory quality standards in emerging markets are forcing instrument upgrades, creating replacement cycles for aging manual microscopy platforms.
Industry Challenges
- Pathologist workforce attrition:Training program bottlenecks in the United States, Germany, and Japan are constraining diagnostic throughput despite instrument capacity expansion.
- Legacy system integration complexity:Hospital IT departments face interoperability failures connecting digital microscopy platforms to existing LIS/PACS architectures, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pathological Microscopes Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscopes, Digital Microscopes, Electron Microscopes, Fluorescence Microscopes, Confocal Microscopes Technology: Brightfield, Darkfield, Phase Contrast, Polarization, Multiphoton Imaging Application: Cancer Diagnosis, Infectious Disease Detection, Genetic Research, Drug Development, Tissue Analysis End User: Research Laboratories, Diagnostic Centers, Pharmaceutical Companies, Academic Institutions, Biotech Firms |
| Companies Covered | Nikon Corporation, Labomed, Carl Zeiss AG, Oxford Instruments, Bruker, Olympus Corporation, Euromex Microscopen, Danaher Corporation, Leica Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pathological Microscopes Market Shifts & Advancements
Computational imaging and artificial intelligence are redefining instrument feature requirements, shifting competitive differentiation from optical performance metrics to software ecosystem completeness and regulatory validation status.
Multiplexed immunofluorescence microscopy is fragmenting traditional single-marker histopathology workflows. Cancer research institutes are adopting 30-plex and 50-plex imaging systems for tumor microenvironment profiling. Spatial biology consortia are compressing the timeline for clinical translation of these research-grade platforms.
The EU AI Act risk classification framework is imposing conformity obligations on diagnostic algorithms embedded in digital pathology systems. Manufacturers must maintain technical documentation and human oversight protocols for AI-assisted cancer detection features. European laboratories are prioritizing vendors with established quality management systems for algorithm lifecycle validation.
Pathology departments are consolidating vendor relationships around integrated platform providers. Single-source contracting for instruments, consumables, and software subscriptions is displacing best-of-breed procurement strategies. Academic medical centers in the United States are negotiating enterprise agreements spanning multiple hospital sites.
Global Pathological Microscopes Market Segmentation
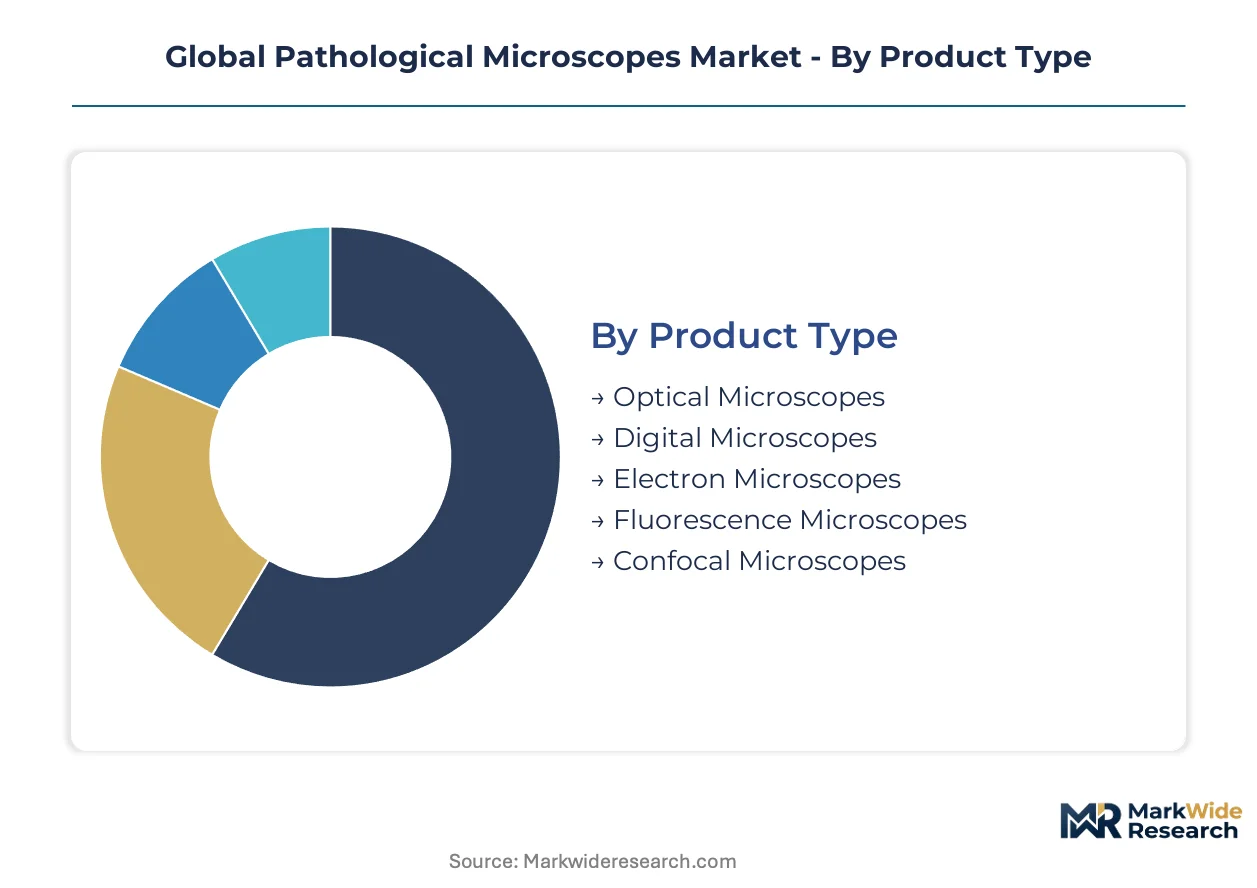
Segmentation in pathological microscopy reveals where capital allocation is shifting amid digital disruption and where legacy optical platforms retain defensive moats. Procurement patterns diverge sharply between high-throughput cancer centers pursuing automation and resource-constrained settings prioritizing equipment longevity.
Product Type:
Substitution pressure from computational imaging and AI-assisted diagnostics is fragmenting traditional product hierarchies, with whole-slide imaging platforms eroding standalone optical instrument procurement in tertiary hospital networks.
- Optical Microscopes:Conventional light microscopy systems employing halogen or LED illumination with achromatic objective lenses remain the installed base foundation across district hospitals and academic pathology departments in India and Southeast Asia. Demand concentrates in Germany and Japan where equipment refresh cycles follow ISO 15189 accreditation mandates, though price sensitivity in emerging markets extends replacement timelines beyond fifteen years.
- Digital Microscopes:Whole-slide imaging systems with automated scanning stages and integrated image management software are capturing procurement share in United States cancer centers pursuing telepathology networks and AI workflow integration. FDA 510(k) clearance pathways for these Class II devices are compressing vendor sales cycles, with hospital laboratories prioritizing vendors offering validated remote consultation capabilities.
- Electron Microscopes:Transmission and scanning electron microscopy platforms resolve subcellular ultrastructure for rare disease identification and renal pathology, serving specialized niches in academic medical centers and national reference laboratories where diagnostic reimbursement supports capital intensity.
- Fluorescence Microscopes:Mercury and LED-illuminated epifluorescence systems enable immunofluorescence diagnostics in nephrology and dermatology, with EU MDR conformity assessment burdens delaying product launches for European manufacturers.
- Confocal Microscopes:Laser scanning systems with pinhole aperture optics deliver optical sectioning for thick tissue specimens, commanding premium positioning in research institutes and pharmaceutical toxicology departments.
Optical Microscopes retain volume leadership across installed base metrics; Digital Microscopes hold the steepest expansion curve in annual procurement value.
Technology:
Cost tier stratification separates research-grade modalities from routine diagnostic workhorses, with premium technologies concentrating in pharmaceutical contract research and economy methods dominating high-volume screening programs.
- Brightfield:Standard transmitted-light illumination with hematoxylin and eosin staining remains the diagnostic workhorse across hospital pathology departments and commercial laboratories, serving cancer diagnosis and infectious disease detection with minimal per-test consumable costs.
- Darkfield:Oblique illumination techniques enhance contrast for unstained specimens including spirochete detection in syphilis diagnosis, retaining specialized utility in reference laboratories and tropical medicine institutes.
- Phase Contrast:Optical path difference amplification enables live cell observation without staining, supporting cell culture monitoring in biotech manufacturing and in vitro fertilization laboratories.
- Polarization:Birefringence detection identifies amyloid deposits, urate crystals, and foreign material in renal and synovial pathology, serving niche diagnostic applications with dedicated hardware requirements.
- Multiphoton Imaging:Near-infrared femtosecond laser excitation enables deep tissue penetration with reduced phototoxicity, commanding premium positioning in neuroscience research institutes and intravital microscopy applications in Japan and the United States.
Brightfield dominates transaction volume across all geographies; Multiphoton Imaging captures the highest average selling prices per installation.
Application:
Customer type differentiation shapes feature requirements, with pharmaceutical procurement prioritizing regulatory validation documentation and clinical laboratories emphasizing throughput metrics and pathologist ergonomics.
- Cancer Diagnosis:Histopathological examination of biopsy specimens for tumor classification, staging, and biomarker assessment drives instrument procurement in hospital networks and dedicated cancer centers across the United States, Germany, and Japan, with screening program expansions creating demand in India's district hospital infrastructure.
- Infectious Disease Detection:Microbiological identification from tissue samples and smears supports tuberculosis, fungal, and parasitic diagnostics in public health laboratories and tropical medicine institutes, with WHO guideline alignment influencing equipment specifications in African and Southeast Asian markets.
- Genetic Research:Cytogenetic analysis and fluorescence in situ hybridization applications in academic medical centers and genome institutes drive high-end microscope configuration with specialized filter sets and camera systems.
- Drug Development:Toxicological pathology and safety assessment in pharmaceutical companies and contract research organizations require GLP-compliant imaging systems with audit trail documentation and validated software.
- Tissue Analysis:Basic histological examination for non-neoplastic conditions including inflammatory and degenerative diseases sustains replacement demand in general hospital pathology departments.
Cancer Diagnosis anchors procurement volume in value terms; Drug Development applications sustain the highest instrument specification premiums.
End User:
Geographic concentration of research funding and diagnostic reimbursement rates creates divergent procurement patterns, with United States academic medical centers and Japanese national university hospitals sustaining premium instrument demand.
- Research Laboratories:National institutes and medical research councils in the United States, Germany, and Japan fund advanced microscopy platforms for basic science and translational investigation, with NIH and DFG grant cycles driving capital equipment acquisition timing.
- Diagnostic Centers:Commercial pathology laboratories and hospital-based departments in the United States and Western Europe pursue automation and digital workflow integration to address pathologist workforce shortages and expand geographic service coverage.
- Pharmaceutical Companies:Multinational drug developers and specialized toxicology contract research organizations in Switzerland, the United States, and the United Kingdom require GLP-validated imaging systems with comprehensive documentation packages for regulatory submission support.
- Academic Institutions:Medical schools and university hospitals combine diagnostic service obligations with training missions, creating mixed procurement profiles spanning routine and research-grade instruments.
- Biotech Firms:Venture-funded development-stage companies and established cell therapy manufacturers prioritize live-cell imaging capabilities for process development and quality control applications.
Diagnostic Centers represent the largest addressable market by unit volume; Pharmaceutical Companies command the highest per-site expenditure on instrument configuration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways for digital pathology systems are compressing commercialization timelines in the United States, while METI industrial policy and EU MDR conformity assessments shape procurement patterns in Japan and Europe respectively.
United States
Hospital pathology departments in Boston, New York, and Houston are expanding instrument procurement to address cancer diagnosis volumes and pathologist workforce shortages. FDA regulates digital pathology systems as Class II medical devices under 21 CFR requirements, accelerating adoption of whole-slide imaging platforms. NIH grant cycles drive capital equipment acquisition timing at academic medical centers in the Greater Boston and San Francisco Bay Area clusters.
Germany
ISO 15189 accreditation mandates for medical laboratories are forcing instrument upgrades in Bavarian and North Rhine-Westphalian hospital networks. EU MDR imposes conformity assessment burdens that extend market access timelines for fluorescence microscopy systems. Baden-Württemberg hosts precision optical component specialists controlling achromatic and apochromatic objective manufacturing.
Japan
Geriatric oncology screening expansion is driving instrument procurement in prefectural hospital networks across Kanto and Kansai regions. METI industrial policy supports domestic microscopy manufacturing through targeted R&D subsidies and production incentives. Tokyo and Osaka anchor the Asia-Pacific installed base with service networks that extend equipment lifecycles.
India
Ayushman Bharat health infrastructure investment is creating first-time microscope procurement demand in tier-2 and tier-3 cities previously served by referral centers. CDSCO regulates medical devices under evolving classification frameworks that shape import and local assembly decisions. Maharashtra and Karnataka districts are seeing concentrated district hospital network expansion with WHO pathology guideline alignment.
United Kingdom
NHS pathology consolidation programs are reshaping procurement specifications toward automated and digital workflow integration. MHRA oversees medical device regulations with post-Brexit divergence from EU MDR creating parallel compliance pathways. London and Southeast England academic medical centers are negotiating enterprise agreements spanning multiple hospital sites.
Global Pathological Microscopes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pathological microscopy supply. The upper tier commands premium positioning through optical engineering heritage and captive lens manufacturing capabilities. Mid-tier assemblers face procurement bottlenecks for objective components. Competitive moves concentrate on strategic partnerships for AI workflow integration and geographic expansion into India's district hospital networks.
Among Japanese precision instrument specialists, Nikon Corporation and Olympus Corporation exemplify vertically integrated optical manufacturing archetypes with deep in-house lens production capabilities. Carl Zeiss AG represents the German optical engineering tradition with premium research-grade positioning. These three anchors collectively illustrate how heritage optics capabilities translate into defensive competitive moats amid digital disruption.
| Leading Market Players |
|---|
| Nikon Corporation |
| Labomed |
| Carl Zeiss AG |
| Oxford Instruments |
| Bruker |
| Olympus Corporation |
| Euromex Microscopen |
| Danaher Corporation |
| Leica Biosystems |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance pathways and EU MDR conformity assessments simultaneously gate supplier qualification and stratify price tiers, with certification status separating premium digital pathology platforms from economy optical instruments in procurement specifications.
Pricing Analysis
Long-term service contracts with automated slide scanning subscriptions dominate United States cancer center procurement, while spot purchases of manual optical systems persist in India's district hospital networks. Price differentiation hinges on FDA 510(k) validation status and ISO 15189 accreditation documentation, with certified platforms commanding substantial premiums over uncertified alternatives. Cost compression in economy-tier optical instruments is intensifying as Indian and Southeast Asian assemblers compete on initial acquisition cost. Academic medical centers in Germany and Japan exhibit lowest price sensitivity due to grant-funded capital cycles, whereas tier-2 hospital administrators in India face severe budget constraints.
Supply Chain Analysis
Extended lead times for apochromatic objective lenses from Baden-Württemberg and Tokyo optical specialists are constraining mid-tier instrument assembly schedules. Manufacturing gravity centers on Germany, Japan, and China, with German and Japanese specialists controlling precision lens grinding and Chinese facilities handling optical housing fabrication. Supply chains draw from rare earth elements for fluorescence filter coatings and specialized glass substrates for achromatic lens production. Single-source vulnerability concentrates in high-numerical-aperture objective manufacturing, where three Japanese and German specialists control critical production capacity. Distribution runs through authorized dealer networks in developed markets and direct government procurement channels in India's Ayushman Bharat infrastructure expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 510(k) and EU MDR certification creates formidable defensive moats, as switching costs lock hospital laboratories into validated instrument platforms with embedded AI diagnostic workflows.
For Market Incumbents: Secure captive supply agreements for apochromatic objective components from German and Japanese optical specialists to insulate against procurement bottlenecks threatening mid-tier assembly capacity. Deepen software ecosystem integration with AI diagnostic algorithm developers to raise switching costs for hospital laboratories already deploying validated digital pathology platforms. Cloud-based computational pathology substitutes pose imminent substitution threats to high-magnification optical resolution demand. For New Entrants and Emerging Players: Telepathology service integration gaps in India's tier-3 district hospitals present accessible white-space targets where established vendors lack localized service infrastructure. Target Maharashtra and Karnataka district hospital networks with bundled instrument-service subscription models that reduce upfront capital barriers for first-time microscope procurement. Partner with domestic Indian assemblers to navigate CDSCO import regulations and establish local assembly presence. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital pathology platforms as FDA validation requirements and AI algorithm development costs escalate. Acquisition candidates with established 510(k) clearance portfolios and validated remote consultation capabilities offer superior long-term viability within a five-to-ten year horizon. Monitor FDA de novo submission volumes for whole-slide imaging systems as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses commercialization timelines for digital pathology vendors targeting United States hospital laboratories. |
| AI Algorithm Companion Development | Validates diagnostic workflows under EU AI Act risk classification frameworks for European market access. |
| Hospital System Partnership Expansion | Locks in multi-site enterprise agreements spanning Boston, New York, and Houston cancer center networks. |
| Objective Lens Supply Agreement | Secures captive component access from Baden-Württemberg and Tokyo optical specialists against bottleneck risk. |
| India District Network Localization | Positions vendors for Ayushman Bharat procurement waves in Maharashtra and Karnataka tier-2 cities. |
Research Methodology
Cross-validation between primary interviews with hospital pathology department heads and secondary analysis of FDA 510(k) submission databases anchors the qualitative findings. Conversations with biomedical engineers, GPO contracts managers, and digital pathology software developers informed instrument procurement specification trends. Secondary sources include CDSCO medical device import records, EU MDR notified body conformity assessment timelines, and hospital capital equipment procurement databases. Bottom-up segmentation modeling triangulates against top-down market sizing from optical component trade flows.
Sensitivity analysis around pathologist workforce attrition rates and AI diagnostic algorithm reimbursement pathways shapes projection confidence intervals across the analysis window. Segmentation dimensions span product type, illumination technology, end-user category, and regional regulatory cluster. CAGRs derive from instrument replacement cycle analysis and digital platform adoption curve modeling. Forecast inputs incorporate NIH grant cycle timing and METI industrial subsidy disbursement patterns.
Forecasts assume regulatory continuity in FDA 21 CFR and EU MDR frameworks; material policy shifts would require re-modeling. Pathologist training program expansion rates and cloud-based AI diagnostic substitution velocity represent key revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygenator Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Stool Management Systems Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Asthma Device Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Low Flux Single-Use Dialyzers Market