
 Whirlpool Turbine Market | 2026-2036
Whirlpool Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Whirlpool Turbine Market Analytics
Scotland is narrowing its whirlpool turbine supply gap through targeted manufacturing investments along the River Clyde corridor. Natel Energy leverages its fish-safe blade architecture to differentiate in ecologically sensitive watersheds. ANDRITZ sustains broad hydro-mechanical expertise that anchors its position across run-of-river installations. Vortex Hydro Energy LLC specializes in low-head vortex induction systems for distributed micro-hydro sites.
A whirlpool turbine converts kinetic energy from free-surface vortices or submerged rotational flows into mechanical rotation, typically operating at heads below five meters with minimal civil infrastructure. These systems employ fixed or variable-pitch runners housed in compact draft tubes, achieving rotational speeds matched to direct-drive permanent magnet generators for off-grid or grid-tied power delivery. Vertical turbines dominate current installations due to simpler bearing arrangements and reduced cavitation risk in low-head riverine settings. Submersible configurations are gaining traction where seasonal flooding demands protected electromechanical packages. Integrated systems that combine turbine, generator, and power electronics in a single deployable unit command attention from developers prioritizing rapid site commissioning.
Federal Energy Regulatory Commission licensing exemptions for conduit hydropower and qualifying conduit facilities are streamlining market entry for whirlpool turbine projects across US waterways. EU Green Deal funding instruments and national renewable energy auctions in Germany, France, and Austria are creating procurement pathways for vortex-based micro-hydro installations. Stakeholders must weigh site-specific flow duration curves against modular system economics when selecting between above-ground and floating deployment architectures.
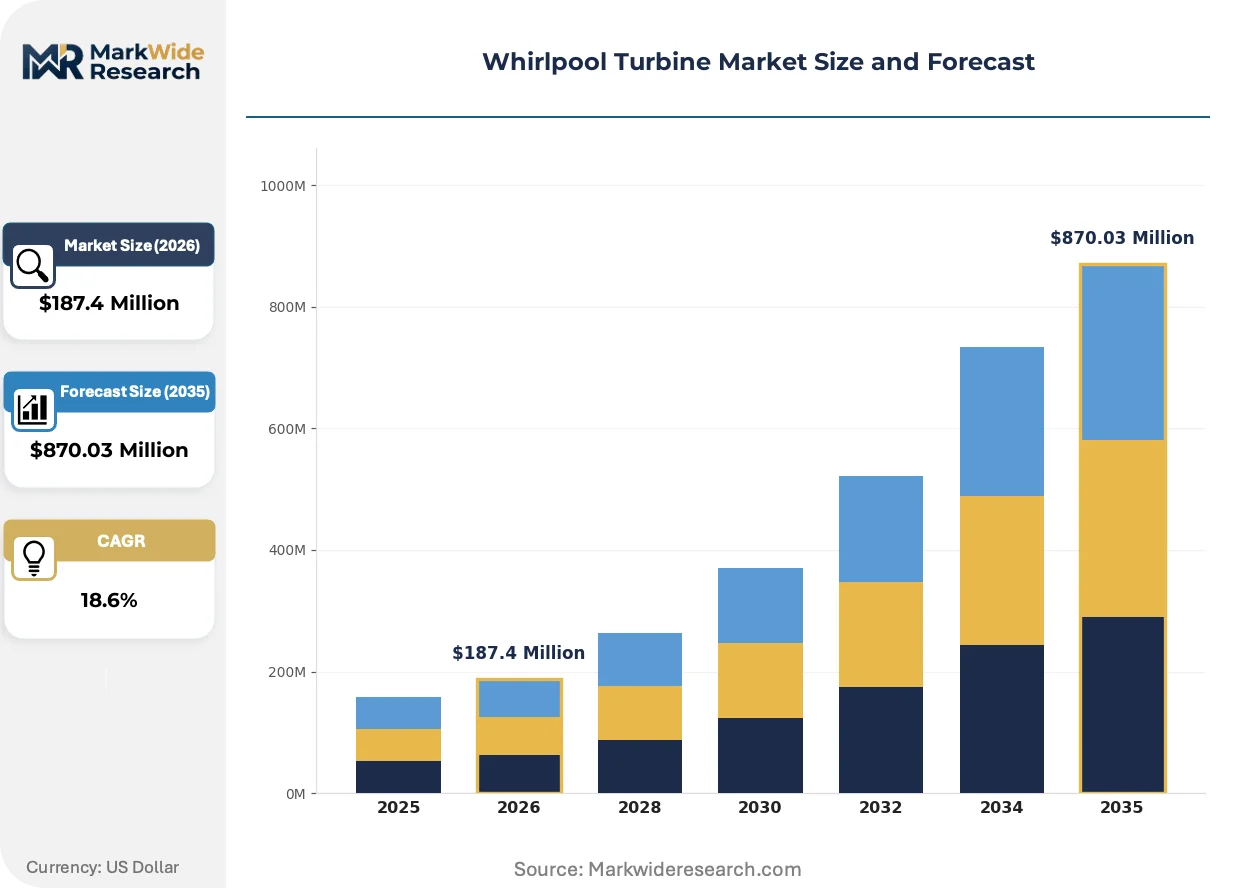
Market Dynamics
Modular turbine architectures are compressing project timelines from years to months, eliminating concrete civil works and unlocking riverine sites previously stranded by high upfront capital requirements. This structural shift toward containerized, deployable systems is redrawing competitive boundaries between traditional hydro-mechanical suppliers and emerging vortex-technology specialists.
Growth Catalysts
- FERC Conduit Exemptions:The Federal Energy Regulatory Commission's streamlined licensing for qualifying conduit facilities removes regulatory friction for whirlpool turbine installations across US waterways, accelerating deployment timelines for distributed micro-hydro projects.
- EU Green Deal Funding:National renewable energy auctions in Germany, France, and Austria create dedicated procurement pathways for vortex-based installations, channeling public capital toward low-head riverine generation.
- Rural Electrification Mandates:Southeast Asian government programs targeting off-grid communities are accelerating orders for sub-kilowatt whirlpool units, with Indonesia, Nepal, and Brazil hosting the densest concentration of active pilot-to-commercial transitions.
Market Restraints
- Flow Duration Uncertainty:Site-specific hydrological variability requires extensive pre-installation monitoring, extending development cycles and raising soft costs for riverine projects in seasonally variable climates.
- Bearing System Concentration:Specialized submersible bearing assemblies rely on a narrow supplier base concentrated in German and Japanese precision manufacturing clusters, creating input vulnerability.
- Grid Interconnection Standards:Inconsistent IEEE 1547 compliance requirements across US utility territories fragment equipment specifications and complicate manufacturer certification pathways.
Strategic Opportunities
- Floating Deployment Architectures:Pontoon-mounted turbine systems eliminate seasonal flooding risks and open previously inaccessible river stretches in the Mekong and Amazon basins where fixed civil works face regulatory prohibition.
- Direct-Drive Generator Convergence:Integration of permanent magnet generators with variable-pitch runners is digitizing power conditioning, enabling grid-forming capabilities without external inverters.
- Scotland's River Clyde Manufacturing Corridor:Targeted industrial investments along this waterway cluster are narrowing domestic supply gaps and creating export capacity for North Sea and Nordic markets.
Industry Challenges
- Fish Passage Certification Complexity:Natel Energy's fish-safe blade architecture has raised performance benchmarks, forcing competitors to redesign runners or absorb extended testing timelines with fisheries regulators.
- Site Assessment Talent Scarcity:Qualified hydrologists capable of modeling free-surface vortex formation in low-head conditions remain concentrated in academic and government research institutions, constraining developer scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whirlpool Turbine Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Turbines, Horizontal Turbines, Mixed Flow Turbines, Submersible Turbines End User: Agriculture, Municipal Water Supply, Power Generation, Irrigation Installation Type: Above Ground, Below Ground, Floating, Integrated Systems Application: Water Treatment, Flood Control, Hydropower, Aquaculture |
| Companies Covered | Kourispower Pty. Ltd, Vortex Hydropower Systems Design and Manufacturing NZ, Suneco Hydro, Natel Energy, ANDRITZ, Turbulent Hydro, Vortex Hydro Energy LLC, Gaia Turbine SA, Dobriyal Brothers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whirlpool Turbine Market Evolving Landscape
Sensor-embedded turbine systems and predictive maintenance algorithms are transforming whirlpool installations from passive mechanical assets into connected infrastructure. This convergence of electromechanical hardware with data-layer intelligence is compressing operational expenditure profiles and reshaping buyer procurement criteria.
Computational fluid dynamics-optimized blade geometries are digitizing runner design cycles, allowing manufacturers to simulate vortex induction patterns before physical prototyping. Run-of-river developers in Austria and Bavaria are adopting these simulation-first workflows, collapsing iteration timelines from months to weeks and enabling site-specific customization at scale production economics.
The EU Green Deal's funding instruments are mandating lifecycle carbon accounting for renewable infrastructure procurement, extending upstream to steel and rare-earth magnet supply chains. German and French auction mechanisms now embed embodied carbon thresholds, favoring turbine suppliers with verified low-carbon manufacturing footprints and documented circular material recovery protocols.
Utility buyers are unbundling equipment supply from long-term service contracts, shifting toward performance-guarantee procurement models where vendors assume operational risk. This restructuring is most visible in Brazilian and Indonesian rural electrification programs, where developers now contract energy availability rather than installed capacity, transferring maintenance burden to technology suppliers.
Whirlpool Turbine Market Segmentation
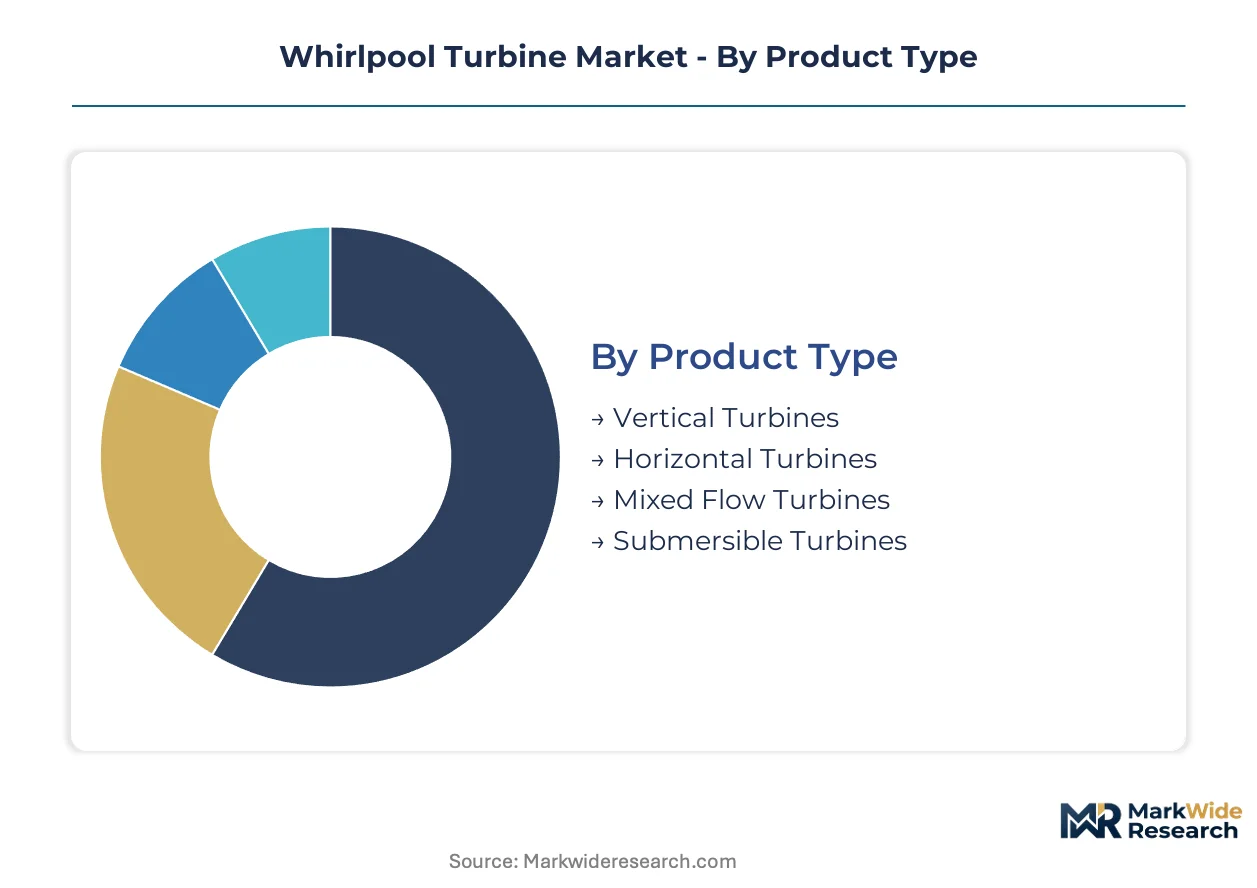
Whirlpool turbine procurement varies sharply across deployment contexts, with installation type and end-use requirements dictating runner geometry, bearing specifications, and civil engineering intensity. Segment-specific selection criteria compress or extend development cycles depending on regulatory exposure and site accessibility.
Product Type:
Vertical turbines rotate through project pipelines fastest due to standardized bearing arrangements and reduced cavitation modeling requirements, while submersible configurations face extended validation timelines for flood-proofing certifications.
- Vertical Turbines:Simpler bearing assemblies and reduced cavitation risk in low-head riverine settings dominate current procurement volumes. Fixed installations across Brazilian and Nepalese rural electrification programs favor these units for their minimal maintenance access requirements and direct-drive generator compatibility.
- Submersible Turbines:Protected electromechanical packages withstand seasonal flooding in Mekong and Amazon basin deployments. Protected housing configurations add procurement lead time but unlock river stretches where fixed civil works face regulatory prohibition from fisheries authorities.
- Horizontal Turbines:Axial-flow runners suit constricted channel geometries with limited vertical clearance.
- Mixed Flow Turbines:Diagonal runners blend radial and axial discharge for intermediate head conditions.
Vertical turbines anchor the volume base while submersible configurations gain share at the steepest rate.
End User:
Power generation contracts command premium pricing tiers due to continuous duty cycles and grid synchronization requirements, whereas irrigation applications tolerate intermittent operation with simpler control systems.
- Power Generation:Continuous duty applications demand precision blade geometries and grid-forming inverter integration. Off-grid communities in Indonesia and rural Brazil specify these units for baseload micro-grid supply, with procurement emphasizing energy availability guarantees over installed capacity metrics.
- Agriculture:Intermittent pumping cycles accommodate simpler runner designs with seasonal deployment flexibility. Southeast Asian government rural electrification programs prioritize sub-kilowatt units for agricultural co-ops, balancing irrigation lift against modest power export revenue.
- Municipal Water Supply:Conduit installations leverage FERC licensing exemptions for streamlined deployment across US water infrastructure.
- Irrigation:Seasonal flow matching allows modular redeployment between canal sites as water availability shifts.
Power generation commands the highest unit margins while agriculture expands most quickly through government mandate programs.
Installation Type:
Above-ground systems minimize site preparation costs but constrain deployment to stable riverbanks, whereas floating architectures eliminate seasonal flooding exposure at the expense of mooring complexity.
- Above Ground:Fixed concrete anchoring suits stable hydrology with predictable flood regimes. Austrian and Bavarian run-of-river developers favor these installations for their rapid commissioning and minimal specialized marine engineering requirements.
- Floating:Pontoon-mounted systems eliminate seasonal flooding risks in variable-flow regimes. Mekong and Amazon basin projects specify these configurations where fixed civil works face outright prohibition from watershed protection authorities.
- Below Ground:Subsurface housing reduces visual impact in sensitive landscapes but extends excavation timelines.
- Integrated Systems:Containerized turbine-generator-power electronics packages compress commissioning from months to weeks.
Above-ground installations retain the largest installed base while floating systems climb the fastest as regulatory barriers harden against fixed infrastructure.
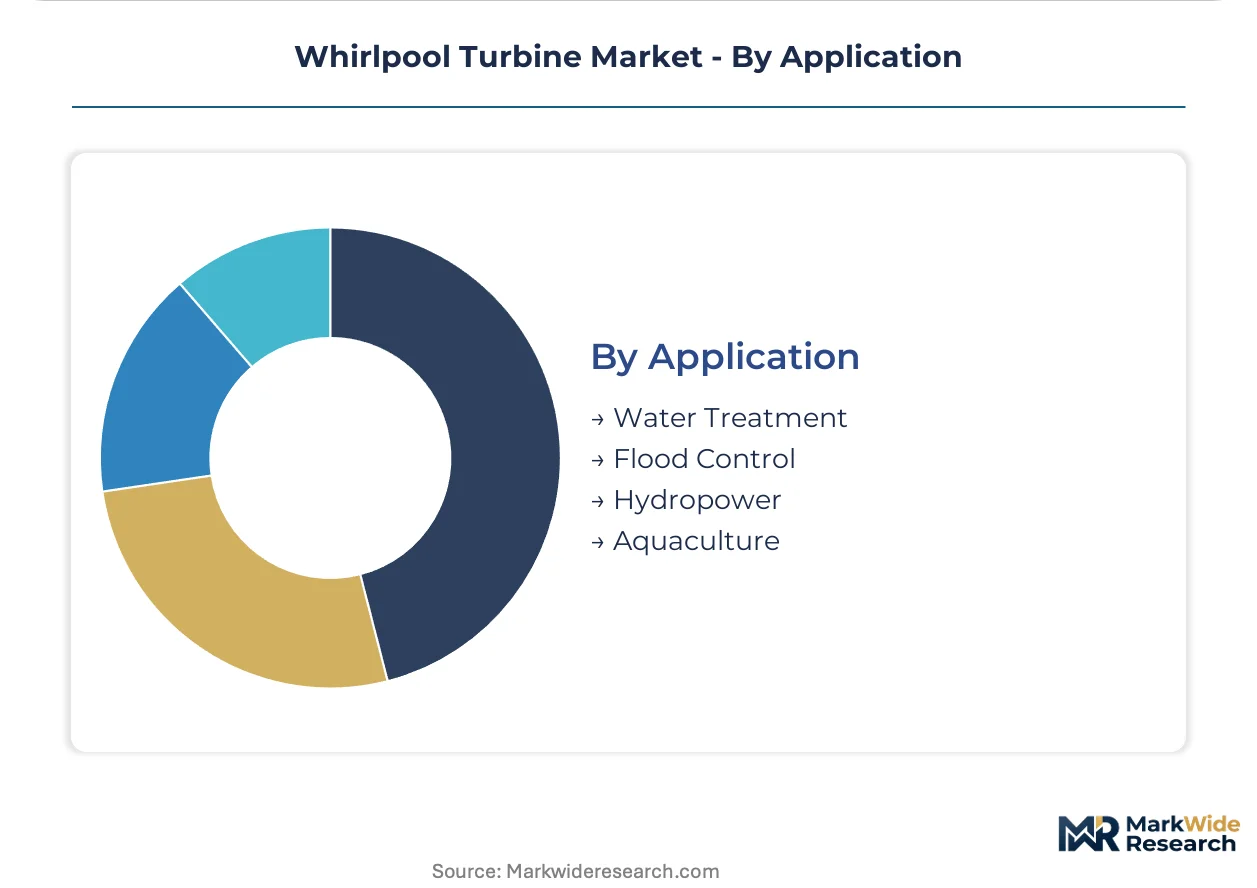
Application:
Hydropower applications concentrate procurement volumes through dedicated renewable energy auctions, while water treatment installations fragment across municipal utility budgets with irregular capital release schedules.
- Hydropower:Grid-tied and off-grid electricity production drives the dominant share of whirlpool turbine deployment. EU Green Deal funding instruments in Germany, France, and Austria channel public capital toward these installations through national renewable energy auctions with embedded lifecycle carbon thresholds.
- Water Treatment:Conduit hydropower recovery within treatment plant infrastructure leverages existing flow infrastructure. US installations benefit from FERC licensing exemptions for qualifying conduit facilities, removing regulatory friction for distributed micro-hydro projects.
- Flood Control:Energy recovery from controlled discharge structures supplements operational budgets for drainage authorities.
- Aquaculture:Oxygenation and circulation requirements in intensive fish farming create niche demand for low-head units.
Hydropower dominates current procurement value while water treatment applications show the steepest expansion trajectory as conduit exemptions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whirlpool turbine deployment patterns diverge sharply by geography: Southeast Asian markets prioritize sub-kilowatt off-grid units for rural electrification, while European and North American procurement emphasizes grid-tied conduit installations with embedded carbon accounting requirements.
United States
FERC conduit exemptions accelerate distributed micro-hydro deployment across municipal water infrastructure. The Federal Energy Regulatory Commission's streamlined licensing removes regulatory friction for qualifying facilities. California and Pacific Northwest utilities pilot sensor-embedded turbine systems for predictive maintenance integration.
Brazil
Rural electrification mandates in Amazon basin states drive sub-kilowatt unit procurement for isolated communities. ANEEL auction mechanisms channel federal capital toward renewable micro-generation in off-grid territories. Minas Gerais and Pará host the densest concentration of pilot-to-commercial project transitions.
Germany
National renewable energy auctions under EU Green Deal funding embed lifecycle carbon thresholds for vortex-based installations. Bavarian run-of-river developers adopt computational fluid dynamics-optimized blade geometries. The Baden-Württemberg precision manufacturing cluster supplies specialized submersible bearing assemblies.
Indonesia
Government rural electrification programs accelerate orders for modular turbine systems in archipelago provinces. PLN off-grid mandates prioritize containerized deployable units for rapid site commissioning. Java and Sulawesi river basins concentrate active pilot projects with floating deployment architectures.
Scotland
Targeted manufacturing investments along the River Clyde corridor narrow domestic supply gaps for North Sea export markets. Scottish Government renewable energy funding supports vortex-technology commercialization. Glasgow-based fabrication clusters develop integrated turbine-generator-power electronics packages.
Whirlpool Turbine Market Competitive Landscape
Capability concentration sits with precision-mechanical specialists; scale advantage sits with diversified hydro-mechanical conglomerates. The vendor base stratifies across three tiers: vortex-technology pioneers with fish-safe blade architectures, established turbine manufacturers leveraging run-of-river expertise, and regional fabricators serving localized rural electrification programs. Dominant competitive moves include modular system integration to compress commissioning timelines and strategic partnerships with fisheries regulators to accelerate environmental certification.
Within the vortex-technology tier, Natel Energy and Vortex Hydro Energy LLC exemplify fish-safe and low-head specialization respectively. ANDRITZ anchors the diversified hydro-mechanical segment with broad run-of-river capabilities. Turbulent Hydro occupies a position among emerging vortex-technology specialists targeting distributed micro-hydro sites.
| Leading Market Players |
|---|
| Kourispower Pty. Ltd |
| Vortex Hydropower Systems Design and Manufacturing NZ |
| Suneco Hydro |
| Natel Energy |
| ANDRITZ |
| Turbulent Hydro |
| Vortex Hydro Energy LLC |
| Gaia Turbine SA |
| Dobriyal Brothers |
| Others |
Value Network & Pricing Analysis
German and Japanese precision manufacturing clusters for submersible bearing assemblies concentrate upstream supply, anchoring margin capture with specialized component suppliers rather than downstream system integrators. This concentration forces turbine OEMs to absorb input cost volatility or pursue multi-year procurement contracts that lock in capacity but compress flexibility.
Pricing Analysis
Long-term offtake agreements dominate commercial procurement, with Brazilian and Indonesian rural electrification programs contracting energy availability guarantees rather than installed capacity. Price differentiation rests on fish-safe blade certification tiers and integrated power electronics bundling. Cost compression in sub-kilowatt units intensifies as government mandate programs aggregate demand and squeeze vendor margins. Agricultural co-ops exhibit highest price sensitivity due to seasonal revenue cycles, while municipal water utilities tolerate premium pricing for FERC-exempt conduit installations with streamlined deployment.
Supply Chain Analysis
Extended payment terms from Southeast Asian government procurement programs strain working capital for European component suppliers. Manufacturing draws from Germany, Japan, and Scotland for precision bearings, rare-earth permanent magnets, and integrated generator assemblies. Single-source vulnerability concentrates in submersible bearing systems from Baden-Württemberg and Nagoya industrial clusters. Distribution runs through regional EPC contractors in Brazil, Indonesia, and Nepal for site-specific commissioning and civil works coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment architectures and regulatory frameworks creates niche opportunities for specialized entrants. Modular system demand from archipelago provinces and flood-prone watersheds rewards agile suppliers over integrated conglomerates.
For Market Incumbents: Pre-empt vortex-technology specialists by acquiring fish-safe blade IP or partnering with fisheries regulators to accelerate certification timelines. ANDRITZ and Natel Energy should lock in exclusive supply agreements with German bearing manufacturers before capacity constraints harden. Backward integration into permanent magnet generator production insulates margin pools from rare-earth price volatility. For New Entrants and Emerging Players: Floating deployment architectures in Mekong and Amazon basin tributaries represent the most penetrable entry point, as fixed civil works face outright prohibition from watershed protection authorities. Pontoon-mounted systems for seasonal flood regimes carry lower regulatory burden and faster commissioning timelines. Target performance-guarantee procurement models with Brazilian and Indonesian rural electrification agencies to transfer operational risk and differentiate against capacity-based competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-mechanical specialists in Scotland and Bavaria with established vortex-technology IP but limited scaling capital. Five-to-ten year viability hinges on regulatory permanence for FERC conduit exemptions and EU Green Deal funding instruments. Monitor ANEEL auction participation rates and PLN off-grid mandate execution as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fish-Safe Blade Certification Investment | Natel Energy's regulatory pathway sets performance benchmarks competitors must match to access ecologically sensitive watersheds. |
| Modular System Integration | Containerized turbine-generator-power electronics packages compress commissioning timelines from months to weeks for Indonesian archipelago deployments. |
| Strategic Partnership with Fisheries Regulators | Early engagement with EPA and state environmental agencies accelerates environmental certification for US conduit installations. |
| Backward Integration into Generator Manufacturing | In-house permanent magnet production insulates margin pools from rare-earth supply volatility and Chinese export restrictions. |
| Geographic Expansion via Floating Deployment | Pontoon-mounted systems unlock Mekong and Amazon basin river stretches where fixed civil works face regulatory prohibition. |
Research Methodology
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and fisheries regulatory specialists converged on the working assumptions for deployment feasibility and environmental certification timelines. Primary interviews with turbine OEM procurement teams and precision-mechanical component suppliers were cross-referenced against FERC licensing databases, EU Green Deal funding instrument disclosures, ANEEL auction records, and IEA distributed generation reports. Bottom-up project pipeline tallies were triangulated with top-down market sizing from national renewable energy auction capacity allocations.
Demand-supply balance modeling anchored the analytical framework, with segmentation across vertical, submersible, and horizontal turbine architectures; power generation, agriculture, and municipal water supply end uses; and above-ground, floating, and integrated installation types. Capacity-weighted average pricing from Brazilian and Indonesian contract awards informed value projections across the analysis window. Hydrological flow duration curves and modular system economics shaped the capacity deployment trajectory, with CAGRs derived from year-over-year auction participation and commercial operation date tracking.
Macroeconomic conditions sit as an overlay; deviation in Southeast Asian government fiscal capacity, German precision manufacturing input costs, or rare-earth magnet export policy would shift the trajectory. Forecasts reflect documented assumptions around FERC exemption permanence, EU Green Deal funding continuity, and ANEEL auction mechanism stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Hydropower Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market