
 Run of River Power Market | 2026-2036
Run of River Power Market Size, Share, and Industry Trends Forecast 2026-2036
Run of River Power Market Intelligence
The integration of advanced automated control systems and predictive analytics is reshaping the operational efficiency of run-of-river power facilities. These digital technologies allow for real-time adjustments to turbine output based on fluctuating water flow. Andritz Hydro specializes in high-efficiency turbine technology for varied flow conditions. Siemens leverages its digital portfolio for integrated grid management, while Voith competes on its comprehensive hydropower equipment and service offerings.
Run of river power is a hydroelectric generation method that harnesses a river's natural flow and elevation drop with minimal water storage. Unlike conventional hydro, it avoids large dams, relying instead on weirs or smaller diversions to channel water through turbines. Small and medium scale capacity projects constitute the bulk of new developments due to faster permitting and lower ecological disruption. Among end users, independent power producers are expanding their portfolios, driven by policies promoting decentralized energy.
Regulatory frameworks such as the EU's Renewable Energy Directive and feed-in tariffs in countries like Vietnam provide critical financial incentives for project development. Concurrently, environmental standards from agencies like the U.S. EPA and Canada's Impact Assessment Agency govern project siting. These rules balance renewable energy targets with ecological preservation. Future viability hinges on navigating site-specific environmental regulations while securing long-term power purchase agreements.
Market Dynamics
The central structural force shaping the run of river power market is the global policy push for decentralized, low-impact renewable energy generation. This momentum, codified in frameworks like the EU Green Deal, favors smaller, faster-to-deploy projects over conventional large-dam hydropower.
Growth Catalysts
- Favorable Regulatory Frameworks:National energy policies, including China's dual carbon goals and feed-in tariffs in Vietnam, are providing direct financial incentives and priority grid access for run of river power projects, accelerating their development pipeline.
- Decentralization by IPPs:Independent power producers (IPPs) are actively expanding their portfolios with smaller, distributed generation assets to mitigate reliance on centralized grids and capitalize on regional energy demand, particularly in remote industrial areas.
- Geographic Suitability:Development is concentrating in mountainous regions with consistent river flows. Countries such as Brazil, Vietnam, and nations across the Alpine region of Europe offer ideal topography for new project siting.
Market Restraints
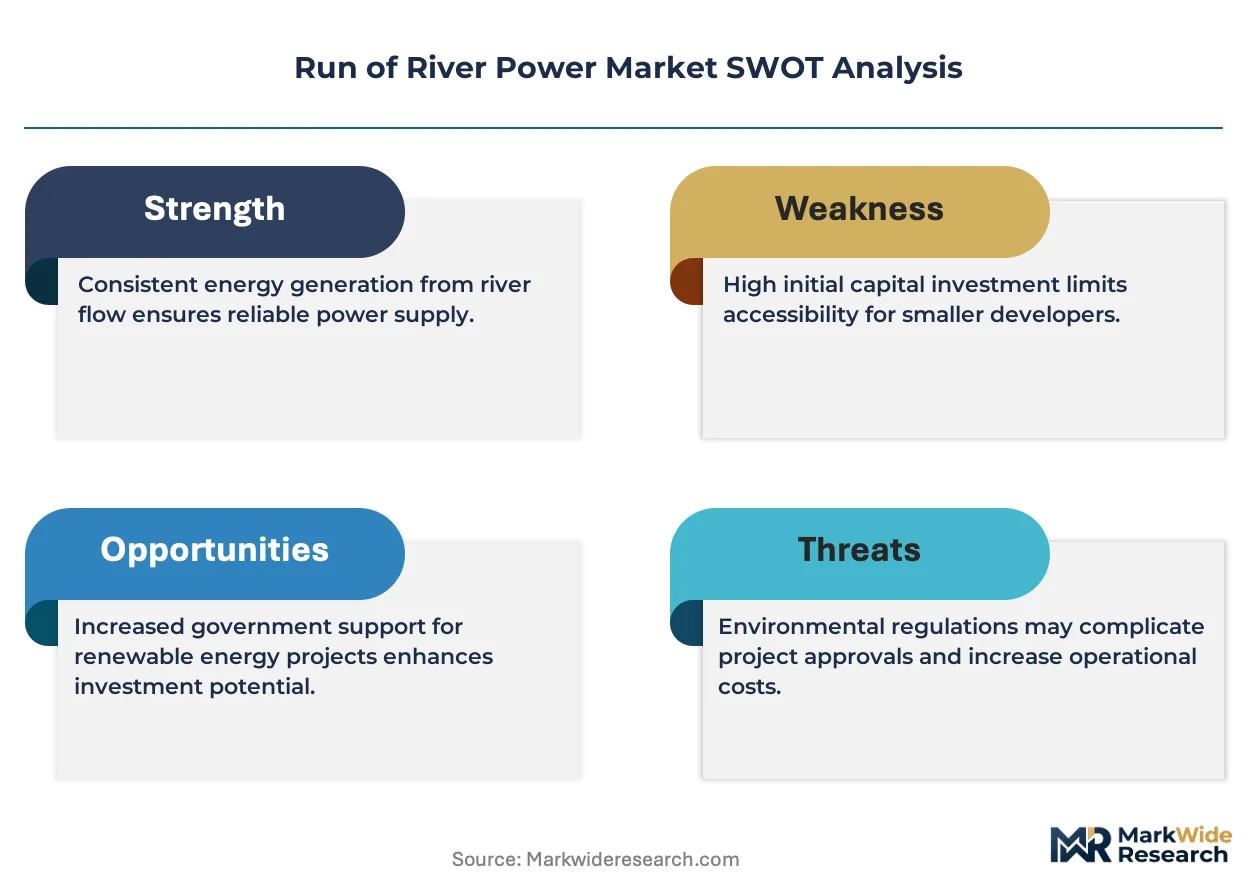
- Hydrological Variability:Project output is directly dependent on natural river flow, making it susceptible to seasonal and climate-change-induced variations in precipitation. This intermittency poses a structural risk to consistent power generation and revenue streams.
- Strict Environmental Scrutiny:Regulatory bodies like Canada's Impact Assessment Agency impose stringent environmental reviews that can delay or block projects. Concerns over impacts on fish migration and local ecosystems create significant project development friction.
- Site-Specific Limitations:The viability of run of river power is fundamentally constrained by geography and topography. The limited availability of suitable sites with the necessary elevation drop and flow rate restricts scalable deployment.
Strategic Opportunities
- Hybridization with Energy Storage:Integrating battery energy storage systems (BESS) with run of river facilities presents a major opportunity. This pairing can smooth output, provide grid stabilization services, and convert intermittent power into a dispatchable asset.
- Underdeveloped Hydropower Potential:Significant untapped potential exists in regions with mountainous terrain and growing energy needs, such as the Andean countries in South America and parts of Southeast Asia, offering new frontiers for project developers.
- Modernization of Aging Assets:Upgrading older, small-scale hydro facilities with modern, high-efficiency turbines and automated controls offers a pathway to increase generation capacity without the need for new greenfield construction and associated permitting hurdles.
Industry Challenges
- Complex Permitting Processes:Developers face operational hurdles in navigating multi-layered, site-specific environmental and land-use regulations from agencies like the U.S. EPA. These lengthy and unpredictable approval timelines increase project costs and risk.
- PPA Negotiation Complexity:Securing bankable, long-term power purchase agreements (PPAs) is a persistent challenge. Competition from other renewable sources like solar and wind puts pressure on pricing and contract terms for run of river generators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Run of River Power Market |
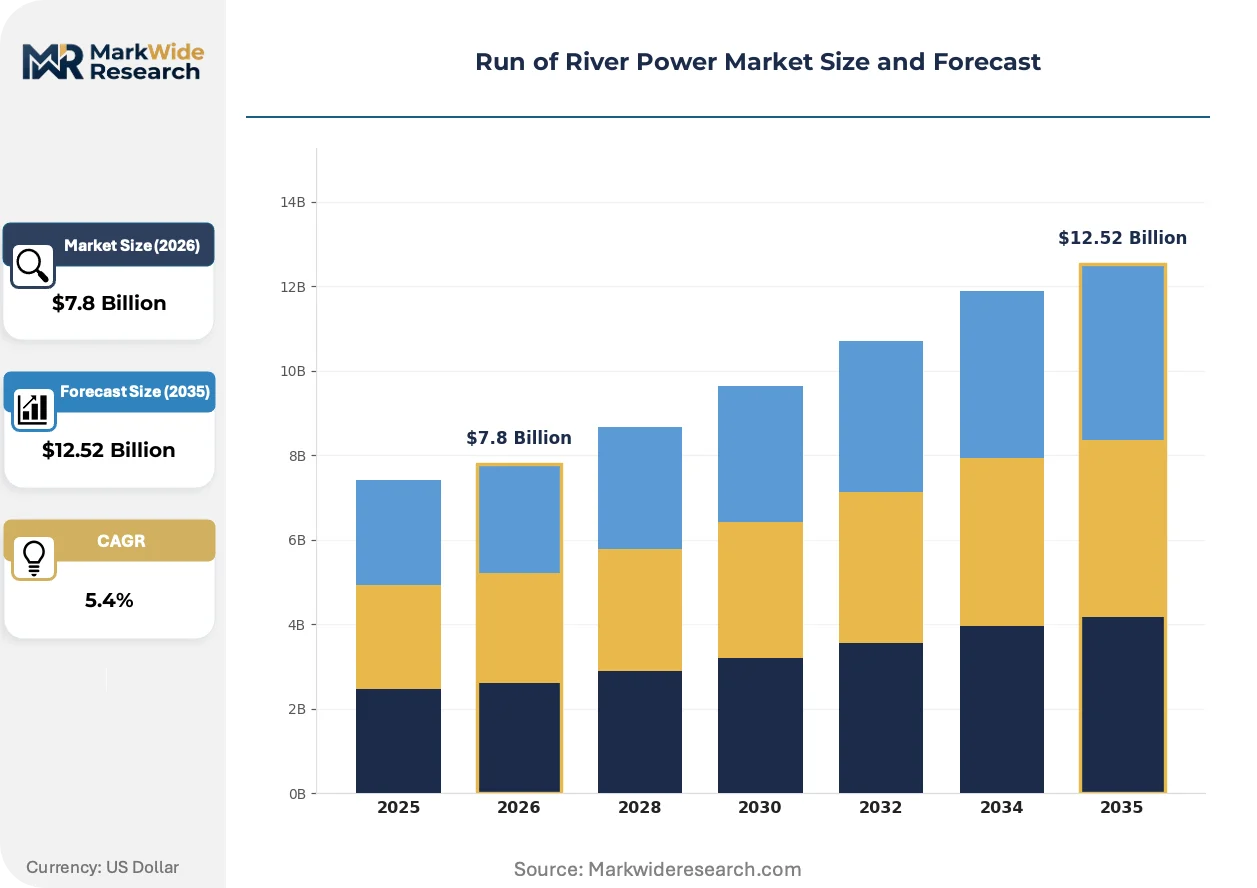
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydropower, Turbine Technology, Energy Storage, Automated Control End User: Utilities, Independent Power Producers, Municipal Corporations, Renewable Energy Developers Installation: Onshore, Integrated Systems, Modular Structures, Dedicated Sites Capacity: Small Scale, Medium Scale, Large Scale, Micro Generation |
| Companies Covered | General Electric, Siemens, ABB, Andritz Hydro, Alstom, China Three Gorges Corporation, Voith, GE Renewable Energy, Sinohydro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Run of River Power Market Strategic Shifts & Innovations
The convergence of digital control technologies and supportive policy mechanisms is enhancing the operational efficiency and financial viability of run of river power assets. These innovations focus on maximizing energy capture from variable water flows while meeting stringent environmental and grid integration requirements.
Automated control systems that incorporate predictive analytics are a key technological evolution. These systems use real-time hydrological data and weather forecasts to adjust turbine settings for optimal performance. Independent power producers are the primary adopters, seeking to maximize electricity output and revenue from their assets. This technology is digitizing plant operations, enabling a shift from reactive manual oversight to proactive, autonomous energy generation management.
Europe's Renewable Energy Directive is an influential policy shift that creates a favorable environment for run of river projects. The directive's sustainability criteria and support schemes implicitly favor smaller-scale hydro with minimal ecological disruption over large dam construction. Project developers in EU member states with significant hydro resources, such as Austria and Italy, are most affected, aligning their investment strategies to capitalize on these specific incentives.
A shift in energy procurement is occurring as industrial consumers in remote areas seek to secure reliable, local power sources. This trend leads to the formation of direct power purchase agreements with nearby run of river facilities, bypassing traditional utility supply chains. This pattern is most pronounced in mountainous regions of countries like Brazil and Vietnam, where industries like mining or manufacturing require stable electricity independent of national grid constraints.
Run of River Power Market Segmentation
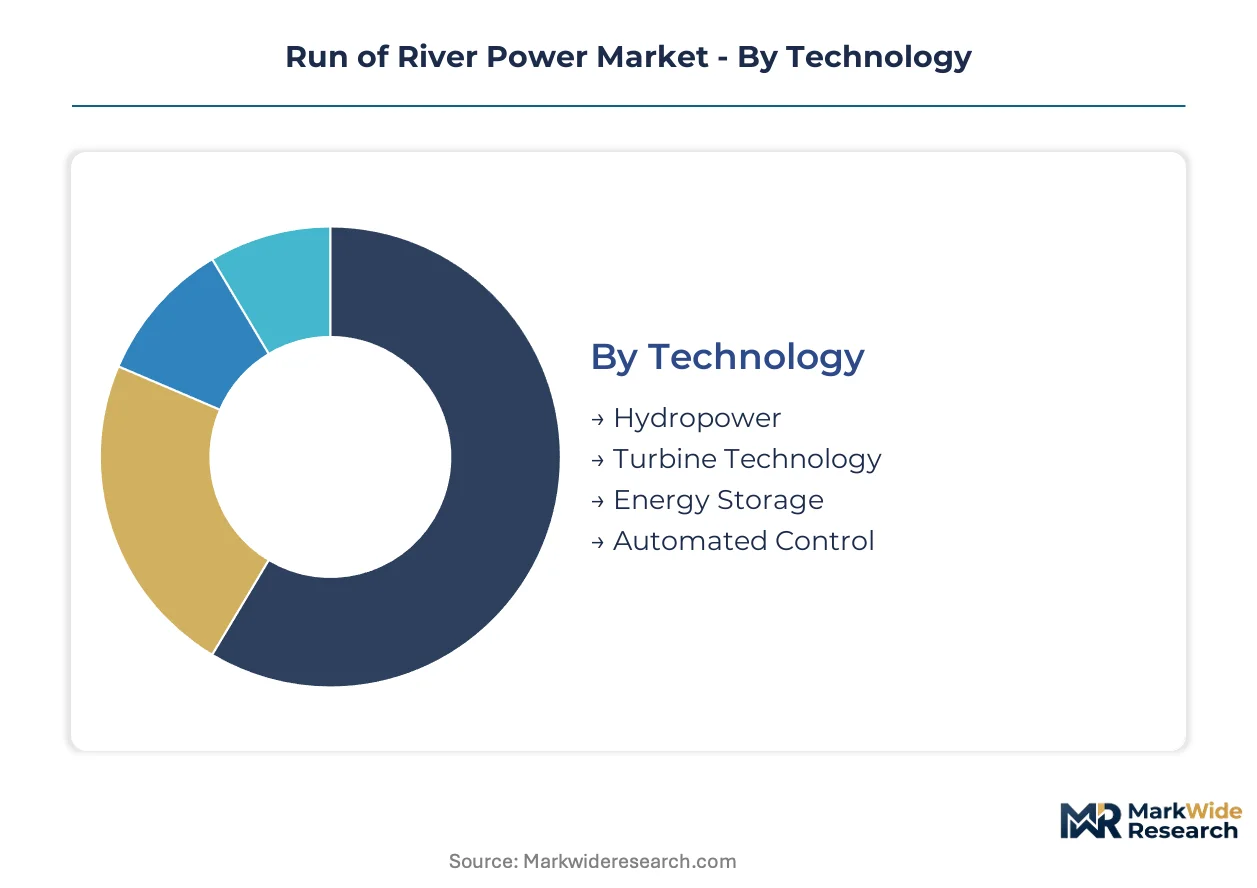
The Run of River Power Market segments across technology, end-user, installation, and capacity, reflecting the diverse approaches to harnessing hydrokinetic energy. Understanding these distinctions is critical for identifying specific market opportunities and challenges. Each segment addresses unique operational demands and investment profiles within the broader renewable energy landscape.
Technology:
The after-sales service intensity for run of river power technologies varies significantly, reflecting the complexity and operational demands of each component.
- Turbine Technology:This segment encompasses the core mechanical systems converting water flow into rotational energy, including Kaplan, Francis, and Pelton designs optimized for varied head and flow conditions. Demand concentrates in regions with diverse hydrological profiles, such as the Alpine countries, where high-efficiency turbines maximize energy capture.
- Automated Control:This segment covers advanced digital systems that manage plant operations, adjust turbine output, and integrate with grid infrastructure using real-time data and predictive analytics. Independent power producers are the primary adopters, seeking to optimize energy output and minimize operational costs across their distributed assets.
- Hydropower:This category refers to the foundational principles and general engineering of run of river systems, focusing on overall plant design and water diversion structures.
- Energy Storage:This segment includes battery energy storage systems (BESS) integrated with run of river facilities to smooth intermittent output and provide grid stability services.
Turbine Technology holds the largest share; momentum sits with Automated Control.
End User:
Customer profiles for run of river power facilities range from large, established utilities to agile, specialized developers.
- Independent Power Producers:These entities develop, own, and operate power generation facilities, selling electricity to utilities or directly to consumers, often driven by decentralized energy policies. Their demand concentrates in remote industrial areas of countries like Brazil and Vietnam, seeking reliable, localized power sources.
- Utilities:This segment includes public or private companies responsible for generating, transmitting, and distributing electricity to a broad consumer base, often integrating run of river projects into their diversified generation portfolios. Utilities in regions like Europe leverage these assets to meet renewable energy mandates under directives like the EU's Renewable Energy Directive.
- Municipal Corporations:Local government bodies utilize run of river projects to provide power for municipal operations or local communities, often focusing on self-sufficiency and local economic benefits.
- Renewable Energy Developers:Companies specializing in the development and construction of various renewable energy projects, including run of river, often for subsequent sale to IPPs or utilities.
Independent Power Producers are expanding most quickly, while Utilities maintain a foundational demand.
Installation:
Installation methods for run of river power projects reflect varying levels of site integration and construction complexity.
- Integrated Systems:This segment involves comprehensive project development where power generation components are seamlessly designed and constructed within the natural river environment, often including advanced digital controls. Demand for integrated systems is pronounced in regions with strict environmental regulations, such as Canada, requiring minimal ecological disruption.
- Onshore:This category refers to all run of river power facilities located on land, utilizing river flow diverted through channels or pipelines to turbines situated on the riverbank or nearby. Onshore installations are prevalent across mountainous geographies like the Andean countries, where suitable elevation drops are readily available.
- Modular Structures:These installations involve prefabricated components that can be assembled on-site, potentially reducing construction time and costs for smaller-scale projects.
- Dedicated Sites:This segment pertains to projects built on specific locations identified solely for run of river power generation, often requiring extensive site preparation and infrastructure development.
Onshore installations remain prevalent, with Integrated Systems gaining significant traction.
Capacity:
The cost tiers associated with run of river power capacity types vary considerably, influenced by scale and infrastructure requirements.
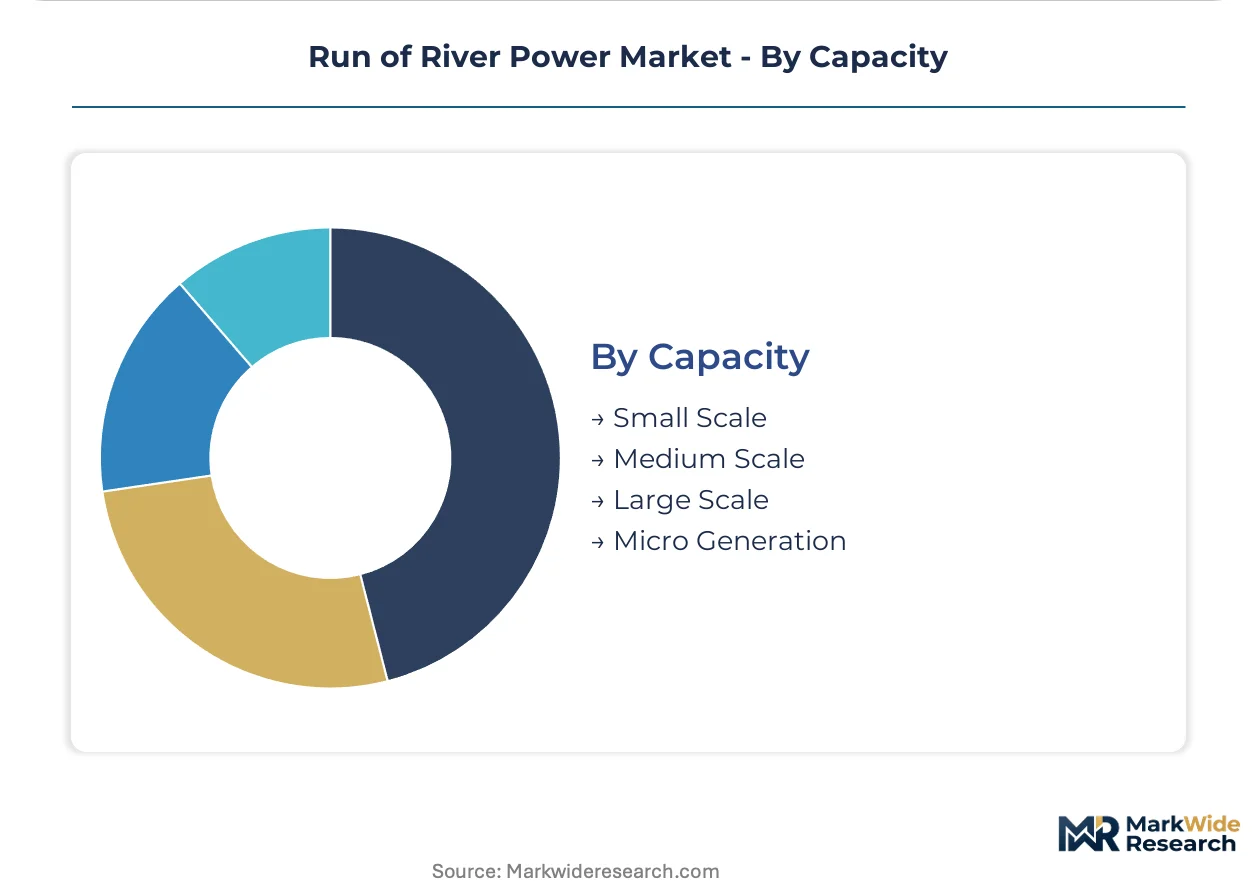
- Small Scale:Projects typically ranging from 1 MW to 10 MW, characterized by faster permitting and lower environmental impact compared to larger hydro schemes. This capacity segment dominates new developments due to favorable policies and easier integration into local grids, particularly in regions like Southeast Asia.
- Medium Scale:Projects generally between 10 MW and 50 MW, balancing higher power output with manageable ecological footprints and requiring more substantial civil works. Such projects are sought by independent power producers for their significant contribution to regional energy supply in areas like Brazil.
- Large Scale:Facilities exceeding 50 MW, which are less common in run of river applications due to the inherent design constraints and increased environmental scrutiny.
- Micro Generation:Very small systems, typically under 1 MW, often serving remote communities or individual properties, prioritizing localized energy access over large-scale grid contributions.
Small Scale projects hold the largest share, and Medium Scale projects are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent power producers drive significant demand for run of river power, particularly in regions promoting decentralized energy generation. These entities seek to expand portfolios with smaller, distributed assets, capitalizing on regional energy needs. Utilities also integrate these projects to meet renewable energy mandates across various geographies.
Vietnam
Vietnam's mountainous regions exhibit strong demand for run of river power due to growing energy needs and suitable topography. The country's feed-in tariffs provide critical financial incentives for new project development. Project developers across the northern and central highlands are actively pursuing small and medium-scale installations.
Brazil
Brazil's independent power producers are expanding their portfolios with run of river facilities to serve remote industrial areas. National energy policies encourage these smaller, distributed generation assets to mitigate grid reliance. The mountainous states of Minas Gerais and Santa Catarina are attracting significant investment for new project siting.
Austria
Austria, a key part of Europe's Alpine region, shows sustained demand for high-efficiency turbine technology given its abundant hydro resources. The EU's Renewable Energy Directive implicitly favors smaller-scale hydro projects with minimal ecological disruption. Project developers in Tyrol and Salzburg are actively modernizing aging assets and developing new sites.
Canada
Canada's demand for run of river integrated systems is driven by stringent environmental standards and a focus on minimal ecological disruption. The Impact Assessment Agency imposes rigorous reviews that shape project development and siting. British Columbia's extensive river systems are a focal point for projects requiring advanced digital controls and careful planning.
United States
United States developers are pursuing run of river projects, particularly for upgrading older, small-scale hydro facilities. The U.S. EPA's environmental standards govern project siting and operational practices. The Pacific Northwest, with its numerous river systems, presents opportunities for both greenfield developments and asset modernization initiatives.
Run of River Power Market Key Industry Players
Channel-controlling players compete with product-specialist players across the run of river power market. The market structure exhibits a tiered consolidation, where large engineering firms offer comprehensive solutions alongside niche technology providers. Strategic archetypes include integrated solution providers, specialized turbine manufacturers, and regional project developers. Portfolio diversification and strategic partnerships represent dominant competitive moves among these entities.
Specialists in advanced turbine technology and integrated hydropower solutions include Andritz Hydro, a GmbH company recognized for developing high-efficiency turbine designs optimized for varied head and flow conditions. Siemens, an AG company, exemplifies a broader digital portfolio, positioning itself as an integrated grid management provider that leverages predictive analytics for operational efficiency. Voith, another GmbH, occupies a strong position through its comprehensive hydropower equipment and service offerings, anchoring the market for full lifecycle support and modernization projects globally. These entities collectively represent the technological frontier in harnessing river flow for energy generation.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| ABB |
| Andritz Hydro |
| Alstom |
| China Three Gorges Corporation |
| Voith |
| GE Renewable Energy |
| Sinohydro Corporation |
| Others |
Cost & Logistics Intelligence
High-efficiency turbine technology, concentrated among a few specialized manufacturers, strongly influences project development costs and ultimately power purchase agreement pricing. This upstream concentration shapes the competitive dynamics for independent power producers.
Pricing Analysis
Long-term power purchase agreements often follow a cost-plus model, frequently indexed to local energy market prices or inflation rates. Pricing differentiation stems from turbine efficiency, project scale, and the level of integrated automated control systems. Competition from alternative renewable sources like solar and wind creates downward pressure on PPA terms for run of river generators. Independent power producers exhibit sensitivity to upfront capital costs, while utilities prioritize long-term grid stability and renewable energy compliance.
Supply Chain Analysis
Specialized turbine manufacturers like Andritz Hydro and Voith, primarily based in Europe, concentrate the supply of core mechanical systems for run of river power. The supply chain relies heavily on high-precision components and advanced digital control systems for operational efficiency. Hydrological variability, driven by climate change, poses a structural risk to consistent power generation and supply. Distribution runs through direct sales from equipment suppliers to project developers, often supported by engineering, procurement, and construction (EPC) firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The run of river power market presents a fragmentation opportunity, driven by the shift towards decentralized energy generation. Industrial consumers in remote areas are actively seeking localized, reliable power sources, creating distinct niches for project developers.
For Market Incumbents:
Entrench existing market positions by actively modernizing aging assets with high-efficiency turbines and advanced automated controls. This proactive approach mitigates the threat from emerging intermittent renewable sources and strengthens operational resilience. Invest in securing long-term power purchase agreements, particularly with industrial consumers, to stabilize revenue streams against market fluctuations. Prioritize capabilities in navigating complex, site-specific environmental regulations.
For New Entrants and Emerging Players:
Underdeveloped hydropower potential in regions like the Andean countries and Southeast Asia represents a significant entry point for new players. Focus on small and medium-scale projects, leveraging their faster permitting processes and lower ecological disruption. Implement hybrid solutions integrating battery energy storage systems to offer dispatchable power, addressing intermittency concerns. Develop specialized expertise in navigating local regulatory frameworks and securing community buy-in for project siting.
For Investors and Strategic Acquirers:
Secondary-cycle assets often sit with independent power producers seeking to optimize their portfolios of renewable generation. The long-term viability of run of river power is robust, driven by global policy support for decentralized, low-impact renewables. Target technology providers specializing in advanced automated controls or high-efficiency turbine modernization for strategic acquisitions. Growth in long-term power purchase agreements for hybridized run of river facilities serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Modernization of Aging Assets | Upgrading older facilities with high-efficiency turbines increases generation capacity without new greenfield construction and associated permitting. |
| Hybridization with Energy Storage | Integrating battery systems with run of river facilities smooths output, providing grid stabilization services and dispatchable power. |
| Investment in Automated Controls | Advanced digital systems optimize turbine output based on real-time hydrological data, maximizing energy capture and operational efficiency. |
| Secure Long-Term PPAs | Long-term power purchase agreements provide revenue stability, attracting investment for new project development and asset upgrades. |
| Geographic Expansion into Underdeveloped Regions | Targeting Andean countries and Southeast Asia taps into significant untapped hydropower potential and growing energy needs. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings of this analysis. Industry stakeholders, including independent power producers, turbine manufacturers, and environmental regulators, provided critical insights. Secondary sources comprised regulatory filings, government energy policies, and hydrological data. This approach enabled comprehensive bottom-up and top-down triangulation of market dynamics.
Calibration of historical growth patterns against projected policy impacts informed the analytical framework across the analysis window. The model segmented the market by technology, end-user, installation, capacity, and regional regulatory frameworks. Compound Annual Growth Rates were derived from these calibrated historical trends and anticipated future developments. Key forecast inputs included evolving renewable energy directives and regional energy demand projections.
Practitioners should monitor significant shifts in hydrological patterns and evolving environmental regulations for early signals of forecast revision. Forecasts reflect current assumptions regarding policy stability and technological adoption. Quarterly review of climate pattern forecasts and national energy policy updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market