
 Global Hydraulic Door Closer Market | 2026-2036
Global Hydraulic Door Closer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Door Closer Market Outlook
Aluminum alloy castings is shifting toward zinc and composite alternatives in mid-tier hydraulic door closer manufacturing, reducing raw material cost volatility for producers. ASSA ABLOY leverages captive foundry capacity across Scandinavia to sustain margin control on premium concealed units. dormakaba competes through electromechanical integration expertise in automatic door systems for airport and healthcare verticals. GEZE anchors its position with surface-mounted closer specialization in German-speaking commercial construction markets.
A hydraulic door closer is a mechanical device containing a spring-loaded hydraulic fluid chamber that regulates door swing speed through adjustable valve-controlled oil displacement, typically rated for cycles between 500,000 and 2 million operations depending on grade certification. Its primary purpose is ensuring controlled closure for fire containment, accessibility compliance, and security in commercial and institutional buildings. Surface-mounted closers still occupy the largest volume share due to retrofit compatibility and lower installation labor, while electromechanical units represent the fastest-expanding margin pool as smart building integration requirements intensify. The commercial application segment dominates value generation, though institutional retrofits are accelerating as schools and hospitals replace aging hardware to meet updated fire door regulations.
EMA and ECHA frameworks in Europe enforce REACH-compliant fluid formulations and CE-marked fire resistance ratings that determine market access for imported closers. The United States ADA and NFPA 80 standards mandate specific opening-force thresholds and fire-rated performance, directly shaping product specification sheets for domestic and export manufacturers. Stakeholders must monitor evolving interoperability demands between hydraulic closers and building access-control networks as electromechanical adoption accelerates.
Market Dynamics
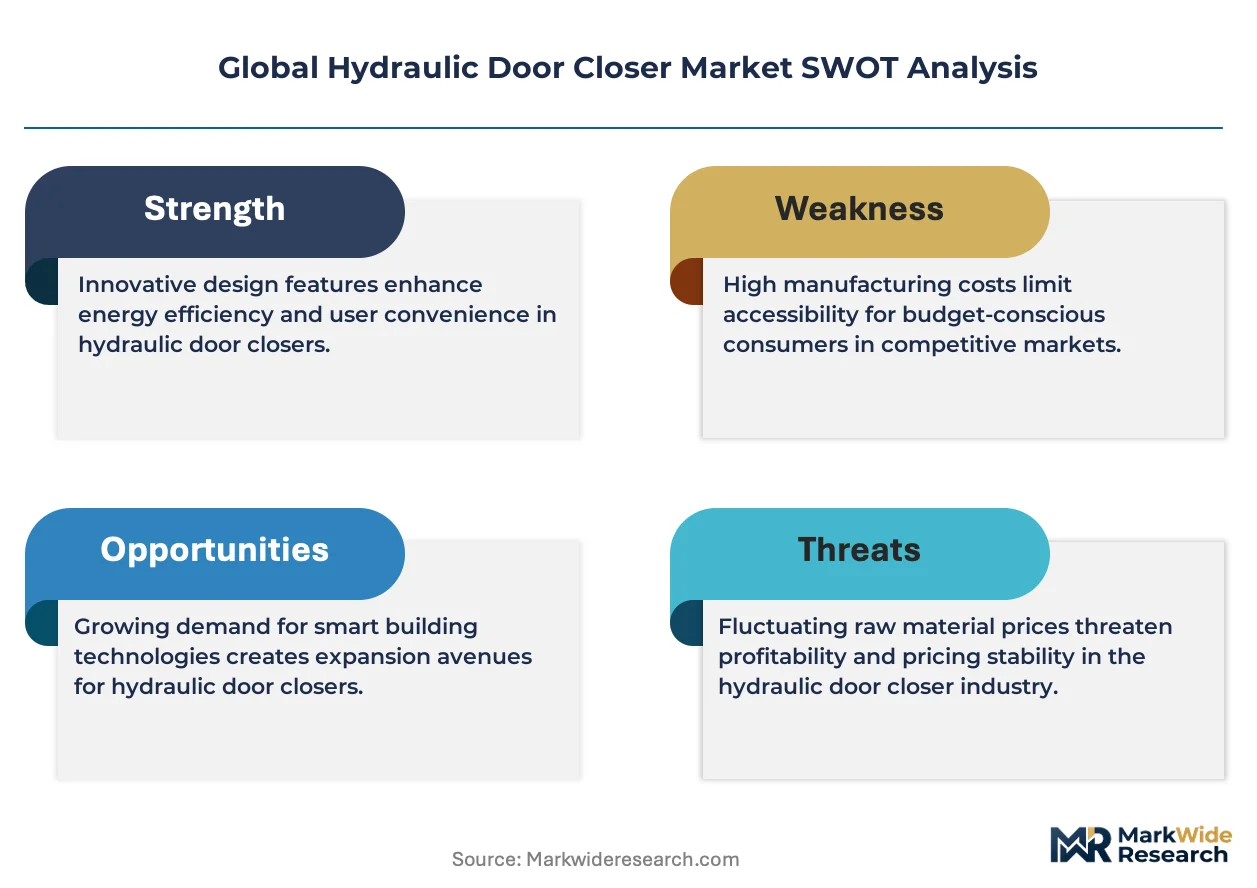
Fire safety certification tightening across multiple jurisdictions is forcing manufacturers to reengineer hydraulic fluid formulations and cycle-testing protocols, compressing product development timelines while elevating compliance costs.
Growth Catalysts
- Commercial real estate retrofit cycles:High-traffic building upgrades in Germany and the United States are accelerating specification of concealed and automatic closers for improved accessibility and fire containment.
- EMA fire safety mandates:Evolving EN standards in Europe are tightening product certification thresholds, creating replacement demand for non-compliant legacy hardware in institutional facilities.
- Urban construction acceleration:China's commercial construction and institutional retrofit programs are compressing procurement cycles for certified door hardware.
Market Restraints
- Raw material substitution costs:Aluminum alloy volatility is pushing mid-tier producers toward zinc and composite alternatives, requiring tooling retooling and qualification delays.
- REACH-compliant fluid scarcity:ECHA framework restrictions on hydraulic oil formulations are limiting supplier pools and extending qualification timelines for European market access.
- Electromechanical substitution pressure:Smart building integration requirements are displacing pure hydraulic units in premium new construction segments.
Strategic Opportunities
- Healthcare vertical penetration:Hospital fire door retrofits present underexploited demand for ADA-compliant low-opening-force closers with antimicrobial surface treatments.
- Airport infrastructure modernization:Automated passenger processing terminals require electromechanical-hybrid closers with access control interoperability.
- Institutional education sector:School safety upgrades driven by NFPA 80 enforcement are creating specification windows for fire-rated hardware replacement programs.
Industry Challenges
- Certification timeline compression:CE marking and UL listing procedures for fire-rated closers are extending from 12 to 18 months due to testing backlog.
- Legacy system integration friction:Electromechanical closer deployment requires coordination with proprietary building management networks, complicating specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Door Closer Market |
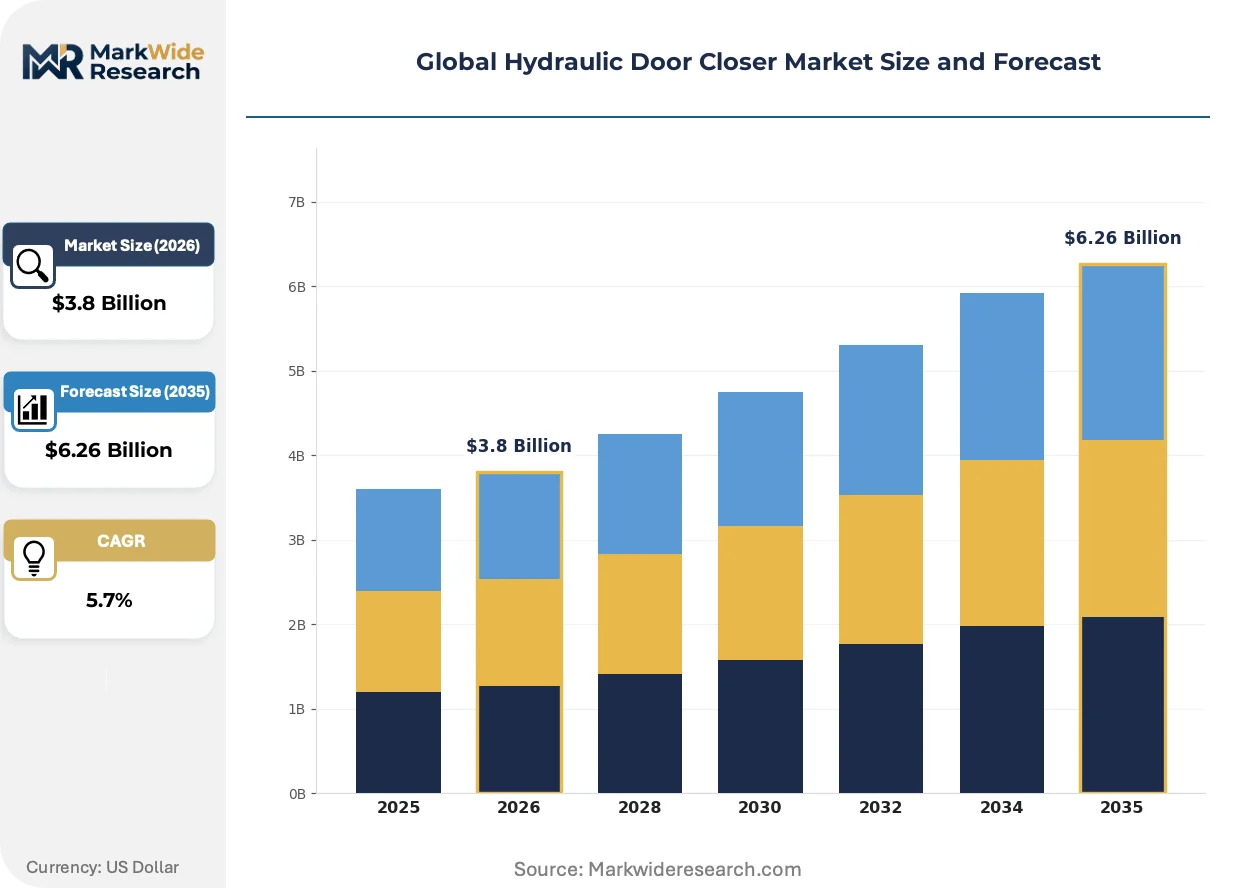
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface-Mounted, Concealed, Automatic, Electromechanical Application: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Renovation, Retrofits, DIY End User: Builders, Contractors, Architects, Homeowners |
| Companies Covered | GEZE, Hager Group, ASSA ABLOY, ISEO, DOM, dormakaba, Gretsch-Unitas, Lawrence Hardware, Allegion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Door Closer Market Strategic Shifts
Electromechanical integration is displacing standalone hydraulic architectures as building automation systems demand real-time door status monitoring and remote force adjustment capabilities.
Sensor-embedded hydraulic closers is converging with IoT building management platforms, enabling predictive maintenance alerts and cycle-count telemetry. Airport and healthcare facility managers are specifying these units for critical fire door applications. This convergence is compressing the traditional hardware procurement cycle into bundled smart building contracts.
REACH fluid formulation restrictions are mandating biodegradable hydraulic oils with equivalent viscosity stability across temperature ranges. European manufacturers are reformulating product lines to maintain CE marking eligibility. German-speaking commercial construction markets are experiencing the most acute specification disruption as EN standards tighten.
Specification authority is migrating from general contractors to specialized fire door consultants, fragmenting traditional distribution channels. Engineering firms now control closer selection for institutional retrofits, displacing hardware distributor influence. This shift is most visible in United States school and hospital renovation projects where ADA and NFPA 80 compliance complexity demands specialist input.
Global Hydraulic Door Closer Market Segmentation
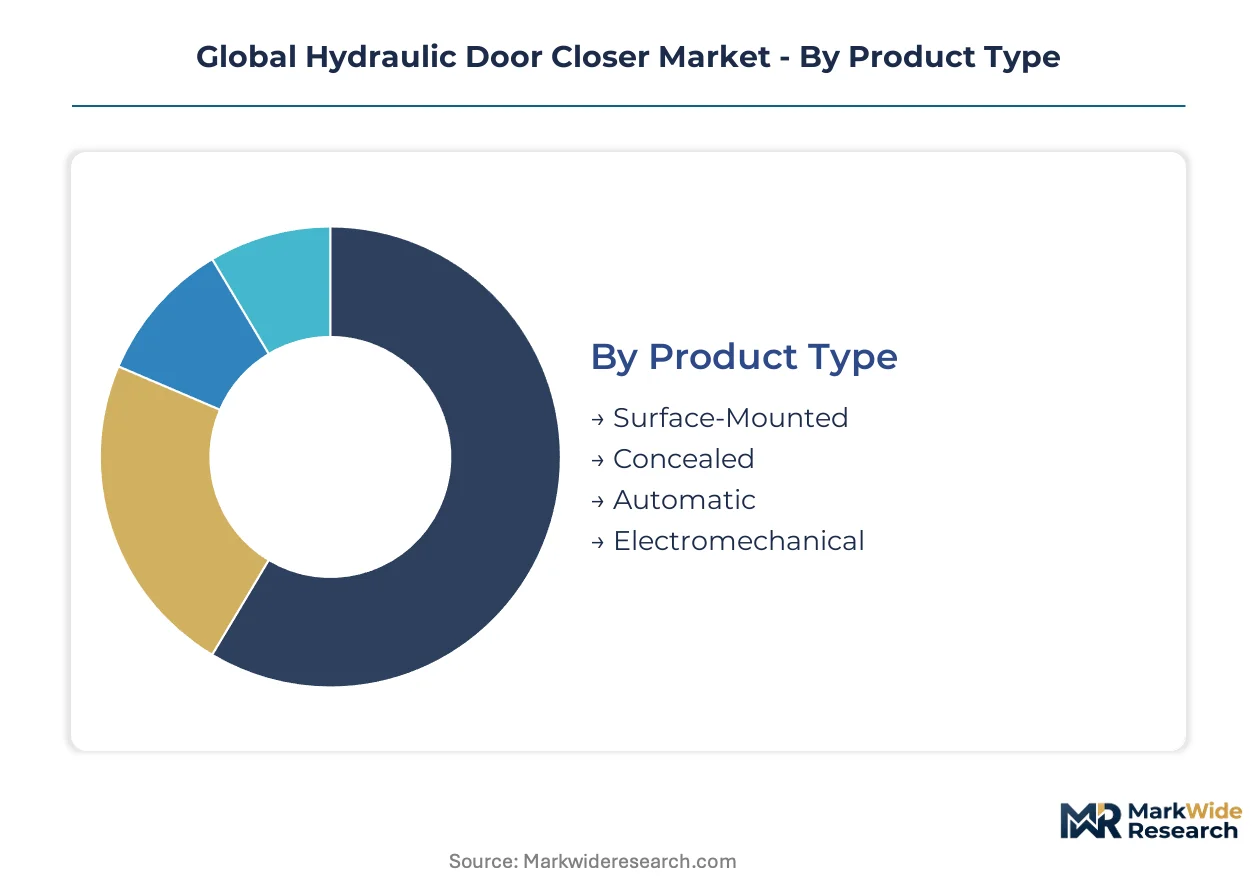
Door closer specification varies sharply across building types, with certification requirements and installation constraints fragmenting procurement patterns. Manufacturers configure fluid formulations, mounting geometries, and cycle ratings to match distinct regulatory and performance thresholds.
Product Type:
Surface-mounted closers carry basic fire resistance ratings under NFPA 80 and EN 1634, while concealed and electromechanical units demand extended CE marking and UL listing protocols that stretch qualification timelines.
- Surface-Mounted:Exposed arm-and-body design with adjustable spring power and hydraulic damping valves. German commercial real estate developers specify these for high-traffic office retrofits where installation speed outweighs aesthetic constraints.
- Concealed:Hidden mechanism embedded within door leaf or frame, requiring precise mortising and fire-rated frame compatibility. United States healthcare facilities are expanding specification for these units to meet ADA low-opening-force mandates without visible hardware.
- Automatic:Pneumatic or hydraulic hold-open with smoke detector release, integrating with building fire alarm systems. Airports in China specify these for passenger boarding bridge applications.
- Electromechanical:Motor-driven closure with position sensing and building management system connectivity. Smart building contracts in Germany bundle these with access control networks.
Leading the category by volume: Surface-Mounted. Expanding most quickly: Electromechanical.
Application:
Cost tier stratification separates premium institutional specifications from economy residential installations, with certification depth determining margin capture.
- Commercial:Office towers, retail centers, and hospitality properties requiring Grade 1 cycle ratings above 1 million operations. United States Class A office renovations are compressing procurement cycles for concealed closers with antimicrobial finishes.
- Institutional:Schools, hospitals, and government facilities subject to NFPA 80 and ADA enforcement. Fire door consultants in the United States control specification for these projects, displacing traditional distributor influence.
- Residential:Single-family and multi-family dwellings with lighter Grade 2 or 3 cycle requirements. DIY channel penetration concentrates in North American big-box retail.
- Industrial:Manufacturing plants and warehousing with corrosion-resistant finishes and extreme temperature fluid formulations. REACH-compliant oil scarcity limits European supplier pools for this segment.
Dominating value generation: Commercial. Steepest expansion trajectory: Institutional.
Installation Type:
Volume concentration favors renovation and retrofit channels where existing frame conditions dictate closer selection over architect preference.
- Renovation:Partial building upgrades with selective hardware replacement. German commercial landlords specify concealed closers during lobby modernization to satisfy updated EN accessibility standards.
- Retrofits:Fire door hardware replacement programs driven by regulatory enforcement. United States school districts are accelerating these projects under tightened NFPA 80 interpretations.
- New Construction:Ground-up development with full specification freedom. Electromechanical integration is displacing pure hydraulic units in premium segments here.
- DIY:Consumer-direct purchase for residential repair and improvement. Surface-mounted units dominate due to minimal tooling requirements.
Capturing highest volume: Renovation. Gaining share fastest: Retrofits.
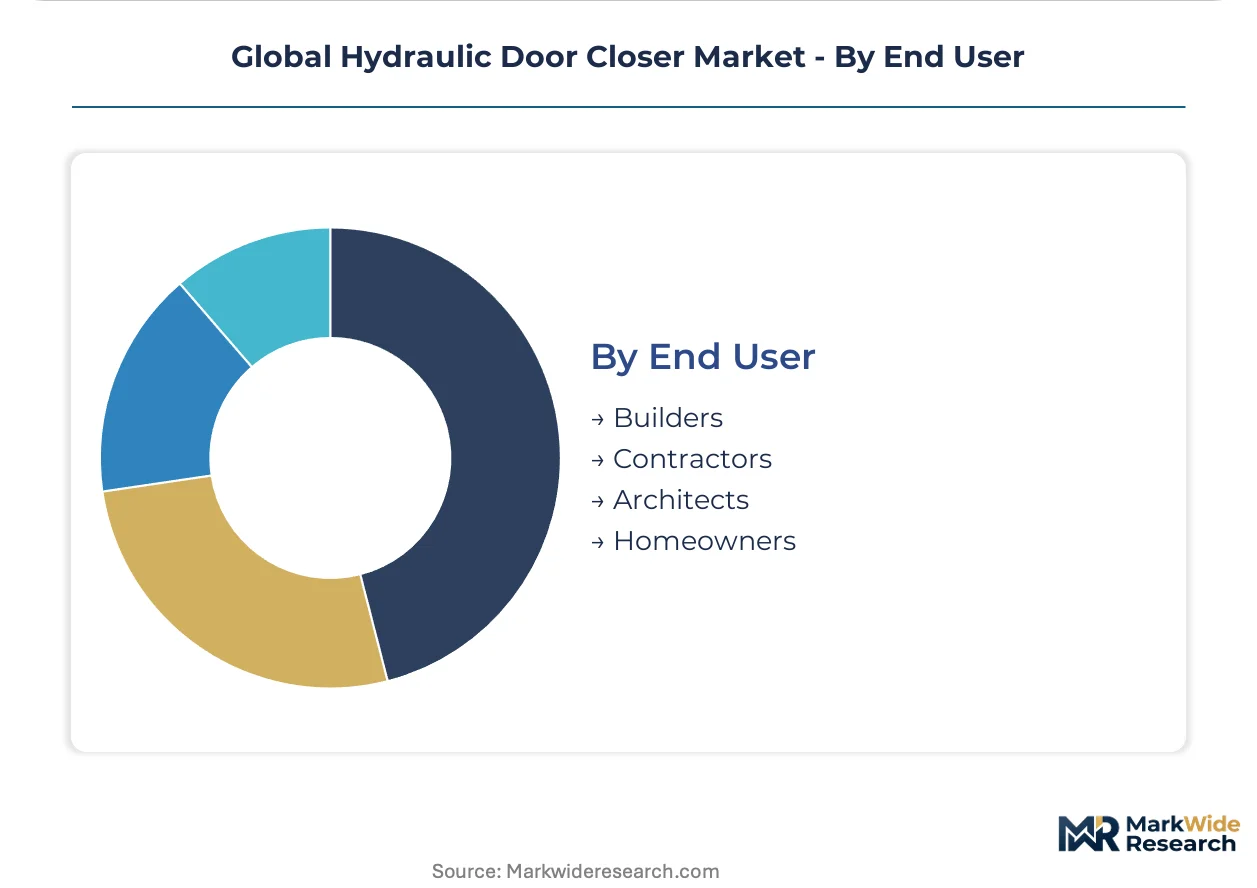
End User:
Specification authority migration is fragmenting traditional distribution, with engineering consultants and fire door specialists displacing contractor-driven selection.
- Architects:Design-phase specification of concealed and aesthetic-integrated closers. German-speaking commercial construction markets show the most acute specification disruption as EN standards tighten.
- Builders:Production home construction with standardized Grade 2 surface-mounted units. Procurement patterns favor volume pricing from captive foundry suppliers.
- Contractors:Installation and replacement execution, increasingly following consultant-specified schedules rather than autonomous selection.
- Homeowners:Reactive replacement demand through retail and e-commerce channels. Price sensitivity limits specification to economy surface-mounted products.
Controlling premium specification: Architects. Scaling volume fastest: Builders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial zones and Chinese special economic districts concentrate hydraulic door closer manufacturing capacity, while regulatory divergence across jurisdictions fragments specification standards. Demand clusters in commercial construction corridors where fire safety mandates and accessibility codes intersect with high-traffic building stock.
United States
Class A office renovations in Manhattan and Chicago accelerate concealed closer procurement for ADA compliance. NFPA 80 enforcement by local fire marshals tightens replacement timelines for aging institutional hardware. Fire door consultants in Boston and Washington D.C. control specification authority, displacing traditional distributor channels.
Germany
Commercial real estate developers in Frankfurt and Munich specify concealed units for lobby modernization under updated EN accessibility standards. EMA and ECHA frameworks enforce REACH-compliant fluid formulations that limit supplier pools. GEZE anchors surface-mounted specialization in German-speaking construction markets through captive technical expertise.
China
Urban commercial construction in Shanghai and Shenzhen compresses procurement cycles for certified door hardware. MIIT and GB standards govern fire resistance ratings for imported closers. Airport infrastructure modernization in Beijing and Guangzhou drives electromechanical-hybrid specification for automated passenger processing terminals.
United Kingdom
Healthcare facility retrofits in London and Birmingham expand demand for ADA-compliant low-opening-force closers. Building Regulations Part B enforcement tightens fire door hardware certification thresholds. Engineering consultants in Manchester and Edinburgh control specification for institutional projects, fragmenting traditional distribution influence.
Japan
Hospital fire door upgrades in Tokyo and Osaka prioritize antimicrobial surface treatments alongside cycle durability. METI and JIS standards shape product qualification protocols for domestic and export manufacturers. Smart building integration requirements in Yokohama and Nagoya accelerate electromechanical adoption over pure hydraulic architectures.
Global Hydraulic Door Closer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium concealed and electromechanical units concentrating among integrated hardware groups while surface-mounted volume disperses across foundry-linked fabricators. Three archetypes dominate: captive-foundry integrated specialists, electromechanical integration experts, and surface-mounted volume producers. Competitive moves center on backward integration into zinc and composite casting capacity, plus qualification acceleration for REACH-compliant fluid formulations.
Among European integrated hardware groups, ASSA ABLOY and dormakaba occupy positions spanning premium concealed and electromechanical segments, while GEZE exemplifies surface-mounted specialization anchored in German-speaking commercial construction markets. These three represent distinct strategic postures: foundry-captive margin control, electromechanical system integration, and regional technical anchoring.
| Leading Market Players |
|---|
| GEZE |
| Hager Group |
| ASSA ABLOY |
| ISEO |
| DOM |
| dormakaba |
| Gretsch-Unitas |
| Lawrence Hardware |
| Allegion |
| Others |
Value Chain & Pricing Dynamics
REACH-compliant fluid formulation mandates in Europe gate qualified supply pools and premium-tier pricing access for hydraulic door closer manufacturers, compressing margins for non-compliant producers while elevating certification-backed pricing power for reformulated product lines. Buyers in German-speaking commercial construction markets now face extended lead times and tiered cost structures as ECHA restrictions limit hydraulic oil supplier options.
Pricing Analysis
Short lead time premiums and spot inventory discounts structure transactional pricing across the hydraulic door closer market, with concealed and electromechanical units commanding substantial uplifts over surface-mounted alternatives due to extended qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates Grade 1 institutional certifications from commercial retrofit grades and residential DIY units. Cost compression in mid-tier segments is intensifying because raw material substitution toward zinc and composite castings requires tooling retooling investments. Institutional buyers in United States healthcare and education verticals exhibit lowest price sensitivity due to NFPA 80 compliance mandates, while residential DIY channels show acute elasticity.
Supply Chain Analysis
CE marking and UL listing qualification gating extends supplier onboarding timelines from 12 to 18 months, concentrating certified manufacturing capacity in Germany, China, and Japan. Raw material inputs draw from aluminum and zinc alloy foundries, REACH-compliant hydraulic fluid blenders, and precision spring manufacturers. Single-source vulnerability runs through European hydraulic oil suppliers restricted by ECHA formulation rules. Distribution runs through fire door consultants and specialized engineering firms for institutional segments, with traditional hardware distributors retaining residential channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA and ECHA fire safety mandates erect barrier-to-entry moats favoring incumbents with captive foundry capacity and established certification portfolios.
For Market Incumbents: Hedge against electromechanical substitution pressure by accelerating backward integration into zinc and composite casting capacity in Germany and China. Secure captive supply of REACH-compliant hydraulic fluid formulations before ECHA restrictions tighten further. Prioritize qualification acceleration for electromechanical-hybrid architectures to defend specification authority in airport and healthcare verticals. For New Entrants and Emerging Players: NFPA 80 enforcement in the United States opens a window for specification-focused entrants targeting school district retrofit programs where fire door consultant influence is displacing traditional distributors. Target institutional education sector replacement cycles in Texas and Florida where compliance deadlines compress procurement timelines. Pursue white-label partnerships with established foundry operators to bypass 18-month certification barriers. For Investors and Strategic Acquirers: Electromechanical closer adoption crossing 15% share in German smart building contracts is the leading indicator that integration-capable hardware groups will command sustained valuation premiums over pure hydraulic specialists. Focus acquisition screening on mid-tier European manufacturers with dormant CE marking portfolios and underutilized foundry capacity. Monitor ECHA hydraulic fluid formulation rulings as the signal for supply-constraint-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Casting | Captive foundry capacity insulates ASSA ABLOY and dormakaba from aluminum alloy volatility in Scandinavian production zones. |
| REACH-Compliant Fluid Reformulation | GEZE's biodegradable hydraulic oil qualification preserves CE marking eligibility across German-speaking commercial construction markets. |
| Electromechanical-Hybrid Development | Sensor-embedded closer architectures capture specification in China airport infrastructure modernization programs. |
| Fire Door Consultant Channel Cultivation | Engineering firm partnerships in United States school retrofits fragment traditional hardware distributor influence. |
| Antimicrobial Surface Treatment Certification | Hospital specification in Japan and United Kingdom demands cycle durability paired with infection control compliance. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fire door consultants, commercial real estate developers, hospital facility managers, and hardware procurement officers at institutional distributors. EMA submission databases, ECHA REACH registration dossiers, NFPA technical committee minutes, and United States import trade data provided cross-validation. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across the analysis window.
Data-stream reconciliation across product type, application, installation channel, and end-user specification authority generated volume and value outputs throughout the forecast period. Segmentation dimensions modeled include surface-mounted versus concealed versus electromechanical architectures, commercial versus institutional versus residential end-use, and renovation versus retrofit versus new construction installation type. CAGRs derived from cycle-count replacement schedules, regulatory enforcement timelines, and smart building integration adoption curves.
The model assumes a particular technology adoption path; alternative pathways for electromechanical-hybrid architectures would alter the outlook if building automation system interoperability standards shift. Forecasts reflect assumptions regarding ECHA hydraulic fluid restriction timelines and NFPA 80 enforcement intensity. A model refresh is warranted upon material change in European fire safety certification protocols or Chinese commercial construction credit conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Europe I-Joist Market