
 Steel Bolts and Nuts Market | 2026-2036
Steel Bolts and Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Bolts and Nuts Market Analytics
Carbon fiber-reinforced polymers is restructuring fastener economics in aerospace subassemblies where weight reduction commands premium pricing. Fastenal Company leverages its branch-based distribution network to control industrial MRO channels across North America. Thyssenkrupp AG anchors European supply through integrated steelmaking and precision forging operations in Germany.
Steel bolts and nuts are threaded mechanical fasteners manufactured from carbon steel, alloy steel, or stainless steel with specified tensile strengths typically ranging from 400 MPa to over 1,000 MPa depending on grade classification; they function to create non-permanent joints between structural components across machinery, infrastructure, and transportation equipment. Hex bolts dominate volume throughput in construction and heavy equipment assembly due to standardized wrench compatibility and established load ratings. Stainless steel grades command premium positioning in marine and chemical processing environments where corrosion resistance extends service intervals. Alloy steel fasteners lead automotive powertrain applications where Grade 8 specifications satisfy torque and fatigue requirements.
ISO 898-1 governs mechanical properties of carbon steel and alloy steel fasteners traded across borders, while REACH restricts hexavalent chromium in coatings and EPA rules shape US galvanizing emissions. China's GB/T 3098 series and SAMR enforcement create parallel compliance obligations for exporters targeting domestic infrastructure projects. Stakeholders must monitor divergence between EU Ecodesign requirements and emerging carbon-border adjustments as these frameworks redefine competitive access for Asian and European producers alike.
Market Dynamics
China's dual carbon goals and tightening GB standards are forcing steel fastener producers to decarbonize smelting operations while maintaining tensile specifications, creating a bifurcation between carbon-compliant and legacy supply chains.
Growth Catalysts
- Electric vehicle assembly expansion:Automotive OEM procurement of high-tensile Grade 8 and 10.9 fasteners is accelerating as EV powertrain architectures demand torque-resistant joint solutions.
- REACH coating restrictions:The EU's hexavalent chromium ban is driving substitution toward zinc-nickel and organic coating systems that extend marine service intervals.
- Stuttgart-Wolfsburg supplier cluster:Germany's automotive engineering concentration sustains premium demand for precision-forged alloy fasteners with documented fatigue resistance.
Market Restraints
- Scrap steel price volatility:Electric arc furnace feedstock costs fluctuate with construction demolition cycles, compressing margin predictability for mid-tier bolt producers.
- Hebei Province supply concentration:China's carbon steel fastener output clusters in a single industrial corridor, exposing buyers to coordinated environmental shutdowns.
- Carbon fiber-reinforced polymer substitution:Aerospace subassemblies above 150°C service thresholds increasingly specify bonded composites over mechanical fastening.
Strategic Opportunities
- India infrastructure build-out:National highway and railway electrification projects under BIS certification mandates are opening specification-grade fastener procurement at scale.
- EU carbon border adjustment mechanism:CBAM phase-in creates first-mover advantage for European mills with verified Scope 3 emissions data on alloy steel inputs.
- Additive manufacturing convergence:Directed energy deposition of 17-4 PH stainless steel is enabling on-demand production of obsolete fastener geometries for MRO channels.
Industry Challenges
- Heat treatment technician scarcity:Austempering and martempering process expertise is retiring faster than vocational programs replenish qualified furnace operators.
- ISO 898-1 certification timelines:Third-party mechanical testing for Grade 12.9 qualification extends 14-18 weeks, delaying automotive platform approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Bolts and Nuts Market |
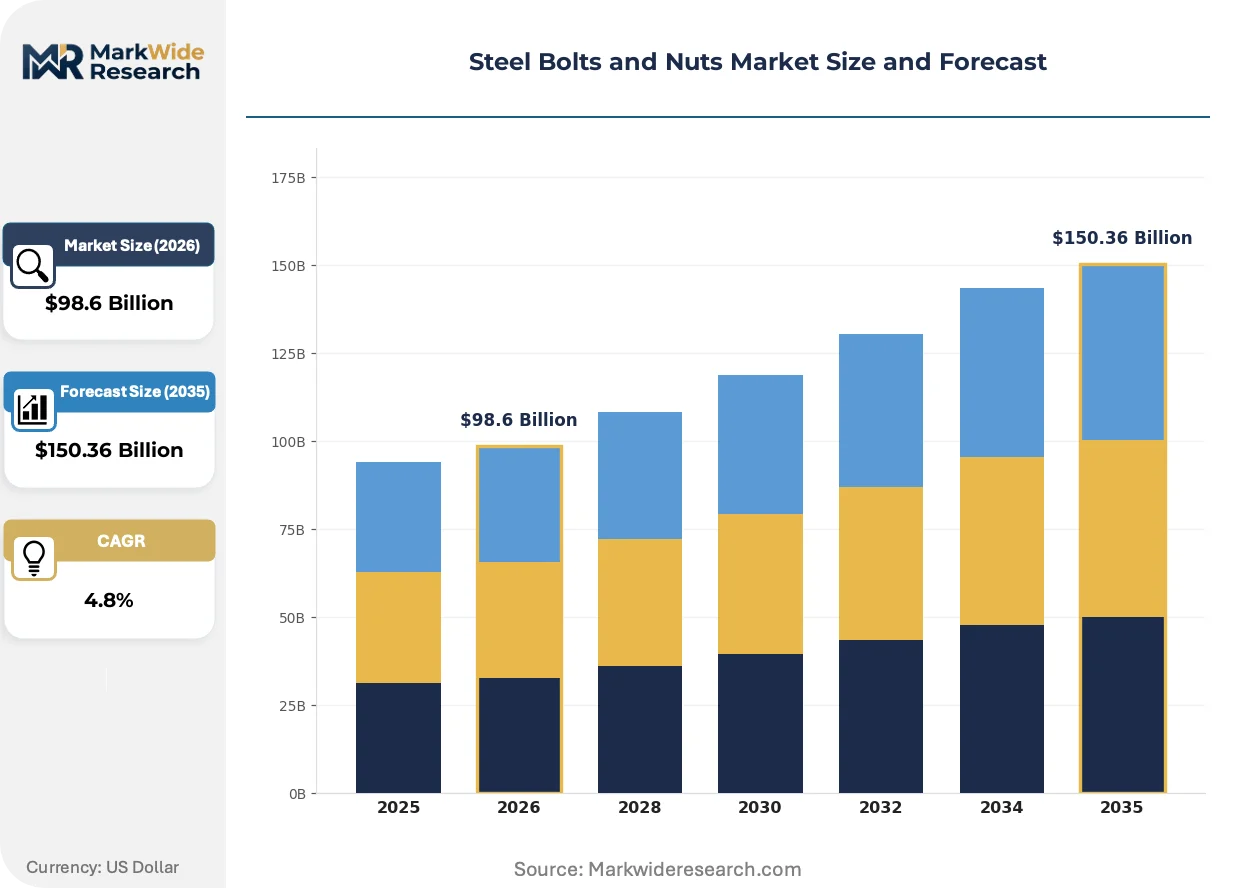
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $150.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hex Bolts, Carriage Bolts, Eye Bolts, Lag Bolts Material Grade: Grade 8, Grade 5, Stainless Steel, Alloy Steel End User: Construction, Automotive, Aerospace, Industrial Coating Type: Zinc Plated, Hot Dip Galvanized, Black Oxide, Nylon Coated |
| Companies Covered | Illinois Tool Works Inc., Stanley Black & Decker, Inc., Fastenal Company, Nucor Corporation, Thyssenkrupp AG, Arconic Corporation, Hilti Corporation, Adolf Würth GmbH & Co. KG, Bulten AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Bolts and Nuts Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to redefine surface engineering and procurement economics across structural fastening applications.
Hot-dip galvanized coating technology is absorbing incremental zinc-aluminum-magnesium alloy formulations that extend salt-spray resistance beyond 1,000 hours. Offshore wind foundation contractors in the North Sea are specifying these formulations for monopile bolted connections exposed to tidal zones. The technology is absorbing market share from conventional pure-zinc galvanizing in marine infrastructure specifications.
REACH Annex XVII restrictions on hexavalent chromium conversion coatings are compelling fastener finishers to adopt trivalent chromium and silane-based pretreatments. Surface treatment lines in Italy and Spain are retooling passivation baths to maintain export eligibility into German automotive supply chains. Stainless steel fastener categories with inherent corrosion resistance are capturing specification preference where coating compliance adds cost complexity.
Automotive OEMs are consolidating supplier panels for powertrain fasteners, reducing approved vendor lists from twelve to four qualified sources per platform. Tier-1 module assemblers in Mexico and Eastern Europe are absorbing the consolidation pressure through long-term volume commitments with indexed steel surcharges. This concentration is most visible in battery tray assembly operations where single-source accountability for torque specification compliance is becoming mandatory.
Steel Bolts and Nuts Market Segmentation
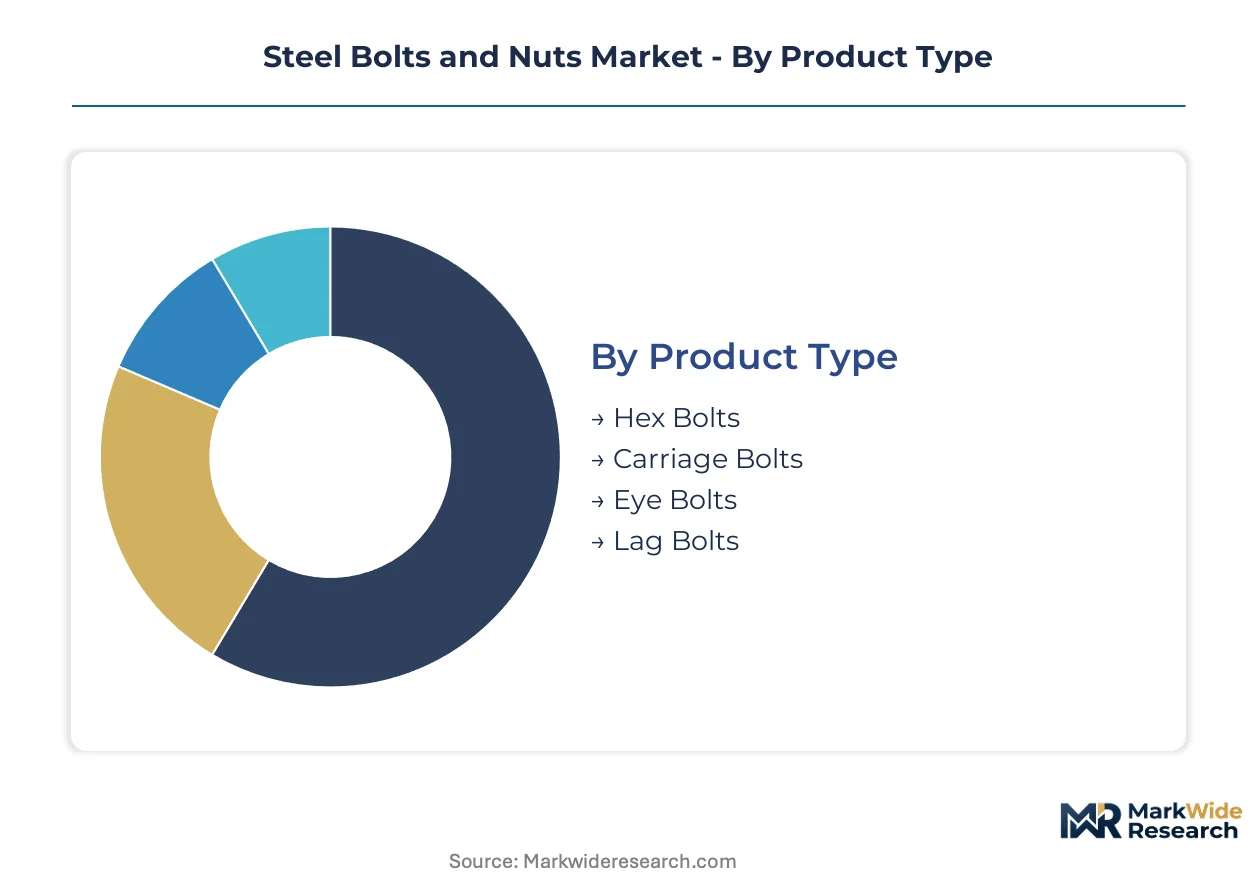
Fastener procurement patterns diverge sharply across end-use applications, with torque specifications, corrosion exposure, and regulatory chemistry driving distinct sourcing behaviors. Material grade selection directly determines heat treatment protocols and coating compliance obligations.
Product Type:
Application torque requirements and installation access constraints separate buyers in this category.
- Hex Bolts:Six-sided head geometry permits standardized wrench engagement across construction and heavy equipment assembly. Demand concentrates in German automotive supplier clusters around Stuttgart and Wolfsburg where documented fatigue resistance supports platform approvals.
- Carriage Bolts:Rounded head with square neck prevents rotation during tightening in wood and structural steel applications. North American railroad infrastructure projects specify these for tie-plate fastening where vibration resistance extends maintenance intervals.
- Eye Bolts:Threaded shank with looped head enables lifting and rigging attachment points.
- Lag Bolts:Coarse wood-thread design provides structural timber connection without pre-drilling requirements.
Volume sits with Hex Bolts; growth tilts toward Eye Bolts as offshore wind installation expands.
Material Grade:
Cost tier positioning and certification complexity stratify procurement panels in this dimension.
- Grade 8:Medium-carbon alloy steel heat-treated to 150 ksi tensile strength satisfies automotive powertrain torque specifications. EV battery tray assemblers in Mexico and Eastern Europe are consolidating approved vendor lists around qualified Grade 8 sources with indexed steel surcharges.
- Stainless Steel:Austenitic and martensitic compositions deliver inherent corrosion resistance without coating compliance burden. Marine infrastructure contractors in the North Sea specify 316-grade fasteners for tidal zone exposure where salt-spray resistance exceeds 1,000 hours.
- Grade 5:Lower tensile rating serves general construction and machinery assembly where cost sensitivity dominates.
- Alloy Steel:Custom chemistry blends address specialized fatigue and temperature requirements.
Volume sits with Grade 5; expansion concentrates in Grade 8 as EV platform approvals accelerate.
End User:
Regulatory exposure and specification documentation intensity separate buyers across these verticals.
- Automotive:OEM powertrain and chassis applications demand ISO 898-1 certification with 14-18 week third-party mechanical testing timelines. Tier-1 module assemblers absorb consolidation pressure through long-term volume commitments tied to torque specification compliance.
- Construction:Structural steel erection and infrastructure projects drive high-volume throughput of standardized fastener geometries. India's national highway and railway electrification build-out under BIS certification mandates is opening specification-grade procurement at scale.
- Aerospace:Weight-critical subassemblies above 150°C service thresholds face carbon fiber-reinforced polymer substitution pressure.
- Industrial:MRO channel demand runs through branch-based distribution networks with on-demand availability requirements.
Volume sits with Construction; expansion concentrates in Automotive as EV assembly scales.
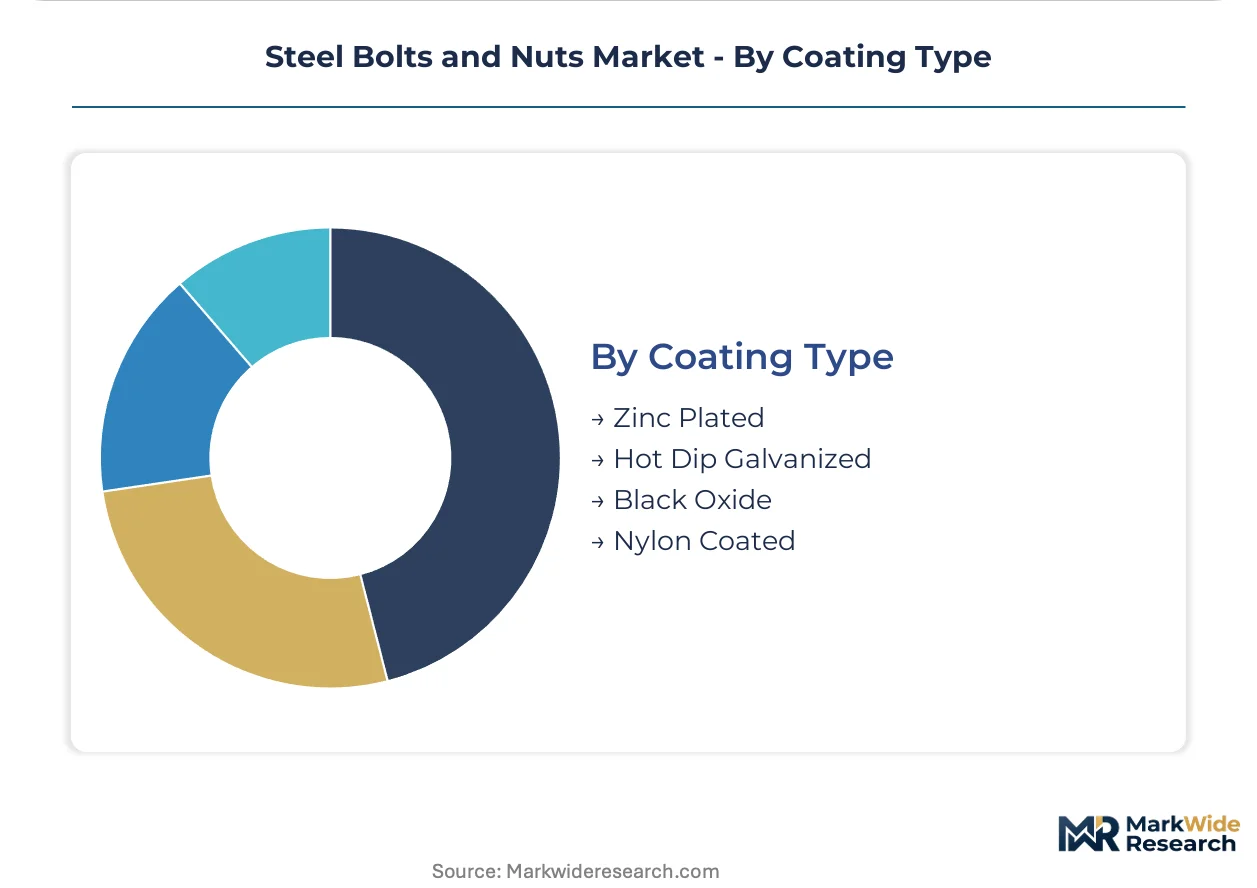
Coating Type:
REACH chemistry restrictions and service environment severity dictate surface engineering choices.
- Hot Dip Galvanized:Zinc-aluminum-magnesium alloy formulations extend salt-spray resistance beyond 1,000 hours for offshore wind monopile connections. North Sea foundation contractors specify these formulations for tidal zone exposure where coating integrity determines service intervals.
- Zinc Plated:Electrodeposited pure zinc with trivalent chromium passivation maintains EU export eligibility under REACH Annex XVII hexavalent chromium bans. Italian and Spanish surface treatment lines are retooling passivation baths to preserve German automotive supply chain access.
- Black Oxide:Conversion coating provides cosmetic finish with minimal corrosion protection for interior applications.
- Nylon Coated:Polymer barrier delivers thread-locking and chemical resistance in specialized industrial environments.
Volume sits with Zinc Plated; expansion concentrates in Hot Dip Galvanized as marine infrastructure accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for steel bolts and nuts concentrates in automotive manufacturing corridors and infrastructure build-out zones across five major economies. Each geography presents distinct regulatory pressures and supply chain configurations that shape procurement patterns for specification-grade fasteners.
China
Hebei Province's carbon steel fastener corridor supplies construction and machinery assembly worldwide. GB/T 3098 series standards and SAMR enforcement create parallel compliance tracks for domestic versus export-bound production. Dual carbon goals are forcing smelting operations to decarbonize while maintaining tensile specifications above 1,000 MPa for automotive applications.
Germany
Stuttgart and Wolfsburg anchor European demand for precision-forged alloy fasteners with documented fatigue resistance. KBA oversight of automotive component certification extends testing timelines for Grade 12.9 qualification. Surface treatment lines in Bavaria and Baden-Württemberg are retooling passivation baths to maintain REACH Annex XVII compliance for hexavalent chromium bans.
United States
EPA rules on galvanizing emissions shape coating technology choices for infrastructure fasteners. Branch-based distribution networks control industrial MRO channels across the Midwest and Southeast manufacturing belts. Electric arc furnace feedstock costs fluctuate with construction demolition cycles, compressing margin predictability for mid-tier bolt producers serving the Texas and California markets.
India
National highway and railway electrification projects under BIS certification mandates are opening specification-grade procurement at scale. Maharashtra and Gujarat host the primary fastener manufacturing clusters serving domestic infrastructure build-out. CDSCO-aligned quality protocols for certain coated fastener applications in medical-adjacent industrial equipment add certification complexity for exporters.
Japan
METI industrial standards govern precision fastener specifications for automotive and machinery exports. JIS-certified producers concentrate in Aichi Prefecture's automotive supplier belt and Osaka's machinery manufacturing corridor. Aging heat treatment technician expertise is retiring faster than vocational programs replenish qualified furnace operators for martempering processes.
Steel Bolts and Nuts Market Competitive Landscape
Automotive OEM supplier panel consolidation dominates the current landscape as approved vendor lists compress from twelve to four qualified sources per platform. The market structure tilts toward tiered concentration: integrated steelmakers with captive forging capacity, specialized precision fastener fabricators, and branch-based distributors controlling MRO channels. Three archetypes define positioning: carbon-compliant European mills with verified Scope 3 data, scale-driven Asian producers serving construction volume, and premium-tier specialists documenting fatigue resistance for automotive platform approvals. Competitive moves center on long-term volume commitments with indexed steel surcharges and geographic expansion into Mexico and Eastern Europe battery tray assembly zones.
Among North American distributors, Fastenal Company exemplifies the branch-based MRO control archetype through its localized inventory network. Integrated European producers are represented by Thyssenkrupp AG, which anchors supply through steelmaking and forging operations. On the precision fabrication tier, Illinois Tool Works Inc. and Stanley Black & Decker, Inc. occupy positions serving specification-grade automotive and industrial assembly requirements. These three entities collectively illustrate the geographic and functional segmentation governing competitive access.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| Stanley Black & Decker, Inc. |
| Fastenal Company |
| Nucor Corporation |
| Thyssenkrupp AG |
| Arconic Corporation |
| Hilti Corporation |
| Adolf Würth GmbH & Co. KG |
| Bulten AB |
| Others |
Value Network & Pricing Analysis
Heat treatment technician scarcity in Japan's Aichi Prefecture widens labor-cost differentials between precision-forged automotive fasteners and commodity-grade construction bolts, compressing margin spreads at the mid-tier as furnace operator wages escalate faster than automated line efficiencies.
Pricing Analysis
Volume concentrates in Grade 5 construction fasteners where per-unit margins compress under scrap steel cost volatility, while premium tiers anchored in Grade 8 and 12.9 automotive specifications sustain pricing power through ISO 898-1 certification barriers and 14-18 week third-party testing timelines. Price differentiation hinges on fatigue documentation intensity and REACH Annex XVII coating compliance, with German automotive OEMs least sensitive due to platform approval lock-in and Indian infrastructure contractors most exposed to spot-market fluctuations. Pricing pressure stems from electric arc furnace feedstock cycles eroding predictability for mid-tier producers serving Texas and California markets.
Supply Chain Analysis
Certification gating through KBA oversight and SAMR enforcement fragments qualified supplier pools, with production gravity in China's Hebei Province, Germany's Stuttgart-Wolfsburg corridor, and India's Maharashtra-Gujarat clusters. Raw material dependencies center on electric arc furnace scrap steel, zinc-aluminum-magnesium alloy coatings, and 17-4 PH stainless steel powder for additive MRO applications. Single-source vulnerability concentrates in Hebei's environmental shutdown exposure, while distribution runs through Fastenal's branch network for North American MRO and Thyssenkrupp's integrated mill-direct channels for European automotive.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as players pursue captive heat treatment capacity to secure furnace operator expertise and compress ISO 898-1 certification timelines.
For Market Incumbents: Acquire qualified heat treatment facilities in Germany's Baden-Württemberg region to lock in martempering process expertise before technician retirements accelerate. Consolidate coating line investments in Italy and Spain to preserve REACH Annex XVII compliance for German automotive supply chain access. Carbon fiber-reinforced polymer substitution in aerospace above 150°C thresholds demands defensive positioning through alloy steel fatigue documentation investments. For New Entrants and Emerging Players: Launch via additive manufacturing service bureaus targeting obsolete fastener geometries for North American MRO channels where Fastenal's inventory gaps create white space. Target India's BIS-certified highway and railway electrification procurement under national infrastructure build-out mandates. Penetrate through directed energy deposition partnerships with offshore wind contractors specifying 17-4 PH stainless steel for monopile connection geometries. For Investors and Strategic Acquirers: Re-rating potential sits with European mills possessing verified Scope 3 emissions data given EU carbon border adjustment mechanism phase-in creating first-mover advantage. Long-term viability favors carbon-compliant producers with integrated steelmaking and precision forging over legacy Hebei-based commodity exporters. Watch CBAM implementation stringency as the inflection signal for competitive access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive martempering capacity locks in scarce technician expertise before Aichi Prefecture retirements peak. |
| Coating Line Retooling for REACH Compliance | Trivalent chromium passivation investments preserve German automotive supply chain eligibility under Annex XVII. |
| Additive Manufacturing Service Bureau Launch | Directed energy deposition of 17-4 PH stainless steel addresses obsolete geometry demand in MRO channels. |
| Scope 3 Emissions Verification Program | Documented alloy steel input carbon intensity secures CBAM-phase competitive positioning for European mills. |
| Long-term Volume Commitment with Steel Surcharge Indexing | Tier-1 battery tray assemblers in Mexico and Eastern Europe absorb OEM consolidation pressure through indexed contracts. |
Research Methodology
Multi-period observation of automotive OEM supplier panel compressions, REACH Annex XVII coating line retooling rates, and Hebei Province environmental shutdown frequencies anchored the trend analysis, supplemented by interviews with heat treatment facility operators, Tier-1 battery tray procurement managers, offshore wind foundation contractors, and North American MRO distribution branch managers. Secondary validation drew from KBA certification timelines, SAMR enforcement disclosures, BIS procurement mandates, EPA galvanizing emission filings, and customs trade data for carbon steel fastener flows. Bottom-up segment sizing triangulated against top-down steel consumption models.
Segment-weighting across material grade, product geometry, end-use vertical, and coating chemistry drove the analytical framework over the projection horizon. CAGRs derived from regression of historical procurement intensity against EV platform ramp schedules, infrastructure build-out commitments, and marine wind installation pipelines. Modeled inputs incorporated heat treatment capacity utilization rates, scrap steel price elasticity, and certification timeline bottlenecks for Grade 12.9 qualification.
Environmental policy stringency in Hebei, REACH chemistry restriction expansion, and carbon border adjustment implementation pace are the dominant revision risks warranting forecast reassessment. A model refresh is warranted upon material change in EU CBAM phase-in timelines or KBA certification protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market