
 Intelligent Building Automation Technologies Market | 2026-2036
Intelligent Building Automation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Building Automation Technologies Market Analytics
Market Context
European system integrators is shifting toward software-defined building stacks that unify formerly siloed mechanical and electrical infrastructure. Honeywell leverages its captive portfolio of sensors and controllers to dominate North American airport and hospital verticals. Siemens sustains technology leadership in digital twin integration for district-scale energy networks. Schneider Electric anchors its position through backward integration into power distribution hardware that feeds directly into its EcoStruxure platform.
Technical Definition and Segment Structure
Intelligent building automation technologies encompass sensor networks, programmable logic controllers, and edge computing nodes that modulate HVAC setpoints, lighting intensity, and access protocols based on real-time occupancy and weather data, typically operating through BACnet or Modbus communication standards with sub-second response latencies. HVAC Controls and Energy Management Systems capture the deepest margin pools as utility-linked demand response programs expand, while IoT Solutions and Cloud-Based Platforms represent the fastest-expanding technology layers as facility managers shift from on-premise servers to subscription-based remote monitoring. Commercial Buildings remain the dominant application category, though Industrial Facilities are gaining traction as manufacturers embed building automation into broader operational technology stacks.
Regulatory Framework and Outlook
The EU Green Deal, F-Gas Regulation, and EPC recast directives are collectively mandating minimum automation depth for buildings above specified floor areas, effectively creating compliance-driven replacement cycles across existing stock. In the United States, ASHRAE Standard 90.1 and city-level benchmarking ordinances in New York and San Francisco impose disclosure requirements that favor instrumented buildings. Stakeholders must monitor how emerging grid-interactive efficient building standards reshape procurement criteria for controls vendors and systems integrators alike.
Market Dynamics
The convergence of EU Green Deal mandates with utility-scale demand response programs is forcing asset owners to replace legacy pneumatic controls with networked digital infrastructure. This regulatory-technology squeeze is compressing replacement cycles and redrawing competitive boundaries between hardware incumbents and software entrants.
Growth Catalysts
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon quota system accelerates HVAC equipment replacement, creating captive demand for compatible automation controllers and refrigerant monitoring sensors.
- Grid-interactive efficient building standards:ASHRAE 90.1-2022 and emerging IEEE 2030.5 protocols enable automated load curtailment contracts that monetize building flexibility for commercial real estate portfolios.
- Retrofit intensity in Germany:The federal Building Energy Act mandates automation depth for buildings exceeding specific floor thresholds, concentrating replacement demand in Frankfurt and Munich commercial districts.
Market Restraints
- Semiconductor input volatility:PLC and edge controller production remains exposed to foundry capacity constraints in Taiwan, creating 12-18 week lead time variability for BACnet-compatible processors.
- Skills concentration in systems integration:Certified commissioning engineers for district-scale BMS deployment cluster in the Netherlands and northern Italy, limiting rollout velocity elsewhere.
- Legacy pneumatic infrastructure:Existing compressed air-based control systems in 1970s-era commercial stock require full-gut renovation rather than overlay retrofit, inflating project economics.
Strategic Opportunities
- Industrial facility convergence:Manufacturing plants are embedding building automation into operational technology stacks, creating unified control layers for HVAC, compressed air, and process cooling.
- Subscription-based remote monitoring:Facility management outsourcing firms in France are adopting cloud-native platforms that displace on-premise server infrastructure and recurring maintenance contracts.
- Netherlands district heating integration:Fourth-generation low-temperature networks require bidirectional automation between building substations and municipal heat pumps, opening controls procurement for housing associations.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 compliance for building automation products requires 14-18 month validation cycles that delay product launches and freeze development roadmaps.
- Interoperability fragmentation:BACnet, Modbus, and emerging MQTT protocols create integration complexity for multi-vendor deployments, inflating commissioning costs and post-warranty support burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Building Automation Technologies Market |
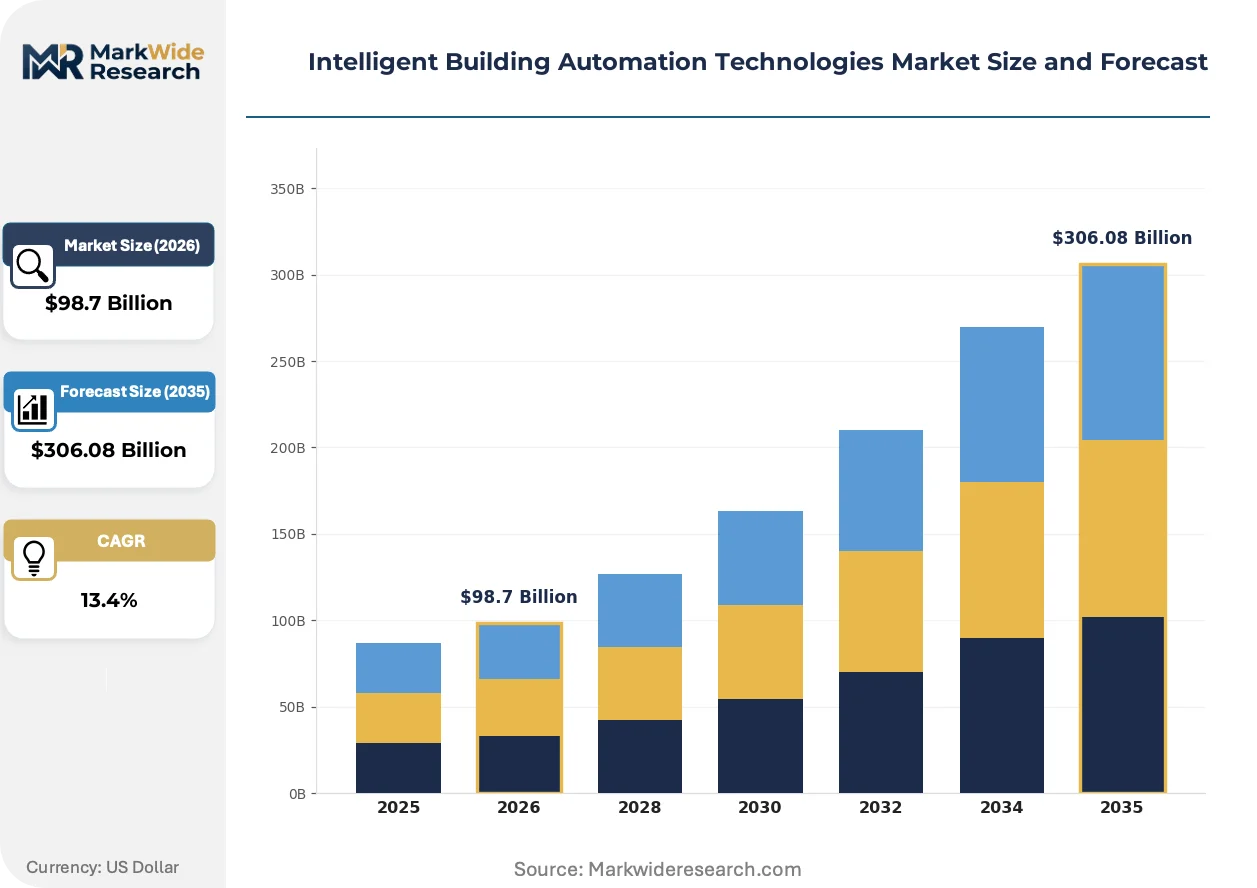
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $306.08 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control Systems, HVAC Controls, Security Systems, Energy Management Systems Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Educational Institutions Technology: Wireless Technologies, Wired Technologies, IoT Solutions, Cloud-Based Platforms End User: Facility Managers, Building Owners, Contractors, Developers |
| Companies Covered | Honeywell, IBM, Johnson Controls, Legrand, Hitachi, Siemens, ABB, Distech Controls, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Building Automation Technologies Market Evolving Landscape
Software-defined control architectures are displacing proprietary hardware stacks, enabling third-party applications to modulate building systems through standardized APIs. This shift is compressing margins for traditional controller manufacturers while opening recurring revenue pools for platform operators.
Digital twin technology is electrifying how district-scale energy networks are commissioned and operated. Siemens and municipal utilities in Copenhagen deploy physics-based building models that predict thermal response to weather and occupancy, reducing commissioning time by eliminating physical trial-and-error tuning. These virtual replicas compress payback periods for deep retrofit projects and enable predictive maintenance contracts that displace break-fix service models.
The EU F-Gas Regulation and its national implementing acts are mandating refrigerant leak detection and automated shutdown for commercial cooling systems above specified charge thresholds. This policy architecture forces asset owners to install connected sensors and edge controllers that were previously optional, creating compliance-driven demand for IoT-enabled HVAC infrastructure. German facility managers face 2027 deadlines that concentrate procurement decisions in 2025-2026 budget cycles.
Third-party energy service companies are capturing building controls procurement from traditional mechanical contractors. French and Dutch commercial real estate owners now contract directly with specialized integrators for performance-guaranteed efficiency retrofits, unbundling controls specification from general construction procurement. This channel shift elevates software capabilities over hardware relationships in vendor selection criteria.
Intelligent Building Automation Technologies Market Segmentation
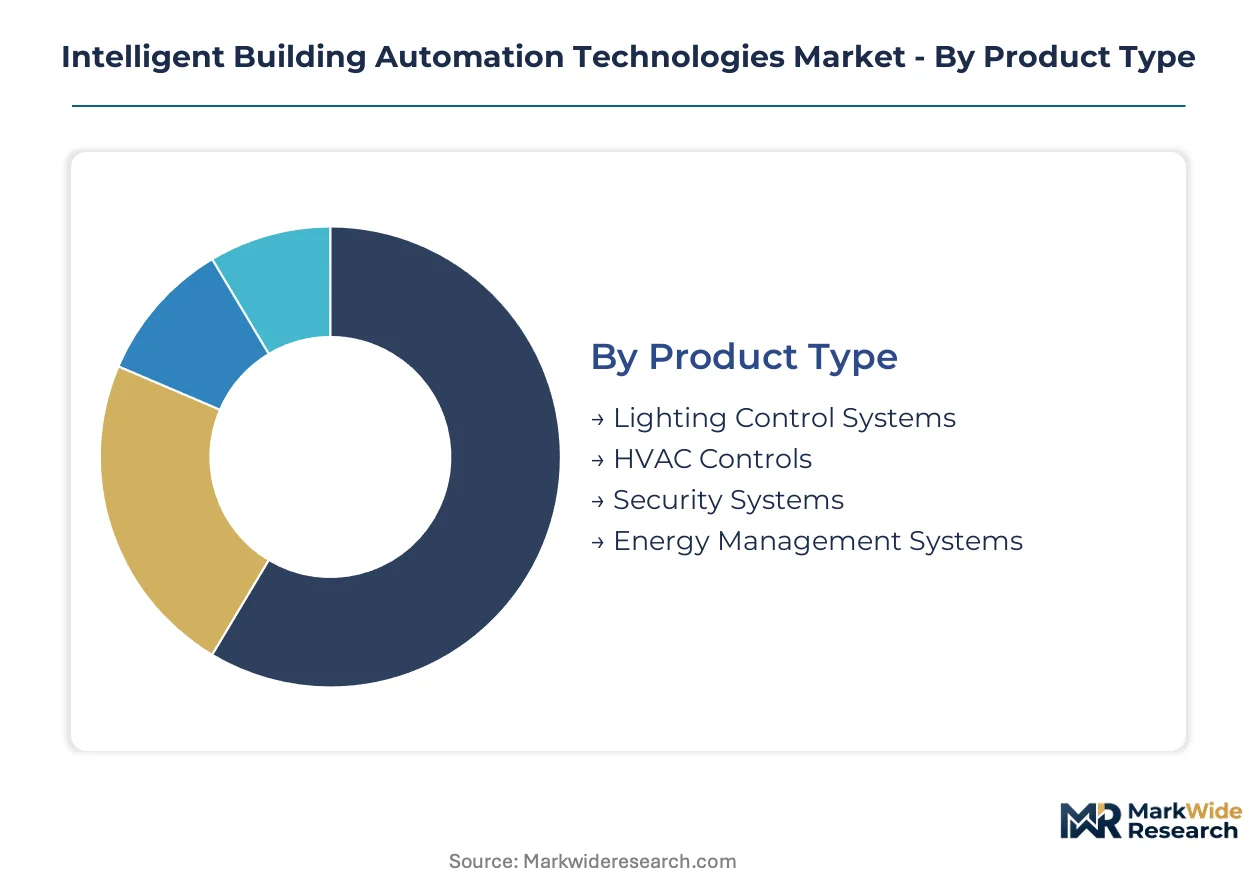
Segmentation in intelligent building automation reveals how regulatory mandates and procurement authority concentrate demand across distinct technology layers and buyer types. Understanding these divisions exposes where compliance burdens fall heaviest and which customer relationships determine contract value.
Product Type:
IEC 62443 cybersecurity certification imposes 14-18 month validation cycles on programmable controllers and networked sensors, with HVAC and energy management products facing the strictest functional safety requirements under EU machinery directives.
- HVAC Controls:Programmable logic controllers and edge nodes modulate refrigerant flow, damper positions, and fan speeds through BACnet or Modbus protocols with sub-second latency. German commercial districts under the federal Building Energy Act mandate automation depth for buildings above specified floor thresholds, concentrating replacement demand in Frankfurt and Munich.
- Energy Management Systems:Software platforms aggregate meter data, weather feeds, and occupancy signals to optimize load scheduling and enable utility-linked demand response participation. ASHRAE 90.1-2022 and emerging IEEE 2030.5 protocols in the United States enable automated curtailment contracts that monetize building flexibility for commercial real estate portfolios.
- Lighting Control Systems:Daylight harvesting and occupancy-based dimming systems using DALI or wireless protocols.
- Security Systems:Integrated access control and surveillance with biometric authentication and video analytics at entry points.
HVAC Controls sits at the top of the volume ranking, with Energy Management Systems climbing the fastest.
Application:
Project economics vary sharply by building vintage and use intensity, with 1970s-era commercial stock requiring full-gut renovation rather than overlay retrofit.
- Commercial Buildings:Office towers, retail centers, and hospitality properties deploy integrated BMS platforms unifying HVAC, lighting, and access systems. French and Dutch commercial real estate owners contract directly with specialized integrators for performance-guaranteed efficiency retrofits, unbundling controls specification from general construction procurement.
- Industrial Facilities:Manufacturing plants embed building automation into operational technology stacks, creating unified control layers for HVAC, compressed air, and process cooling. Semiconductor foundries and automotive assembly plants in Germany drive convergence demand as they integrate environmental controls with production systems.
- Residential Buildings:Multi-family housing associations in the Netherlands procure bidirectional automation for fourth-generation district heating substations.
- Educational Institutions:University campuses and K-12 districts prioritize deferred maintenance avoidance through predictive analytics on mechanical equipment.
Commercial Buildings dominates current installed base, with Industrial Facilities expanding most quickly as OT-IT convergence accelerates.
Technology:
Communication protocol selection determines integration complexity and cybersecurity exposure, with wireless and cloud deployments facing heightened scrutiny under IEC 62443 standards.
- Cloud-Based Platforms:Subscription-native architectures displace on-premise server infrastructure, enabling remote monitoring and predictive maintenance contracts. Facility management outsourcing firms in France adopt these platforms to eliminate recurring maintenance obligations and enable centralized portfolio oversight.
- IoT Solutions:Sensor networks and edge controllers with cellular or LoRaWAN backhaul support refrigerant leak detection mandated by EU F-Gas Regulation. German facility managers face compliance deadlines that concentrate procurement decisions in upcoming budget cycles.
- Wireless Technologies:Zigbee, Z-Wave, and Wi-Fi 6 deployments reduce installation labor in retrofit applications.
- Wired Technologies:Ethernet/IP and RS-485-based fieldbus systems persist in security-critical and high-interference environments.
Wired Technologies retains the largest installed footprint, though Cloud-Based Platforms are gaining share fastest as procurement shifts toward operational expenditure models.
End User:
Decision-making authority and technical sophistication vary dramatically across buyer types, with facility managers controlling operational budgets and developers optimizing capital expenditure.
- Facility Managers:Operational stewards with direct accountability for energy costs, occupant complaints, and regulatory compliance. Netherlands housing associations delegate controls procurement for district heating integration to this cohort, creating concentrated demand for bidirectional substation automation.
- Building Owners:Asset holders with portfolio-scale efficiency targets and EPC rating obligations under EU directives. German federal mandates for automation depth in large floor-area buildings drive owner-directed replacement of legacy pneumatic infrastructure.
- Contractors:Mechanical and electrical installation firms specifying controls during new construction and major renovation.
- Developers:Project sponsors pre-certifying buildings to BREEAM or LEED standards to secure tenant premiums and green financing.
Facility Managers represent the most active procurement segment, with Building Owners accelerating fastest as regulatory liability shifts from operational to asset-level accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where building automation technology migrates, as EU F-Gas compliance costs widen the gap between European and Asian production economics. German engineering firms absorb certification burdens through captive vertical integration, while Chinese manufacturers exploit cost-of-compliance gaps in wireless sensor assembly.
United States
Utility-scale demand response programs in Texas and California are accelerating grid-interactive building deployments. ASHRAE 90.1-2022 and city-level benchmarking ordinances in New York and San Francisco impose disclosure requirements that favor instrumented buildings. Silicon Valley data center clusters and Manhattan commercial districts concentrate procurement of cloud-native energy management platforms.
Germany
The federal Building Energy Act mandates automation depth for buildings exceeding specified floor thresholds, concentrating replacement demand in Frankfurt and Munich commercial districts. F-Gas Regulation phase-down timelines force 2027 compliance deadlines that compress procurement into 2025-2026 budget cycles. Bavarian automotive assembly plants and North Rhine-Westphalia chemical complexes drive industrial facility convergence demand.
France
Facility management outsourcing firms in Paris and Lyon are adopting subscription-based remote monitoring platforms that displace on-premise server infrastructure. Third-party energy service companies capture building controls procurement from traditional mechanical contractors through performance-guaranteed efficiency retrofits. Île-de-France commercial real estate owners unbundle controls specification from general construction procurement.
Netherlands
Fourth-generation low-temperature district heating networks require bidirectional automation between building substations and municipal heat pumps. Randstad housing associations procure controls for substation integration, creating concentrated demand for certified commissioning engineers. Amsterdam and Rotterdam retrofit cycles intensify as EU Green Deal mandates tighten energy performance obligations.
China
Dual carbon goals and GB standards for building energy efficiency are accelerating smart city deployments in Yangtze River Delta and Pearl River Delta megaclusters. Domestic manufacturers exploit cost advantages in wireless sensor production while European incumbents face IEC 62443 certification timeline disadvantages. Shanghai and Shenzhen commercial tower construction absorbs software-defined control architectures at scale.
Intelligent Building Automation Technologies Market Competitive Landscape
North American producers anchor the premium controls tier through captive sensor portfolios and airport-hospital vertical specialization; European specialists hold technology leadership in digital twin integration and district-scale energy networks. The vendor base fragments across three strategic archetypes: diversified industrial conglomerates with power distribution hardware, pure-play software platforms monetizing subscription telemetry, and mid-scale system integrators capturing retrofit procurement. Competitive positioning hardens through backward integration into power distribution hardware and strategic partnerships around grid-interactive protocol certification.
Within the diversified industrial tier, Honeywell and Siemens exemplify divergent geographic anchoring strategies. Honeywell represents North American vertical specialization in critical infrastructure controls, while Siemens occupies a position in European district-energy system integration. Schneider Electric sits within the hardware-software convergence archetype through its EcoStruxure platform architecture. These three companies illustrate how competitive positioning fragments across regional regulatory environments and vertical application depth.
| Leading Market Players |
|---|
| Honeywell |
| IBM |
| Johnson Controls |
| Legrand |
| Hitachi |
| Siemens |
| ABB |
| Distech Controls |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
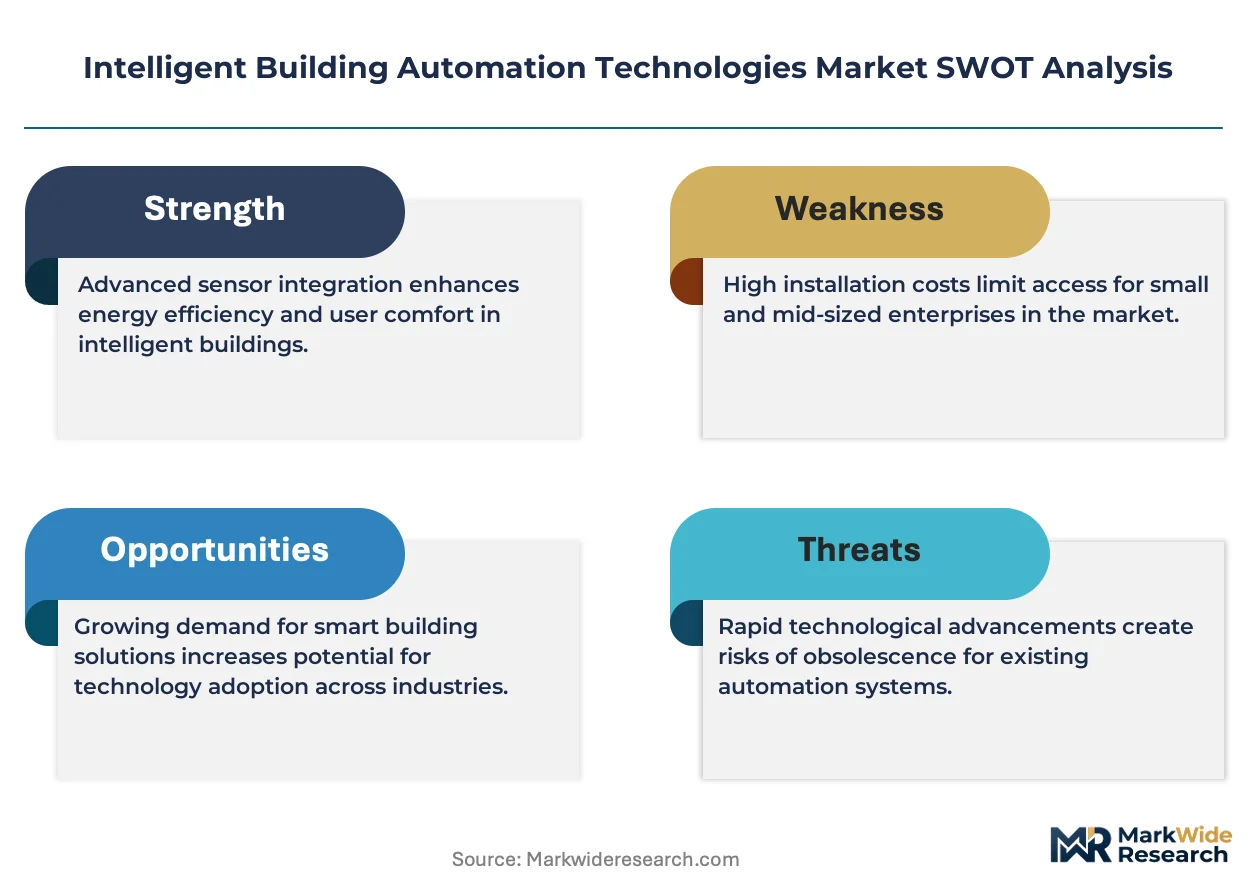
F-Gas Regulation compliance deadlines in Germany are compressing procurement timelines and forcing asset owners toward pre-certified controller bundles that carry embedded margin premiums for systems integrators. This specification-driven urgency elevates the bargaining position of vendors with captive certification resources while squeezing price-sensitive retrofit projects toward stripped-down sensor configurations.
Pricing Analysis
Distributor margins on BACnet-compatible controllers typically range from 15-25% for standard-tier products, with certified-IEC 62443 variants commanding 8-12 point premiums. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated edge nodes from white-label alternatives. Pricing pressure stems from semiconductor input volatility that compresses margins on entry-level PLCs. Small-scale facility managers exhibit highest price sensitivity, while district-scale housing associations prioritize lifecycle service bundling over unit economics.
Supply Chain Analysis
Regional distribution centers in the Netherlands and northern Italy anchor hub-and-spoke patterns for certified commissioning hardware, with satellite warehouses in Frankfurt and Munich serving compressed retrofit timelines. Controller production draws from Taiwanese foundry capacity for BACnet processors, German sensor fabrication for refrigerant leak detection, and Chinese wireless module assembly. Single-source vulnerability concentrates in Taiwan semiconductor supply for PLC edge processors. Distribution runs through authorized systems integrators who bundle hardware with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent building automation has shifted toward a late-cycle quality story as EU Green Deal mandates harden specification floors and asset owners prioritize compliance-grade instrumentation over cost-optimized alternatives.
For Market Incumbents: Cement technology leadership through backward integration into power distribution hardware that feeds proprietary platform architectures. Deepen certification investment in IEC 62443 validation cycles to freeze out software entrants lacking compliance infrastructure. Defend against pure-play cloud platforms by anchoring long-term service contracts around predictive maintenance telemetry.
For New Entrants and Emerging Players: Capture white-space in Netherlands district heating substation automation where fourth-generation network requirements outpace incumbent response capacity. Target French facility management outsourcing firms with subscription-native architectures that displace legacy server infrastructure. Lead with API-first integration that unbundles hardware specification from software procurement.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale system integrators holding certified commissioning capacity in constrained geographies. Five-to-ten year viability favors vendors with district-scale energy network deployment experience. Monitor F-Gas Regulation implementation velocity as inflection indicator for replacement cycle intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Investment | Fourteen-month validation cycles freeze development roadmaps for non-compliant competitors. |
| District Heating Integration Partnership | Bidirectional substation automation opens procurement from Netherlands housing associations. |
| Cloud-Native Platform Migration | Subscription architectures displace on-premise servers in French facility management outsourcing. |
| Refrigerant Monitoring Sensor Deployment | F-Gas Regulation mandates create compliance-driven demand for IoT-enabled HVAC infrastructure. |
| Digital Twin Integration | Physics-based building models compress commissioning time for deep retrofit projects. |
Research Methodology
Direct dialogue with systems integration engineers, facility management procurement leads, municipal utility planning officers, and certified commissioning specialists grounded this analysis in operational reality. Secondary validation drew from EU F-Gas implementing act filings, ASHRAE standard revision documentation, German federal Building Energy Act regulatory impact assessments, and customs data on BACnet controller trade flows. Bottom-up project pipeline enumeration was triangulated against top-down addressable stock estimates.
Segment-level outputs across the projection horizon reflect modeled deployment of HVAC controls, energy management systems, and IoT-enabled sensor networks by building vintage, application intensity, and regulatory compliance tier. CAGRs were derived from replacement cycle compression under EU Green Deal mandates and utility-linked demand response program expansion. Forecast inputs incorporated semiconductor lead time variability and certified engineer availability constraints.
Regulatory implementation delays, foundry capacity disruptions, and interoperability standard fragmentation are the dominant revision risks that could alter trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Signage Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
AEC Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Building Management System Market