
 United States Smart Windows Market | 2026-2036
United States Smart Windows Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart Windows Market Intelligence
The capital-intensity divergence between electrochromic deposition specialists and liquid-crystal assemblers is rotating competitive investment toward in-house sputtering equipment and captive tungsten-oxide supply. View, Inc. leverages vertically integrated fabrication facilities in Mississippi to control coating throughput. Gentex Corporation anchors its position through automotive-centric dimming expertise extended into architectural channels. PPG Industries competes via broad chemical coatings infrastructure that sustains pilot-line scale for smart glazing iterations.
Smart windows are glazing systems that modulate visible light transmission and solar heat gain through applied voltage, thermal response, or photoactive layers, typically employing tungsten-oxide or viologen-based electrochromic films between conductive substrates to achieve dynamic opacity control for energy management. Electrochromic glass dominates installed value due to proven cycling durability exceeding fifty thousand switches, while liquid-crystal glass segments capture premium retrofit margins in conference-room privacy applications. IoT-enabled technology layers are expanding fastest as building-management system integration becomes standard in Class-A commercial specifications.
The Department of Energy enforces performance benchmarks through ENERGY STAR certification pathways that filter substandard dynamic glazing from federal procurement eligibility. California Title 24 building codes mandate solar heat gain coefficient thresholds that effectively require electrochromic or thermochromic solutions for compliance in new commercial construction. Stakeholders must monitor NHTSA glazing safety standards as automotive smart-window adoption accelerates, since harmonization between optical performance and crashworthiness testing remains unresolved.
Market Dynamics
The Inflation Reduction Act's energy-efficient building tax credits are compressing payback periods for electrochromic retrofits, accelerating procurement timelines among commercial office developers in Manhattan and San Francisco while reshaping supplier capacity planning.
Growth Catalysts
- California Title 24 mandates:Zero-net-energy building codes in Los Angeles and San Diego metro corridors require dynamic glazing for solar heat gain compliance, pulling electrochromic demand into new commercial construction.
- Electrochromic cycling durability:Proven switching lifespans exceeding fifty thousand cycles reduce replacement frequency and maintenance burden for facility managers in Class-A office portfolios.
- IoT-enabled building management integration:Smart windows with embedded sensors and API connectivity are becoming standard in commercial specifications, enabling automated daylight harvesting and HVAC load reduction.
Market Restraints
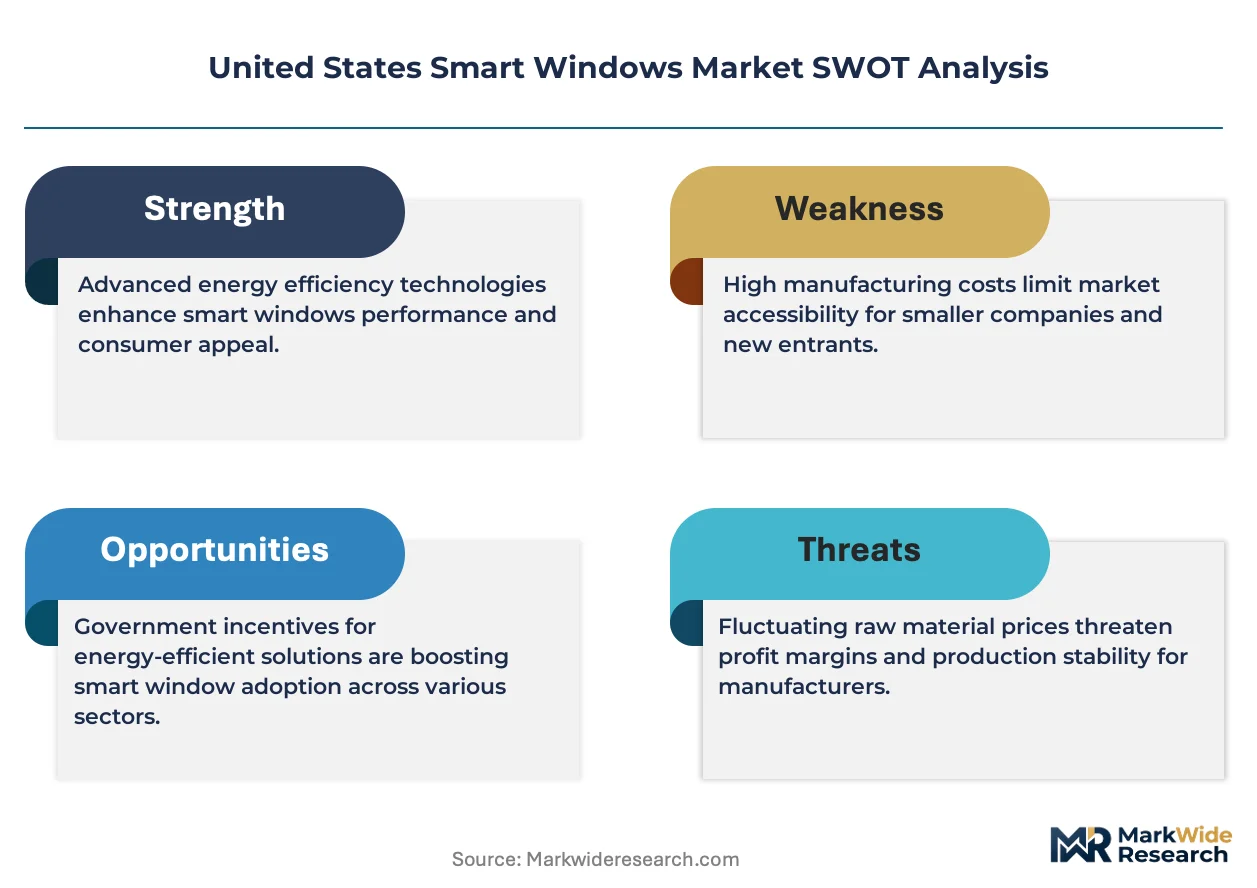
- Tungsten oxide supply concentration:Sputtering-grade tungsten oxide feedstock relies on limited domestic refining capacity, exposing coating specialists to input cost volatility and qualification delays.
- High upfront capital intensity:Electrochromic fabrication requires captive sputtering equipment and cleanroom infrastructure that locks smaller glazing contractors out of direct procurement relationships.
- Automotive glazing safety friction:NHTSA optical performance and crashworthiness testing standards remain unresolved for dynamic automotive applications, delaying crossover from architectural channels.
Strategic Opportunities
- Texas and Florida commercial corridors:Sunbelt states without California-style mandates present underpenetrated retrofit potential as cooling-load economics independently justify dynamic glazing investments.
- Privacy-centric liquid-crystal retrofits:Conference room and healthcare applications command premium margins through instant opacity switching without the thermal management complexity of electrochromic systems.
- Utility demand-response programs:Smart windows with grid-interactive controls qualify for peak-load reduction incentives from FERC-jurisdictional regional transmission organizations, creating new revenue stacking models.
Industry Challenges
- Electrochromic deposition technician scarcity:Sputtering process engineers with thin-film coating expertise command premium wages, constraining Mississippi and Ohio fabrication facility expansion timelines.
- Multi-system integration complexity:BACnet and Modbus protocol harmonization between smart window controllers and legacy building automation systems extends commissioning cycles and escalates project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart Windows Market |
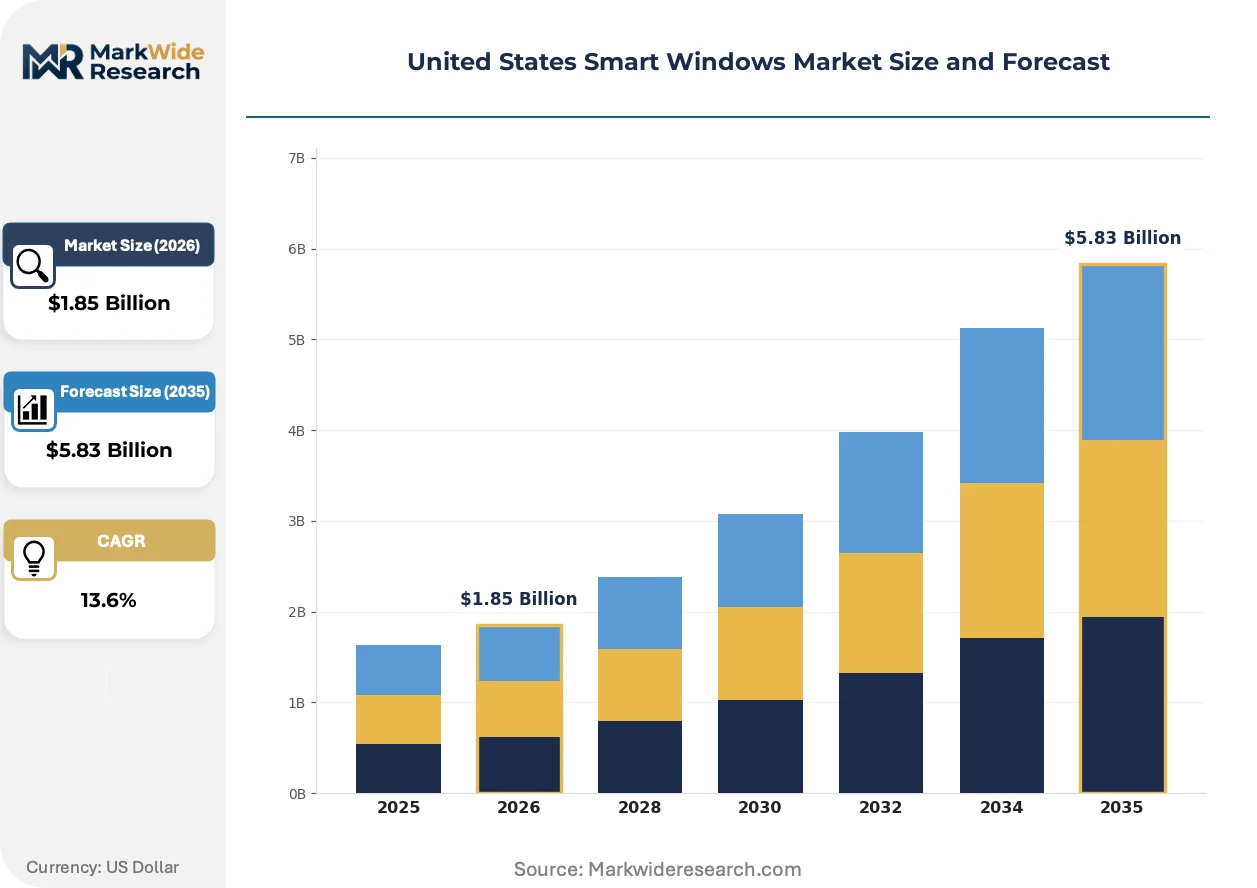
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.83 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic Glass, Thermochromic Glass, Photochromic Glass, Liquid Crystal Glass Application: Residential, Commercial, Automotive, Aerospace End User: Homeowners, Builders, Architects, Manufacturers Technology: Nanotechnology, IoT-Enabled, Solar Control, Smart Coatings |
| Companies Covered | View, Inc., Gentex Corporation, PPG Industries, Saint-Gobain, SAGE Electrochromics, Research Frontiers Inc., Gauzy Ltd., Polytronix Inc, RavenBrick LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart Windows Market Strategic Shifts & Innovations
Active voltage modulation technologies are migrating from premium commercial niches toward mid-market multifamily and educational construction, compressing the technology adoption curve and forcing coating specialists to rethink throughput economics.
Photovoltaic-integrated electrochromic glass is supplanting standalone dynamic glazing in net-zero commercial prototypes. Developers in Austin and Miami are specifying building-integrated photovoltaics with embedded tinting layers that generate power while managing solar gain. This convergence is compressing the addressable market for pure-play electrochromic suppliers without captive solar cell fabrication.
The Inflation Reduction Act's Section 179D deduction pathway is tightening documentation requirements for energy-efficient building retrofits. Commercial property owners must now secure third-party certification of modeled energy savings to claim accelerated depreciation, which filters speculative smart window proposals from federal tax-advantaged financing. Large institutional investors with in-house sustainability engineering teams are capturing this compliance burden advantage over smaller developers.
Building owners are consolidating vendor relationships through single-source facade performance contracts that bundle smart window supply, installation, and ongoing tint optimization services. General contractors in the Pacific Northwest are ceding specification control to integrated facade specialists who assume energy savings guarantees. This channel compression is marginalizing traditional glazing subcontractors who lack controls integration capabilities.
United States Smart Windows Market Segmentation
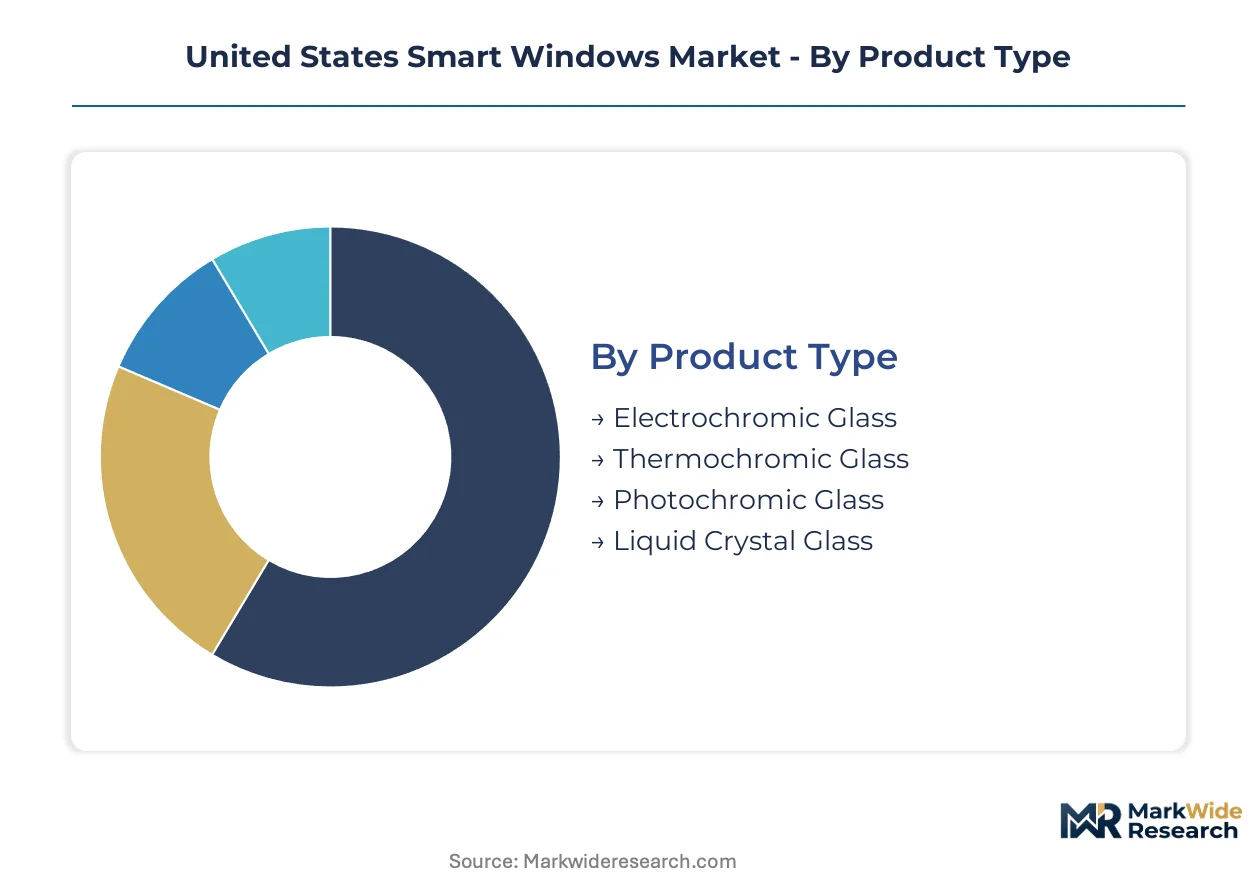
Technology selection in the United States Smart Windows Market determines compliance pathways under California Title 24 and federal procurement standards. Procurement patterns diverge sharply across electrochromic, thermochromic, and liquid-crystal systems based on cycling durability requirements and integration complexity with building automation infrastructure.
Product Type:
FERC-jurisdictional utility incentive programs and DOE ENERGY STAR certification pathways differentiate electrochromic systems from passive alternatives, creating distinct procurement channels for active versus responsive glazing technologies.
- Electrochromic Glass:Tungsten-oxide films between conductive substrates achieve voltage-driven opacity modulation with cycling durability exceeding fifty thousand switches. Class-A commercial developers in Manhattan and San Francisco specify these systems for solar heat gain compliance under accelerated depreciation timelines from the Inflation Reduction Act.
- Liquid Crystal Glass:Polymer-dispersed liquid crystal layers enable instant opacity switching without thermal management complexity. Conference room and healthcare retrofits in Los Angeles and San Diego metro corridors command premium margins for privacy applications where cycling frequency exceeds electrochromic economic thresholds.
- Thermochromic Glass:Vanadium-dioxide coatings respond passively to temperature thresholds without electrical infrastructure.
- Photochromic Glass:Silver-halide or naphthopyran compounds darken under UV exposure for residential skylight and atrium applications.
Electrochromic glass handles the majority of throughput; liquid crystal glass is the fastest mover on share.
Application:
Cooling-load economics and mandate structures segment demand across building types, with commercial specifications leading on technology complexity and automotive channels facing unresolved NHTSA testing standards.
- Commercial:Zero-net-energy building mandates in California and Section 179D documentation requirements pull electrochromic demand into new construction and retrofit portfolios. Building owners consolidate vendor relationships through single-source facade performance contracts that bundle supply, installation, and ongoing tint optimization.
- Residential:Mid-market multifamily and educational construction segments compress adoption curves as active voltage modulation migrates from premium commercial niches.
- Automotive:NHTSA optical performance and crashworthiness testing standards remain unresolved, delaying crossover from architectural channels.
- Aerospace:Cabin pressure cycling and weight constraints favor electrochromic systems with proven altitude performance.
Commercial applications dominate installed value; residential channels are expanding most quickly as cooling-load economics independently justify investments in Texas and Florida corridors.
End User:
Technical capability and procurement scale determine specification control, with institutional investors capturing compliance advantages over smaller developers under tightened Section 179D documentation requirements.
- Builders:General contractors in the Pacific Northwest cede specification control to integrated facade specialists who assume energy savings guarantees.
- Architects:Design-phase influence over glazing specifications shapes technology selection for net-zero commercial prototypes.
- Homeowners:Retrofit demand concentrates in California metro corridors driven by zero-net-energy mandates.
- Manufacturers:Automotive and aerospace OEMs specify smart glazing for cabin comfort and weight reduction targets.
Builders coordinate the largest project volumes; architects are gaining influence fastest as facade performance contracts consolidate vendor relationships.
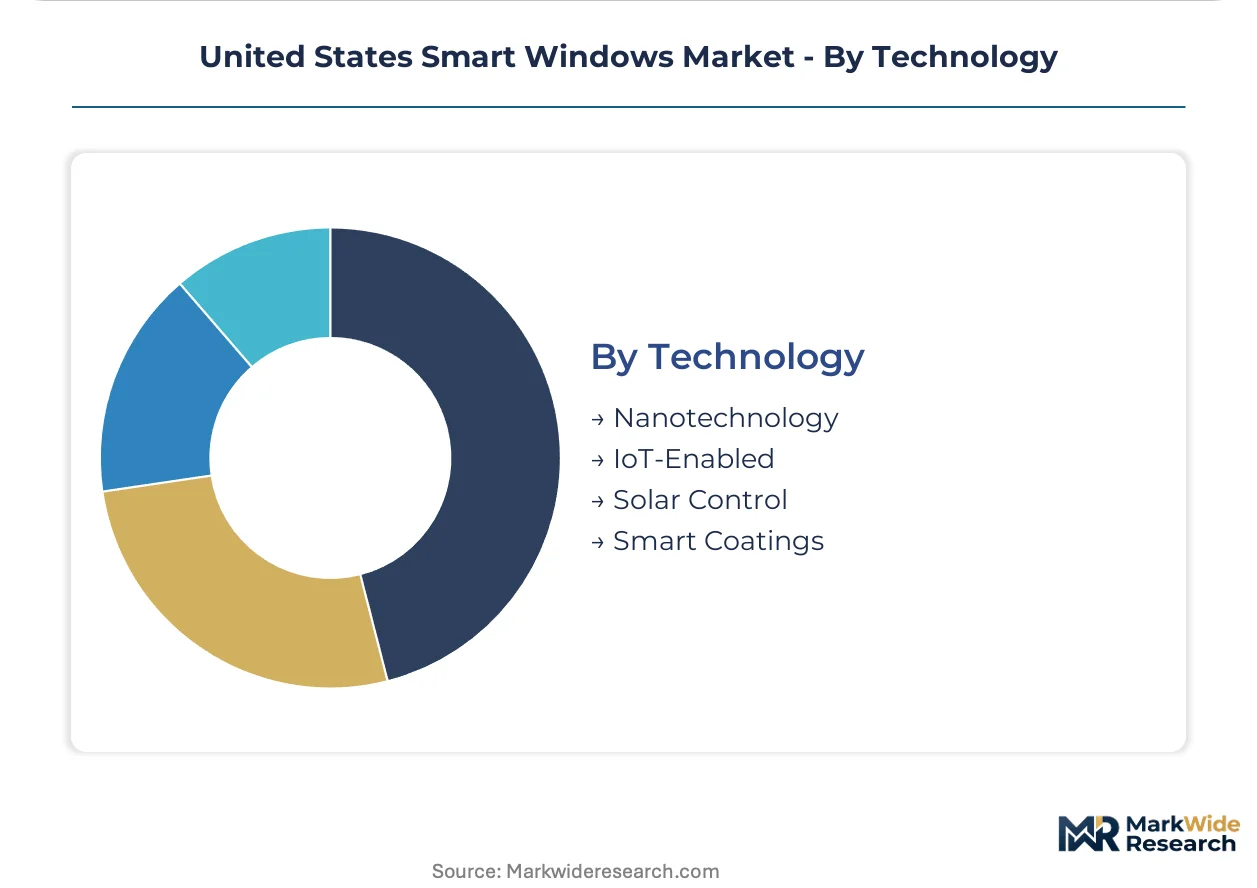
Technology:
Integration depth with building management systems segments technology tiers, with IoT-enabled layers expanding fastest as BACnet and Modbus protocol harmonization becomes standard in Class-A specifications.
- IoT-Enabled:Embedded sensors and API connectivity enable automated daylight harvesting and HVAC load reduction through grid-interactive controls qualifying for FERC-jurisdictional peak-load reduction incentives.
- Nanotechnology:Thin-film deposition processes enable electrochromic cycling durability and optical precision.
- Smart Coatings:Multi-layer sputtered films achieve dynamic performance without full electrochromic infrastructure.
- Solar Control:Spectrally selective layers manage infrared transmission independent of visible light modulation.
IoT-enabled systems command the steepest expansion trajectory; nanotechnology underpins the manufacturing base across all active glazing categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States smart windows trade flows reflect concentrated import dependence for sputtering-grade tungsten oxide feedstock, with domestic fabrication capacity expanding in Mississippi and Ohio to offset supply chain exposure.
California
Zero-net-energy building mandates in Los Angeles and San Diego metro corridors drive electrochromic specification rates above national averages. Title 24 solar heat gain coefficient thresholds effectively require dynamic glazing compliance for new commercial construction. The San Francisco Bay Area anchors retrofit demand as Class-A office developers accelerate depreciation-driven procurement under Inflation Reduction Act timelines.
Texas
Cooling-load economics independently justify smart window investments across Dallas-Fort Worth and Houston commercial corridors without California-style regulatory mandates. ERCOT grid instability amplifies demand-response value propositions for IoT-enabled facade systems. Austin developers lead photovoltaic-integrated electrochromic adoption in net-zero commercial prototypes.
New York
Manhattan commercial office retrofits concentrate procurement timelines around Section 179D documentation requirements for accelerated depreciation claims. NYSERDA clean energy programs supplement federal incentives for building envelope upgrades. The Hudson Yards district exemplifies single-source facade performance contracting with embedded energy savings guarantees.
Florida
Sunbelt cooling economics drive retrofit potential across Miami and Tampa commercial markets absent stringent statewide energy codes. Hurricane-resistant glazing specifications create hybrid demand for impact-rated smart window systems. The Orlando hospitality corridor commands premium margins for liquid-crystal privacy applications in conference and guest room retrofits.
Pacific Northwest
Seattle and Portland building owners consolidate vendor relationships through integrated facade specialists assuming performance risk. Washington State clean building performance standards tighten operational carbon thresholds for existing commercial stock. The region's technology sector employment base sustains specification sophistication for BACnet-integrated daylight harvesting systems.
United States Smart Windows Market Key Industry Players
Concentration sits with vertically integrated electrochromic fabricators controlling captive sputtering equipment and tungsten-oxide supply chains. The vendor base spans three strategic tiers: premium-tier integrated specialists, mid-market coating licensees, and regional glazing contractors lacking controls integration capabilities. Dominant competitive moves include backward integration into thin-film deposition equipment and strategic partnerships with building automation system providers.
Among Mississippi-based fabricators, View, Inc. occupies a position exemplifying captive production infrastructure for coating throughput control. Gentex Corporation represents automotive-centric dimming expertise extended into architectural channels. PPG Industries anchors the chemical coatings infrastructure tier sustaining pilot-line scale for smart glazing iterations.
| Leading Market Players |
|---|
| View, Inc. |
| Gentex Corporation |
| PPG Industries |
| Saint-Gobain |
| SAGE Electrochromics |
| Research Frontiers Inc. |
| Gauzy Ltd. |
| Polytronix Inc |
| RavenBrick LLC |
| Others |
Cost & Logistics Intelligence
Ninety-day qualification cycles for sputtering-grade tungsten oxide feedstock concentrate procurement leverage among electrochromic fabricators, amplifying pricing power for captive suppliers while compressing margins for coating specialists without backward integration into refining capacity. This lead-time rigidity forces project developers to lock material positions early, shifting contract structures toward long-term offtake agreements that transfer commodity volatility risk downstream.
Pricing Analysis
Configured-to-order electrochromic glazing commands a thirty-five to fifty percent premium over standard architectural glass specifications, with price differentiation driven by cycling durability certification tiers and integration complexity with BACnet building automation systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by electrochromic switching lifespan guarantees, with Class-A commercial developers in Manhattan and San Francisco exhibiting lowest price sensitivity due to Section 179D tax credit absorption. Cost compression in mid-market multifamily retrofits is intensifying because liquid-crystal assemblers are displacing electrochromic solutions in privacy-centric applications.
Supply Chain Analysis
Strait of Malacca transit underwrites sputtering-grade tungsten oxide feedstock flows from Chinese refining centers to Mississippi and Ohio fabrication facilities, creating single-source vulnerability exposure for domestic electrochromic producers. Raw material dependencies center on tungsten oxide, indium tin oxide conductive substrates, and polymer-dispersed liquid crystal compounds, with supply chain risk concentrated in tariff exposure on Chinese-origin critical minerals. Distribution runs through integrated facade specialists who assume performance risk, marginalizing traditional glazing subcontractors lacking controls integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Smart Windows Market functions as a defensive-moat arena where regulatory entrenchment through California Title 24 compliance pathways and ENERGY STAR certification creates switching costs that protect incumbent positions.
For Market Incumbents: Consolidate specification control through single-source facade performance contracts that bundle supply, installation, and ongoing tint optimization services. Deepen backward integration into captive tungsten oxide refining capacity to defend against input cost volatility from concentrated Chinese supply. Lock in exclusive BACnet protocol partnerships with building automation system providers to raise integration barriers for coating licensees.
For New Entrants and Emerging Players: Anchor in Texas and Florida commercial corridors where cooling-load economics independently justify dynamic glazing investments absent California-style mandates. Target liquid-crystal privacy retrofits in Orlando hospitality and Dallas healthcare verticals where instant opacity switching commands premium margins without electrochromic thermal management complexity. Pursue utility demand-response program qualification as a go-to-market wedge for grid-interactive IoT-enabled systems.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because Inflation Reduction Act energy-efficient building tax credits and evolving state-level zero-net-energy mandates create durable demand pull for compliance-enabled suppliers. Acquisition focus should center on electrochromic deposition specialists with captive sputtering equipment and qualified tungsten oxide supply chains. Watch FERC-jurisdictional regional transmission organization rulemakings on peak-load reduction incentives as the signal for demand-response revenue stacking inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Oxide Refining | Captive supply of sputtering-grade feedstock insulates Mississippi and Ohio fabricators from Chinese export volatility. |
| Single-Source Facade Performance Contracting | Integrated specialists assume energy savings guarantees while marginalizing traditional glazing subcontractors. |
| BACnet Protocol Harmonization Investment | Seamless building automation integration becomes standard in Class-A commercial specifications. |
| Utility Demand-Response Program Qualification | Grid-interactive controls unlock FERC-jurisdictional peak-load reduction incentives for building owners. |
| Liquid-Crystal Privacy Retrofit Specialization | Conference room and healthcare applications command premium margins through instant opacity switching. |
Research Approach
A standing panel of electrochromic fabrication plant managers, Class-A commercial property developers, building automation system integrators, and FERC-jurisdictional utility demand-response program administrators provided ongoing calibration against market developments. Primary interview intelligence combined with secondary validation from Department of Energy ENERGY STAR certification databases, California Energy Commission Title 24 compliance filings, and SEC 10-K disclosures from publicly traded coating specialists. Bottom-up project pipeline tracking across Manhattan, San Francisco, Los Angeles, and San Diego metro corridors triangulated against top-down addressable market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning technology type, application vertical, end-user archetype, and integration depth with building management systems. CAGRs were derived from installation run-rate trajectories, retrofit penetration curves, and new construction specification rates. Industry-specific forecast inputs incorporated Inflation Reduction Act tax credit absorption timelines and Title 24 mandate compliance deadlines.
Material uncertainties — tariff escalations on Chinese-origin tungsten oxide, NHTSA automotive glazing safety standard resolutions, and ERCOT grid stability disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding electrochromic cycling durability improvements and liquid-crystal cost curves. Practitioners should keep alternative scenarios live as FERC demand-response rulemakings and state-level zero-net-energy mandate expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
AEC Market
Building Automation Systems
Global Enterprise Building Solutions Market