
 Fibrin Glue Market | 2026-2036
Fibrin Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Fibrin Glue Market Analysis
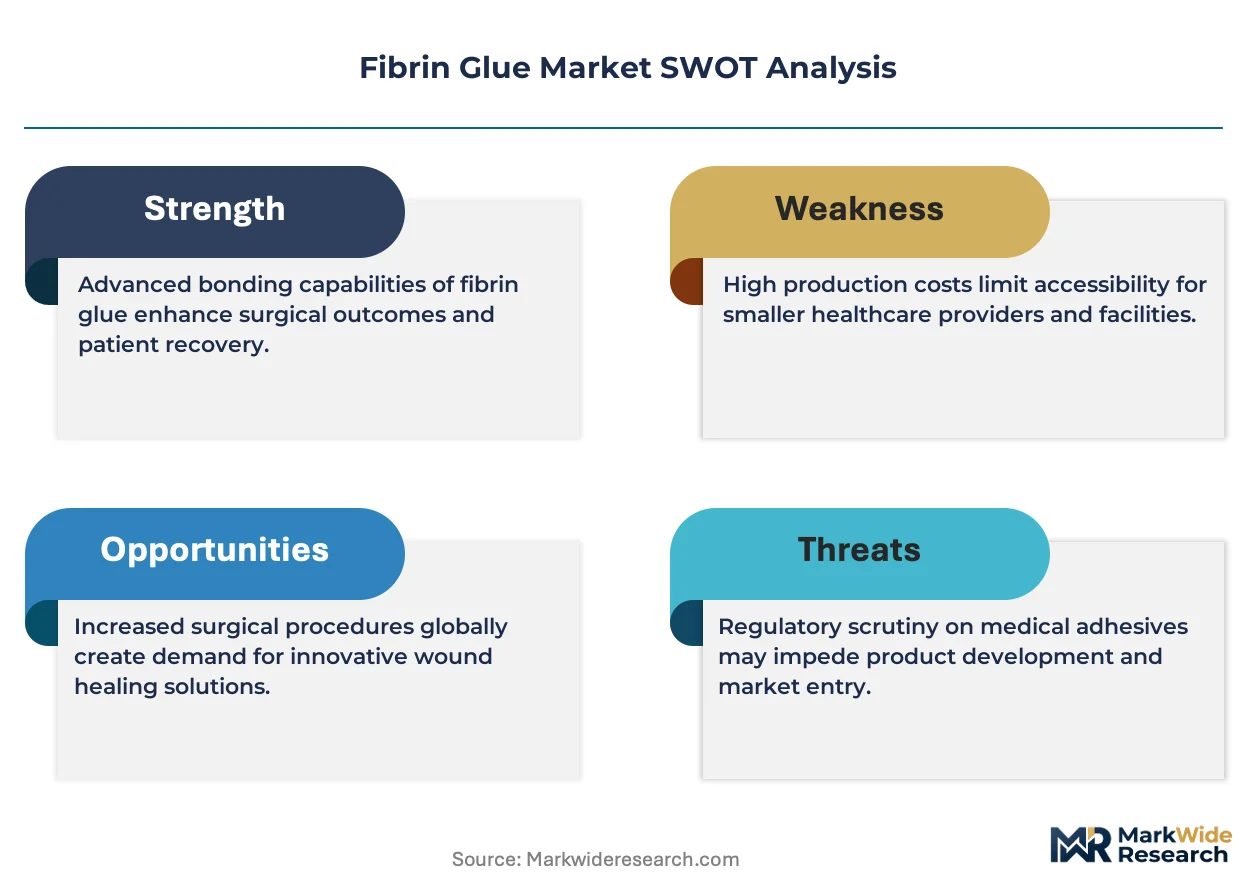
Hospital procurement is narrowing around fewer fibrin glue suppliers with validated plasma supply chains. Baxter International Inc sustains broad geographic coverage through its plasma fractionation infrastructure. Grifols S.A. anchors European supply with vertically controlled donor networks. Johnson & Johnson competes on surgeon training ecosystems and operating room integration.
Fibrin glue comprises a biological adhesive formed from fibrinogen and thrombin, typically derived from human or bovine plasma, that polymerizes upon mixing to create a hemostatic sealant mimicking the final coagulation cascade. The product type dimension shows human-source formulations retaining dominant share while synthetic alternatives attract development investment for pathogen-free assurances. Application concentration in cardiac surgery reflects high-value procedural volumes, though orthopedic surgery represents the fastest-expanding usage segment as arthroscopic techniques advance.
The FDA enforces plasma sourcing documentation and viral inactivation validation for all commercial fibrin sealants, while the EMA's MDR framework imposes enhanced clinical evidence requirements for Class III device re-certification. ISO 13485 quality management standards govern manufacturing consistency across jurisdictions. Stakeholders must monitor evolving plasma collection economics and synthetic polymer efficacy thresholds as regulatory pathways diverge between biological and non-biological product categories.
Market Dynamics
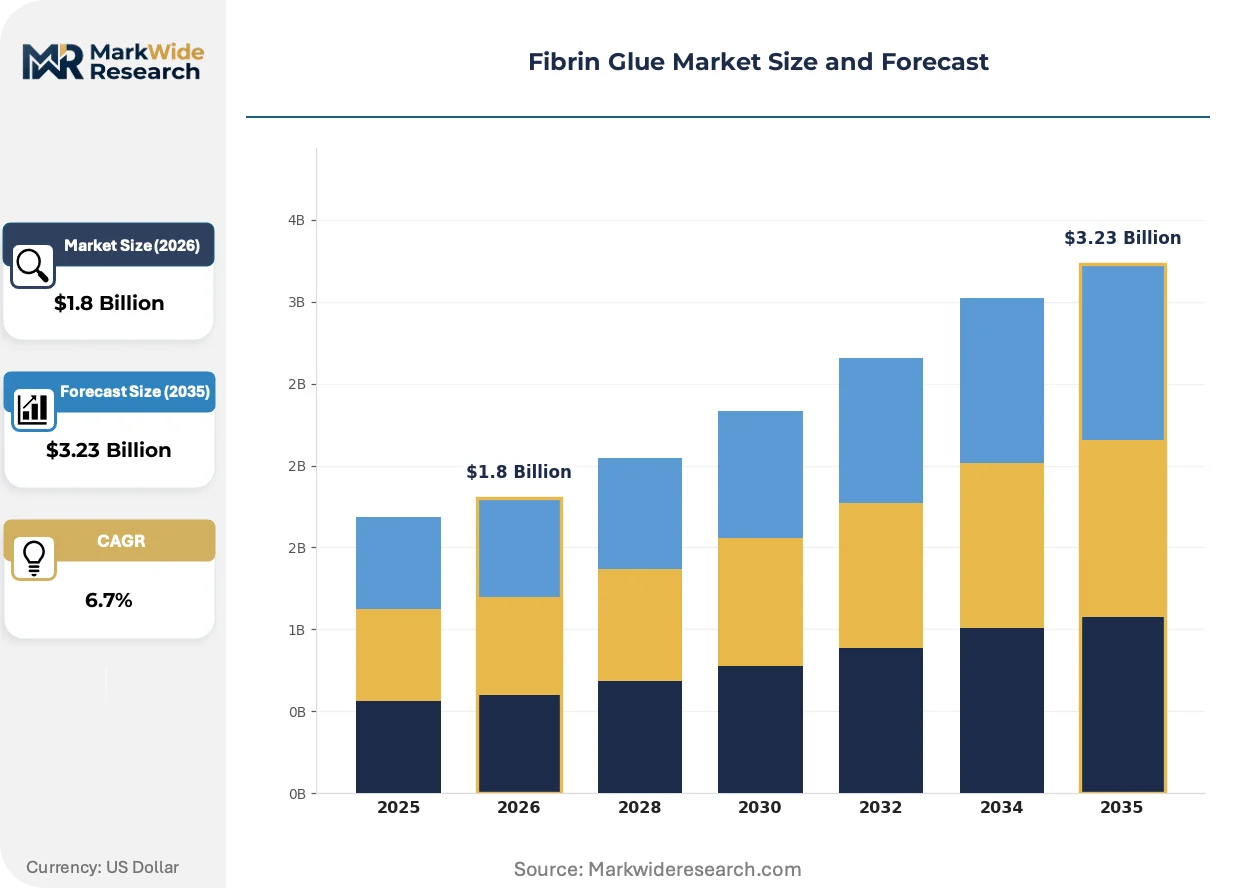
Hospital procurement consolidation is compressing supplier margins while elevating plasma traceability requirements as the decisive competitive filter. Cardiac surgery volume expansion and arthroscopic technique diffusion are pulling fibrin glue into higher-throughput settings where standardization protocols dominate purchasing decisions.
Growth Catalysts
- Cardiac surgery protocol standardization:Health systems in the United States are embedding fibrin sealants into mandatory hemostasis bundles for coronary artery bypass grafting procedures. This procedural codification locks in recurring procurement volumes across integrated delivery networks.
- EMA MDR Class III re-certification:The European Union's Medical Device Regulation is forcing manufacturers to generate fresh clinical evidence for legacy products. Incumbents with established trial infrastructure capture market access that new entrants cannot replicate within compliance timelines.
- Arthroscopic technique advancement:Orthopedic surgery is adopting fibrin glue for meniscal repair and rotator cuff fixation. This application expansion diversifies revenue beyond cardiac centers into ambulatory surgery facilities with different purchasing cadences.
Market Restraints
- Plasma fractionation concentration:Human-source fibrinogen supply depends on a narrow base of fractionators with validated viral inactivation protocols. Any disruption at major collection centers cascades through downstream sealant production.
- FDA donor deferral policies:Stringent plasma donor screening criteria in the United States constrain raw material availability. Collection economics tighten when eligible donor pools contract under revised vCJD geographic risk exclusions.
- Synthetic polymer efficacy gap:Non-biological sealants from polyethylene glycol and cyanoacrylate platforms achieve comparable burst strength in soft tissue applications. Price-sensitive hospital systems substitute these alternatives where hemostatic performance requirements permit.
Strategic Opportunities
- Indian outpatient surgery expansion:India's Central Drugs Standard Control Organization is streamlining Class III device registration pathways. Manufacturers establishing local plasma fractionation partnerships can access government hospital tenders ahead of multinational incumbents.
- Japan's aging surgical population:Japan's Ministry of Health, Labour and Welfare is reimbursing advanced hemostatic agents for elderly patients with coagulopathy risk. This demographic tailwind supports premium pricing for fibrin sealants with rapid polymerization profiles.
- Synthetic-biological hybrid formulations:Convergence of recombinant fibrinogen production with synthetic cross-linking chemistry is opening pathogen-free product categories. These platforms bypass plasma supply constraints while retaining biological adhesion kinetics.
Industry Challenges
- Viral inactivation validation timelines:Demonstrating 4-log reduction across enveloped and non-enveloped viruses requires 18-24 month stability studies. These certification delays compress product refresh cycles and extend capital lockup periods.
- Cold chain integrity maintenance:Lyophilized fibrin sealants require controlled temperature storage through distribution networks. Temperature excursion events during last-mile delivery to rural hospitals trigger batch quarantines and inventory write-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibrin Glue Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Source, Bovine Source, Synthetic, Others Application: Cardiac Surgery, Orthopedic Surgery, Neurological Surgery, Plastic Surgery End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Delivery Mode: Pre-filled Syringe, Vial, Lyophilized Form, Others |
| Companies Covered | Medtronic PLC, Asahi Kasei Corporation, Baxter International Inc, B.Braun SE, Octapharma AG, Johnson & Johnson, Pfizer Inc, Grifols S.A., CSL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibrin Glue Market Emerging Trajectories
Biological sealant technology is fragmenting along purity and sourcing axes as regulatory pathways diverge between plasma-derived and recombinant platforms. Hospital procurement is simultaneously demanding broader application claims and narrower supplier rosters.
Synthetic fibrinogen analogs are migrating from research-phase constructs toward commercial-scale production using yeast and plant expression systems. Orthopedic surgery departments in German university hospitals are piloting these recombinant formulations for arthroscopic applications where immunogenicity concerns are lower. This technology trajectory is compressing the historical cost premium of biological sealants while forcing plasma-dependent manufacturers to defend their sourcing narratives.
Japan's PMDA is tightening post-market surveillance requirements for biological medical devices with novel viral inactivation claims. Manufacturers must now submit real-world hemostasis outcome data from designated medical institutions as a condition of continued marketing authorization. Cardiac surgery units in Tokyo and Osaka are responding by consolidating purchases around suppliers with established Japanese pharmacovigilance infrastructure.
Hospital supply chains are unbundling fibrin glue from traditional surgical pack contracts. United States integrated delivery networks are negotiating direct manufacturer agreements that bypass distributor markups for high-volume sealant categories. This channel restructuring is most visible in Texas and Florida health systems where cardiac surgery case volumes justify dedicated logistics arrangements with plasma fractionators.
Fibrin Glue Market Segmentation
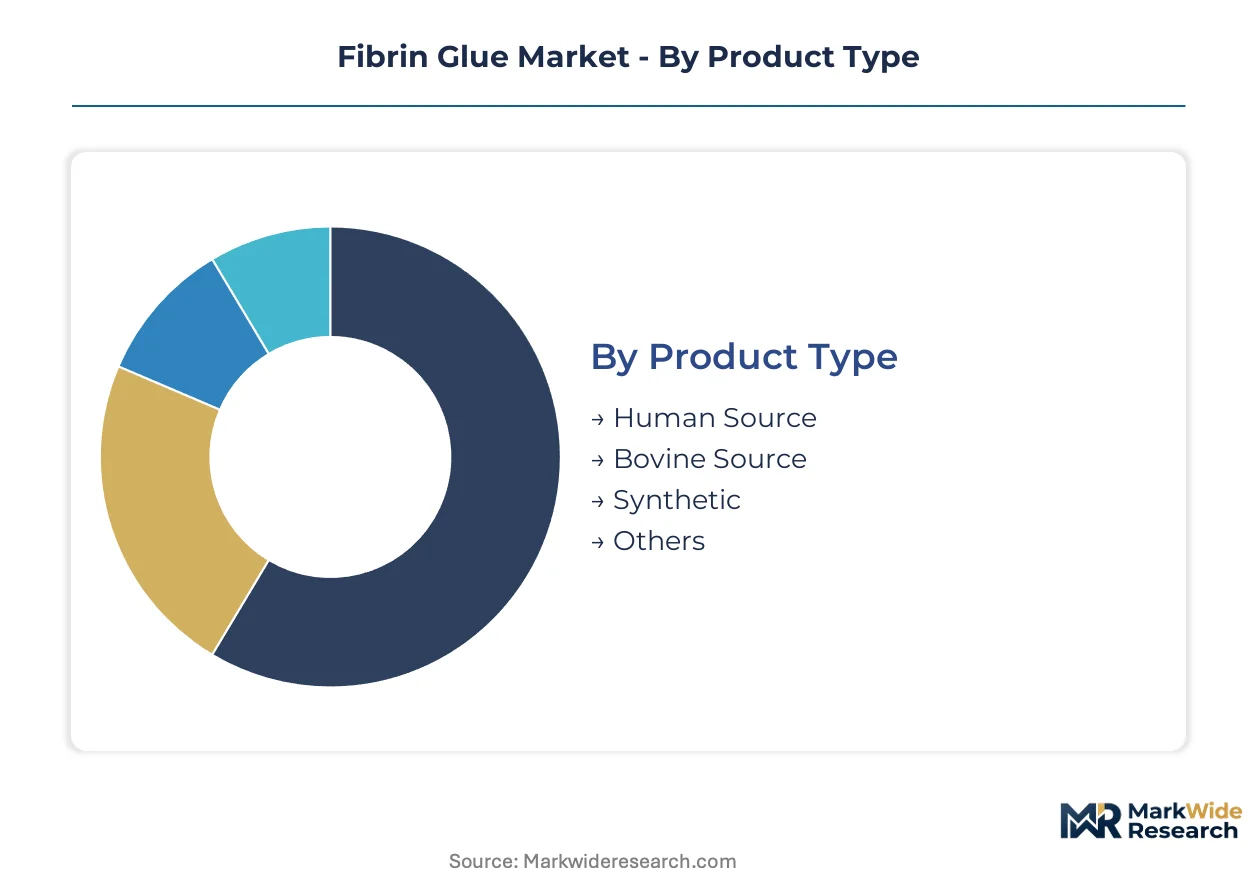
Fibrin glue segmentation reveals divergent supply chain risks and clinical adoption patterns across sourcing technologies and surgical settings. Procurement decisions increasingly weight plasma traceability against synthetic performance guarantees, while delivery format choices reflect storage infrastructure constraints.
Product Type:
Clinical use-cases span from high-risk cardiac procedures demanding proven viral inactivation to outpatient settings tolerating synthetic alternatives.
- Human Source:Plasma-derived fibrinogen and thrombin formulations dominate cardiac surgery protocols. United States hospital systems prioritize suppliers with FDA-validated viral inactivation documentation for coronary artery bypass grafting bundles.
- Synthetic:Recombinant and polymer-based sealants bypass plasma supply constraints entirely. German university hospitals pilot yeast-expressed fibrinogen analogs for arthroscopic applications where immunogenicity profiles permit substitution.
- Bovine Source:Bovine thrombin formulations serve cost-sensitive markets with established bovine spongiform encephalopathy screening protocols.
- Others:Autologous fibrin sealants processed from patient blood intraoperatively occupy niche regenerative medicine applications.
Established volume favors human-source formulations; emerging adoption favors synthetic platforms.
Application:
Revenue concentration aligns with procedural complexity and reimbursement tiers across surgical specialties.
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement procedures consume the highest sealant volumes per case. United States integrated delivery networks embed fibrin glue into mandatory hemostasis protocols with locked-in procurement contracts.
- Orthopedic Surgery:Meniscal repair and rotator cuff fixation applications are expanding fastest as arthroscopic techniques diffuse into ambulatory settings. Texas and Florida health systems negotiate direct manufacturer agreements for high-throughput orthopedic centers.
- Neurological Surgery:Dural sealing and cerebrospinal fluid leak repair demand rapid polymerization profiles with minimal tissue reactivity.
- Plastic Surgery:Skin graft fixation and flap adhesion applications prioritize cosmetic outcome preservation over hemostatic speed.
Cardiac surgery anchors procurement scale; orthopedic surgery drives volume diversification.
End User:
Site-of-care economics reshape purchasing cadences and storage requirements across delivery settings.
- Hospitals:Academic medical centers and community hospital systems consolidate fibrin glue purchasing through integrated delivery networks. Cold chain infrastructure supports lyophilized inventory management for cardiac surgery departments.
- Ambulatory Surgical Centers:Freestanding orthopedic and plastic surgery facilities favor pre-filled syringe formats with simplified preparation protocols. Texas ASC networks bypass distributor markups through direct plasma fractionator contracts.
- Clinics:Wound care and minor procedure settings utilize lower-concentration sealant variants with reduced storage requirements.
- Home Care:Post-operative drain site management and chronic wound applications represent emerging off-label utilization with limited formal reimbursement.
Hospital systems dominate procurement volume; ambulatory surgical centers reshape channel economics.
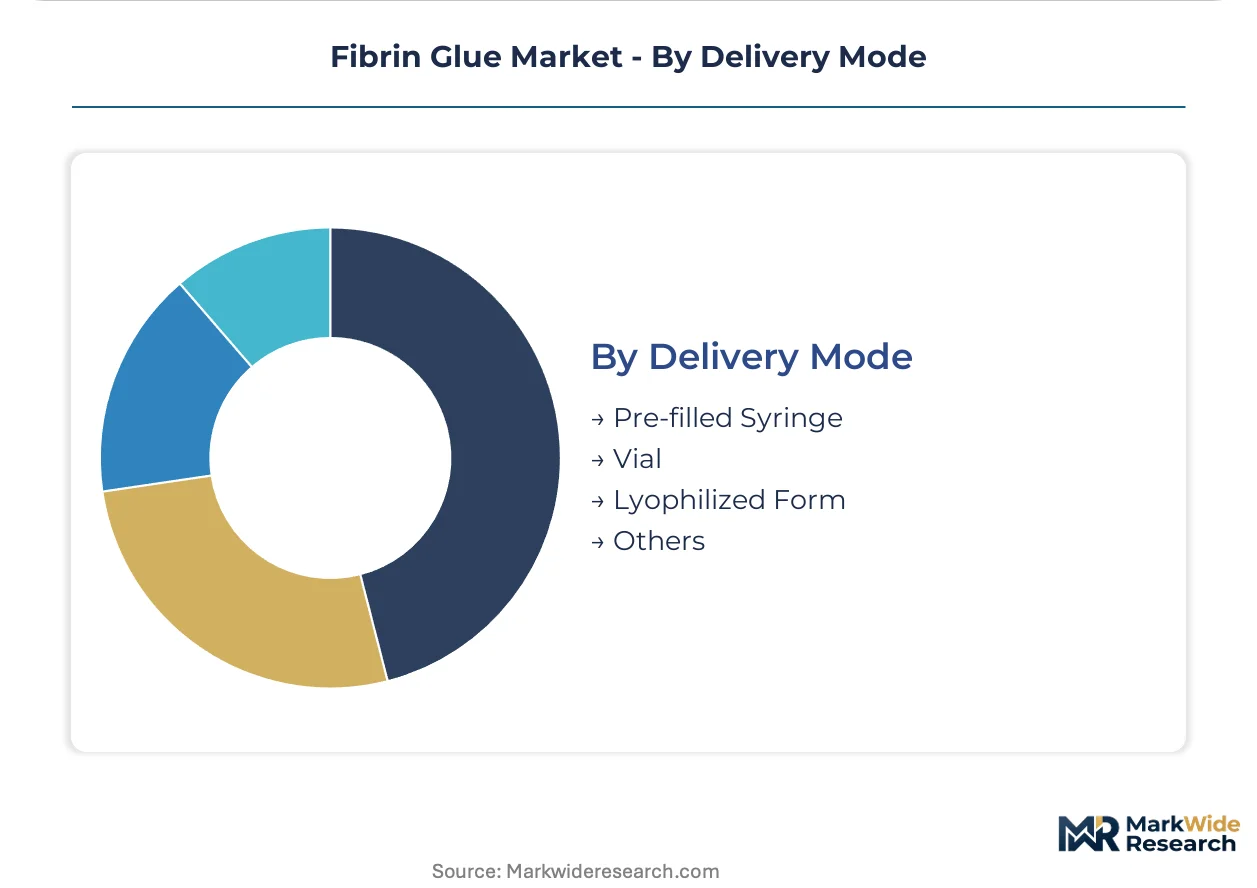
Delivery Mode:
Format selection reflects preparation time constraints, storage infrastructure, and waste minimization priorities.
- Lyophilized Form:Freeze-dried fibrinogen and thrombin components offer extended shelf stability with controlled temperature storage. Rural hospital networks in the United States manage temperature excursion risks through centralized pharmacy distribution.
- Pre-filled Syringe:Ready-to-use dual-chamber syringes eliminate reconstitution steps for time-critical cardiac procedures. Japanese cardiac surgery units specify rapid polymerization profiles for elderly coagulopathy patients.
- Vial:Traditional vial formats persist in high-volume hospital settings with dedicated pharmacy reconstitution services.
- Others:Spray applicators and custom mixing systems serve specialized plastic surgery and burn center applications.
Lyophilized formats anchor inventory flexibility; pre-filled syringes capture procedural efficiency premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA plasma sourcing mandates and EMA MDR re-certification timelines are redrawing procurement geographies for biological sealants. Hospital system consolidation and direct manufacturer contracting now dominate volume allocation across major surgical markets.
United States
Integrated delivery networks in Texas and Florida embed fibrin glue into mandatory cardiac surgery hemostasis bundles. The FDA enforces stringent donor deferral policies and viral inactivation documentation that filter supplier eligibility. Major health systems in Houston and Miami negotiate direct logistics arrangements with plasma fractionators, bypassing traditional distributor channels.
Germany
University hospital orthopedic departments pilot yeast-expressed fibrinogen analogs for arthroscopic applications. The EMA's MDR Class III device framework demands fresh clinical evidence for legacy product re-certification. Industrial clusters in Baden-Württemberg and Bavaria host surgical device manufacturers advancing recombinant production platforms.
Japan
The Ministry of Health, Labour and Welfare reimburses advanced hemostatic agents for elderly surgical patients with coagulopathy risk. PMDA post-market surveillance requirements now mandate real-world outcome data from designated medical institutions. Tokyo and Osaka cardiac surgery units consolidate purchases around suppliers with established Japanese pharmacovigilance infrastructure.
India
Central Drugs Standard Control Organization streamlines Class III device registration pathways for outpatient surgery expansion. Government hospital tenders attract manufacturers establishing local plasma fractionation partnerships. Metropolitan surgical centers in Mumbai and Delhi accelerate procurement of pathogen-free sealant alternatives.
Switzerland
Swissmedic oversees marketing authorization for biological medical devices with novel viral inactivation claims. Basel and Zurich academic medical centers maintain cold chain integrity for lyophilized inventory through centralized pharmacy distribution. Premium pricing persists for rapid-polymerization formulations serving high-complexity cardiac procedures.
Fibrin Glue Market Vendor Landscape
On the supply side, the industry is consolidating around plasma fractionators with validated viral inactivation infrastructure and diversified surgical sealant portfolios. Three archetypes dominate: vertically integrated plasma collectors controlling donor networks, diversified medtech conglomerates leveraging surgeon training ecosystems, and recombinant biotechnology specialists bypassing biological sourcing constraints entirely. Competitive dynamics center on M&A activity securing fractionation capacity and strategic partnerships with integrated delivery networks for direct procurement contracts.
Within the plasma-dependent tier, Baxter International Inc, Grifols S.A., and CSL Limited exemplify archetypes of geographic coverage through fractionation infrastructure, European supply anchoring via donor network control, and Asia-Pacific market presence respectively. These entities occupy positions where plasma traceability documentation serves as the decisive competitive filter for hospital procurement. Johnson & Johnson and Medtronic PLC represent diversified conglomerates competing on operating room integration and surgeon training protocols rather than raw material sourcing advantages.
| Leading Market Players |
|---|
| Medtronic PLC |
| Asahi Kasei Corporation |
| Baxter International Inc |
| B.Braun SE |
| Octapharma AG |
| Johnson & Johnson |
| Pfizer Inc |
| Grifols S.A. |
| CSL Limited |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific cold chain corridors linking Los Angeles to Osaka and Rotterdam to Mumbai transmit temperature excursion risks that amplify price spreads between plasma-dependent and synthetic sealant tiers. These logistics cost dynamics concentrate pricing power with fractionators maintaining validated viral inactivation documentation while forcing hospital systems toward direct procurement contracts that bypass distributor markups.
Pricing Analysis
Certification level creates the primary spread between FDA-grade plasma-derived formulations and CE-marked synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects viral inactivation validation depth, with premium tiers commanding substantial markups for documented 4-log reduction protocols. Cost compression in standard-tier human-source products is intensifying because synthetic polymer alternatives achieve comparable burst strength in soft tissue applications. Ambulatory surgical centers exhibit highest price sensitivity due to constrained reimbursement schedules, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Export-control restrictions on plasma fractionation technology limit capacity expansion outside established United States, Germany, and Switzerland manufacturing clusters. Raw material supply draws from validated donor networks, viral inactivation reagent stocks, and specialized lyophilization equipment. Single-source vulnerability concentrates at major plasma collection centers where donor deferral policy changes cascade through downstream sealant production. Distribution runs through integrated delivery network direct contracts that displace traditional medical-surgical distributor channels for high-volume cardiac surgery accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fibrin glue penetration remains early-cycle in outpatient orthopedic settings, with arthroscopic technique diffusion providing sustained adoption tailwinds across ambulatory surgery networks.
For Market Incumbents: Insulate plasma supply advantages through captive donor network expansion in United States Midwest collection regions. Deepen backward integration into viral inactivation chemistry production to offset reagent cost volatility. Synthetic recombinant entrants threaten substitution in meniscal repair applications where immunogenicity profiles permit.
For New Entrants and Emerging Players: Yeast-expressed fibrinogen analogs for German university hospital orthopedic departments represent the most penetrable entry point, bypassing plasma sourcing constraints entirely. India's government hospital tenders for outpatient surgery expansion offer second-mover access ahead of multinational incumbent localization. Partner with domestic plasma fractionators for CDSCO registration pathway acceleration.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to monetize non-core biological sealant divisions. Long-term viability centers on recombinant platform economics achieving cost parity with plasma-derived alternatives. Monitor Japanese PMDA real-world outcome data requirements as inflection indicator for regulatory barrier escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Fractionation Partnership | CDSCO registration acceleration unlocks Indian government hospital procurement channels. |
| Recombinant Platform Development | Yeast-expressed fibrinogen analogs bypass FDA donor deferral policy constraints entirely. |
| Hospital System Direct Contracting | Texas and Florida integrated delivery networks displace distributor markups for cardiac surgery volumes. |
| EMA MDR Class III Re-certification | Fresh clinical evidence requirements filter market access for legacy biological sealant portfolios. |
| Japanese Pharmacovigilance Infrastructure | PMDA real-world outcome data mandates consolidate purchasing around established compliance architectures. |
Methodological Framework
The analysis maps plasma-derived, recombinant, and synthetic-biological hybrid sub-sectors, each validated through procurement directors at integrated delivery networks, cardiac surgery department heads, orthopedic arthroscopy specialists, and plasma fractionation operations executives. Primary interview findings triangulate against FDA 510(k) filings, EMA MDR technical documentation, hospital GPO contract databases, and plasma collection center regulatory submissions. Bottom-up demand modeling from surgical procedure volumes reconciles with top-down manufacturer revenue segmentation across product type, application, and delivery mode dimensions.
Forecast assumptions hold fixed current FDA donor deferral geography exclusions and EMA MDR re-certification timelines while varying synthetic polymer efficacy thresholds and recombinant production cost curves over the projection horizon. Segmentation modeling incorporates sourcing technology, surgical specialty, end-user site-of-care, and regional regulatory cluster dimensions. CAGRs derive from procedure volume elasticity to technique standardization and reimbursement tier adjustments.
Practitioners should monitor viral inactivation validation study delays and synthetic polymer burst strength equivalence claims for early signals of competitive displacement. Forecasts reflect assumptions of sustained plasma collection economics and stable regulatory pathway differentiation. Material shifts in recombinant production cost structures or unified global biological device standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market