
 Tranexamic Acid API Market | 2026-2036
Tranexamic Acid API Market Size, Share, and Industry Trends Forecast 2026-2036
Tranexamic Acid API Market Insights
Pharmaceutical-grade USP specification compliance is collapsing the supplier base toward certified manufacturers. Kyowa Pharma Chemical leverages its synthetic amino acid expertise to sustain Japanese pharmacopeia registrations across multiple export markets. Xian Libang Pharmaceutical anchors volume production through backward integration into key raw material precursors. Shilpa Medicare differentiates via dedicated oncology-grade API capabilities that command premium positioning in regulated channels.
Tranexamic acid API is the synthetic derivative of the amino acid lysine, produced through catalytic hydrogenation of p-aminomethylbenzoic acid intermediates to achieve purity thresholds exceeding 99.5% for injectable applications. The compound functions primarily as a plasmin inhibitor to reduce bleeding in surgical and trauma protocols. Injectable formulations dominate value capture due to sterility validation costs and aseptic processing requirements that create margin barriers. Surgical procedures applications represent the fastest-expanding demand pool as enhanced recovery after surgery protocols expand transfusion-avoidance targets. Topical delivery modes remain nascent but attract development investment from dermatology-focused formulators seeking patent differentiation.
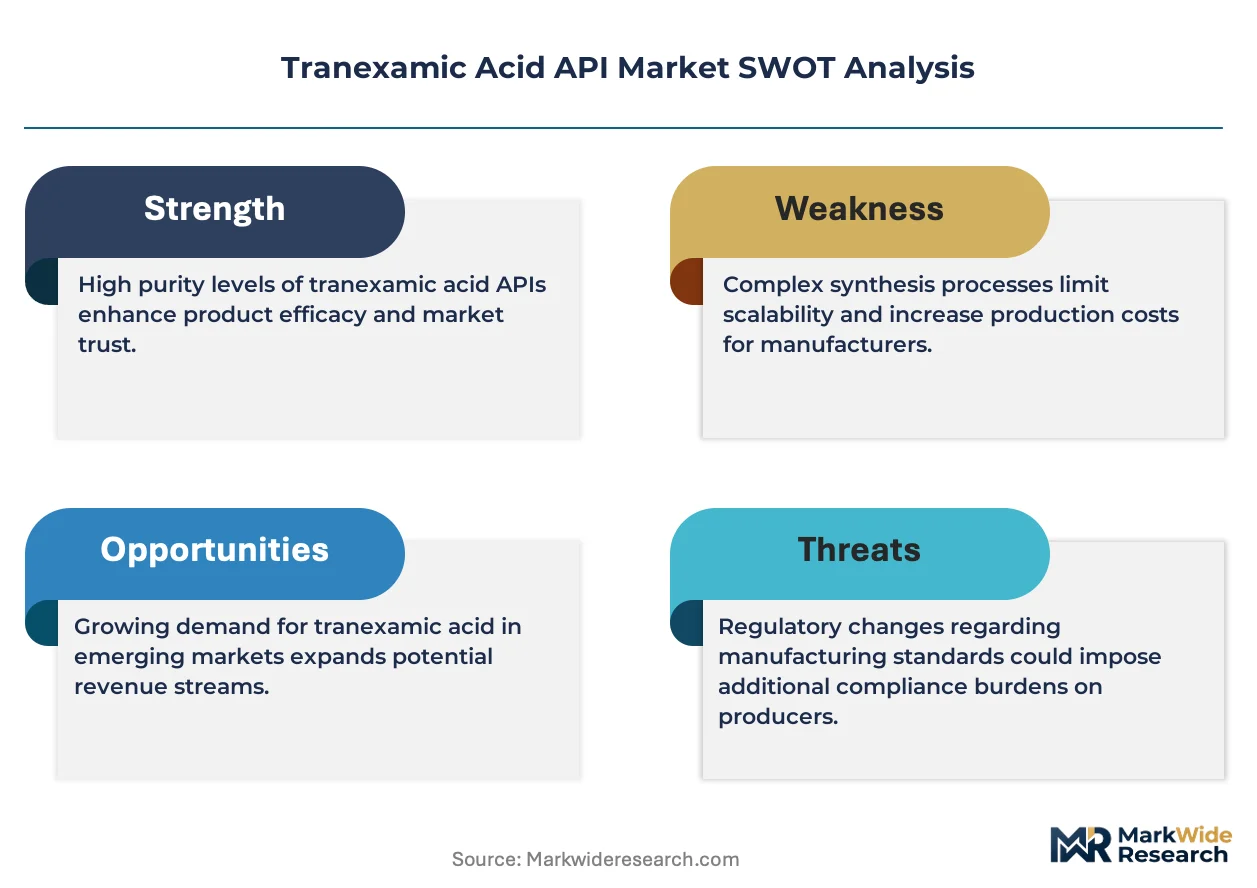
FDA enforces current Good Manufacturing Practice audits for active pharmaceutical ingredient facilities supplying US-distributed finished doses, while EMA's Active Substance Master File framework governs European market access through centralized quality documentation. India's CDSCO aligns with ICH Q7 guidelines for API export certification, creating convergent compliance burdens for multi-territory suppliers. Buyers must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to avoid batch rejection risks at customs clearance points.
Market Dynamics
Hospital procurement consolidation is concentrating purchasing power into integrated delivery networks, compressing supplier margins while simultaneously demanding sterility documentation that only certified API manufacturers can satisfy. This buyer-side concentration is restructuring competitive viability around pharmacopeial registration breadth rather than unit cost alone.
Growth Catalysts
- Enhanced Recovery After Surgery protocols:Transfusion-avoidance targets in perioperative care are expanding prophylactic tranexamic acid utilization across orthopedic and cardiac surgical suites in US hospital systems.
- CDSCO export certification alignment:India's adoption of ICH Q7 guidelines is streamlining multi-territory compliance for API suppliers serving regulated markets.
- Catalytic hydrogenation efficiency gains:Continuous-flow reactor adoption is reducing p-aminomethylbenzoic acid conversion costs for manufacturers with process chemistry capabilities.
Market Restraints
- Raw material precursor concentration:p-aminomethylbenzoic acid supply clusters among Chinese specialty chemical producers, exposing buyers to single-source disruption risk.
- Sterility validation cost escalation:Aseptic processing infrastructure requirements for USP-grade injectable APIs create capital barriers excluding mid-scale manufacturers.
- Topical formulation substitution:Advanced hemostatic agents and fibrin sealants are capturing select dermatology and dental applications where mucosal bleeding control is primary.
Strategic Opportunities
- Veterinary hemostasis applications:Off-label surgical use in equine and companion animal procedures represents an underpenetrated channel with reduced regulatory burden.
- EMA Active Substance Master File centralization:Harmonized European quality documentation is enabling single-registration access to multiple EU member state markets.
- Oncology-grade API premium tier:Dedicated manufacturing lines for cytotoxic-compatible tranexamic acid are commanding price premiums from formulators serving hematology protocols.
Industry Challenges
- Analytical method transfer complexity:Migrating impurity profiling from pharmacopeial to in-house validated methods delays batch release timelines for multi-territory suppliers.
- Sterile API containment engineering:Isolator technology implementation for potent compound handling requires specialized cleanroom construction expertise that concentrates among limited engineering firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tranexamic Acid API Market |
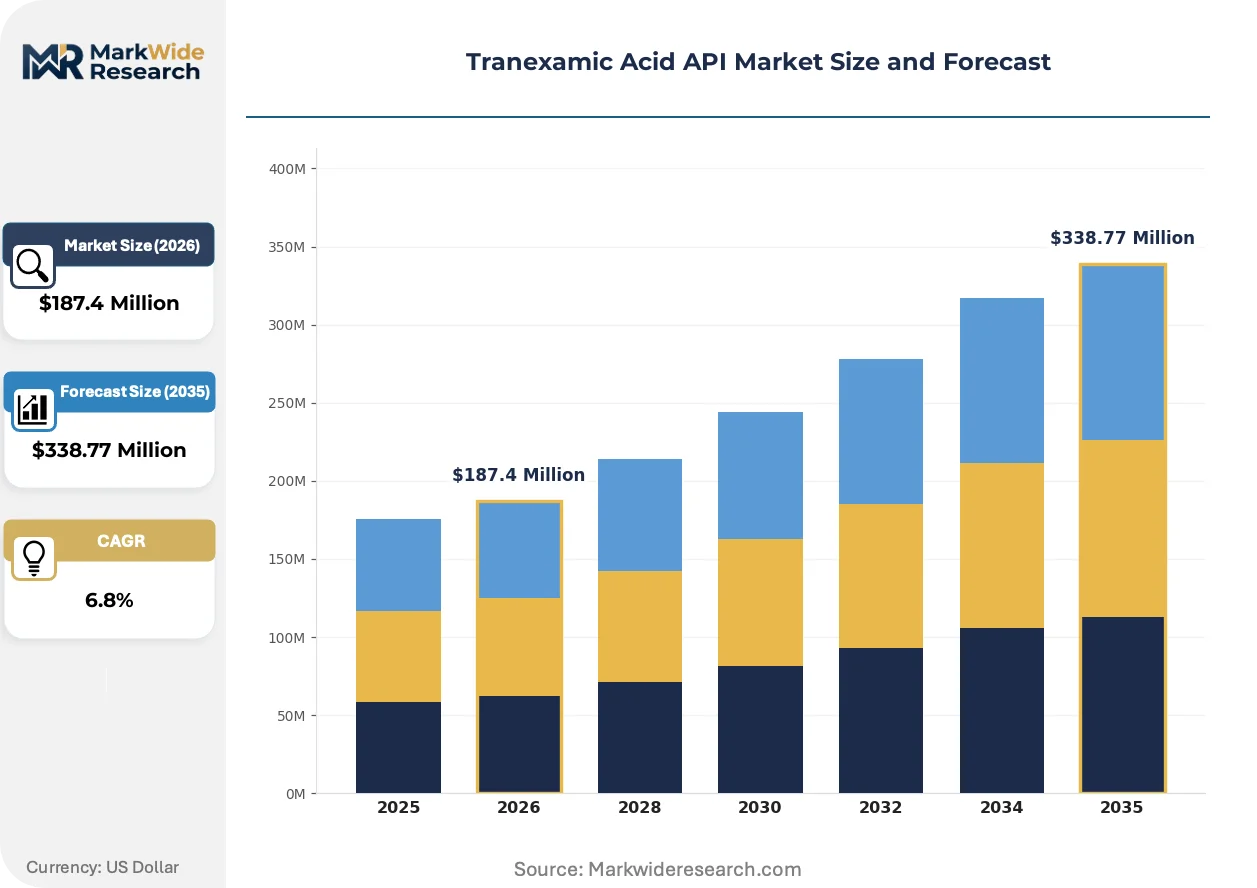
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
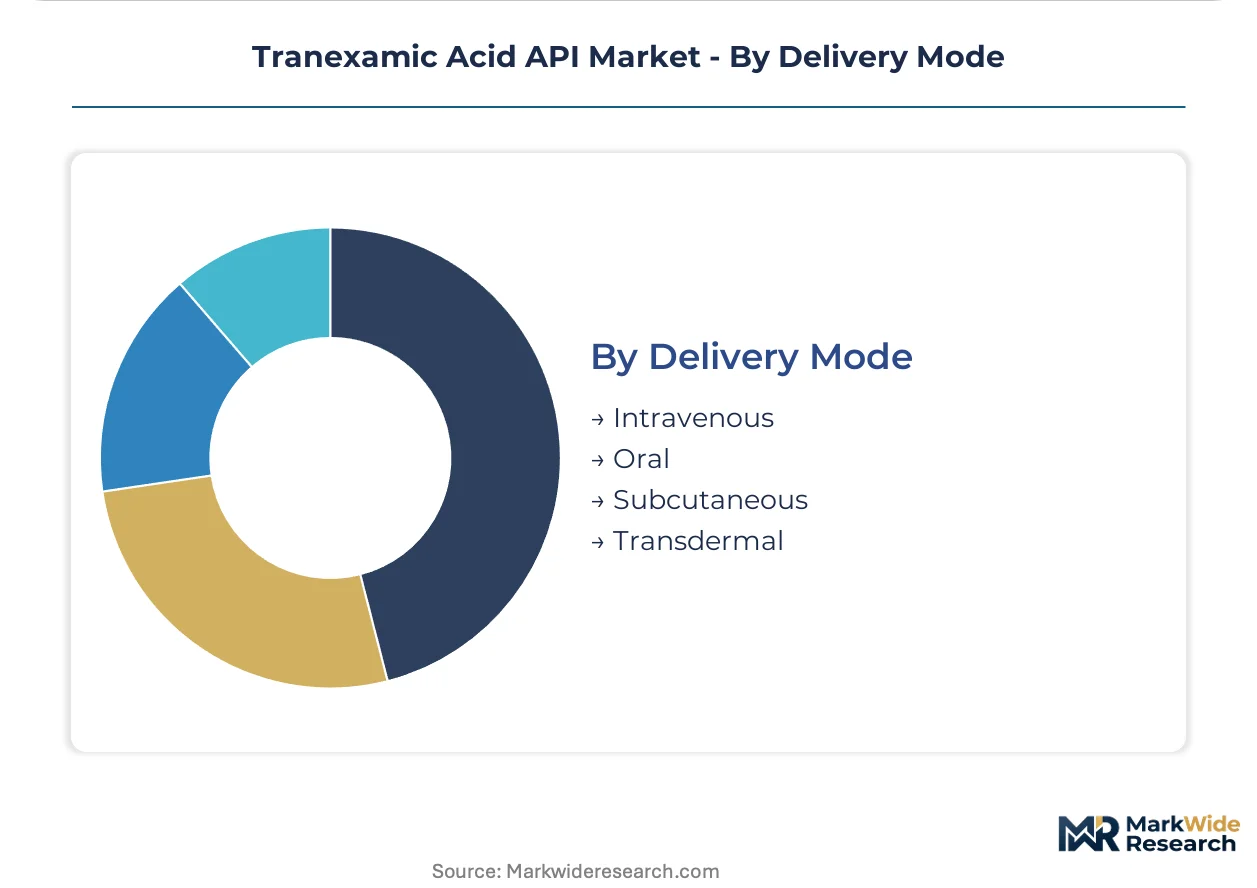
| Segmentation | Product Type: Injectable, Oral Tablet, Topical, Oral Solution Application: Coagulation Disorders, Surgical Procedures, Heavy Menstrual Bleeding, Trauma Management End User: Hospitals, Clinics, Home Care, Pharmacy Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal |
| Companies Covered | Xian Libang Pharmaceutical, Kyowa Pharma Chemical, Pfizer Inc, Metrochem API, Rochem International, Shilpa Medicare, Hangzhou Longshine Bio-Tech, Solara Active Pharma Sciences, Hunan Huateng Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tranexamic Acid API Market Trends and Innovations
Process analytical technology integration is transforming quality assurance from offline testing to real-time release, compressing manufacturing cycle times while tightening purity control. This shift is redefining competitive advantage around data infrastructure rather than scale alone.
Continuous manufacturing platforms are decomposing traditional batch-based API production economics. Mid-scale manufacturers in India and China are adopting flow chemistry for catalytic hydrogenation steps, reducing solvent waste and cycle times. This technology is decomposing the historical scale advantage of large-batch specialists, enabling nimbler producers to compete on total cost despite smaller absolute volumes.
EMA's revised Active Substance Master File guidance is mandating enhanced supply chain transparency for API starting materials. European finished dose manufacturers must now document geographic origin through specified intermediates. This policy is compressing acceptable vendor lists for EU-bound tranexamic acid, favoring suppliers with captive or long-contracted precursor supply.
Integrated delivery networks are consolidating injectable API procurement into multi-year sole-source agreements with mandatory sterility assurance documentation. Hospital systems in the United States are displacing fragmented purchasing through centralized pharmacy and therapeutics committees. This concentration is visible most acutely in tertiary surgical centers where transfusion protocol standardization drives formulary uniformity.
Tranexamic Acid API Market Segmentation
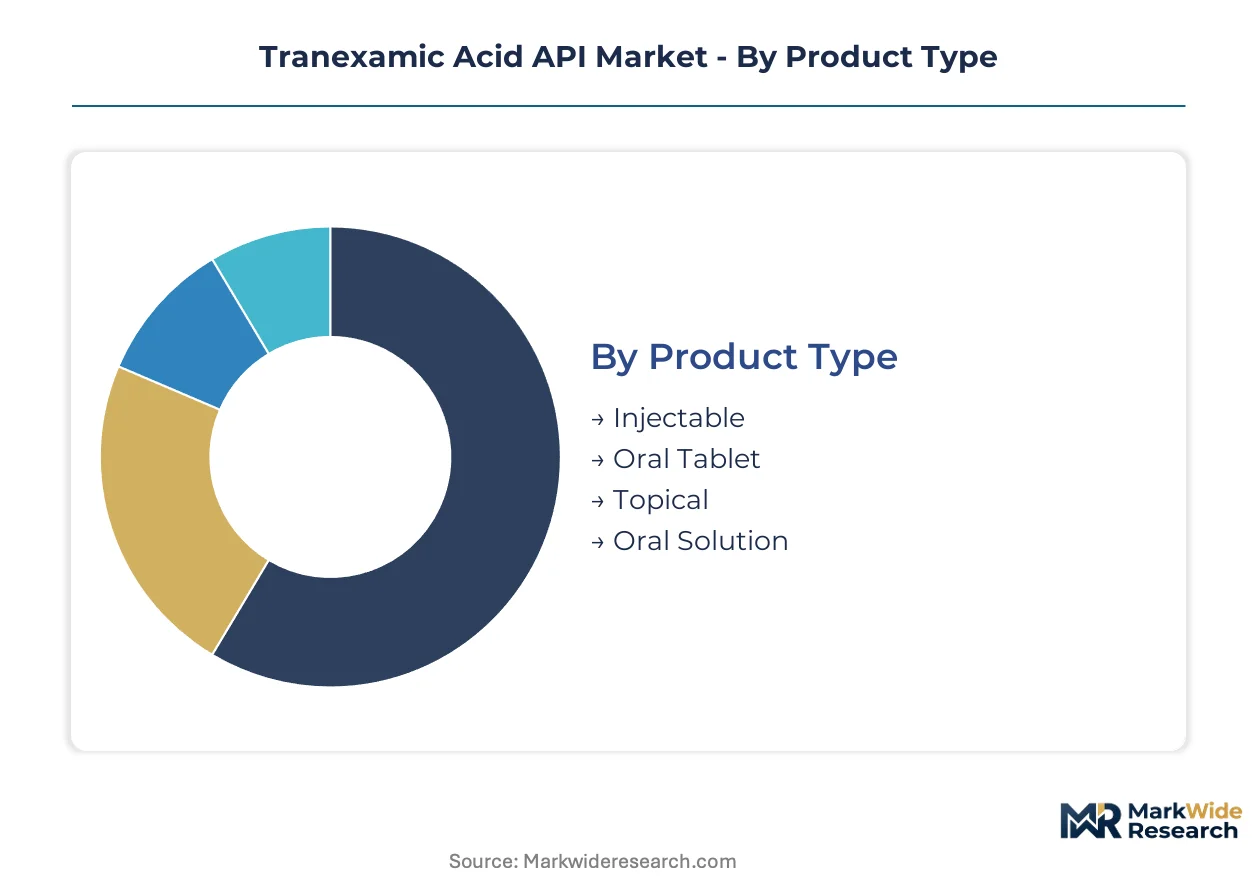
Segmentation in tranexamic acid API reveals how sterility requirements, formulation complexity, and end-use concentration reshape procurement economics. Each dimension exposes different margin vulnerabilities and competitive moats for certified manufacturers serving regulated markets.
Product Type:
Substitution pressure from advanced hemostatic agents and fibrin sealants varies sharply across formulation categories, with parenteral grades maintaining the strongest defensive position due to regulatory barriers.
- Injectable:USP-grade sterile API requiring aseptic processing and endotoxin testing below 0.03 EU/mg. Hospital procurement consolidation into integrated delivery networks concentrates demand for documented sterility assurance in US tertiary surgical centers.
- Oral Tablet:Non-sterile API with lower purity thresholds but compressed margins from commoditized excipient blending. Generic manufacturers in India source EP-grade material for European finished dose formulators seeking cost containment.
- Topical:Semi-solid compatible API grades with specialized particle size distribution for dermatological hemostasis gels.
- Oral Solution:Liquid formulation APIs requiring enhanced solubility profiles and stability data under ICH Q1A conditions.
Injectable anchors the volume base while topical gains share at the steepest rate as dermatology formulators seek patent differentiation.
Application:
Cost tier stratification separates premium-positioned surgical prophylaxis from commoditized menstrual bleeding management, with trauma protocols commanding emergency-use premiums.
- Surgical Procedures:Perioperative bleeding prophylaxis in orthopedic and cardiac suites under Enhanced Recovery After Surgery protocols. US hospital systems standardize tranexamic acid inclusion in transfusion-avoidance order sets, concentrating procurement through centralized pharmacy committees.
- Coagulation Disorders:Hereditary angioedema and fibrinolytic deficiency treatments requiring chronic administration. European hematology centers source EMA-registered API through Active Substance Master File holders with documented starting material provenance.
- Heavy Menstrual Bleeding:Gynecological indication with expanding over-the-counter availability pressuring API margins.
- Trauma Management:Pre-hospital and emergency department use in hemorrhage control protocols with military and civilian applications.
Surgical procedures anchor the value base while trauma management climbs the fastest as battlefield medicine protocols expand civilian adoption.
End User:
Customer type concentration determines documentation burden, with institutional purchasers demanding sterility validation that excludes uncertified suppliers.
- Hospitals:Integrated delivery networks and tertiary surgical centers with mandatory aseptic API documentation. FDA cGMP audit requirements filter approved vendor lists to manufacturers with isolator technology and real-time release testing capabilities.
- Clinics:Outpatient surgical facilities with intermediate sterility requirements and price-sensitive procurement through group purchasing organizations.
- Home Care:Self-administered oral and subcutaneous formulations with simplified cold chain logistics.
- Pharmacy:Compounding and retail dispensing channels with variable regulatory oversight across state and national jurisdictions.
Hospitals anchor the revenue base while home care expands most quickly as patient self-administration protocols reduce institutional bed utilization.
Delivery Mode:
Supply concentration in intravenous API manufacturing creates margin capture for sterile specialists, while oral routes face commoditization from multi-source generic competition.
- Intravenous:Parenteral-grade API with sterility assurance and particulate matter controls below USP <788> limits. CDSCO export certification alignment enables Indian manufacturers to serve US and EU markets through convergent ICH Q7 compliance.
- Oral:Conventional solid and liquid dosage form APIs with established pharmacopeial monographs and compressed pricing from high-volume Chinese producers.
- Subcutaneous:Injectable-grade material with modified release characteristics for extended bleeding prophylaxis.
- Transdermal:Novel permeation-enhanced formulations under development for mucosal and dermatological applications.
Intravenous anchors the margin base while transdermal shows the steepest development trajectory as formulation patents seek differentiation beyond generic parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for tranexamic acid clusters in Asian chemical processing hubs where catalytic hydrogenation capabilities and amino acid synthesis expertise overlap. Western pharmaceutical buyers are diversifying procurement across multiple jurisdictions to reduce single-source exposure.
China
Specialty chemical producers in Zhejiang and Hunan provinces dominate p-aminomethylbenzoic acid precursor supply, feeding downstream API conversion facilities. NMPA enforces current Good Manufacturing Practice audits for facilities supplying finished doses distributed domestically. Hangzhou and Changsha anchor the production corridor where continuous-flow reactor adoption is compressing conversion costs.
India
CDSCO export certification alignment with ICH Q7 guidelines enables API suppliers to serve US and EU markets through convergent compliance frameworks. Maharashtra and Telangana host sterile API manufacturing clusters where isolator technology investments filter competitive viability. Mumbai and Hyderabad concentrate EMA-registered manufacturers with documented starting material provenance for European buyers.
United States
FDA cGMP audits for active pharmaceutical ingredient facilities filter approved vendor lists to manufacturers with real-time release testing capabilities. Enhanced Recovery After Surgery protocols in tertiary surgical centers standardize tranexamic acid inclusion in transfusion-avoidance order sets. New Jersey and North Carolina house formulation specialists serving integrated delivery networks with multi-year sole-source agreements.
Japan
PMDA maintains Japanese pharmacopeia registrations that sustain export market access for synthetic amino acid specialists. Osaka and Tokyo metropolitan areas concentrate manufacturers leveraging fermentation-derived process chemistry expertise. METI industrial policy supports domestic API resilience through targeted supply chain security investments.
Germany
EMA Active Substance Master File centralization enables single-registration access to multiple EU member state markets for API holders with enhanced supply chain transparency. Bavaria and North Rhine-Westphalia host finished dose formulators sourcing EMA-registered tranexamic acid for hematology protocols. Frankfurt and Munich anchor the distribution corridor for sterile injectable APIs serving European hospital systems.
Tranexamic Acid API Market Competitive Landscape
Concentration sits with certified manufacturers capable of USP-grade sterility documentation and multi-territory pharmacopeial registrations. The supplier base compresses toward players with isolator technology and real-time release testing infrastructure. Three archetypes define competitive positioning: large-scale chemical processors with backward integration into precursors, specialized sterile API manufacturers with oncology-grade capabilities, and diversified pharmaceutical conglomerates with captive demand. Capacity expansion and pharmacopeial registration breadth represent the dominant competitive moves as hospital procurement consolidation elevates documentation requirements above unit cost.
Among Asian API specialists, Xian Libang Pharmaceutical and Shilpa Medicare exemplify the tier of manufacturers combining volume production with regulated-market certifications. Kyowa Pharma Chemical occupies a position representing Japanese pharmacopeia expertise across multiple export jurisdictions. These three entities anchor the competitive structure where synthetic amino acid process capabilities intersect with sterile manufacturing infrastructure requirements.
| Leading Market Players |
|---|
| Xian Libang Pharmaceutical |
| Kyowa Pharma Chemical |
| Pfizer Inc |
| Metrochem API |
| Rochem International |
| Shilpa Medicare |
| Hangzhou Longshine Bio-Tech |
| Solara Active Pharma Sciences |
| Hunan Huateng Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Multi-year sole-source agreements with integrated delivery networks lock in both supply access and price visibility for tranexamic acid API, binding hospital procurement committees to manufacturers with documented sterility assurance while insulating certified suppliers from spot-market volatility.
Pricing Analysis
FDA cGMP audit requirements dictate the pricing tier structure across the tranexamic acid API market. Three-tier pricing structure across premium, standard, and economy levels separates USP-grade sterile injectable from EP-grade oral and non-pharmacopeial technical grades. Price differentiation rests on isolator technology investment and real-time release testing capabilities. Cost compression in oral tablet grades is intensifying because high-volume Chinese producers saturate generic finished dose channels. Group purchasing organizations serving outpatient clinics exhibit highest price sensitivity, while tertiary surgical centers prioritize sterility documentation over unit cost.
Supply Chain Analysis
Inventory buffers for p-aminomethylbenzoic acid precursors extend lead times by three to six months, forcing API converters to carry working capital exposure through catalytic hydrogenation cycles. Manufacturing concentrates in China, India, and Japan, with Zhejiang province and Maharashtra state anchoring sterile processing clusters. Feedstock supply draws from Chinese specialty chemical producers concentrated in Hunan province. Single-source vulnerability in precursor supply exposes converters to disruption risk from environmental compliance inspections. Distribution runs through EMA-registered holders for European hospital systems and direct procurement channels for US integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow reactor adoption represents a technological inflection reshaping process economics, enabling mid-scale manufacturers to challenge large-batch specialists on total conversion cost while meeting tightening USP purity thresholds.
For Market Incumbents: Secure backward integration into p-aminomethylbenzoic acid precursors through long-term offtake contracts with Zhejiang and Hunan specialty chemical producers. Expand isolator technology capacity in Maharashtra and Telangana clusters to defend against emerging Indian competitors with CDSCO export certification. Sterility validation cost escalation creates margin protection for manufacturers with existing aseptic infrastructure. For New Entrants and Emerging Players: CDSCO export certification fast-track enables market entry through convergent ICH Q7 compliance serving both US and EU buyers. Veterinary hemostasis applications in equine and companion animal surgery represent underpenetrated white-space with reduced regulatory burden compared to human pharmaceutical channels. Target oncology-grade API tier where dedicated manufacturing lines command premium positioning from hematology formulators. For Investors and Strategic Acquirers: Capital is best deployed toward sterile API specialists with multi-territory pharmacopeial registrations and documented starting material provenance. Long-term viability over the projection horizon favors manufacturers combining synthetic amino acid process chemistry with isolator technology investments. Watch for EMA Active Substance Master File guidance revisions on supply chain transparency as inflection indicator for vendor list compression.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | Enables USP-grade sterile API production for FDA-audited hospital procurement channels. |
| Continuous-Flow Reactor Adoption | Reduces catalytic hydrogenation cycle times and solvent waste for p-aminomethylbenzoic acid conversion. |
| EMA Active Substance Master File Registration | Centralizes European market access through harmonized quality documentation for multiple EU member states. |
| Backward Integration into Precursors | Captive p-aminomethylbenzoic acid supply mitigates single-source disruption risk from Chinese environmental inspections. |
| Oncology-Grade Manufacturing Line Investment | Dedicated cytotoxic-compatible capacity commands price premiums from hematology protocol formulators. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at API manufacturers, hospital procurement managers in integrated delivery networks, formulary directors at tertiary surgical centers, and CDSCO certification specialists, then refined through secondary validation against FDA cGMP inspection databases, EMA Active Substance Master File registers, Indian customs export records, and USP monograph revision notices. Bottom-up volume estimates from catalytic hydrogenation capacity installations were triangulated against top-down demand projections from surgical procedure growth rates.
Variance decomposition across the modeling period isolates volume drivers by product type, application, end user, and delivery mode, with particular attention to sterility grade tier and regional regulatory cluster. CAGRs were derived from segmented growth trajectory analysis incorporating Enhanced Recovery After Surgery protocol adoption curves and CDSCO export certification alignment timelines. Forecast inputs include hospital procurement consolidation patterns and continuous-flow reactor penetration rates in Indian and Chinese manufacturing clusters.
Decision-makers should treat outputs as directional under assumptions of sustained FDA cGMP audit intensity and stable p-aminomethylbenzoic acid precursor supply; material deviation in environmental compliance enforcement or pharmacopeial harmonization progress would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market