
 North America Acrylic Adhesives Market | 2026-2036
North America Acrylic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acrylic Adhesives Market Analytics
Modular vehicle platform architectures is realigning how Tier-1 suppliers specify adhesive systems across bonded joints and mixed-material assemblies. 3M leverages its materials science portfolio to dominate structural bonding applications for electric vehicle battery enclosures. Henkel AG & Co. KGaA anchors its position through R&D intensity in reactive acrylic platforms tailored to aluminum-intensive body structures.
Acrylic adhesives comprise formulations built on polymethyl methacrylate or polyacrylate backbones, curing through evaporation, UV initiation, or two-part chemical reaction to deliver durable bonds across metals, plastics, and composites. Water-based acrylics lead volume in packaging and woodworking applications where low-VOC compliance is mandatory, while reactive acrylics capture premium margin pools in automotive structural assembly where cure speed and shear strength determine specification. Solvent-based grades retain niche positions in specialty coating applications though face substitution pressure from regulatory tightening.
EPA regulates volatile organic compound emissions under 40 CFR 59 for adhesive consumer products, while OSHA sets workplace exposure limits for residual monomers in manufacturing environments. Health Canada and PMRA coordinate cross-border chemical notification requirements that shape product registration timelines for suppliers operating in both markets. Stakeholders must monitor evolving state-level chemical disclosure rules and battery safety standards that will determine which acrylic platforms qualify for next-generation vehicle and energy storage applications.
Market Dynamics
EPA VOC regulations under 40 CFR 59 and California CARB standards are compressing solvent-based formulation margins while redirecting converter capital toward water-based and reactive acrylic platforms. This regulatory compression intersects with automotive lightweighting mandates to reshape specification patterns across bonded assembly applications.
Growth Catalysts
- Automotive Lightweighting Mandates:United States and Mexican OEMs are expanding bonded joints in mixed-material body structures to meet Corporate Average Fuel Economy standards, directly increasing structural acrylic consumption per vehicle.
- 40 CFR 59 Compliance Deadlines:EPA adhesive and sealant rules are forcing packaging converters toward water-based acrylics, eliminating solvent-based alternatives in consumer goods labeling and flexible packaging laminates.
- Electric Vehicle Battery Enclosure Bonding:Thermal management requirements for lithium-ion packs are creating specification pull for toughened acrylic systems that bond aluminum cooling plates to composite housings.
Market Restraints
- Acrylic Monomer Price Volatility:Feedstock exposure to propylene and methanol markets creates margin instability for formulators lacking backward integration into monomer production.
- Cure Speed Limitations in Cold Environments:Water-based acrylics face performance constraints below 10°C, restricting outdoor construction applications in Canadian prairie provinces and northern US states during winter months.
- Polyurethane Structural Adhesive Substitution:Two-part polyurethane systems capture load-bearing automotive applications where acrylics cannot match elongation-at-break requirements for crash-durable joints.
Strategic Opportunities
- Mexican Automotive Supplier Base:Queretaro and Guanajuato manufacturing corridors remain underpenetrated by reactive acrylic technical service teams, creating first-mover advantage for specification capture at expanding Tier-1 stamping and assembly operations.
- UV-Curable Acrylic Convergence with Digital Printing:Narrow-web label converters are integrating UV inkjet presses with inline UV acrylic coating stations, enabling single-pass production for premium cosmetic and pharmaceutical packaging.
- Inflation Reduction Act Clean Manufacturing Credits:Domestic content incentives for US-produced battery components are accelerating local adhesive formulation capacity investments to qualify for production tax credits.
Industry Challenges
- Formulation Chemist Talent Scarcity:Retirement waves among acrylic polymerization specialists are outpacing university pipeline output, particularly for radiation-cure and anaerobic platform expertise.
- Dual EPA-OSHA Compliance Complexity:Manufacturers must simultaneously satisfy 40 CFR 59 product emissions limits and OSHA permissible exposure limits for residual methyl methacrylate monomer in production environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acrylic Adhesives Market |
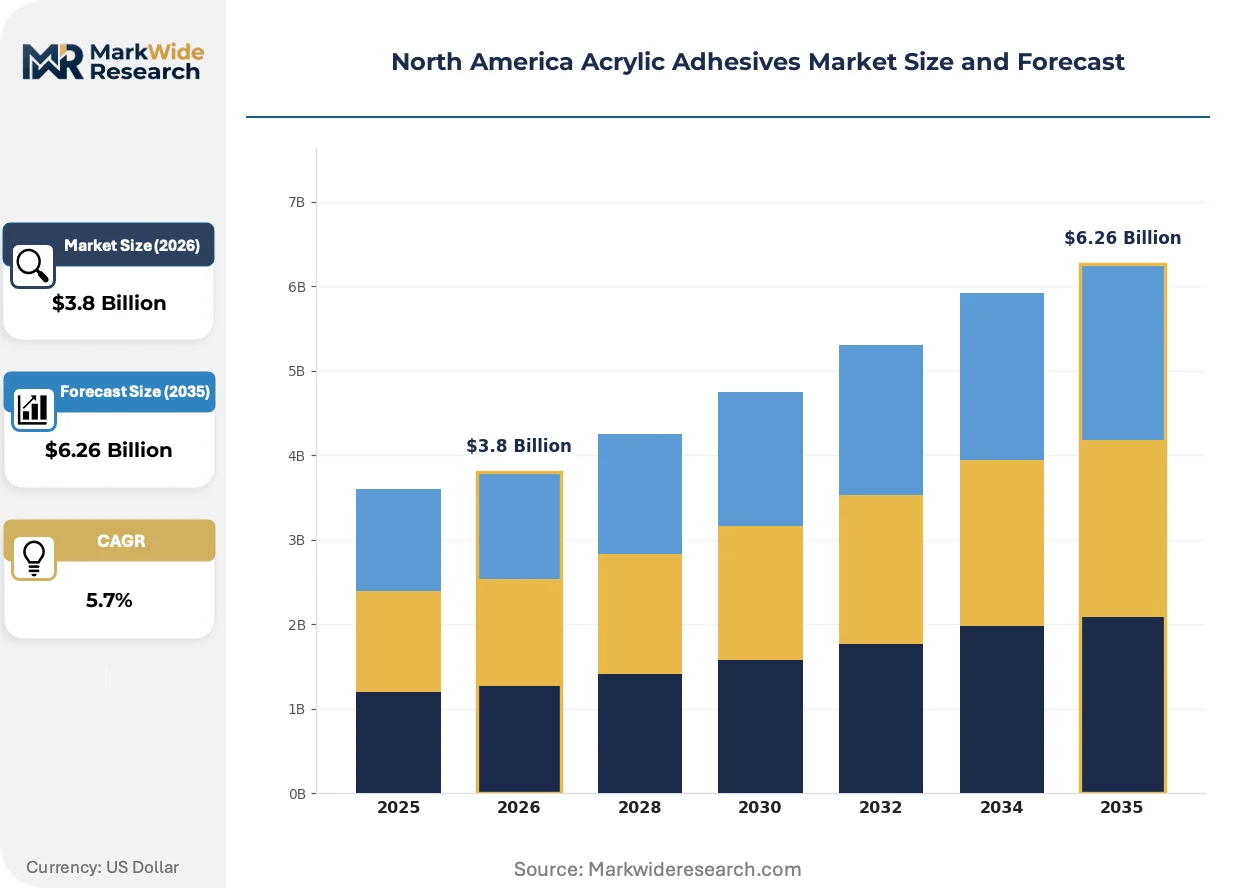
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Reactive, Structural End User: Automotive, Construction, Electronics, Healthcare Application: Packaging, Woodworking, Bonding, Coating Sales Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller, Sika AG, Arkema Group, Avery Dennison Corporation, Dow, Ashland, Adhesives Research Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acrylic Adhesives Market Evolving Landscape
Formulation science is pivoting toward systems that reconcile regulatory compression with performance escalation in structural bonding. Three convergent developments are redrawing competitive boundaries across technology platforms and end-use specifications.
Hybrid acrylic-urethane systems are expanding into automotive crash-durable applications previously reserved for pure polyurethane chemistries. Tier-1 suppliers in Michigan and Ontario are qualifying these systems for aluminum-to-carbon fiber joints where rapid fixture strength and controlled elongation must coexist. The technology is expanding into battery enclosure assembly lines where cure-on-demand flexibility reduces work-in-process inventory.
California CARB SCM 2007.0 and subsequent amendments are tightening VOC limits for adhesive products used in consumer goods and building materials. Formulators serving the US West Coast market are reformulating solvent-based pressure-sensitive adhesives into UV-curable or hot-melt acrylic alternatives to maintain shelf placement at major retailers. The regulation is compressing product development cycles as compliance deadlines approach for architectural panel and flooring installation categories.
Specification authority is migrating from converter procurement departments to OEM engineering teams conducting joint design-for-manufacturing reviews. Automotive platform engineers in Detroit and Stuttgart design studios now dictate adhesive selection during body-in-white concept phases, displacing traditional spot-buy patterns. This shift is most visible in electric vehicle programs where battery pack sealing and thermal interface bonding require early adhesive integration into CAD models and simulation workflows.
North America Acrylic Adhesives Market Segmentation
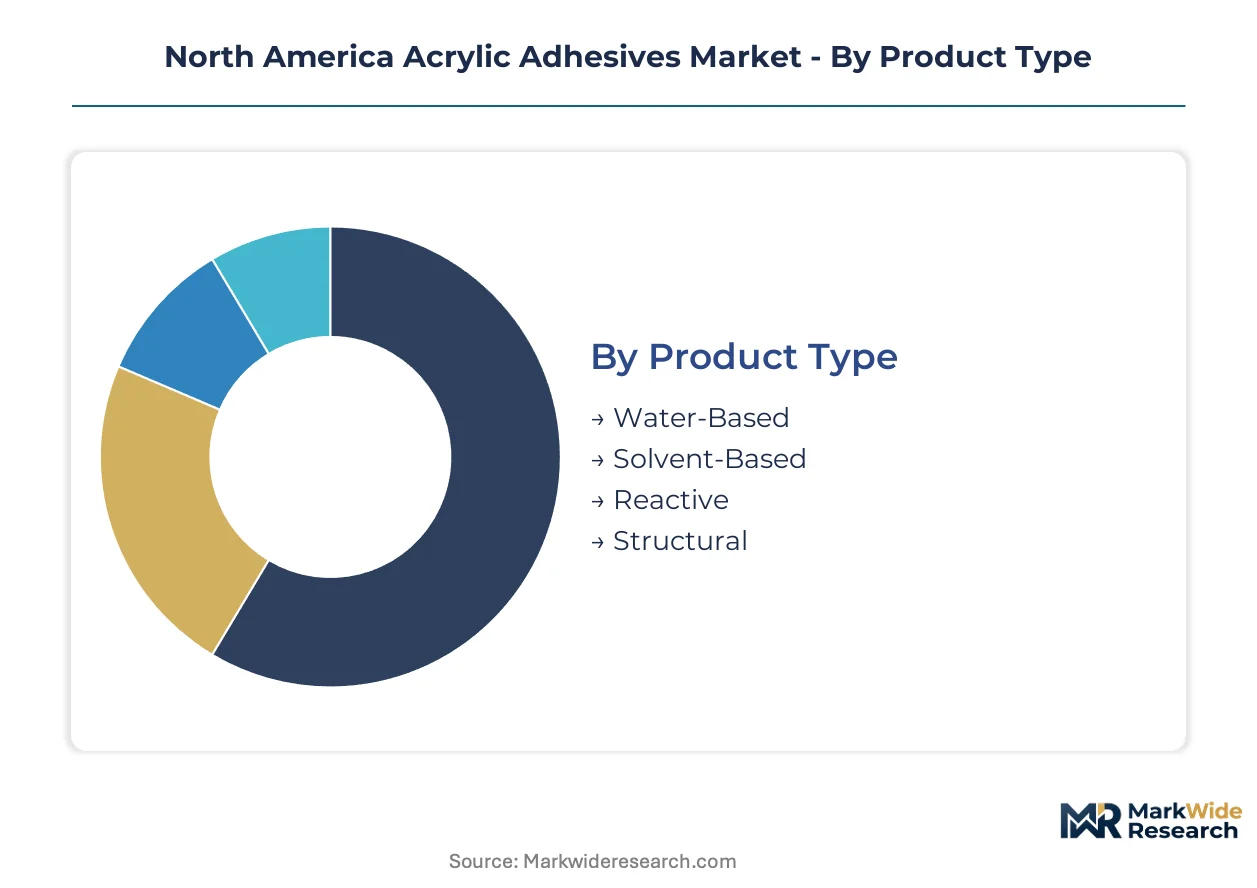
Acrylic adhesive specification patterns diverge sharply between commodity converters seeking regulatory compliance and automotive engineers demanding structural performance. Understanding these segment boundaries clarifies where formulation investments concentrate versus where price competition dominates procurement decisions.
Product Type:
Integration depth varies from standalone surface applications to embedded reactive systems curing within multi-material assemblies.
- Water-Based:Emulsion polymers suspended in aqueous carriers deliver low-VOC bonding for paper, film, and wood substrates. EPA 40 CFR 59 compliance deadlines are eliminating solvent alternatives in flexible packaging operations across Michigan and Ohio, redirecting converter capital toward water-based lines. Volume placements concentrate in Water-Based; the faster expansion belongs to Reactive.
- Solvent-Based:Solutions of acrylic polymers in organic carriers retain adhesion to low-surface-energy plastics where water-based systems fail. CARB SCM 2007.0 amendments are compressing shelf space for these formulations in California retail channels, forcing reformulation investments or market exit.
- Reactive:Two-part systems polymerizing through chemical reaction achieve structural strength in metal and composite bonding. Cure-on-demand flexibility reduces work-in-process inventory in Ontario automotive assembly lines.
- Structural:Toughened formulations engineered for load-bearing joints in crash-durable applications. Thermal management requirements for lithium-ion battery enclosures are pulling specification authority toward these premium platforms.
Water-Based dominates packaging tonnage; Reactive captures value growth in bonded vehicle structures.
End User:
Customer sophistication tiers separate specification-driven OEM engineering from procurement-led converter buying.
- Automotive:Mixed-material body-in-white assembly and electric vehicle battery enclosure bonding demand rapid-fixture reactive systems. Corporate Average Fuel Economy standards in the United States and Mexico are expanding bonded joint applications per vehicle platform.
- Construction:Pressure-sensitive tapes and sealants for building envelope applications face cure speed limitations below 10°C, restricting winter specification in Canadian prairie provinces and northern US states.
- Electronics:UV-curable acrylics enable precise coating of circuit boards and display laminates without thermal damage to sensitive components.
- Healthcare:Medical-grade acrylics for device assembly and transdermal patch construction require ISO 10993 biocompatibility certification and FDA master file submission.
Automotive commands formulation R&D priority; Healthcare maintains the steepest margin tier despite smaller volume.
Application:
Process integration determines whether adhesives function as standalone finishes or embedded bonding layers.
- Packaging:Label laminates and flexible film constructions consume water-based pressure-sensitive adhesives in high-speed converting operations. CARB compliance deadlines are accelerating solvent-to-water transitions in California labeling facilities.
- Woodworking:Furniture and cabinet assembly utilize PVA-acrylic hybrid emulsions where bond line visibility and sandability matter.
- Bonding:Structural assembly of dissimilar materials in transportation and industrial equipment relies on reactive and toughened acrylic platforms.
- Coating:Protective and decorative finishes for architectural panels and flooring installations face tightening VOC limits under California SCM amendments.
Packaging anchors volume demand; Bonding applications are climbing the fastest as vehicle lightweighting accelerates.
Sales Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to manufacturing.
- Online:E-procurement platforms serve small-volume MRO buyers and research laboratories seeking rapid sample acquisition.
- Retail:Big-box and specialty hardware channels distribute consumer-grade caulks, tapes, and repair kits with limited technical support.
- Distributors:Regional chemical distributors maintain local inventory and application expertise for mid-tier converters and fabricators.
- Direct Sales:Manufacturer technical teams engage directly with OEM engineering groups for specification capture in automotive and electronics programs.
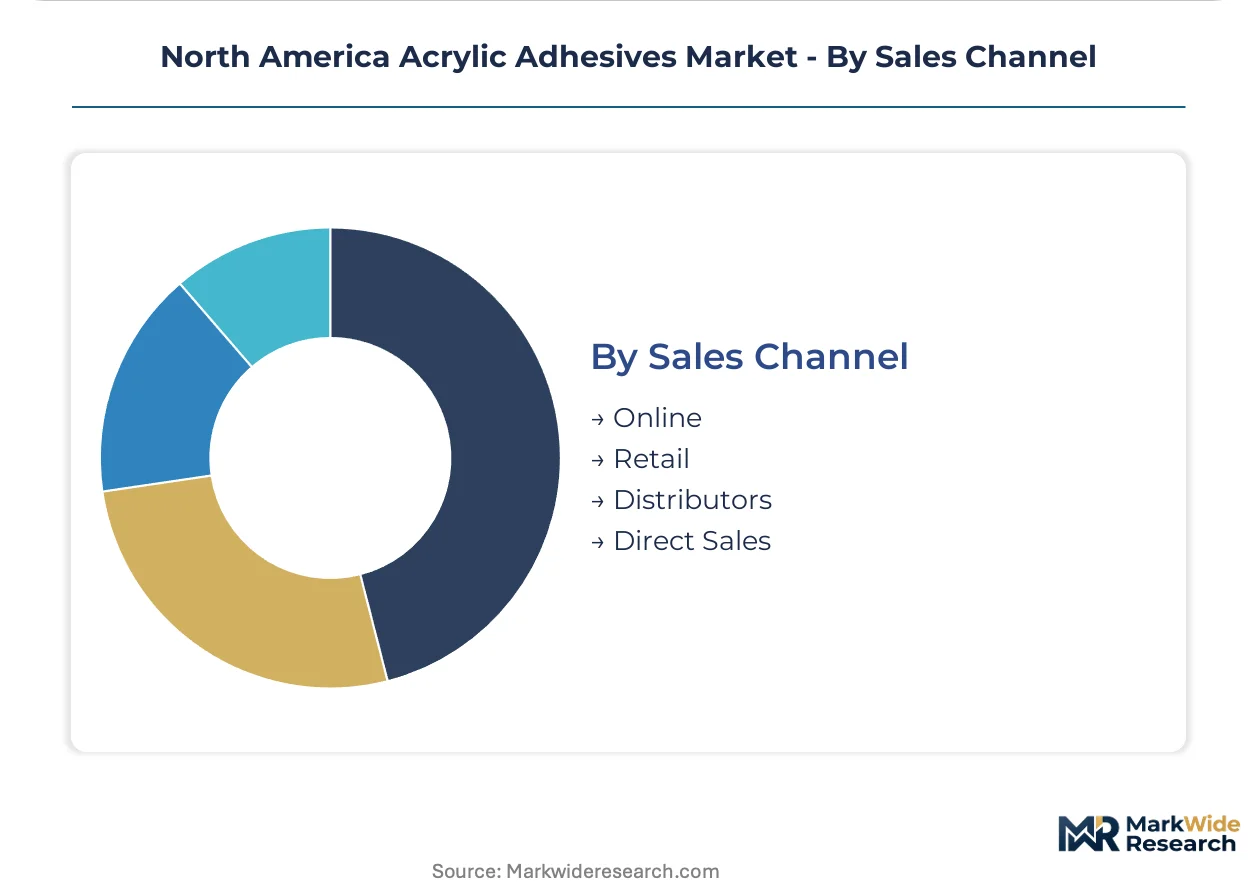
Distributors handle the bulk of converter volume; Direct Sales commands strategic priority for platform-level adhesive specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-Mexico-Canada Agreement manufacturing incentives are concentrating adhesive demand across integrated automotive corridors spanning the Great Lakes and central Mexican industrial zones.
United States
Corporate Average Fuel Economy standards and Inflation Reduction Act battery manufacturing credits are expanding bonded assembly lines. EPA 40 CFR 59 compliance deadlines are eliminating solvent-based alternatives in Michigan and Ohio packaging converters. The Great Lakes automotive corridor spanning Detroit, Toledo, and Cleveland anchors structural acrylic specification for electric vehicle platforms.
Canada
Battery supply chain investments in Ontario and Quebec are pulling demand for thermal interface bonding systems. Health Canada and PMRA coordinate cross-border chemical notification requirements with US EPA timelines. The Windsor-Toronto-Oshawa manufacturing triangle concentrates automotive adhesive technical service operations for Detroit Three platform engineering.
Mexico
OEM assembly expansion in Querétaro and Guanajuato is creating specification opportunities at Tier-1 stamping operations. Mexican environmental regulations under SEMARNAT are tightening VOC limits for imported adhesive formulations. The Bajío automotive cluster around Silao and Irapuato remains underpenetrated by reactive acrylic application engineering teams.
North America Acrylic Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The market structure concentrates around multinational chemical conglomerates with backward integration into monomer production, mid-cap regional formulators serving converter niches, and specialized tape manufacturers with captive coating capacity. Competitive moves center on geographic expansion into Mexican automotive corridors and portfolio diversification into UV-curable and hybrid acrylic-urethane platforms.
Among diversified materials conglomerates, 3M and Henkel AG & Co. KGaA exemplify the integrated archetype combining monomer supply control with OEM specification authority. Dow and Arkema Group occupy positions bridging commodity polymer supply and specialty formulation. H.B. Fuller and Sika AG represent the mid-cap focused specialists concentrating technical service resources on automotive and construction verticals respectively.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller |
| Sika AG |
| Arkema Group |
| Avery Dennison Corporation |
| Dow |
| Ashland |
| Adhesives Research Inc. |
| Others |
Value Network & Pricing Analysis
California CARB SCM 2007.0 amendments gate qualified supply and premium-tier pricing access by forcing solvent-based formulators toward water-based and UV-curable platforms, compressing margins for non-compliant players while rewarding early reformulation investments with shelf placement at major retailers.
Pricing Analysis
Margin tightening in water-based grades reflects feedstock exposure to propylene and methanol markets, while reactive acrylics command premium positioning through crash-durable certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified medical grades from industrial commodity formulations. Cost-down pressure on packaging converters accelerates because EPA 40 CFR 59 compliance deadlines eliminate solvent alternatives. Small-volume MRO buyers exhibit highest price sensitivity; OEM engineering teams prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Saudi Arabian propylene derivatives and German specialty monomer suppliers feeding North American formulation plants. Raw material flows draw from Texas Gulf Coast petrochemical complexes, Alberta natural gas liquids, and imported acrylate esters. Logistics chokepoints concentrate at Port Houston and rail terminals serving Michigan automotive corridors. Distribution runs through regional chemical distributors maintaining local inventory for mid-tier converters, with direct manufacturer engagement for OEM specification capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EPA 40 CFR 59 and California CARB standards erect barrier-to-entry moats favoring formulators with capital reserves for reformulation and certification investments.
For Market Incumbents: Acquire technical service teams specializing in reactive acrylic platforms for aluminum-intensive body structures. Consolidate specification authority at Detroit Three platform engineering departments before hybrid acrylic-urethane systems displace pure chemistries. Deepen captive supply of methyl methacrylate monomer to insulate margins from propylene volatility. For New Entrants and Emerging Players: Regional distributors in Querétaro and Guanajuato represent the most penetrable channel partner type for specification capture at expanding Tier-1 stamping operations. Target battery enclosure bonding applications where thermal management requirements outpace incumbent technical service capacity. Lead with UV-curable platforms for narrow-web label converters integrating inline coating with digital printing presses. For Investors and Strategic Acquirers: OEM engineering team takeover of adhesive specification authority is the leading indicator that platform-level contract values will concentrate among qualified suppliers. Five-to-ten year viability favors mid-cap formulators with backward integration into monomer production and ISO 10993 certification pathways. Watch for Inflation Reduction Act domestic content credit qualification as inflection signal for US formulation capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive supply of methyl methacrylate insulates margins from propylene price swings at Gulf Coast crackers. |
| Reactive Acrylic Technical Service Expansion | On-site application engineering in Mexican Bajío cluster captures specification authority at new Tier-1 facilities. |
| UV-Curable Platform Development | Inline coating compatibility with narrow-web digital presses opens premium cosmetic and pharmaceutical packaging segments. |
| ISO 10993 Biocompatibility Certification | Medical-grade qualification for transdermal patches and device assembly commands steepest margin tier in healthcare vertical. |
| Water-Based Formulation Capacity Addition | EPA 40 CFR 59 compliance positions converters for flexible packaging laminates in Michigan and Ohio corridors. |
Research Methodology
Independent corroboration across adhesive formulator R&D directors, Tier-1 supplier procurement managers, and OEM platform engineers underwrites the qualitative findings. Secondary validation draws from EPA regulatory filings, ACC industry statistics, SEC 10-K disclosures from diversified materials conglomerates, and customs trade data tracking acrylic monomer flows. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down production capacity assessments across US Gulf Coast and Canadian petrochemical corridors.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, end-use industry, application method, and regional production hub. CAGRs derive from regression analysis against automotive production forecasts, packaging converter capital expenditure cycles, and regulatory compliance timeline modeling. Industry-specific inputs include Corporate Average Fuel Economy standard stringency projections and Inflation Reduction Act battery manufacturing credit qualification criteria.
Caveats apply where acrylic monomer price volatility, Mexican environmental regulatory tightening under SEMARNAT, or cold-weather cure speed limitations in Canadian prairie provinces could materially shift the outlook. Deviation in EPA enforcement intensity or California CARB amendment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Waterproofing Admixture Market