
 Adhesives and Sealants Market | 2026-2036
Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesives and Sealants Market Intelligence
The EU Green Deal is recalibrating procurement criteria across European construction and automotive supply chains, pushing formulators toward low-VOC and bio-based chemistries. Henkel AG & Co. KGaA anchors its position through backward integration into resin synthesis and regional compounding networks. Sika AG specializes in construction-grade systems, leveraging its geographic density in European infrastructure repair. Dow Inc. competes on acrylic and silicone platforms, sustaining R&D intensity in pressure-sensitive adhesives for electronics.
Adhesives and sealants are polymeric or elastomeric substances formulated to bond substrates or fill gaps through surface wetting, chemical curing, or pressure activation, with bond strengths typically ranging from 0.1 MPa for pressure-sensitive tapes to 40 MPa for structural epoxies. Their primary purpose is to replace mechanical fasteners, reduce assembly weight, and provide environmental sealing across industrial and consumer applications. Polyurethane dominates volume in construction and automotive assembly due to its toughness and cure-rate flexibility, while silicone captures premium margin pools in aerospace and electronics thermal management where temperature stability exceeds 200°C. Acrylic formulations lead growth in electronics and medical device bonding, driven by UV-cure speed and optical clarity requirements.
EPA VOC regulations in the United States and REACH in Europe restrict solvent content and mandate hazard communication, forcing reformulation investments and reshaping raw material sourcing. China's SAMR enforces GB standards for construction adhesive emissions, creating compliance barriers for imported products. Japan's METI promotes JIS-certified sealants in public infrastructure, reinforcing quality-based procurement. Stakeholders must monitor regulatory divergence across these jurisdictions to align product portfolios with diverging permissible chemistries and testing protocols.
Market Dynamics
Automotive OEMs in Germany and Japan are systematically replacing welded joints with bonded assemblies to cut vehicle weight and improve crash energy absorption, forcing adhesive formulators to engineer structural epoxies that cure in seconds on robotic lines.
Growth Catalysts
- REACH compliance acceleration:European ECHA restrictions on solvent content are pushing formulators toward waterborne and hot-melt systems. Construction contractors in France and Germany now specify low-VOC products as default.
- EV battery thermal management:Automotive battery packers in China's eastern manufacturing corridor are sourcing silicone gap fillers and thermally conductive adhesives at scale to manage cell-to-cell heat transfer.
- Japan's infrastructure renewal:METI-certified JIS sealants are mandatory in public bridge and tunnel repair contracts, creating anchored demand for high-performance polyurethane and modified silicone systems.
Market Restraints
- Petrochemical feedstock volatility:Polyols and isocyanates for polyurethane production fluctuate with crude oil and natural gas pricing, compressing margin predictability for mid-sized compounders.
- Chinese domestic supply concentration:Silicone intermediates and organotin catalysts cluster in Jiangsu and Shandong provinces, exposing non-Chinese formulators to geographic supply risk and export license delays.
- Cure-speed limitations in ambient conditions:Moisture-cure silicones and two-part epoxies face throughput constraints in high-humidity or low-temperature construction environments, limiting substitution of mechanical fasteners.
Strategic Opportunities
- India's electronics manufacturing expansion:PLI scheme incentives for smartphone and semiconductor assembly in Tamil Nadu and Karnataka are creating demand for UV-cure acrylics and anisotropic conductive films.
- EU Green Deal bio-based procurement:Public construction tenders in Italy and Spain now weight bio-based content in scoring, rewarding formulators with certified epoxy and polyurethane feedstocks from non-petroleum sources.
- Building-integrated photovoltaics:Solar laminate manufacturers in South Korea are adopting optically clear, UV-stable encapsulant adhesives that bond glass to photovoltaic cells without frame rails.
Industry Challenges
- Formulation chemist shortage:Specialized expertise in rheology modification and cure kinetics is scarce across European and North American R&D centers, lengthening product development cycles.
- Multi-jurisdiction certification burden:Construction adhesives require separate fire-rated testing under EN 13501 in Europe, ASTM E84 in the United States, and GB 8624 in China, multiplying compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesives and Sealants Market |
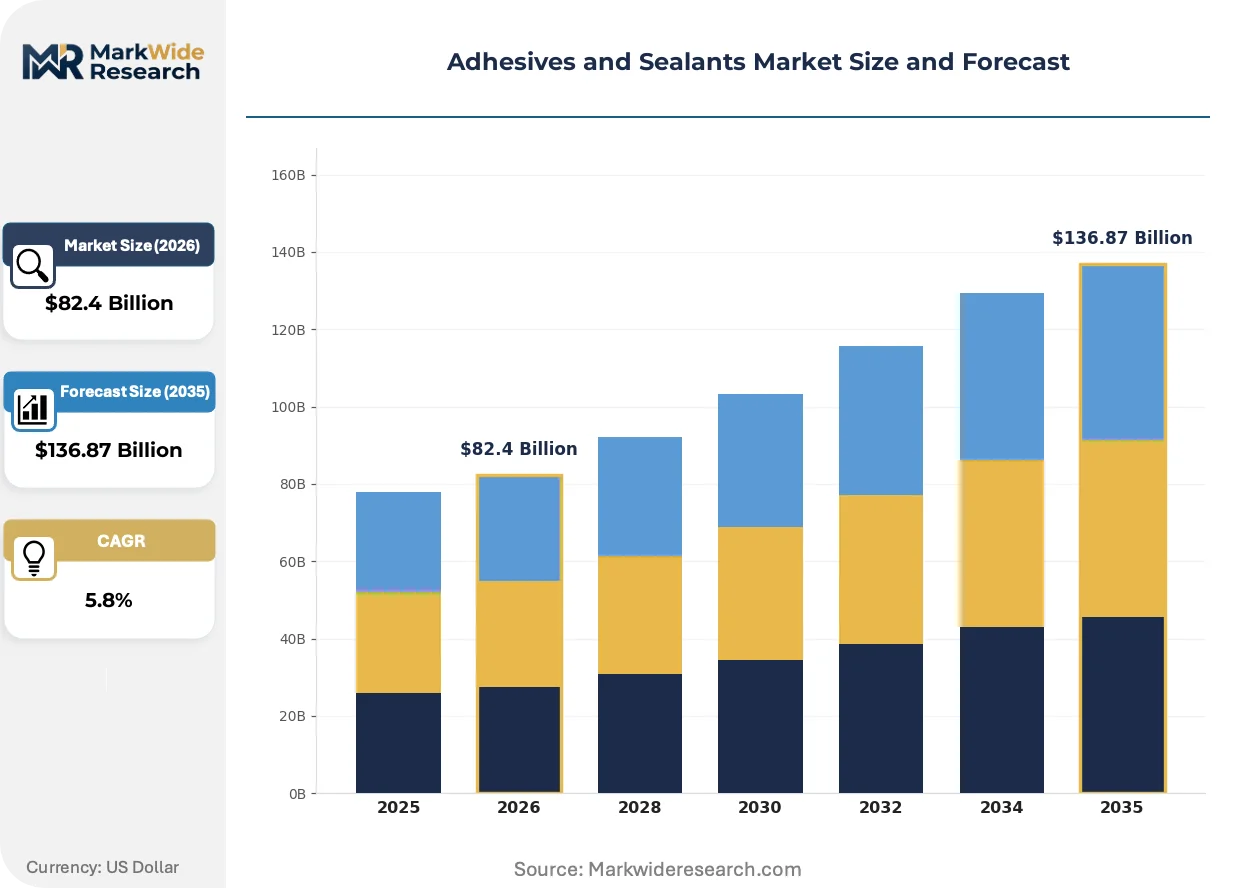
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $136.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Acrylic Application: Construction, Automotive, Aerospace, Electronics End User: Manufacturers, Contractors, DIY Consumers, Distributors Form: Liquid, Paste, Film, Spray |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller Company, Arkema S.A., Dow Inc., Huntsman Corporation, Avery Dennison Corporation, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesives and Sealants Market Strategic Shifts & Innovations
Formulators are engineering adhesives that function as structural elements rather than assembly aids, embedding sensing capabilities and enabling circular disassembly through reversible chemistries.
UV-LED curing technology is converging with oxygen-tolerant photoinitiator systems to enable instant bonding of transparent medical device components and electronics displays. Medical device manufacturers in Switzerland and Germany are retrofitting production lines with 395nm LED arrays. This convergence is compressing cycle times from minutes to seconds while eliminating thermal damage to heat-sensitive substrates.
The EPA's evolving VOC rules under the Clean Air Act are forcing architectural sealant producers to eliminate aromatic solvents and certain glycol ethers from sprayable formulations. Coatings and adhesive manufacturers serving the US construction sector are reformulating with exempt compounds and higher solids content. Southern California's SCAQMD district enforces the strictest limits, creating a regulatory laboratory that prefigures national standards.
Automotive Tier-1 suppliers are consolidating adhesive specifications across platform programs, reducing approved vendor lists from dozens to handfuls. Procurement teams at German and Japanese OEMs now mandate single-source accountability for bonded joint performance, displacing fragmented multi-supplier arrangements. This concentration is most visible in battery pack assembly, where cell-to-cell bonding and module encapsulation are awarded as integrated system contracts.
Adhesives and Sealants Market Segmentation
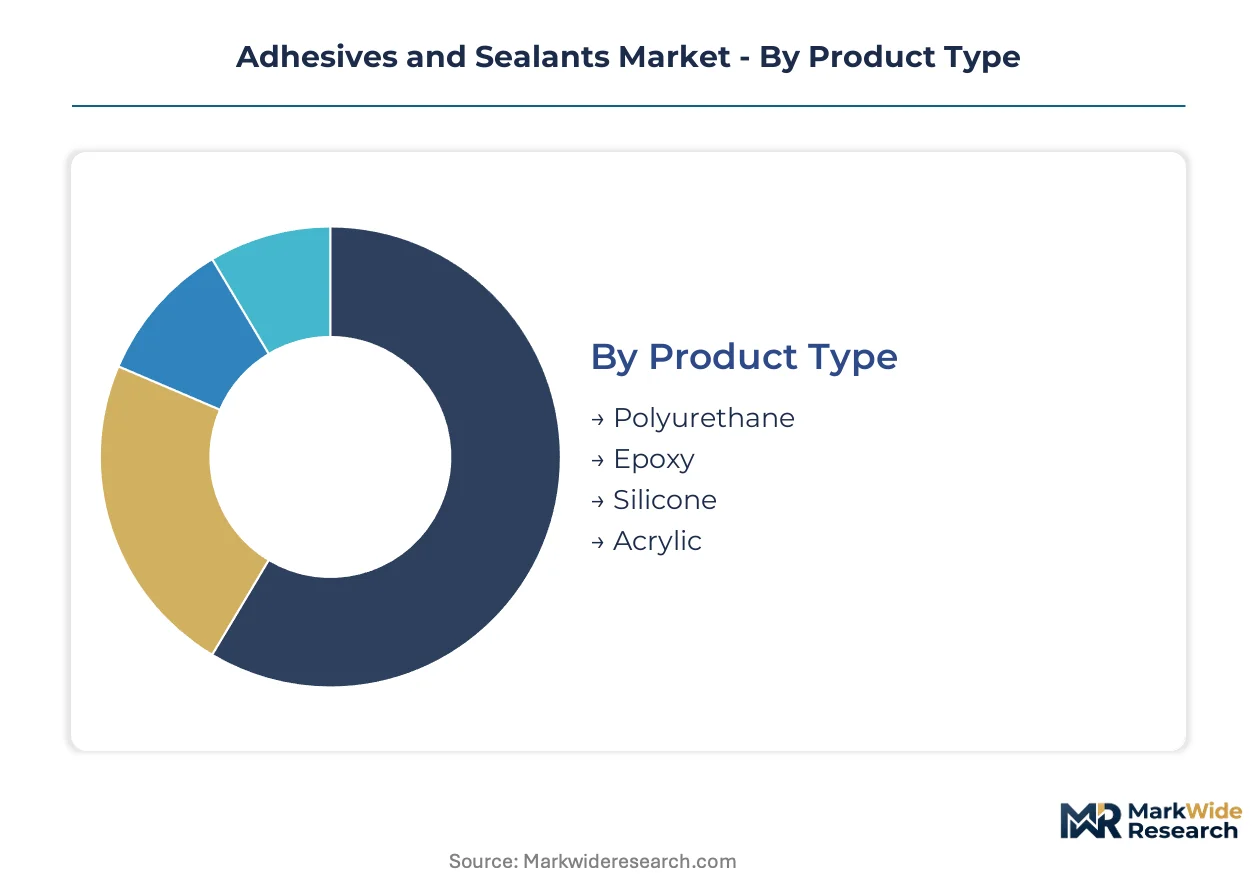
Segmentation in adhesives and sealants reveals distinct capital requirements, formulation complexity, and regulatory exposure across chemistries and applications. Understanding these divisions exposes where margin pools concentrate and where supply bottlenecks form.
Product Type:
Polyurethane and silicone production demand the heaviest upfront investment in reactor systems, distillation trains, and moisture-controlled packaging lines.
- Polyurethane:Two-part systems combining polyols and isocyanates cure through moisture or heat activation, delivering toughness and flexibility across temperature ranges. Construction contractors in Germany and Japan specify polyurethane for structural glazing and bridge expansion joints, driven by load-bearing requirements and long service-life guarantees. Most installed capacity flows through Polyurethane. Expansion is steepest in Silicone.
- Epoxy:Thermosetting resins formed from epichlorohydrin and bisphenol-A achieve bond strengths exceeding 30 MPa, making them indispensable for automotive structural bonding and aerospace composite lamination. German automotive OEMs are consolidating epoxy specifications across electric vehicle platforms, forcing formulators to engineer rapid-cure variants compatible with robotic assembly cycles.
- Silicone:Organosiloxane polymers maintain elastomeric properties from -60°C to 250°C, commanding premium pricing in electronics thermal management and medical device sealing where biocompatibility and dielectric stability are mandatory.
- Acrylic:UV-curable or solvent-borne formulations based on methacrylate monomers dominate electronics display bonding and medical tape applications, with optical clarity and instant tack enabling high-throughput manufacturing.
Polyurethane absorbs the majority of fixed capital deployment. Acrylic is gaining share fastest in electronics manufacturing corridors.
Application:
Demand patterns split sharply between project-based construction cycles and continuous automotive production, with aerospace and electronics occupying specialized niches.
- Construction:Sealants for expansion joints, curtain wall glazing, and waterproofing membranes must comply with EN 13501 fire ratings in Europe and GB 8624 in China. French and German public tenders now weight low-VOC content in scoring, redirecting procurement toward waterborne and silyl-terminated polymer systems.
- Automotive:Structural bonding of aluminum and carbon fiber composites replaces welded joints to reduce vehicle weight and improve crash energy absorption. Battery pack assembly in China's eastern manufacturing corridor consumes thermally conductive adhesives for cell-to-cell heat dissipation.
- Aerospace:Film adhesives and paste syntactics for composite primary structures require FAA certification and sustained performance across thermal cycling regimes, limiting qualified suppliers to a handful of formulators with Nadcap-accredited facilities.
- Electronics:Anisotropic conductive films and underfill epoxies for semiconductor packaging demand sub-micron filler dispersion and ionic purity below 10 ppm, concentrating supply among Japanese and South Korean specialty chemical producers.
Construction commands the largest volume footprint. Electronics is expanding most quickly under India's PLI scheme for smartphone and semiconductor assembly.
End User:
Procurement behavior diverges between specification-driven manufacturers and price-sensitive contractors, with DIY channels serving fragmented maintenance demand.
- Manufacturers:Automotive OEMs and electronics assemblers mandate single-source accountability for bonded joint performance, consolidating approved vendor lists and requiring formulators to carry finished goods inventory near production facilities.
- Contractors:Construction applicators in Italy and Spain prioritize unit economics and ambient cure reliability over technical sophistication, creating demand for pre-formulated cartridges and bulk dispensing systems.
- DIY Consumers:Retail channels for home repair and craft applications favor small-format packaging with intuitive dispensing, with growth concentrated in North American big-box retailers and European home improvement chains.
- Distributors:Technical distributors in industrial clusters provide formulation blending, just-in-time delivery, and application training, capturing margin through value-added services rather than commodity trading.
Manufacturers drive the majority of technical specification and volume commitment. Distributors are climbing the fastest as regional compounding networks deepen.
Form:
Physical state determines application equipment requirements, shelf stability, and logistics economics across the value chain.
- Liquid:Low-viscosity systems for spray, roll, or dip coating enable high-speed lamination and impregnation processes. Automotive underbody coatings and wood veneer bonding in Italian furniture manufacturing rely on solventborne or waterborne liquid formulations.
- Paste:Thixotropic compounds maintain position on vertical surfaces and fill gaps up to 25mm, serving construction sealant cartridges and automotive seam sealing applications where sag resistance is critical.
- Film:Unsupported or carrier-supported adhesive films deliver precise thickness control and clean handling for aerospace composite bonding and electronics die-attach, requiring refrigerated storage and controlled humidity environments.
- Spray:Aerosol or pump-spray formats target insulation, sound damping, and temporary fixturing applications, with EPA VOC regulations in the United States constraining solvent content and propellant chemistry.
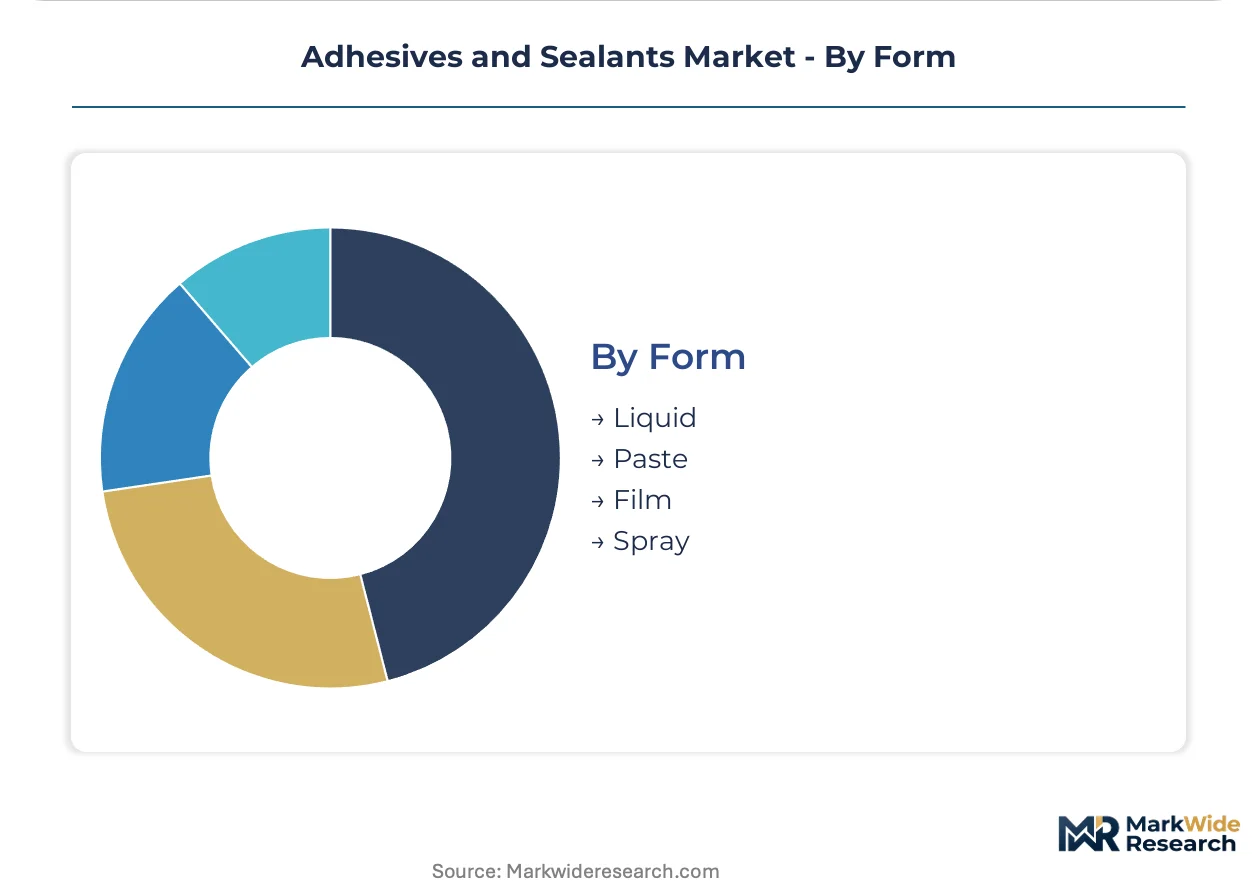
Paste formulations carry the broadest installed application infrastructure. Film formats are expanding most quickly in battery pack and aerospace assembly where precision and cleanliness dominate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial adhesive chemistry in the early twentieth century, with Bayer and Henkel establishing the first synthetic resin laboratories that would later define global formulation standards. This heritage continues to shape procurement patterns and technical specifications across major manufacturing economies.
United States
Automotive OEMs in Michigan and Ohio are converting final assembly lines to bonded aluminum-intensive architectures, eliminating thousands of spot welds per vehicle. EPA VOC enforcement under the Clean Air Act forces architectural sealant producers in Southern California to eliminate aromatic solvents entirely. The SCAQMD district operates as a regulatory laboratory where reformulated sprayable systems debut before national rollout.
Germany
Automotive OEMs in Stuttgart and Munich specify structural epoxies that cure in under 90 seconds for robotic bonding of carbon fiber passenger cells. REACH compliance through ECHA restricts solvent content in construction-grade systems, pushing formulators toward waterborne polyurethane. The Rhine-Ruhr industrial corridor hosts captive resin synthesis facilities that supply compounders across Central Europe.
China
EV battery packers in Jiangsu and Zhejiang provinces consume thermally conductive silicone gap fillers at volumes exceeding any other national market. SAMR enforcement of GB 8624 fire ratings for construction adhesives creates compliance barriers for imported products. The Yangtze River Delta concentrates silicone intermediate production, exposing non-Chinese formulators to geographic supply risk.
Japan
METI-certified JIS sealants are mandatory in public bridge and tunnel repair contracts, creating anchored demand for high-performance polyurethane systems. Automotive OEMs in Toyota City and Hiroshima are expanding bonded assembly lines to improve crash energy absorption. The Kanto region hosts specialized R&D centers for electronics-grade underfill epoxies with sub-micron filler dispersion.
India
PLI scheme incentives for smartphone assembly in Tamil Nadu and Karnataka are creating demand for UV-cure acrylics and anisotropic conductive films. BIS certification requirements for construction adhesives in public infrastructure projects redirect procurement toward tested domestic formulations. The Delhi-Mumbai Industrial Corridor anchors distribution networks serving both automotive and electronics manufacturing clusters.
Adhesives and Sealants Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth, with structural epoxy and silicone specialists capturing value pools that commodity acrylic producers cannot access. The vendor base organizes into three tiers: integrated resin producers with captive feedstock, regional compounders with formulation blending capabilities, and application-focused specialists with Nadcap or medical-grade certifications. Two competitive moves dominate: backward integration into resin synthesis to secure polyol and isocyanate supply, and consolidation of approved vendor lists at German and Japanese automotive OEMs.
Within the integrated chemistry tier, Henkel AG & Co. KGaA and Dow Inc. represent archetypes of backward integration into resin synthesis, while Sika AG exemplifies geographic density strategies in European infrastructure. These three anchors illustrate how scale and specialization split the competitive landscape between system-level suppliers and regional formulators.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| Arkema S.A. |
| Dow Inc. |
| Huntsman Corporation |
| Avery Dennison Corporation |
| Illinois Tool Works Inc. |
| Others |
Cost & Logistics Intelligence
Crude oil and natural gas price indices cascade directly into polyurethane feedstock costs, compressing margin predictability for mid-sized compounders and forcing a three-tier pricing structure across premium, standard, and economy levels. Polyol and isocyanate volatility separates structural epoxy producers with captive resin synthesis from commodity acrylic blenders exposed to spot market swings.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between automotive OEMs and certified adhesive formulators, with price differentiation anchored in REACH compliance tier and Nadcap accreditation depth. Certification grade and volume scale separate premium silicone suppliers serving aerospace from economy-grade construction sealant producers. Cost compression in standard-tier acrylics is intensifying because Chinese domestic manufacturers are expanding UV-cure capacity. DIY retail channels exhibit highest price sensitivity, while German automotive OEMs prioritize single-source accountability over unit economics.
Supply Chain Analysis
India's PLI scheme and China's SAMR enforcement of GB standards are reshaping sourcing patterns toward domestic-content compliance. Silicone intermediates and organotin catalysts concentrate in Jiangsu and Shandong provinces, while epoxy resin production clusters in Germany's Rhine-Ruhr corridor and the US Gulf Coast. The supply chain draws from petrochemical feedstocks, specialty chemical catalysts, and precision filler dispersions. Single-source vulnerability runs through Jiangsu province's silicone intermediate dominance. Distribution runs through technical distributors providing regional compounding and just-in-time delivery to manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
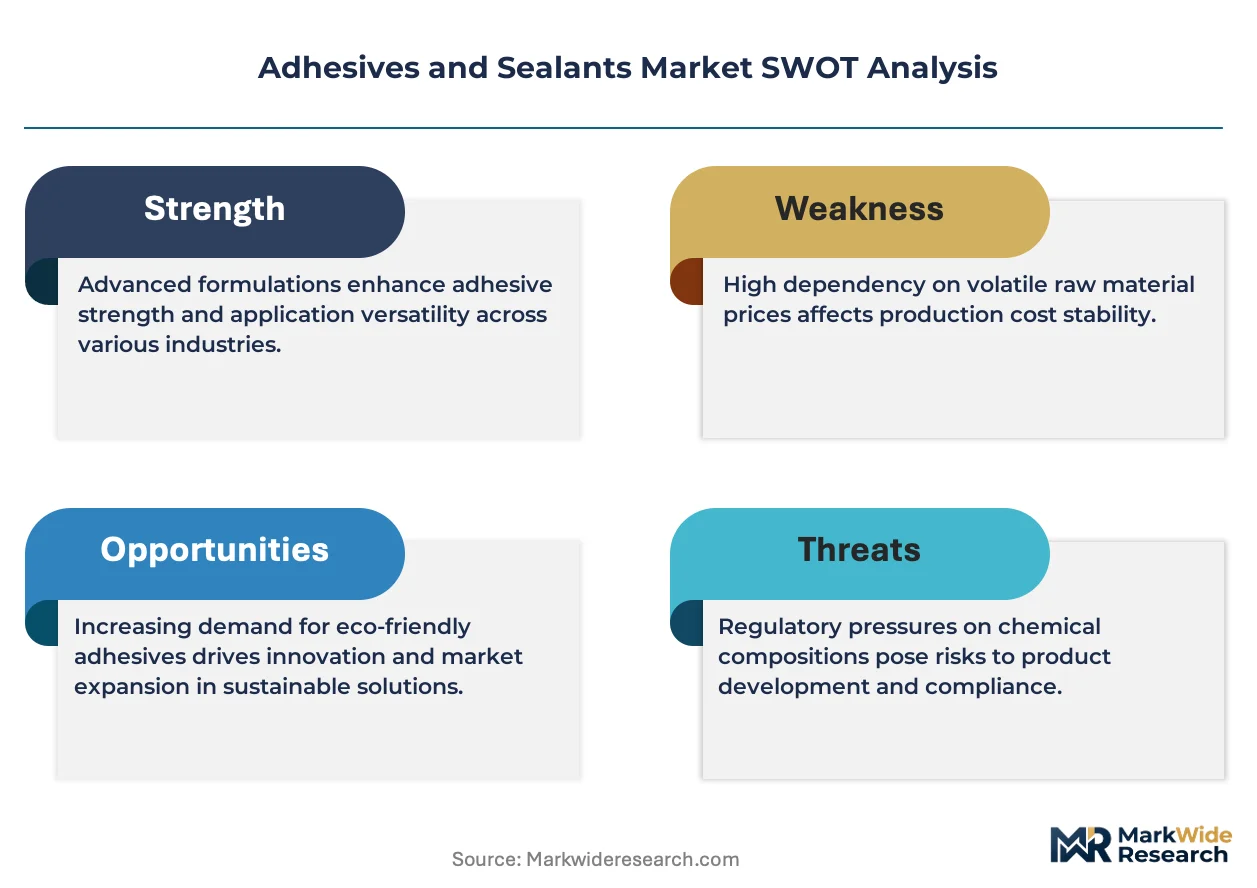
The adhesives and sealants market functions as a regulatory compounder where REACH compliance milestones and EPA VOC rule evolution are systematically displacing solvent-based formulations and rewarding reformulation investment.
For Market Incumbents: Extend backward integration into polyol and isocyanate synthesis to secure feedstock supply against petrochemical volatility, while consolidating approved vendor relationships with German and Japanese automotive OEMs who are reducing supplier counts. Capacity addition in China's eastern manufacturing corridor captures EV battery packer demand for thermally conductive silicones. Certification investment in EN 13501 and GB 8624 fire ratings defends position against emerging regional compounders. For New Entrants and Emerging Players: The gap between premium aerospace-grade epoxies and economy construction acrylics offers white-space targeting for mid-tier UV-cure formulations serving India's electronics manufacturing expansion. Specialty medical device bonding and building-integrated photovoltaics encapsulants represent the most penetrable application segments. A go-to-market angle anchored in bio-based feedstock certification captures EU Green Deal procurement scoring advantages in Italian and Spanish public tenders. For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounders possessing Nadcap-accredited facilities and established automotive OEM qualification pathways. The five-to-ten year viability window favors targets with demonstrated regulatory navigation across ECHA, EPA, and SAMR jurisdictions. Acquisition target archetype: mid-cap formulators with captive resin synthesis and geographic density in European infrastructure repair. Watch EV battery thermal management specification consolidation as the inflection indicator signaling platform-scale adhesive procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive polyol supply insulates margin from crude oil volatility and secures automotive OEM qualification. |
| Green Manufacturing Transition | Bio-based epoxy and polyurethane feedstocks unlock EU Green Deal procurement scoring in Italian public tenders. |
| Long-term Supply Agreement | Single-source accountability contracts with German OEMs consolidate bonded joint performance liability. |
| Capacity Expansion | Regional compounding networks in China's Yangtze River Delta reduce logistics exposure to export license delays. |
| Joint Venture | Technology licensing partnerships with South Korean electronics chemical producers access sub-micron filler dispersion capabilities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulator R&D directors, automotive Tier 1 procurement leads, construction contractor specification managers, and technical distributor operations heads with secondary validation. Customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR GB standard enforcement records anchored the data foundation. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated volume and value estimates.
Segment-weighting approaches modeled chemistry type, application end-use, and regional regulatory cluster across the projection horizon. Analytical frameworks incorporated grade tier differentiation, OEM qualification depth, and domestic-content compliance requirements. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand projection. Industry-specific forecast inputs included EV battery pack assembly line expansion rates and public infrastructure tender award patterns.
Caveats apply where petrochemical feedstock volatility, export license restrictions on Chinese silicone intermediates, or accelerated EPA VOC rule enforcement could materially shift the outlook. Forecasts reflect documented assumptions about regulatory implementation timelines and OEM platform standardization decisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Silicone Sealants Market