
 Europe Acrylic Adhesives Market | 2026-2036
Europe Acrylic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acrylic Adhesives Market Foresight
Aftermarket service revenue for adhesive application equipment is narrowing as manufacturers push integrated bonding system sales. Henkel AG & Co. KGaA leverages its European distribution network to sustain direct relationships with automotive OEMs. Sika AG anchors its position through specialized construction-grade formulations that dominate infrastructure refurbishment across Southern Europe. Arkema Group competes by extending its UV-curable portfolio for electronics miniaturization applications.
Europe acrylic adhesives are synthetic resin systems formulated from acrylic monomers, typically polymerized through free-radical mechanisms to achieve peel strengths ranging from 5 to 30 N/cm depending on crosslink density. These adhesives bond dissimilar substrates including metals, plastics, and composites without surface pretreatment in many formulations, serving primary roles in structural assembly, lamination, and sealing across industrial manufacturing. Water-based formulations now lead volume shipments as manufacturers reformulate to eliminate volatile organic compound emissions, while UV-curable segments capture expanding margin pools in electronics and medical device bonding where rapid cure cycles reduce work-in-process inventory. Hot melt acrylics sustain growth in packaging applications driven by e-commerce fulfillment demands, though solvent-based systems face structural decline under tightening EU industrial emissions regulations.
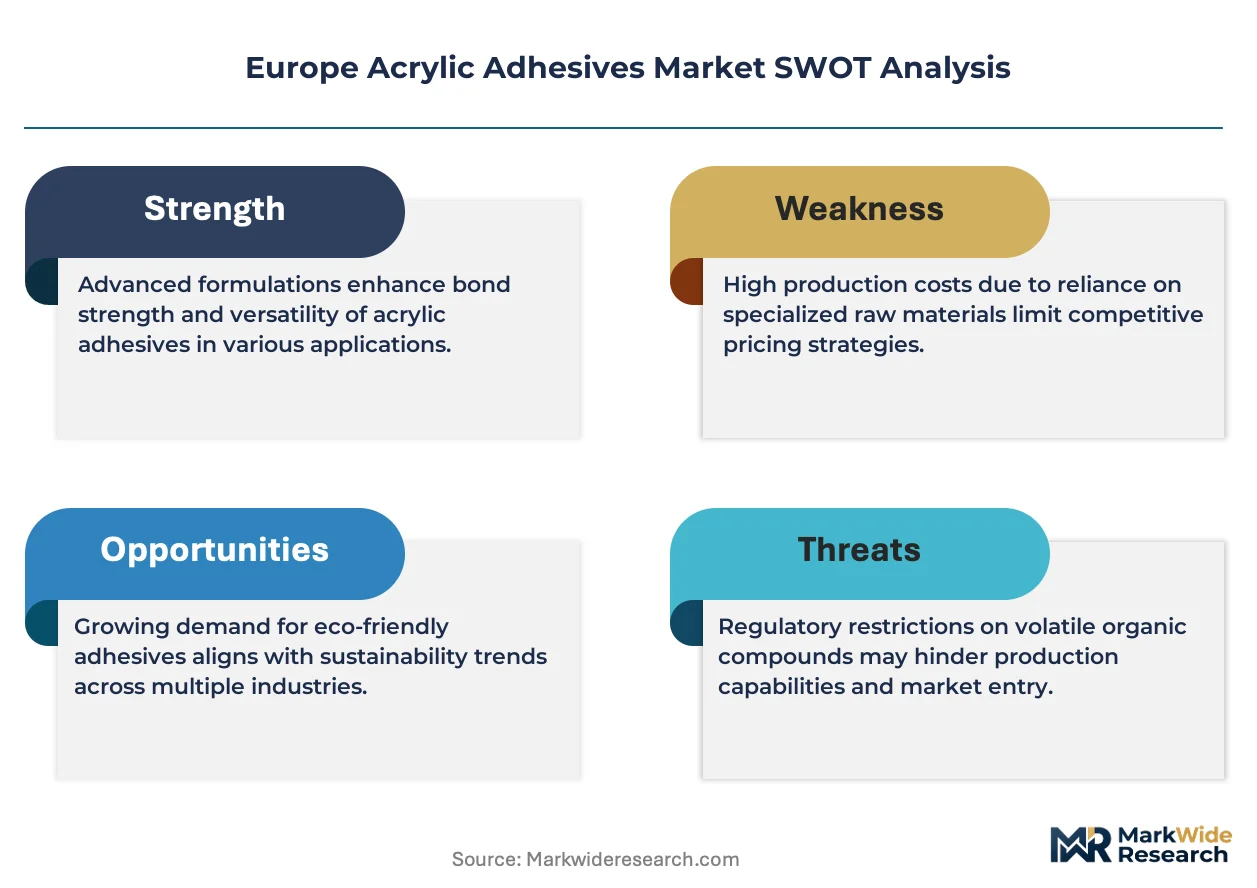
REACH registration requirements and the EU Green Deal's chemical sustainability framework compel raw material disclosure and substitution of hazardous substances across adhesive supply chains. ECHA's restriction proposals on specific monomers and the F-Gas Regulation's phase-down targets indirectly reshape pressure-sensitive tape manufacturing processes that rely on foam blowing agents. The EU AI Act's emerging quality documentation standards will soon extend to automated adhesive dispensing systems in automotive and electronics sectors. Stakeholders must monitor regulatory pre-announcements to anticipate formulation lock periods and secure alternative chemistries before compliance deadlines crystallize.
Market Dynamics
REACH registration deadlines and the EU Green Deal's chemical sustainability mandates are forcing rapid formulation turnover across European adhesive supply chains, compressing R&D cycles while elevating compliance costs for mid-tier producers.
Growth Catalysts
- Automotive lightweighting:German and French OEMs are expanding bonded assembly applications in electric vehicle platforms, displacing mechanical fasteners with structural acrylic systems in battery pack enclosures and body-in-white joints.
- E-commerce packaging surge:Hot melt acrylic adhesives capture expanding share in automated fulfillment lines across Poland and the Netherlands, driven by same-day delivery logistics requiring rapid case sealing at ambient temperatures.
- UV-curable electronics bonding:Medical device manufacturers in Switzerland and Ireland are adopting solvent-free acrylic systems for miniaturized component assembly, eliminating thermal cure cycles that damage heat-sensitive substrates.
Market Restraints
- Monomer supply concentration:Acrylic acid and specialty ester production clusters in the ARA region (Antwerp-Rotterdam-Amsterdam), creating vulnerability to unplanned refinery outages and force majeure declarations.
- REACH authorization costs:Small and mid-sized formulators face disproportionate compliance burdens from ECHA's substance evaluation procedures, particularly for legacy toughening agents and adhesion promoters.
- Hybrid polyurethane-acrylic competition:Flexible packaging converters in Italy and Spain are substituting moisture-cure PUR systems for acrylic hot melts in high-performance lamination applications requiring superior moisture barrier properties.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland present whitespace for water-based pressure-sensitive adhesives in sustainable packaging, as pulp and paper industry clusters seek bio-based bonding alternatives to synthetic rubber systems.
- CSRD-aligned carbon accounting:The EU Corporate Sustainability Reporting Directive creates procurement preference for adhesives with verified lifecycle carbon footprints, rewarding early movers with Scope 3 reduction credentials.
- UV-LED convergence:Integration of 395nm LED curing arrays with acrylic formulations is digitizing dispensing line controls, enabling real-time bond quality verification in automotive electronics assembly.
Industry Challenges
- Formulation chemist scarcity:European universities produce insufficient polymer science graduates familiar with free-radical cure kinetics and rheology modification, forcing manufacturers to poach talent from coatings and sealants sectors.
- Dual-use export controls:Structural adhesives with specified peel and shear strength thresholds face licensing complexity under EU Regulation 2021/821, delaying shipments to aerospace subcontractors in non-EU jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acrylic Adhesives Market |
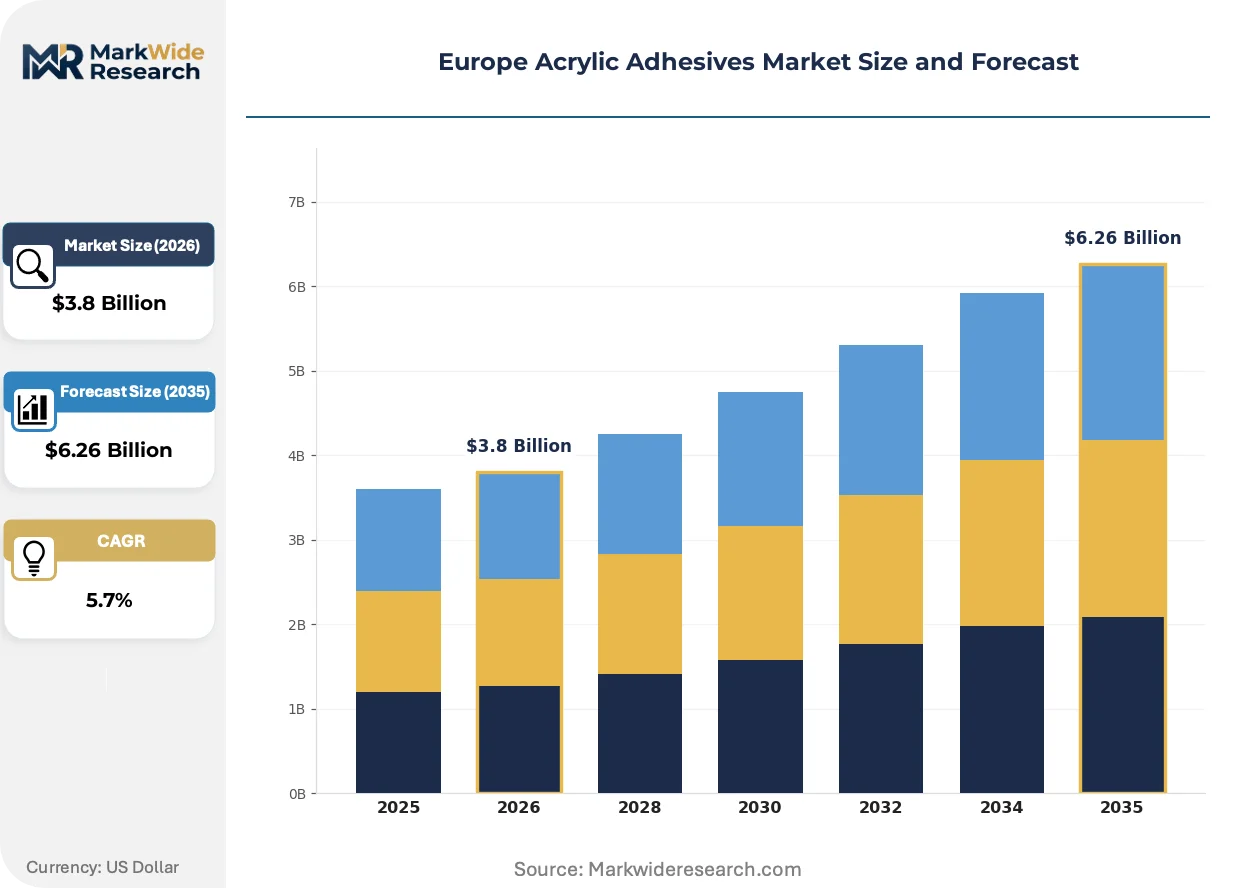
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Hot Melt, UV Curable Application: Construction, Automotive, Packaging, Electronics End User: Manufacturers, Contractors, Retailers, DIY Consumers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, Avery Dennison Corporation, H.B. Fuller Company, Dow, Huntsman International LLC, BASF, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acrylic Adhesives Market Shifts & Advancements
Digital process control systems and photopolymerization advances are compressing cure cycles while embedding quality assurance directly into manufacturing execution systems, fundamentally altering how bonding operations integrate with broader production workflows.
UV-LED curing technology is digitizing acrylic adhesive dispensing operations across European automotive electronics lines. Tier suppliers in Bavaria and Baden-Württemberg are retrofitting robotic cells with 395nm arrays that enable instantaneous cure verification through integrated photodiode feedback. The technology is digitizing quality documentation for the EU AI Act's emerging manufacturing traceability requirements.
REACH restriction proposals targeting specific acrylate monomers are compelling formulation houses to validate substitute chemistries ahead of sunset dates. ECHA's 2024-2025 evaluation roadmap prioritizes skin-sensitizing substances common in medical-grade adhesives, forcing Swiss and German formulators to accelerate biocompatible alternative development. Electronics and wound-care segments face the steepest compliance timelines.
Integrated bonding system sales are displacing standalone adhesive procurement across French and German automotive OEMs. Tier suppliers now contract for complete dispensing-cure-verification packages rather than bulk resin volumes, compressing margins for pure-play chemical suppliers while elevating equipment-software bundling specialists. The shift is most visible in Stuttgart and Wolfsburg production corridors.
Europe Acrylic Adhesives Market Segmentation
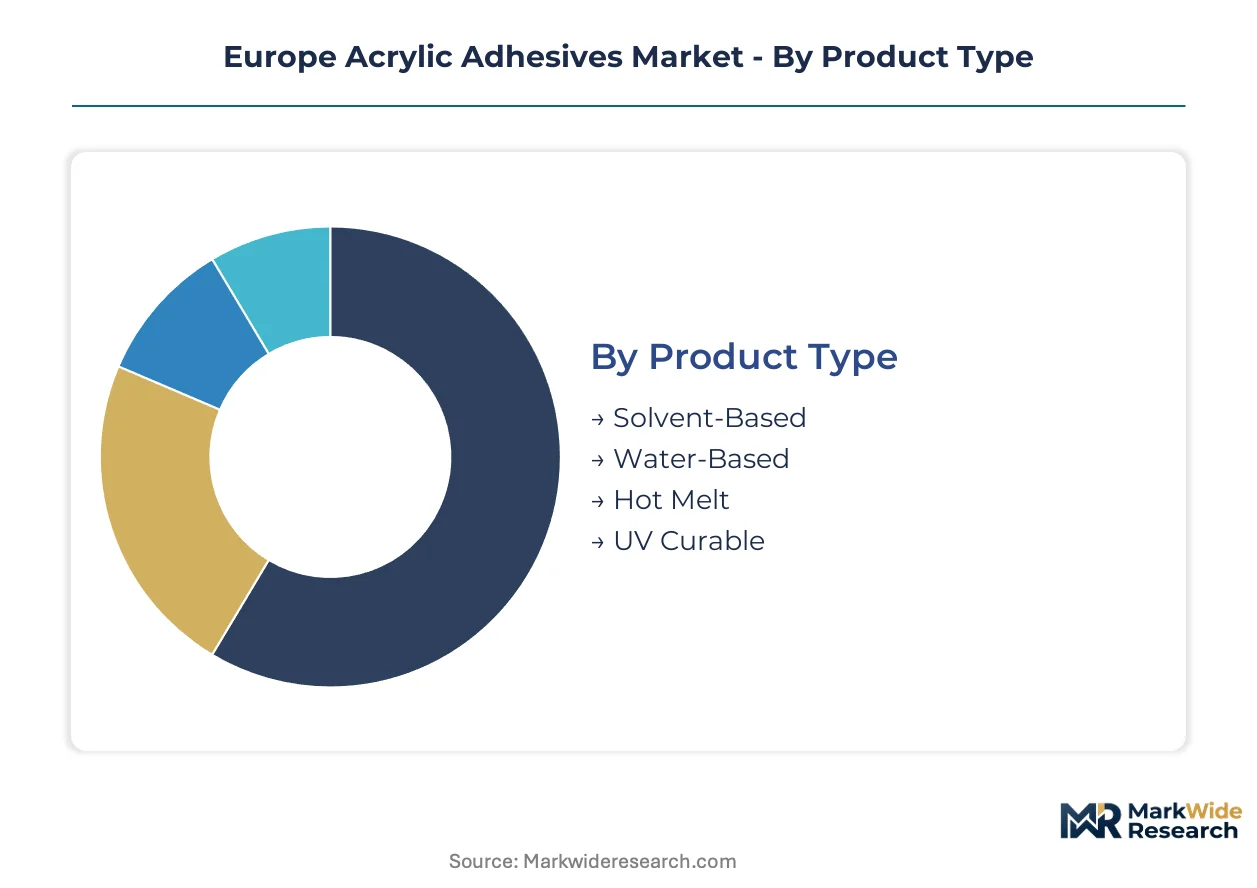
Segmentation reveals how formulation chemistry, application requirements, and procurement patterns fragment demand across European supply chains. Manufacturers configure production assets around these divisions to capture margin pools in automotive structural bonding and electronics miniaturization.
Product Type:
Mature water-based systems dominate volume shipments while UV-curable platforms emerge as the technology frontier for precision assembly.
- Water-Based:Emulsion polymerized systems with 40-60% solids content serve construction and packaging applications where low VOC emissions satisfy REACH compliance. German automotive OEMs specify these formulations for interior trim lamination to meet cabin air quality standards.
- UV Curable:Photoinitiated acrylic monomers cure in seconds under 395nm LED arrays, eliminating thermal damage to heat-sensitive substrates. Swiss medical device manufacturers and Irish electronics assemblers drive specification growth for miniaturized component bonding.
- Solvent-Based:High-solids formulations persist in aerospace and specialty industrial applications requiring aggressive substrate wetting, though ECHA restriction proposals accelerate phase-out timelines.
- Hot Melt:Thermoplastic acrylic block copolymers enable rapid case sealing in Polish and Dutch automated fulfillment lines, capturing e-commerce packaging demand without solvent emissions.
Water-based formulations handle the majority of throughput; UV-curable systems are expanding most quickly on share as electronics and medical device specifications multiply.
Application:
Cost tier stratification separates high-value structural assembly from commodity sealing operations.
- Automotive:Toughened acrylic systems bond dissimilar substrates in battery pack enclosures and body-in-white joints, displacing mechanical fasteners in Stuttgart and Wolfsburg production corridors. German and French OEMs specify these for electric vehicle lightweighting programs.
- Electronics:Low-outgassing formulations with ionic purity below 50 ppm serve PCB assembly and display lamination. Bavarian tier suppliers integrate these with automated dispensing-cure-verification systems.
- Construction:Pressure-sensitive and structural grades anchor Southern European infrastructure refurbishment, where Sika AG formulations dominate facade bonding and flooring installation.
- Packaging:Hot melt acrylics sustain case and carton sealing across Central European fulfillment networks, driven by same-day delivery logistics requiring ambient-temperature processing.
Automotive applications command premium pricing; electronics bonding exhibits the steepest specification escalation as miniaturization intensifies.
End User:
Customer type determines formulation complexity and technical service intensity.
- Manufacturers:Industrial OEMs and tier suppliers procure engineered systems with validated cure protocols, quality documentation, and regulatory compliance packages. These buyers contract for integrated bonding systems rather than standalone resins.
- Contractors:Construction trades purchase mid-viscosity formulations through wholesale channels, prioritizing open time and substrate versatility for on-site application variability.
- Retailers:Hardware and home improvement chains stock consumer-grade cartridges and tubes, competing on shelf placement and brand recognition.
- DIY Consumers:Individual purchasers select convenience formats with simplified application instructions, generating low-margin volume through mass-market distribution.
Manufacturers absorb the bulk of technical sales resources; contractor channels generate the most volatile demand swings with construction cycle sensitivity.
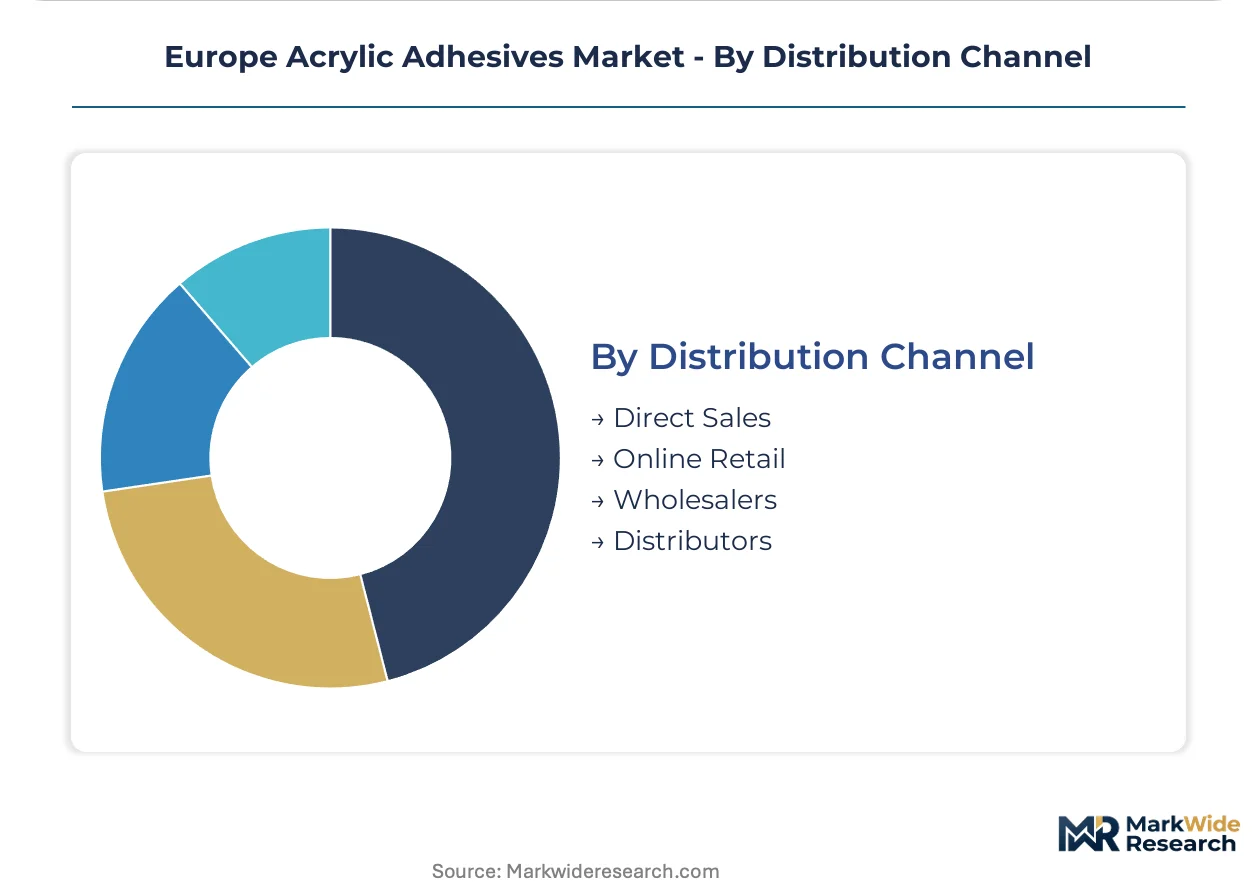
Distribution Channel:
Supply concentration varies by customer scale and formulation specialization requirements.
- Direct Sales:Henkel AG & Co. KGaA and specialized formulators maintain direct relationships with automotive OEMs, embedding technical service teams within customer R&D facilities. These partnerships lock in multi-year supply agreements with formulation co-development clauses.
- Distributors:Regional chemical distributors stock standard grades for mid-tier manufacturers, providing inventory management and just-in-time delivery across industrial corridors.
- Wholesalers:Construction-focused wholesalers serve contractor demand with bulk packaging and trade credit terms, concentrating in Southern European refurbishment markets.
- Online Retail:E-commerce platforms capture DIY and small contractor procurement, though hazardous material shipping restrictions limit formulation options.
Direct sales channels capture the highest value per kilogram; distributor networks sustain the broadest geographic coverage across fragmented industrial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments across European procurement patterns. German automotive OEMs absorb premium structural formulations without volume elasticity, while Italian packaging converters aggressively substitute on cost. Southern European construction trades prioritize open-time versatility over specification compliance.
Germany
Stuttgart and Wolfsburg production corridors anchor structural acrylic demand for electric vehicle battery enclosures and body-in-white joints. REACH registration deadlines from ECHA compress formulation cycles for domestic suppliers. Bavarian tier suppliers integrate UV-LED curing arrays with automated dispensing systems for real-time bond verification.
France
Paris Basin manufacturing clusters specify toughened acrylic systems for aerospace subassembly bonding under dual-use export licensing complexity. The EU Green Deal's chemical sustainability mandates accelerate water-based formulation shifts among domestic formulators. Lyon-based specialty chemical houses validate substitute monomers ahead of ECHA sunset dates.
Italy
Packaging converters in Lombardy and Emilia-Romagna substitute moisture-cure polyurethane for acrylic hot melts in high-performance lamination requiring moisture barrier properties. CSRD-aligned carbon accounting creates procurement friction for adhesives lacking verified lifecycle footprints. Milan industrial districts witness volatile demand swings tied to construction cycle sensitivity.
Netherlands
Rotterdam-Amsterdam petrochemical corridors concentrate acrylic acid and specialty ester production, exposing supply chains to unplanned refinery outage risk. Polish and Dutch automated fulfillment lines drive hot melt acrylic consumption for same-day delivery case sealing. Eindhoven electronics clusters adopt low-outgassing formulations for PCB assembly with ionic purity below 50 ppm.
Switzerland
Swiss medical device manufacturers in Basel and Zurich pharmaceutical corridors specify solvent-free UV-curable systems for miniaturized component assembly. ECHA restriction proposals targeting skin-sensitizing acrylates accelerate biocompatible alternative development timelines. Geneva precision manufacturing clusters eliminate thermal cure cycles to protect heat-sensitive substrates.
Europe Acrylic Adhesives Market Competitive Landscape
Capability concentration sits with specialized formulators possessing validated cure protocols and regulatory compliance packages; scale advantage sits with diversified chemical conglomerates commanding raw material backward integration. The vendor base stratifies across three tiers: integrated bonding system providers, pure-play adhesive specialists, and regional distributors. Dominant competitive moves include M&A to capture dispensing equipment capabilities and capacity expansion in water-based emulsion polymerization.
Among diversified European chemical conglomerates, Henkel AG & Co. KGaA and Sika AG exemplify contrasting archetypes. Henkel represents the integrated system provider model, embedding technical service within customer R&D facilities. Sika occupies a position as the construction-grade formulation specialist, anchoring Southern European infrastructure refurbishment demand. Arkema Group sits within the materials science tier, extending UV-curable portfolios for precision assembly applications.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Dow |
| Huntsman International LLC |
| BASF |
| Others |
Supply & Pricing Matrix
Undercapacity in European water-based emulsion polymerization is forcing formulators to accept longer lead times and cede pricing leverage to ARA-region acrylic acid producers. This utilization squeeze concentrates margin capture upstream while downstream buyers face volume allocation protocols during peak automotive specification cycles.
Pricing Analysis
Aftermarket service revenue for adhesive application equipment is narrowing as manufacturers push integrated bonding system sales. Three-tier pricing structure across premium structural, standard industrial, and economy packaging levels separates automotive OEM contracts from construction wholesale channels. Cost compression in standard industrial grades is intensifying because Italian packaging converters aggressively substitute moisture-cure polyurethane systems. Contractor channels exhibit the highest price sensitivity; German automotive OEMs absorb premium formulations without volume elasticity.
Supply Chain Analysis
Contract manufacturing concentration among Dutch and German toll polymerization houses limits formulation flexibility for mid-tier European suppliers. Acrylic acid and specialty ester production clusters in Belgium, the Netherlands, and Germany; supply chains draw from ARA-region petrochemical corridors. Feedstock dependencies include crude oil derivatives, methanol, and sulfuric acid catalysts. Single-source vulnerability from unplanned refinery outages exposes formulators to force majeure declarations. Distribution runs through direct technical sales for automotive OEMs and regional chemical distributors for mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European acrylic adhesive markets reward players who control scarce formulation chemist talent and validated cure protocol libraries. The gap between polymer science graduate supply and industrial demand widens annually, compressing R&D throughput for unprepared competitors.
For Market Incumbents: Entrench position by embedding technical service teams within Stuttgart and Wolfsburg OEM R&D facilities, locking multi-year supply agreements with formulation co-development clauses. Accelerate backward integration into acrylic acid ester production to reduce ARA-region supply vulnerability. Prioritize certification investment for EU AI Act traceability requirements before compliance deadlines crystallize. For New Entrants and Emerging Players: Establish a beachhead in Sweden and Finland water-based pressure-sensitive adhesives for sustainable packaging, where pulp and paper industry clusters seek bio-based bonding alternatives. Target Swiss medical device UV-curable segments facing ECHA restriction timelines on skin-sensitizing monomers. Pursue equipment-software bundling partnerships rather than pure resin supply to bypass incumbent technical service moats. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated bonding system providers with captive dispensing equipment capabilities. Long-term viability favors formulators with verified lifecycle carbon footprints under CSRD-aligned procurement standards. Monitor ECHA substance evaluation pre-announcements as inflection indicators for formulation lock periods and substitute chemistry validation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Water-Based Emulsion Polymerization | Addresses REACH compliance volume shifts while capturing German automotive interior trim lamination specifications. |
| Backward Integration into Acrylic Acid Ester Production | Reduces ARA-region supply concentration risk and insulates margins from petrochemical feedstock volatility. |
| UV-LED Curing Equipment Bundling | Aligns with Bavarian tier supplier demand for real-time bond verification and EU AI Act traceability documentation. |
| Biocompatible Monomer Substitution R&D | Anticipates ECHA sunset dates on skin-sensitizing acrylates in Swiss medical device and Irish electronics segments. |
| Joint Venture for Nordic Sustainable Packaging | Captures whitespace in Sweden and Finland pulp and paper industry conversion from synthetic rubber systems. |
Research Methodology
Operator-level perspectives from polymer plant managers, automotive OEM procurement leads, construction contractor purchasing heads, and technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from ECHA restriction proposals, Cefic chemical industry reports, customs and trade flow data, and SEC filings of diversified chemical conglomerates. Bottom-up volume estimates triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed demand projections across baseline, accelerated regulatory, and supply disruption cases. Segmentation dimensions modeled include formulation chemistry tier, end-use industry vertical, geographic production cluster, and customer procurement archetype. CAGRs derived from elasticity-adjusted volume trajectories incorporating automotive lightweighting program schedules, e-commerce fulfillment automation deployment, and REACH compliance phase-in timelines.
Stress conditions across acrylic acid supply interruptions, ECHA authorization cost spikes, and hybrid polyurethane substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation cadence and OEM platform standardization decisions. Quarterly review of ECHA evaluation roadmap updates, automotive production schedule revisions, and LED curing equipment deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Lead Encapsulants Market