
 Hemophilia Treatment Market | 2026-2036
Hemophilia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hemophilia Treatment Market Analysis
Subscription-based patient support programs is hardening into a core revenue layer beyond the vial itself. CSL Behring leverages integrated home-infusion services to sustain long-term patient retention. Takeda Pharmaceutical Company Limited anchors its competitive stance through geographic dominance in Asia-Pacific hemophilia markets. Novo Nordisk specializes in recombinant factor portfolio breadth across both hemophilia A and B indications.
Hemophilia treatment encompasses therapeutic interventions for inherited coagulation factor deficiencies, primarily factor VIII or factor IX concentrates administered via intravenous infusion to restore hemostatic function and prevent bleeding episodes. Recombinant DNA technology now dominates production, yielding proteins with reduced immunogenicity profiles compared with plasma-derived alternatives. Factor concentrates command the largest margin pool due to chronic prophylactic dosing requirements, while gene therapy represents the fastest-growing therapy area as one-time interventions challenge conventional replacement paradigms. Homecare settings are expanding fastest among end users, driven by subcutaneous delivery innovations that reduce hospital dependency.
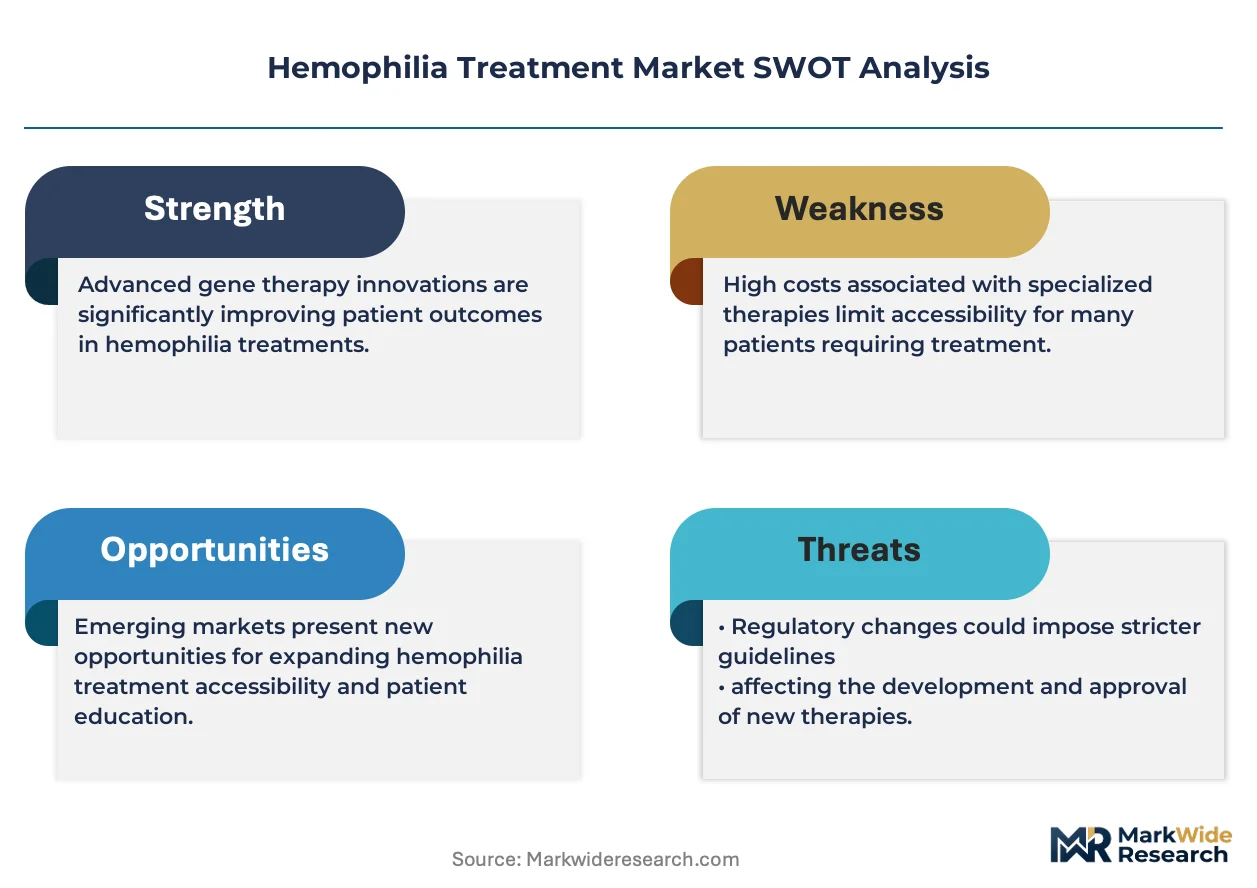
FDA biologics licensing requirements and EMA's Committee for Medicinal Products for Human Use shape clinical trial endpoints and post-market surveillance obligations for hemophilia therapies. The EU's Orphan Drug Regulation and the US Orphan Drug Act confer exclusivity incentives that directly influence pipeline prioritization decisions among developers. Gene therapy durability data and payer willingness to underwrite single-administration premiums at population scale constitute the decisive variables stakeholders must track.
Market Dynamics
Gene therapy durability data is compressing reimbursement timelines as payers weigh one-time administration premiums against chronic prophylactic dosing costs. This structural tension between curative intent and budget impact is reshaping pipeline prioritization across recombinant and plasma-derived portfolios.
Growth Catalysts
- EMA Orphan Drug Regulation:Extended market exclusivity provisions incentivize developers to advance novel hemophilia B gene therapies through accelerated assessment pathways.
- Subcutaneous delivery innovation:Home-infusion technologies reduce hospital dependency and expand prophylactic regimen adherence among pediatric and adult patient cohorts.
- Japan's reimbursement framework:Prophylactic factor concentrate coverage supports chronic dosing models that sustain manufacturer revenue predictability.
Market Restraints
- Plasma supply concentration:United States plasma collection infrastructure dominates raw material availability for factor concentrates, creating geographic dependency risk.
- Gene therapy manufacturing complexity:Viral vector production scale-up constraints limit batch yields and extend patient wait times for one-time interventions.
- Factor VIII inhibitor formation:Immunogenicity complications in severe hemophilia A patients necessitate bypassing agent switches that fragment treatment economics.
Strategic Opportunities
- Brazil's expanding hemophilia registry:Underdiagnosed severe patient populations present volume growth potential as ANVISA streamlines biologics importation.
- Extended half-life factor fusion:Fc-fusion and PEGylation technologies converge to reduce infusion frequency and differentiate portfolio positioning.
- Specialty pharmacy direct distribution:Disintermediation of hospital outpatient channels captures margin and deepens patient data capture for adherence programs.
Industry Challenges
- Gene therapy durability uncertainty:Long-term factor expression monitoring requirements strain post-market surveillance infrastructure and payer confidence.
- Biologics manufacturing talent scarcity:Viral vector and cell culture expertise gaps constrain capacity expansion timelines across contract development organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemophilia Treatment Market |
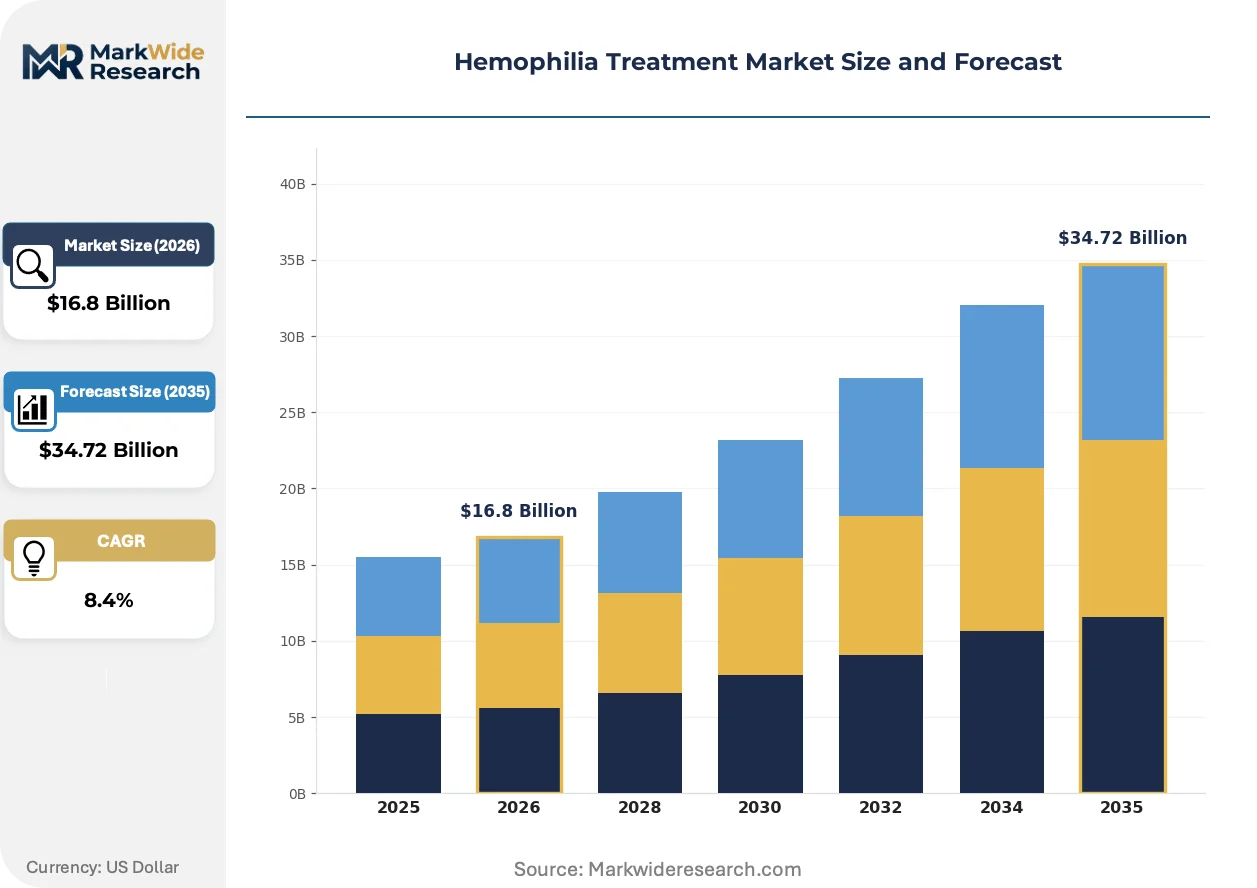
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Factor Concentrates, Desmopressin, Antifibrinolytic Agents, Fibrin Sealants Therapy Area: Prophylactic Therapy, On-Demand Therapy, Gene Therapy, Multidisciplinary Care End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Delivery Mode: Intravenous, Subcutaneous, Intra-muscular, Oral |
| Companies Covered | CSL Behring, Takeda Pharmaceutical Company Limited, Pfizer, Bayer, Sanofi, Novo Nordisk, Octapharma, F. Hoffmann-La Roche, BioMarin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemophilia Treatment Market Emerging Trajectories
Non-factor replacement mechanisms are challenging traditional concentrate paradigms through bispecific antibody and siRNA modalities that bypass defective clotting pathways entirely. These platforms promise subcutaneous administration intervals measured in months rather than days.
Emicizumab is integrating a bispecific antibody architecture that bridges activated factor IX and factor X to restore hemostasis without exogenous factor VIII replacement. Hemophilia A patients with inhibitors are adopting this prophylactic approach at accelerating rates. The technology is integrating chronic replacement regimens into quarterly or less frequent dosing schedules that compress hospital utilization and shift site-of-care economics toward home administration.
REACH registration requirements in Europe are tightening chemical substance traceability standards for plasma-derived product excipients and manufacturing reagents. Manufacturers must now document supply chain substance volumes above one-tonne annual thresholds. Plasma fractionators serving EU markets are responding by qualifying alternative suppliers and submitting extended safety data dossiers to ECHA.
Patient advocacy organizations are consolidating purchasing influence through centralized tender negotiations that aggregate national demand volumes. Hospital procurement committees in Germany are ceding decision authority to centralized sickness fund consortia that negotiate multi-year factor concentrate agreements. This concentration is most visible in statutory health insurance regions where reference pricing mechanisms standardize reimbursement across equivalent therapeutic alternatives.
Hemophilia Treatment Market Segmentation
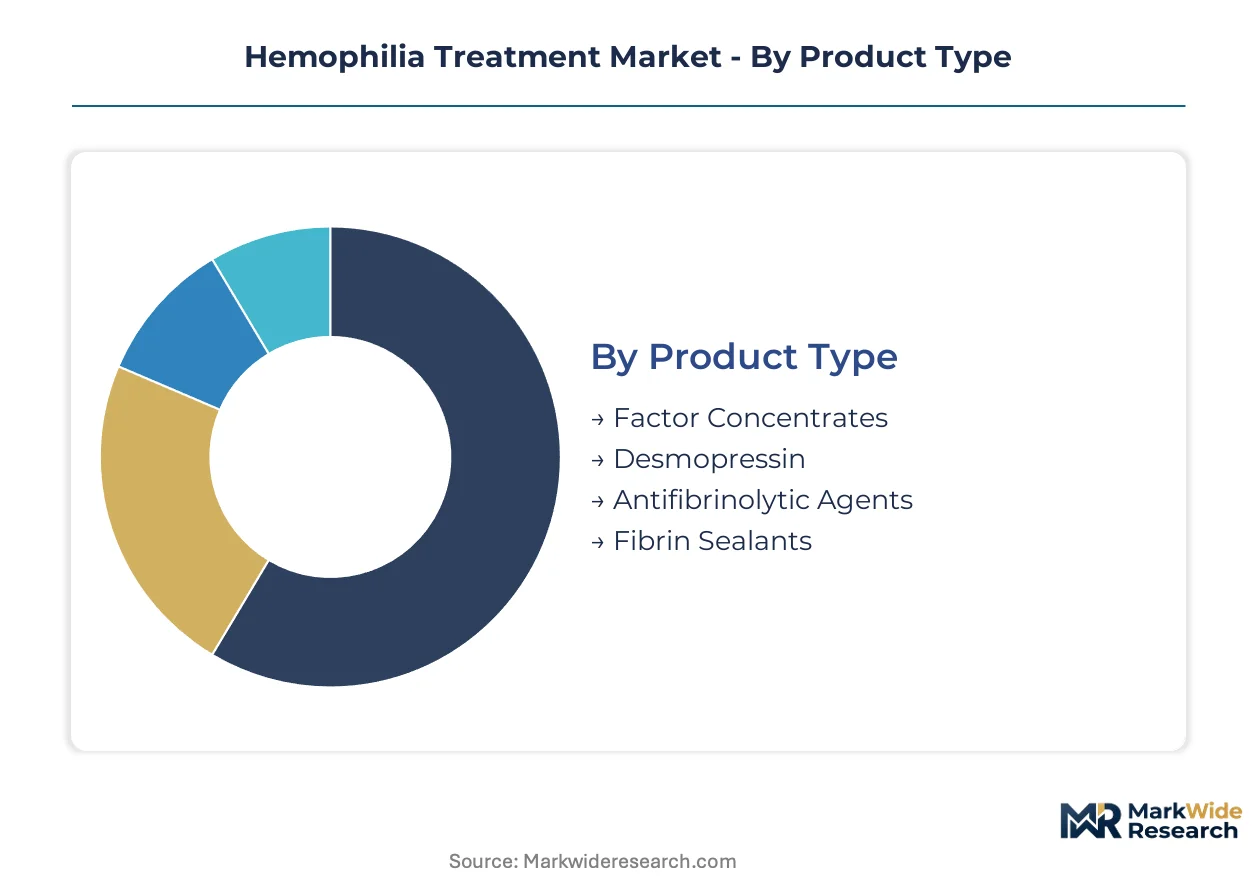
Treatment modality selection in hemophilia care hinges on disease severity, inhibitor status, and patient lifestyle compatibility. Segmentation reveals where pharmaceutical investment concentrates versus where clinical practice lags behind approved indications.
Product Type:
Recombinant DNA platforms now dominate development pipelines, displacing plasma-derived alternatives through reduced pathogen transmission risk and supply security.
- Factor Concentrates:Recombinant factor VIII and IX proteins constitute the therapeutic backbone, with Fc-fusion and PEGylation extending half-lives to reduce infusion burden. Demand clusters in the United States and Germany, where prophylactic regimens receive full reimbursement and home-infusion infrastructure is mature. Manufacturing scale constraints around viral vector production for gene therapies indirectly sustain factor concentrate volumes.
- Desmopressin:Synthetic vasopressin analogs stimulate endogenous factor VIII release from endothelial stores, limiting utility to mild hemophilia A and select von Willebrand disease phenotypes. Japan's reimbursement framework supports desmopressin as a cost-conscious alternative for mild cases, though severe disease progression eventually necessitates concentrate replacement.
- Antifibrinolytic Agents:Tranexamic acid and epsilon-aminocaproic acid inhibit plasmin-mediated fibrinolysis, serving as adjunctive therapy for mucosal bleeding.
- Fibrin Sealants:Topical hemostatic preparations deliver concentrated fibrinogen and thrombin for surgical field management.
Mature deployment sits with Factor Concentrates. Newer deployment is concentrated in Desmopressin for mild phenotypes.
Therapy Area:
Cost-tier stratification separates chronic prophylaxis from episodic intervention, with gene therapy commanding premium positioning against lifetime concentrate costs.
- Prophylactic Therapy:Scheduled factor administration prevents spontaneous bleeding and joint damage, requiring 2-3 weekly infusions for severe hemophilia A. Germany's sickness fund consortia negotiate multi-year agreements that secure manufacturer revenue predictability while ceding procurement authority from hospital committees.
- On-Demand Therapy:Episodic treatment responds to acute bleeding events, prevalent in resource-constrained settings where prophylaxis infrastructure is absent. Brazil's expanding hemophilia registry reveals underdiagnosed severe populations defaulting to on-demand protocols due to supply chain fragmentation.
- Gene Therapy:Single-administration AAV vector delivery of functional factor VIII or IX genes promises durable expression. FDA and EMA accelerated pathways compress development timelines, though durability uncertainty strains post-market surveillance infrastructure.
- Multidisciplinary Care:Integrated hematology, orthopedics, and physical therapy coordination optimizes long-term joint outcomes.
Mature deployment sits with On-Demand Therapy. Newer deployment is concentrated in Gene Therapy.
End User:
Site-of-care migration toward home administration reshapes distribution economics and patient data capture opportunities.
- Hospitals:Acute bleeding management and surgical prophylaxis sustain inpatient concentrate utilization, particularly for inhibitor patients requiring bypassing agents. United States tertiary centers maintain hemophilia treatment center networks that aggregate severe case volumes.
- Homecare:Subcutaneous delivery innovations enable patient self-administration, reducing hospital dependency and improving prophylactic adherence. CSL Behring's integrated home-infusion services exemplify vertical control over the patient relationship.
- Clinics:Outpatient hematology units manage stable patients between acute events.
- Specialty Pharmacies:Direct distribution nodes capture margin and deepen adherence program engagement.
Mature deployment sits with Hospitals. Newer deployment is concentrated in Homecare.
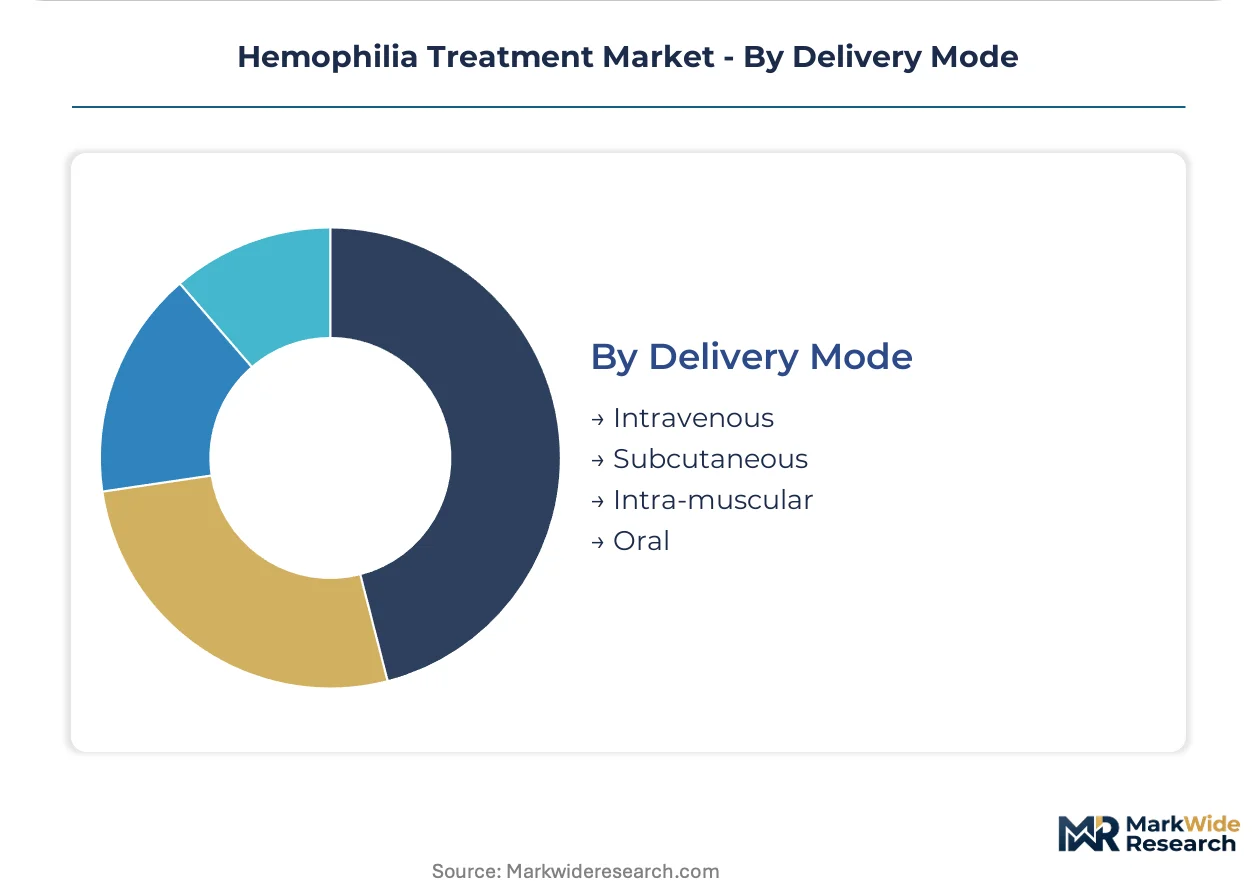
Delivery Mode:
Route selection determines dosing frequency, patient autonomy, and healthcare system cost structure.
- Intravenous:Direct factor concentrate infusion into circulation achieves immediate hemostatic levels, remaining standard for severe bleeding and surgical coverage. Central venous access devices in pediatric populations reduce peripheral vein trauma but introduce infection risk.
- Subcutaneous:Emicizumab's bispecific antibody architecture enables quarterly or less frequent dosing via subcutaneous injection, compressing hospital utilization. This modality is expanding fastest among end users as Takeda and Roche compete for prophylactic positioning.
- Intra-muscular:Limited applicability due to hematoma risk in coagulopathic patients.
- Oral:Restricted to desmopressin and antifibrinolytic adjuncts.
Mature deployment sits with Intravenous. Newer deployment is concentrated in Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors hemophilia treatment center concentration, hosting specialized hematology units that aggregate severe case volumes and drive clinical trial recruitment for novel therapies.
United States
Prophylactic factor concentrate reimbursement through commercial and Medicare Part B programs sustains chronic dosing models. FDA accelerated approval pathways compress gene therapy development timelines. North Carolina's Research Triangle Park hosts viral vector manufacturing facilities that supply AAV-based treatments.
Germany
Sickness fund consortia negotiate multi-year factor concentrate agreements that secure manufacturer revenue predictability. EMA's Committee for Medicinal Products for Human Use shapes post-market surveillance obligations for hemophilia therapies. Bavaria's Munich cluster concentrates specialized hemophilia treatment centers with integrated orthopedic and physical therapy coordination.
Japan
METI's reimbursement framework supports prophylactic regimens that reduce joint damage progression in severe hemophilia A patients. PMDA review pathways accommodate orphan drug applications for novel factor concentrates. Tokyo's Kanto region hosts the highest density of hemophilia treatment centers with home-infusion infrastructure.
Brazil
ANVISA streamlines biologics importation for underdiagnosed severe hemophilia populations transitioning from on-demand to prophylactic protocols. The Ministry of Health's national hemophilia registry expansion targets case identification in underserved regions. São Paulo's metropolitan health network aggregates the largest treated patient cohort in Latin America.
United Kingdom
NHS England's specialized commissioning framework concentrates hemophilia care within designated treatment centers. MHRA alignment with EMA standards facilitates parallel market access for recombinant and gene therapy products. London's Royal Free Hospital and Oxford University Hospitals anchor national gene therapy trial networks.
Hemophilia Treatment Market Vendor Landscape
Capital-heavy plasma fractionators compete with asset-light recombinant biologic developers for hemophilia market positioning. The vendor base concentrates around integrated plasma collectors, specialized biotechnology firms, and diversified pharmaceutical conglomerates with rare disease portfolios. Three archetypes dominate: plasma-derived concentrate specialists leveraging captive raw material supply, recombinant factor innovators extending half-life through Fc-fusion and PEGylation technologies, and gene therapy developers promising one-time administration. Competitive moves center on specialty pharmacy direct distribution partnerships and subscription-based patient support program expansion.
Within the plasma-derived concentrate tier, CSL Behring and Octapharma exemplify vertical control over collection-to-patient supply chains. Among recombinant factor innovators, Takeda Pharmaceutical Company Limited and Novo Nordisk occupy positions defined by geographic market dominance and portfolio breadth across hemophilia A and B indications. On the gene therapy frontier, BioMarin and F. Hoffmann-La Roche represent the transition from chronic replacement paradigms toward durable expression models.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical Company Limited |
| Pfizer |
| Bayer |
| Sanofi |
| Novo Nordisk |
| Octapharma |
| F. Hoffmann-La Roche |
| BioMarin |
| Others |
Supply Flow & Price Mechanics
Plasma collection infrastructure in the United States feeds downstream pricing tiers for factor concentrates, with raw material scarcity at collection centers translating into premium positioning for recombinant alternatives and cost-conscious procurement for plasma-derived products.
Pricing Analysis
Value-based pricing anchors on lifetime cost equivalence between gene therapy and chronic prophylaxis. Three-tier pricing structure across premium, standard, and economy levels separates gene therapy from extended half-life recombinants from standard factor concentrates. Pricing pressure stems from centralized sickness fund negotiations in Germany that compress margins on chronic replacement products. Hospital procurement committees exhibit highest price sensitivity, while specialty pharmacy direct distribution channels absorb premium markups for adherence program bundling.
Supply Chain Analysis
Viral vector production capacity rests on contract development organizations concentrated in the United States, Germany, and Switzerland. AAV manufacturing draws from plasmid DNA, HEK293 cell lines, and chromatography resins as critical inputs. Single-source vulnerability around plasmid suppliers creates bottleneck risk for gene therapy batch release. Distribution runs through specialty pharmacy networks that disintermediate hospital outpatient channels and capture patient data for adherence programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with captive plasma supply or gene therapy manufacturing expertise, with gene therapy durability uncertainty forcing subscale recombinant producers toward exit.
For Market Incumbents: Acquire viral vector manufacturing capacity to secure gene therapy supply chain control against emerging biotech developers. Lock in multi-year plasma collection agreements in the United States to defend raw material access. Invest in subcutaneous delivery platform R&D to differentiate from intravenous-dependent competitors. For New Entrants and Emerging Players: Direct-to-patient digital channels enable bypass of consolidated hospital procurement committees in Germany and the United States. Target Brazil's underdiagnosed severe hemophilia populations transitioning from on-demand to prophylactic protocols. Pursue ANVISA regulatory consulting partnerships to accelerate biologics importation licensing. For Investors and Strategic Acquirers: FDA gene therapy durability guidance publication is the leading indicator that payer confidence will solidify for single-administration premiums. Position for 5-10 year horizon where gene therapy developers with post-market surveillance infrastructure command valuation premiums. Watch EMA accelerated assessment pathway approvals as inflection signal for European reimbursement traction.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | AAV viral vector capacity expansion in North Carolina's Research Triangle Park reduces patient wait times. |
| Specialty Pharmacy Direct Distribution | Disintermediation of hospital channels captures margin and deepens adherence data capture for CSL Behring. |
| Extended Half-Life Factor Fusion | Fc-fusion and PEGylation technologies reduce infusion frequency and differentiate Takeda's portfolio positioning. |
| Patient Support Program Subscription | Integrated home-infusion services sustain long-term retention beyond the vial itself for chronic prophylaxis patients. |
| Regulatory Accelerated Pathway Navigation | FDA and EMA orphan drug exclusivity incentives compress development timelines for novel hemophilia B gene therapies. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Bottom-up and top-down triangulation validated patient population estimates and treatment cost models across recombinant, plasma-derived, and gene therapy modalities.
Bottom-up modeling anchored on patient cohort sizing by severity and inhibitor status, while top-down checks applied reimbursement framework analysis across the United States, Germany, and Japan. Segmentation dimensions included treatment modality, therapy area, end user setting, and delivery mode. CAGRs derived from pricing trajectory analysis and volume elasticity assumptions around gene therapy uptake curves and factor concentrate prophylaxis adherence rates.
The model holds under stable gene therapy durability data and payer willingness frameworks; deviation in long-term factor expression monitoring outcomes or centralized tender negotiation expansion would shift volume and value projections. A small set of named triggers—EMA post-market surveillance requirements, FDA gene therapy labeling updates, and Brazil's hemophilia registry completion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Global Therapeutic Vaccines Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Market