
 Global Gene Therapy Market | 2026-2036
Global Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gene Therapy Market Intelligence
A shortage of viral vector manufacturing specialists is redrawing competitive boundaries across the gene therapy landscape. Novartis AG leverages its Basel-based cell and gene therapy manufacturing network to sustain supply security for approved therapies. bluebird bio anchors its position through concentrated expertise in lentiviral vector production for rare disease indications.
Gene therapy encompasses the delivery of nucleic acid constructs into target cells to correct, replace, or silence defective genes, typically employing engineered viral capsids with defined tropism profiles or lipid nanoparticle formulations with specific payload capacities exceeding 10 kilobases. Its primary commercial purpose centers on durable therapeutic correction of monogenic disorders and modulation of oncogenic pathways. Adeno-Associated Virus vectors dominate current revenue pools due to established safety profiles in ocular and CNS applications, while CRISPR-based editing platforms represent the fastest-expanding technology segment as clinical programs advance toward regulatory filings. Oncology applications command the largest share of active clinical trials, though genetic disorders generate premium pricing power due to smaller addressable populations and orphan drug designations.
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme are compressing development timelines while raising manufacturing quality benchmarks for commercial readiness. The EU's Clinical Trials Regulation and Japan's PMDA regenerative medicine framework are converging on standardized vector characterization requirements that shape global product development strategies. Stakeholders must monitor how evolving FDA guidance on long-term follow-up studies and the EU AI Act's implications for computational biology tools will reshape trial design and post-market surveillance obligations.
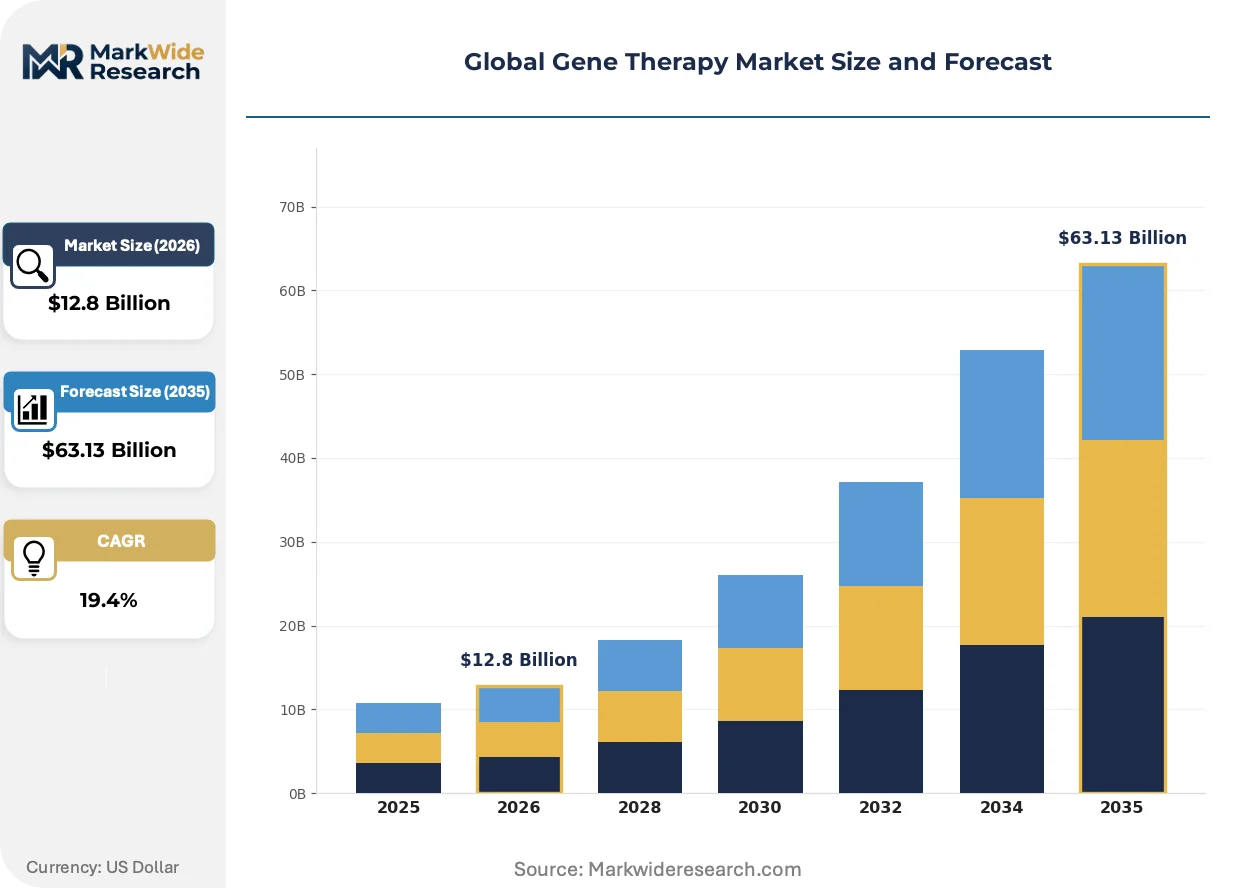
Market Dynamics
Viral vector manufacturing capacity scarcity is compressing development timelines and redrawing competitive boundaries across the gene therapy landscape, forcing developers to secure captive supply or risk program delays.
Growth Catalysts
- FDA's Regenerative Medicine Advanced Therapy designation:This pathway accelerates review timelines for qualifying candidates, compressing the interval between pivotal trial completion and commercial authorization.
- CRISPR-based editing platforms:Academic medical centers in Boston and Research Triangle Park are expanding in-house manufacturing capabilities to support these precision medicine programs.
- Orphan drug incentives:Premium pricing power in genetic disorders attracts development investment toward smaller addressable populations with unmet need.
Market Restraints
- Plasmid DNA supply concentration:Limited qualified suppliers in North America and Europe create single-source vulnerabilities for AAV production campaigns.
- Long-term follow-up study requirements:FDA guidance mandates 15-year patient monitoring post-treatment, extending liability windows and post-market surveillance costs.
- Lentiviral vector production complexity:Stable producer cell line development remains technically constrained, limiting batch-to-batch consistency for ex vivo applications.
Strategic Opportunities
- Japan's PMDA regenerative medicine framework:Conditional approval pathways enable earlier revenue generation for therapies demonstrating surrogate endpoints in limited populations.
- In vivo gene editing convergence:Integration of base editing with lipid nanoparticle delivery expands addressable targets beyond liver-localized indications.
- India's CDSCO emerging pathway:Local clinical trial requirements are evolving to accommodate global development programs, opening access to treatment-naive patient populations.
Industry Challenges
- Vector analytics standardization:Empty capsid quantification methods vary across contract manufacturers, complicating regulatory dossier preparation.
- Fill-finish capacity alignment:Aseptic processing bottlenecks at specialized CDMOs delay commercial launch readiness even when drug substance is available.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gene Therapy Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $63.13 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adeno-Associated Virus, Lentivirus, Retrovirus, Plasmid DNA Technology: CRISPR, TALEN, ZFN, RNA Interference Application: Oncology, Genetic Disorders, Infectious Diseases, Cardiovascular Diseases End User: Hospitals, Research Institutes, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Novartis AG, Biogen Inc., Pfizer, Spark Therapeutics, bluebird bio, Sarepta Therapeutics, Orchard Therapeutics, Alnylam Pharmaceuticals, Krystal Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gene Therapy Market Strategic Shifts & Innovations
Gene therapy manufacturing is experiencing a fundamental restructuring as platform technologies mature and regulatory frameworks converge on standardized quality benchmarks.
Next-generation AAV capsid engineering is bifurcating the vector landscape. Directed evolution platforms generate novel serotypes with enhanced tissue specificity and reduced immunogenicity. Large pharmaceutical developers are licensing these engineered variants to differentiate oncology and CNS pipelines. The technology is bifurcating competitive positioning between companies with proprietary capsid libraries and those dependent on legacy serotypes.
The EU AI Act is reshaping computational biology tool deployment. Machine learning models used for patient selection or manufacturing process optimization now face validation requirements for high-risk AI systems. Gene therapy developers utilizing predictive algorithms for vector design must document training data provenance and model interpretability. European sponsors are establishing dedicated AI governance functions to maintain compliance without constraining innovation cycles.
Hospital-based point-of-care manufacturing is disrupting traditional supply chain configurations. Academic medical centers in the United States are installing closed-system bioreactors for autologous cell therapy processing at bedside. This decentralization eliminates cold chain logistics for certain ex vivo applications. The shift is most visible in CAR-T adjacent programs where vein-to-vein time critically determines patient eligibility and clinical outcomes.
Global Gene Therapy Market Segmentation
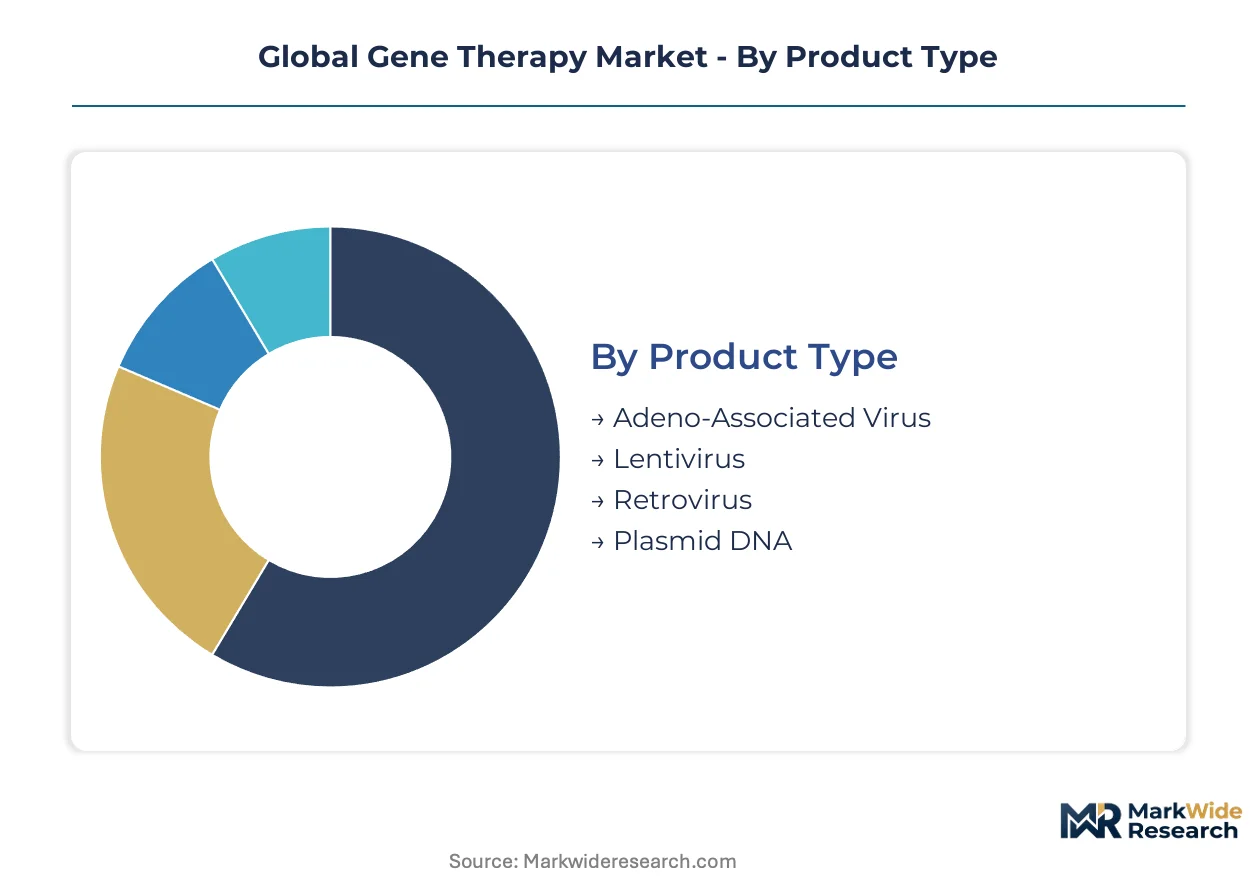
Gene therapy market segmentation reflects distinct regulatory pathways, manufacturing complexity tiers, and reimbursement frameworks that determine commercial viability. Each category carries specific FDA, EMA, and PMDA compliance requirements that shape product development timelines and capital allocation decisions.
Product Type:
FDA's regenerative medicine guidance and EMA's advanced therapy medicinal products framework impose divergent purity specifications across vector categories, with capsid empty-to-full ratios and residual host cell DNA limits varying by delivery mechanism.
- Adeno-Associated Virus:Engineered capsids with tissue-specific tropism profiles dominate ocular and CNS applications due to established safety databases. Demand concentrates in Boston and Research Triangle Park academic medical centers expanding in-house GMP suites for AAV production.
- Lentivirus:Stable producer cell line development remains technically constrained, limiting batch consistency for ex vivo CAR-T and stem cell modification programs. bluebird bio anchors manufacturing expertise for rare disease indications requiring lentiviral delivery.
- Retrovirus:Gamma-retroviral platforms retain utility in hematopoietic stem cell gene therapy despite integration profile concerns. Clinical applications center on severe combined immunodeficiency and other primary immunodeficiencies.
- Plasmid DNA:Linearized constructs serve as starting material for mRNA and AAV production campaigns. Supply concentration in North America and Europe creates single-source vulnerabilities for manufacturing scale-up.
Adeno-Associated Virus handles the majority of throughput; Lentivirus is the fastest mover on share.
Technology:
Cost tier differentiation separates platform technologies by intellectual property licensing fees, reagent expenses, and specialized equipment requirements that determine accessibility for academic versus commercial developers.
- CRISPR:Programmable nuclease systems with guide RNA-directed specificity enable multiplexed editing and base modification. Academic medical centers in Boston and Research Triangle Park are expanding manufacturing capabilities to support precision medicine programs.
- TALEN:Transcription activator-like effector nucleases offer reduced off-target profiles compared to first-generation platforms. Agricultural and industrial biotech applications precede therapeutic adoption due to regulatory pathway clarity.
- ZFN:Zinc finger nuclease platforms retain relevance in ex vivo settings where validated delivery protocols exist. Sangamo Therapeutics maintains proprietary position in HIV reservoir reduction and hemophilia B programs.
- RNA Interference:siRNA and shRNA modalities provide transient gene silencing without permanent genomic modification. Alnylam Pharmaceuticals and Ionis Pharmaceuticals dominate commercial development with liver-targeted GalNAc conjugate delivery.
CRISPR commands the premium development tier; RNA Interference delivers the steepest volume expansion as chronic disease applications mature.
Application:
Orphan drug incentives and reimbursement pressure create margin stratification across therapeutic areas, with genetic disorders commanding premium pricing against oncology's volume-driven competitive dynamics.
- Oncology:CAR-T and TCR-T cell therapies represent the largest share of active clinical trials. Novartis AG leverages its Basel-based manufacturing network to sustain supply security for approved hematologic malignancy treatments.
- Genetic Disorders:Monogenic conditions with well-defined patient populations generate premium pricing power. Spinal muscular atrophy, hemophilia, and inherited retinal dystrophies anchor commercial portfolios.
- Infectious Diseases:Functional cure approaches for HIV and hepatitis B utilize gene editing to disrupt viral reservoirs. Development timelines extend due to complex endpoint validation requirements.
- Cardiovascular Diseases:Angiogenic gene therapy and gene editing for familial hypercholesterolemia represent emerging applications. Verve Therapeutics advances PCSK9 inactivation programs toward regulatory filings.
Oncology generates the highest trial volume; Genetic Disorders capture the fastest regulatory approval velocity.
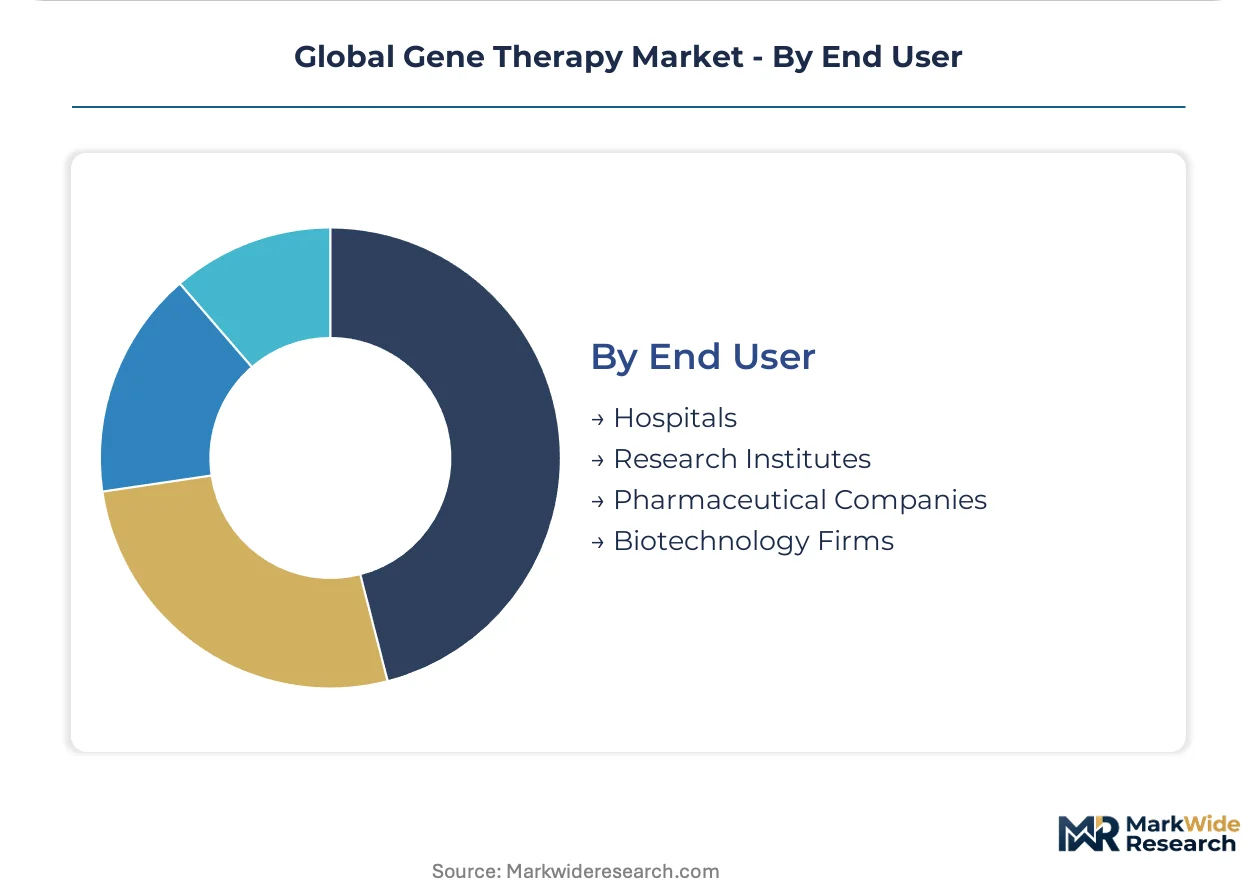
End User:
Customer type determines facility investment scale, regulatory inspection frequency, and quality system sophistication required for GMP compliance across the value chain.
- Hospitals:Academic medical centers are installing closed-system bioreactors for point-of-care autologous processing. This decentralization eliminates cold chain logistics for certain ex vivo applications.
- Research Institutes:Preclinical vector production and proof-of-concept studies drive demand for small-scale GMP suites. Technology transfer to commercial partners depends on standardized analytical methods.
- Pharmaceutical Companies:Large developers license engineered capsid variants to differentiate oncology and CNS pipelines. Manufacturing investments prioritize captive supply security over contract manufacturing dependence.
- Biotechnology Firms:Emerging companies concentrate on single-vector platforms and specific tissue targeting modalities. Partnership structures with CDMOs determine program timelines and regulatory risk profiles.
Pharmaceutical Companies deploy the largest capital commitments; Biotechnology Firms are gaining share fastest through platform specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy consumption patterns diverge sharply by geography. The United States prioritizes oncology applications with premium reimbursement structures, while Japan and Germany concentrate on rare disease frameworks with conditional approval pathways. Switzerland and the United Kingdom anchor manufacturing and regulatory innovation respectively.
United States
FDA's Regenerative Medicine Advanced Therapy designation accelerates commercial authorization timelines for qualifying candidates. The 15-year post-treatment follow-up mandate extends liability windows for developers. Boston and Research Triangle Park academic medical centers are expanding in-house GMP vector manufacturing suites to support precision medicine programs.
Switzerland
Swissmedic's alignment with EMA advanced therapy medicinal products standards enables streamlined European market access. Basel anchors a concentrated cell and gene therapy manufacturing network serving continental supply security needs. Novartis AG leverages this infrastructure to sustain commercial operations for approved hematologic malignancy treatments.
Germany
The country's national pharmaceutical regulator enforces stringent vector characterization requirements under EU Clinical Trials Regulation convergence. Munich and Heidelberg clusters concentrate CRISPR-based editing platform development toward regulatory filings. Hospital-based point-of-care manufacturing pilots are disrupting traditional cold chain logistics for autologous applications.
Japan
PMDA's regenerative medicine framework enables conditional approval based on surrogate endpoints in limited populations. This pathway compresses revenue generation timelines compared to full approval requirements. Tokyo and Osaka academic medical centers are installing closed-system bioreactors for bedside autologous cell therapy processing.
United Kingdom
MHRA post-Brexit alignment with international standards maintains attractiveness for global clinical trial placement. London and Cambridge clusters concentrate lentiviral vector expertise for rare disease indications. The national health system's outcome-based reimbursement negotiations are reshaping pricing power for genetic disorder therapies.
Global Gene Therapy Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in gene therapy competitive structure. Large pharmaceutical developers with captive manufacturing networks control supply security for commercial-stage assets. Biotechnology firms concentrate on single-vector platforms and specific tissue targeting modalities. Strategic moves center on capacity expansion through in-house GMP suite installation and technology licensing for engineered capsid variants.
Within the integrated pharmaceutical tier, Novartis AG and Pfizer occupy positions defined by manufacturing network scale and regulatory dossier experience. bluebird bio exemplifies the specialist archetype, anchoring expertise concentration in lentiviral vector production for rare disease indications. These three entities represent distinct competitive positioning: network-scale supply security, diversified platform breadth, and focused vector specialization respectively.
| Leading Market Players |
|---|
| Novartis AG |
| Biogen Inc. |
| Pfizer |
| Spark Therapeutics |
| bluebird bio |
| Sarepta Therapeutics |
| Orchard Therapeutics |
| Alnylam Pharmaceuticals |
| Krystal Biotech |
| Others |
Cost & Logistics Intelligence
Twenty-four to thirty-six month viral vector manufacturing lead times compress pricing power for developers lacking captive supply, concentrating margin capture among integrated manufacturers with Basel and Boston-based GMP networks while forcing price-sensitive biotechnology firms toward contract manufacturing dependence.
Pricing Analysis
Long-term offtake agreements dominate commercial-stage gene therapy procurement, with multi-year supply contracts anchoring vector pricing for approved therapies while spot purchasing governs clinical-trial-stage campaigns. Three-tier pricing structure across premium, standard, and economy levels separates FDA-registered GMP suites from research-grade production and emerging-market CDMO offerings. Price differentiation hinges on capsid empty-to-full ratio certification and validated plasmid DNA provenance. Pricing pressure stems from plasmid DNA supply concentration in North America and Europe, tightening margins for developers without backward integration into starting material production. Biotechnology firms exhibit highest price sensitivity due to capital constraints, while pharmaceutical companies prioritize supply security over unit cost.
Supply Chain Analysis
Inbound logistics costs for temperature-sensitive viral vector shipments concentrate risk on trans-Atlantic and trans-Pacific trade lanes, where cold chain integrity failures can invalidate entire GMP production batches. Supply concentrates in the United States, Switzerland, and Germany, with Basel and Boston anchoring commercial-scale manufacturing and Heidelberg supporting CRISPR platform development. Plasmid DNA, specialized cell culture media, and qualified resin feeds constitute critical input dependencies. Single-source vulnerability in plasmid DNA supply creates structural risk for AAV production scale-up. Distribution runs through specialized biologics couriers with validated cold chain protocols, bypassing general freight networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
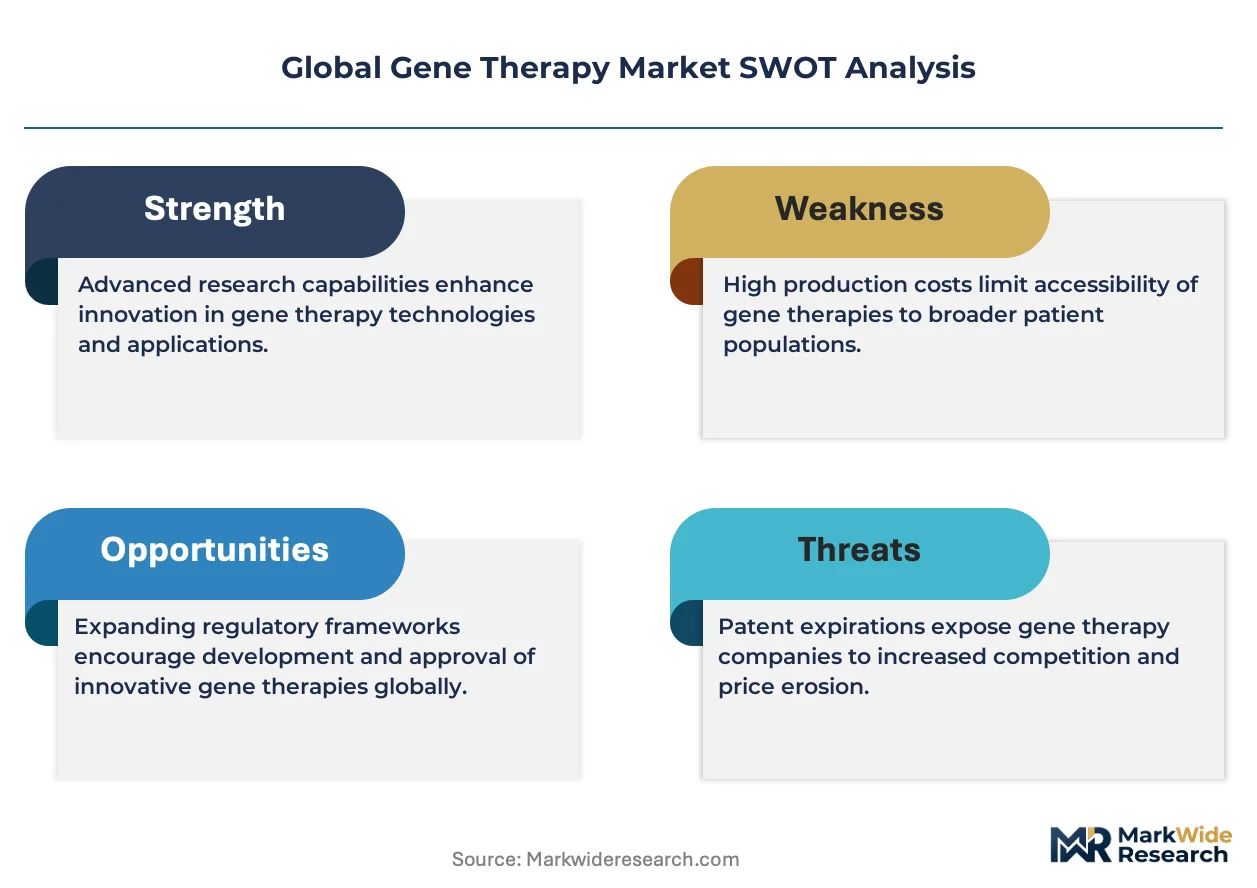
This market functions as a defensive-moat story where regulatory entrenchment and fifteen-year FDA follow-up mandates create switching costs that protect incumbent positions against new vector platform entrants.
For Market Incumbents: Compound manufacturing network advantages by expanding Basel-based GMP capacity and securing captive plasmid DNA supply through backward integration into starting material production. Vector analytics standardization gaps across contract manufacturers present margin defense opportunities through proprietary quality benchmarking. Threat from CRISPR-based editing platforms displacing legacy viral delivery necessitates licensing convergence with base editing innovators. Capacity addition in Research Triangle Park academic medical centers reinforces geographic clustering benefits. For New Entrants and Emerging Players: Point-of-care manufacturing equipment and closed-system bioreactor installation services represent underserved white space where incumbents under-serve hospital-based autologous processing demand. India's CDSCO emerging pathway offers the most penetrable regulatory geography for treatment-naive patient access. Japan's conditional approval framework enables earlier revenue generation for therapies demonstrating surrogate endpoints. Go-to-market positioning should target academic medical center GMP suite outsourcing partnerships rather than direct therapeutic development. For Investors and Strategic Acquirers: Long-term, this sits as a platform-specialization play because vector manufacturing expertise concentrates irreplaceably in limited human capital pools with decade-long training curves. Acquisition targets should display concentrated lentiviral or AAV production capabilities with established regulatory dossier experience. The signal to watch is FDA guidance evolution on long-term follow-up study design, which would reshape liability duration assumptions and capital allocation efficiency across development portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive GMP capacity in Basel and Boston secures supply continuity for commercial-stage gene therapies. |
| Regulatory Approval Pathway | FDA Regenerative Medicine Advanced Therapy designation compresses review timelines for qualifying candidates. |
| Licensing Agreement | Engineered capsid variant partnerships differentiate oncology and CNS pipeline positioning. |
| Pipeline Diversification | CRISPR-based editing platform integration expands addressable targets beyond liver-localized indications. |
| Clinical Trial Advancement | EU Clinical Trials Regulation convergence shapes standardized vector characterization for dossier preparation. |
Research Approach
Operator-level perspectives from vector manufacturing directors, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down market sizing triangulation ensured methodological robustness.
Sensitivity analysis framed the quantitative approach, with segmentation across vector type, technology platform, therapeutic application, and end-user category modeled throughout the forecast period. CAGRs derived from historical approval velocity analysis and pipeline progression rates. Forecast inputs incorporated manufacturing capacity expansion timelines, regulatory pathway conversion probabilities, and reimbursement negotiation outcomes by national health system archetype.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA frameworks; material policy shifts would require re-modeling of development timeline assumptions and commercial authorization probabilities. Vector immunogenicity signal emergence or manufacturing quality enforcement changes represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Global Therapeutic Vaccines Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market