
 Global Hospital Asset Management Market | 2026-2036
Global Hospital Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Asset Management Market Foresight
Consolidation among integrated delivery networks is recalibrating procurement priorities for enterprise-wide asset visibility. GE Healthcare leverages its installed base of imaging equipment to extend into connected asset management platforms. IBM Corporation anchors its position through Watson IoT integration with hospital electronic health record systems. Siemens Healthineers competes on workflow automation tied to its diagnostic device ecosystem.
Hospital asset management encompasses the systematic tracking, maintenance, and utilization optimization of medical equipment and supplies through automated identification and real-time monitoring technologies. RFID Solutions operate at ultra-high frequency bands to enable room-level accuracy for infusion pumps and wheelchairs without line-of-sight scanning requirements. Cloud Computing infrastructure now dominates deployment architecture as health systems prioritize centralized dashboards over on-premise servers. Artificial Intelligence applications within inventory forecasting represent the fastest-expanding technology segment, with algorithms predicting utilization patterns to reduce rental expenses and capital overstock.
The FDA enforces Unique Device Identification requirements that mandate standardized labeling for traceability across the device lifecycle, directly expanding addressable market for automated tagging systems. EMA's Medical Device Regulation imposes equivalent post-market surveillance obligations across European member states, creating parallel compliance-driven replacement cycles. Stakeholders must monitor how CMS reimbursement rules for hospital-acquired conditions reshape capital allocation toward predictive maintenance capabilities that reduce equipment-related adverse events.
Market Dynamics
Health system consolidation into multi-site networks is forcing procurement departments toward enterprise-wide asset visibility platforms rather than siloed department-level tracking systems.
Growth Catalysts
- FDA Unique Device Identification:The mandate for standardized medical device labeling creates replacement demand for legacy infrastructure across US hospital networks.
- Cloud Computing migration:Health systems are abandoning on-premise servers for centralized dashboards that enable remote monitoring of equipment utilization rates.
- RFID ultra-high frequency deployment:Room-level accuracy without line-of-sight requirements is eliminating manual scanning workflows for infusion pumps and wheelchairs.
Market Restraints
- Capital intensity of retrofit:Legacy equipment lacking native connectivity requires expensive hardware overlays before software platforms can function.
- Interoperability fragmentation:Proprietary data protocols from incumbent device manufacturers block seamless integration with third-party asset management platforms.
- Cybersecurity liability exposure:Connected medical devices create attack surfaces that trigger higher malpractice insurance premiums and IT security staffing demands.
Strategic Opportunities
- Artificial Intelligence convergence with inventory forecasting:Machine learning algorithms predicting utilization patterns can reduce rental expenses and capital overstock for health systems.
- EMA Medical Device Regulation compliance cycles:European post-market surveillance obligations are creating parallel demand for automated tagging systems across EU member states.
- Value-based care contracting expansion:CMS reimbursement rules for hospital-acquired conditions are redirecting capital toward predictive maintenance capabilities that reduce equipment-related adverse events.
Industry Challenges
- Integration complexity with EHR systems:Hospital IT departments face multi-year timelines to synchronize asset data flows with electronic health record architectures from incumbent vendors.
- Specialized technician scarcity:Biomedical engineering teams lack training in radio-frequency engineering and cloud infrastructure management required for next-generation platform maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Asset Management Market |
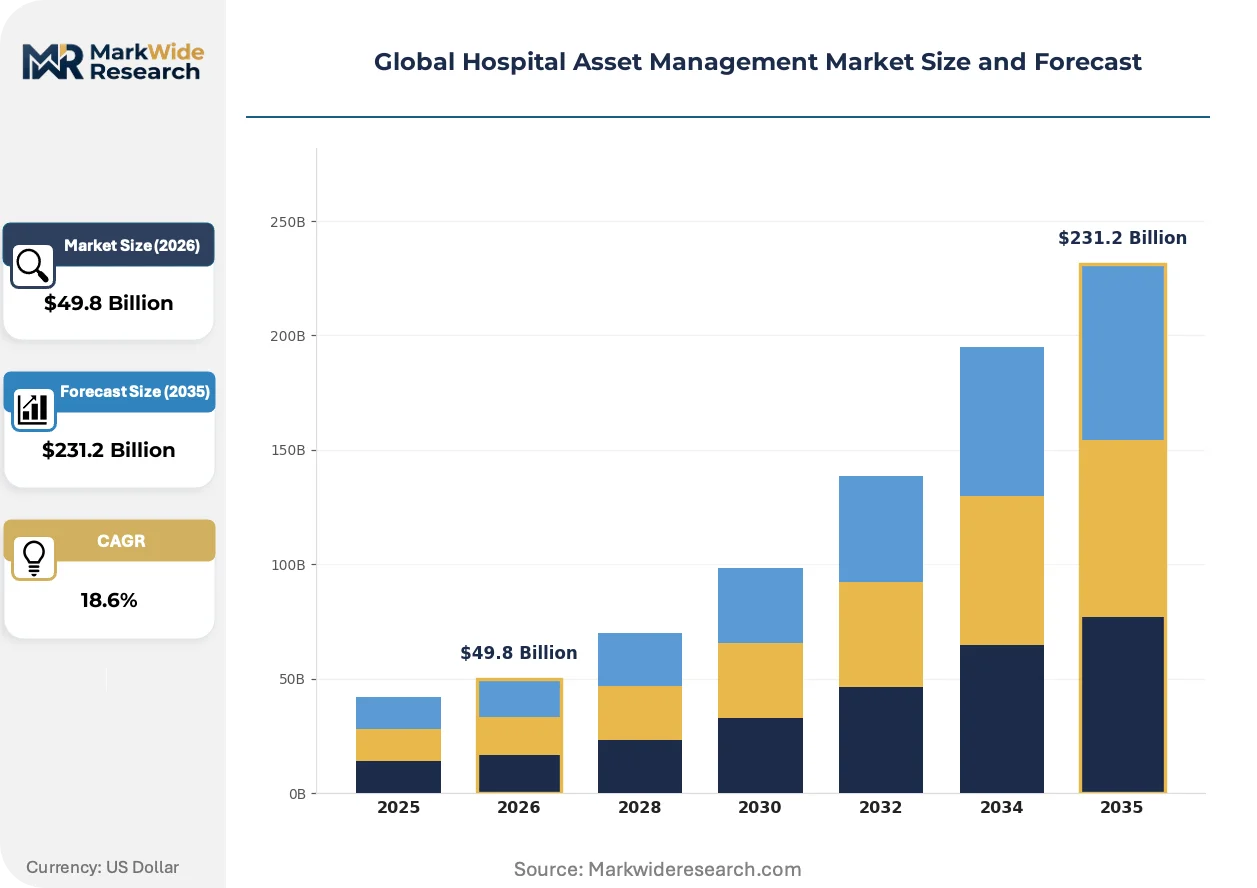
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $231.2 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFID Solutions, Barcoding Systems, GPS Trackers, Asset Tagging, Medical Equipment Monitoring Technology: IoT, Cloud Computing, Artificial Intelligence, Blockchain, Data Analytics Application: Inventory Tracking, Equipment Maintenance, Resource Optimization, Compliance Management, Workflow Automation End User: Hospitals, Diagnostic Centers, Surgical Centers, Rehabilitation Facilities, Ambulatory Services |
| Companies Covered | GE Healthcare, IBM Corporation, Siemens Healthineers, Zebra Technologies Corporation, STANLEY Healthcare, CenTrak Inc., AiRISTA Flow, Sonitor Technologies, Awarepoint Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Asset Management Market Shifts & Advancements
Real-time location systems are migrating from passive tracking to active workflow orchestration, with sensor networks now triggering automated maintenance dispatch and patient flow optimization.
Bluetooth Low Energy beacon infrastructure is rewriting how hospitals locate mobile equipment. These mesh networks transmit proximity data to central dashboards, enabling nurses to find nearest-available wheelchairs or infusion pumps within seconds. Academic medical centers in the United States are deploying BLE at scale, compressing equipment search time from fifteen minutes to under sixty seconds and directly improving patient throughput metrics.
The FDA's Unique Device Identification rule is mandating standardized labeling for traceability across the device lifecycle. This regulatory pressure is compelling healthcare providers to replace barcode-only systems with automated identification technologies that capture unique device identifiers at point of use. Cardiac catheterization labs and surgical suites face the steepest compliance timelines, driving concentrated procurement of RFID-enabled instrument tracking.
Health system procurement departments are consolidating vendor relationships around integrated platform providers rather than point solutions. Single-source contracts spanning hardware, software, and implementation services are displacing multi-vendor assemblies that created data silos. Integrated delivery networks with ten or more hospital campuses are most aggressive in this consolidation, using purchasing volume to extract performance guarantees from enterprise platform vendors.
Global Hospital Asset Management Market Segmentation
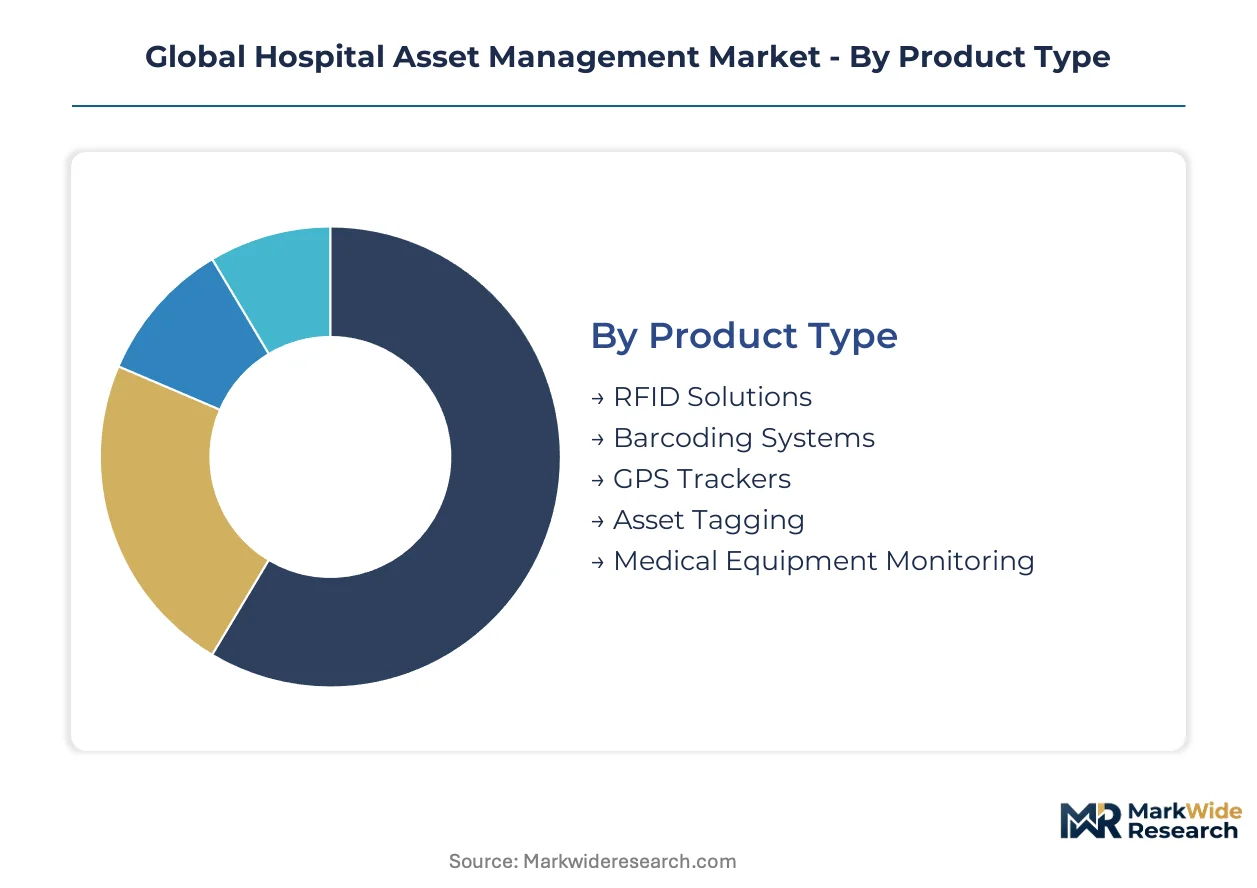
Hospital asset management procurement follows distinct technology refresh cycles across hardware, software, and service layers. Segmentation reveals where health systems concentrate capital as regulatory deadlines and operational pressures force infrastructure replacement.
Product Type:
Upgrade cycles vary sharply by product maturity, with legacy barcode systems facing accelerated replacement while emerging sensor categories capture greenfield deployment budgets.
- RFID Solutions:Ultra-high frequency tags and readers enable room-level location accuracy without line-of-sight scanning. United States health systems deploy these most aggressively in cardiac catheterization labs to meet FDA Unique Device Identification deadlines for high-risk device traceability.
- Barcode Systems:Linear and 2D barcode infrastructure dominates installed base but requires scanner hardware replacement to capture FDA-mandated unique device identifiers at point of care. European hospitals under EMA Medical Device Regulation face parallel compliance-driven refresh timelines.
- GPS Trackers:Satellite-based positioning serves mobile assets across sprawling hospital campuses and satellite clinics where indoor precision matters less than outdoor fleet coordination.
- Asset Tagging:Passive and active tag hardware spans disposable labels for consumables through ruggedized beacons for surgical instruments, with material specification varying by sterilization requirements.
- Medical Equipment Monitoring:Sensor networks attached to infusion pumps, ventilators, and imaging equipment stream utilization and predictive maintenance data to centralized dashboards.
RFID Solutions sits at the top of the volume ranking, with Asset Tagging climbing the fastest as health systems expand beyond pilot deployments to enterprise-wide instrument tracking.
Technology:
Architecture decisions increasingly favor cloud-native platforms over on-premise installations, reshaping vendor selection criteria and implementation timelines across deployment categories.
- IoT:Sensor networks and edge computing nodes collect real-time telemetry from connected medical devices. United States academic medical centers deploy these at scale to compress equipment search times and improve patient throughput metrics.
- Cloud Computing:Centralized infrastructure enables remote monitoring of utilization rates across multi-site hospital networks without capital-intensive server maintenance. Health system consolidation into integrated delivery networks accelerates procurement of SaaS-based asset visibility platforms.
- Artificial Intelligence:Machine learning algorithms predict utilization patterns to reduce rental expenses and capital overstock, representing the segment gaining share fastest as procurement departments prioritize outcome-based analytics.
- Blockchain:Distributed ledger technology supports immutable device lifecycle records for regulatory audit trails, though deployment remains concentrated in pilot programs at leading health systems.
- Data Analytics:Business intelligence tools aggregate asset telemetry into dashboards for procurement and biomedical engineering teams, with integration complexity varying by electronic health record vendor.
Cloud Computing commands the largest deployment share, with Artificial Intelligence expanding most quickly as predictive capabilities prove ROI through reduced equipment rental spend.
Application:
Use case prioritization reflects immediate compliance pressure versus longer-term operational efficiency, with regulatory deadlines forcing sequencing that favors tracking over optimization.
- Inventory Tracking:Real-time location systems monitor consumables, implants, and mobile equipment across hospital campuses. United States surgical suites deploy these most intensively to eliminate manual counts and capture unique device identifiers for FDA compliance.
- Equipment Maintenance:Predictive algorithms and automated work order dispatch extend asset lifespan and reduce emergency repair costs. CMS reimbursement rules for hospital-acquired conditions redirect capital toward these capabilities as risk mitigation investments.
- Resource Optimization:Utilization analytics identify underused equipment for redeployment or disposal, addressing capital efficiency pressures under value-based care contracts.
- Compliance Management:Automated documentation of device location, sterilization status, and maintenance history supports regulatory audit readiness across FDA and EMA jurisdictions.
- Workflow Automation:Sensor-triggered alerts and automated dispatch streamline patient flow and equipment availability, with Bluetooth Low Energy infrastructure enabling sub-minute equipment location in leading deployments.
Inventory Tracking leads procurement volume, with Workflow Automation demonstrating the steepest expansion trajectory as real-time location systems mature from passive tracking to active orchestration.
End User:
Facility type determines scale economics and integration complexity, with multi-site networks commanding platform pricing that smaller surgical centers cannot access.
- Hospitals:Acute care facilities with 200+ beds deploy enterprise-wide platforms spanning RFID, cloud infrastructure, and AI analytics. United States health system consolidation creates procurement departments with authority to mandate standardized asset visibility across ten or more campuses.
- Diagnostic Centers:Imaging-focused facilities prioritize tracking of mobile equipment and contrast media inventory, with integration into radiology information systems driving vendor selection.
- Surgical Centers:Ambulatory surgery facilities face compressed FDA compliance timelines for high-risk device traceability, concentrating demand for RFID-enabled instrument tracking in cardiac and orthopedic specialties.
- Rehabilitation Facilities:Long-term care and physical therapy centers track durable medical equipment across extended patient stays, with lower sensor density requirements than acute settings.
- Ambulatory Services:Mobile clinics and home health operations require GPS-enabled tracking for equipment deployed across dispersed geographies, with cellular connectivity substituting for hospital WiFi infrastructure.
Hospitals dominate absolute spending, with Surgical Centers showing the fastest growth rate as outpatient migration and regulatory deadlines converge on this facility type.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in the United States, Germany, and Japan anchor the geographic distribution of hospital asset management innovation. Health system consolidation and regulatory compliance timelines concentrate procurement authority in these markets.
United States
Integrated delivery networks spanning ten or more campuses mandate enterprise-wide asset visibility platforms. FDA Unique Device Identification deadlines for high-risk medical devices accelerate RFID deployment in cardiac catheterization labs. The Boston-Cambridge corridor hosts concentrated academic medical centers deploying Bluetooth Low Energy infrastructure at scale.
Germany
University hospital networks prioritize predictive maintenance capabilities to extend imaging equipment lifespan. EMA Medical Device Regulation post-market surveillance obligations drive automated tagging system procurement across Baden-Württemberg and Bavaria. Siemens Healthineers anchors diagnostic device ecosystem integration from its Erlangen headquarters.
Japan
Super-aging demographics compress equipment utilization optimization timelines in Tokyo and Osaka metropolitan hospitals. METI industrial policy supports IoT sensor network adoption for remote monitoring of mobile medical devices. The Kansai region concentrates pilot deployments for AI-driven inventory forecasting algorithms.
United Kingdom
NHS England procurement frameworks consolidate vendor relationships around integrated platform providers. GDPR compliance requirements shape cloud infrastructure selection for multi-site hospital networks. London teaching hospitals lead European adoption of real-time location systems for surgical instrument tracking.
China
Tier-3 hospital expansion programs in the Yangtze River Delta generate greenfield demand for connected asset management infrastructure. NMPA medical device traceability regulations align with international UDI standards. Shanghai's medical device industrial park hosts domestic RFID hardware manufacturing clusters.
Global Hospital Asset Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology layers. The market exhibits tiered concentration with imaging equipment incumbents leveraging installed base advantages against independent software vendors. Three archetypes dominate: industrial conglomerates with healthcare divisions, enterprise software platforms extending into healthcare verticals, and dedicated real-time location system specialists. Strategic moves center on cloud infrastructure partnerships and AI capability acquisitions rather than horizontal consolidation.
Among industrial conglomerates with healthcare divisions, GE Healthcare and Siemens Healthineers exemplify equipment-centric platform strategies. IBM Corporation represents enterprise software platforms extending through Watson IoT integration. These three anchors occupy positions reflecting distinct heritage advantages—imaging hardware, diagnostic workflows, and cognitive computing infrastructure respectively.
| Leading Market Players |
|---|
| GE Healthcare |
| IBM Corporation |
| Siemens Healthineers |
| Zebra Technologies Corporation |
| STANLEY Healthcare |
| CenTrak Inc. |
| AiRISTA Flow |
| Sonitor Technologies |
| Awarepoint Corporation |
| Others |
Supply & Pricing Matrix
Integrated delivery networks with ten or more campuses dominate procurement volume and enforce subscription-based SaaS pricing with performance guarantees rather than perpetual licensing. Their consolidated purchasing power compresses margins for point-solution vendors while rewarding integrated platform providers with multi-year enterprise contracts.
Pricing Analysis
Bundle-unbundle splits separate hardware-tag procurement from software-platform subscriptions, with RFID reader hardware typically sold outright while location analytics deploy as annual SaaS tiers. Price differentiation hinges on FDA UDI compliance certification and cloud deployment scale, with smaller surgical centers facing acute cost compression from EMA MDR retrofit mandates. Academic medical centers show lowest price sensitivity due to grant-funded innovation budgets, while community hospitals under value-based care contracts resist per-bed licensing fees.
Supply Chain Analysis
Semiconductor supply for UHF RFID chips rests on Taiwanese foundry capacity and Dutch lithography equipment, with antenna substrate materials drawing from Chinese and German specialty chemical producers. BLE beacon assembly concentrates in Shenzhen and Seoul, creating single-source vulnerability for hospital networks requiring rapid deployment scale. Distribution runs through North American and European medical device distributors with GPO contract access, bypassing direct OEM relationships for mid-tier health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic arbitrage between FDA-mandated U.S. replacement cycles and EMA MDR-driven European refresh waves, with compliance timeline gaps creating six-to-twelve month demand phasing advantages for vendors with dual-certification readiness.
For Market Incumbents: Anticipate cloud-native challengers undercutting on-premise maintenance revenue by embedding predictive analytics as standard SaaS features. Defend position through backward integration into UHF RFID chip design and captive production of sterilization-hardened tags for surgical instrument tracking. Prioritize Watson IoT-style EHR integration certifications that lock out third-party middleware.
For New Entrants and Emerging Players: Enter via AI-driven inventory forecasting modules that retrofit atop existing RTLS infrastructure without hardware replacement. Target ambulatory surgical centers facing compressed FDA compliance timelines with RFID-enabled instrument tracking as a managed service. Lead with utilization analytics ROI guarantees rather than infrastructure CapEx pitches.
For Investors and Strategic Acquirers: Enterprise software platforms expanding into healthcare verticals are the most active acquirer in this space, seeking RTLS specialists with hospital EHR integration capabilities. Long-term viability favors vendors with cloud-native architectures and AI/ML talent density over hardware-centric legacy players. Watch CMS reimbursement rule expansions for hospital-acquired conditions as the inflection signal for predictive maintenance capability valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | GE Healthcare leverages imaging installed base to mandate enterprise-wide asset visibility platform adoption. |
| Software Companion Development | Watson IoT integration with Epic and Cerner EHR systems creates switching costs for competing RTLS vendors. |
| FDA Submission | RFID-enabled surgical instrument tracking accelerates UDI compliance for cardiac catheterization labs. |
| CE Marking Pathway | EMA MDR post-market surveillance obligations drive automated tagging system procurement across German university hospitals. |
| Reimbursement Strategy | CMS hospital-acquired condition penalties redirect capital toward predictive maintenance capabilities reducing equipment-related adverse events. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, biomedical engineering director surveys, and GPO contract database analysis — were reconciled against secondary validation from FDA UDI guidance documents, EMA MDR implementation timelines, and CMS reimbursement rule filings. Primary fieldwork engaged RTLS vendor sales executives, health system IT directors, and surgical suite nursing leadership across integrated delivery networks. Bottom-up equipment deployment estimates and top-down health system IT budget allocations were triangulated to constrain forecast variance.
Data-stream reconciliation across product type, technology architecture, application use case, and facility tier dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment refresh cycle modeling and regulatory deadline impact assessment. Cloud migration velocity and AI/ML capability adoption curves served as healthcare-specific forecast inputs, with Bluetooth Low Energy infrastructure deployment timelines cross-referenced against academic medical center capital expenditure disclosures.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time utilization telemetry from legacy barcode systems introduce uncertainty bands around AI forecasting module adoption curves. Forecasts reflect assumptions regarding FDA UDI enforcement consistency and EMA MDR audit intensity. Regulatory timeline delays, health system merger activity, and cybersecurity incident frequency warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Specialty Medical Chairs Market