
 Europe Dental Software Market | 2026-2036
Europe Dental Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dental Software Market Foresight
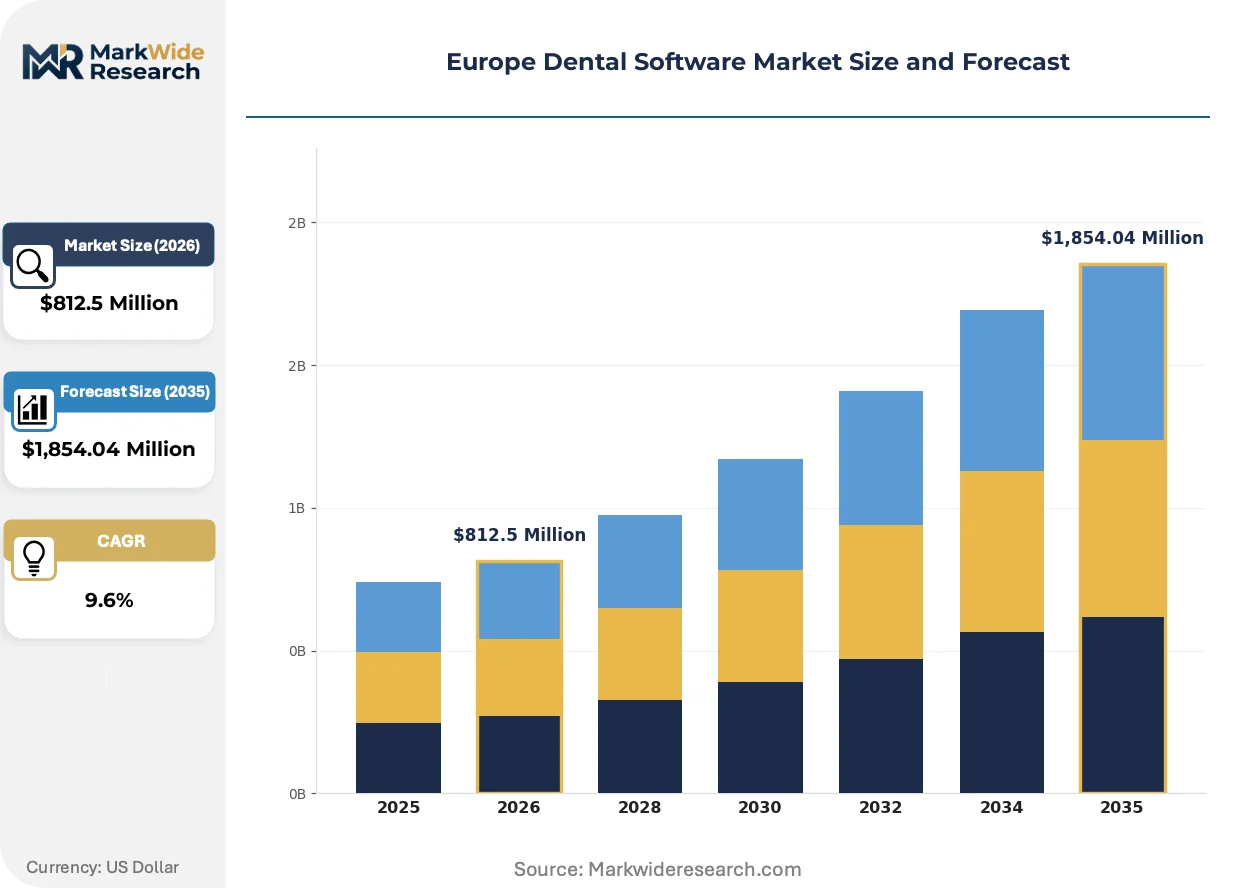
The capital-intensity divergence between cloud-native developers and legacy on-premises vendors is collapsing as subscription economics displace perpetual-license models. Dentsply Sirona leverages its installed base of imaging hardware to bundle software contracts across European dental chains. Henry Schein Inc anchors its position through distribution control in Nordic and Benelux markets. KaVo Dental GmbH competes by specializing in practice-management tools calibrated to German regulatory workflows.
Europe dental software encompasses clinical and administrative applications that manage patient records, treatment planning, billing, and diagnostic imaging across oral healthcare settings. These systems typically integrate DICOM-compliant imaging protocols, HL7 FHIR interoperability standards, and encrypted cloud architectures to ensure cross-border data portability within the European Economic Area. Practice Management and Imaging Software segments lead current revenue pools, reflecting persistent demand for workflow consolidation in multi-chair clinics. Cloud-based deployment is expanding fastest as Germany's BSI IT-Grundschutz certification and France's HDS health data hosting standards ease provider migration concerns.
The EU Medical Device Regulation and GDPR impose stringent clinical-validation and data-residency requirements on dental software marketed for diagnostic use across member states. EMA guidance on Software as a Medical Device and national health data authorities in France and Germany shape product roadmaps and market-access timelines. Stakeholders must monitor evolving CE-marking obligations for AI-powered imaging analysis tools and teledentistry platforms.
Market Dynamics
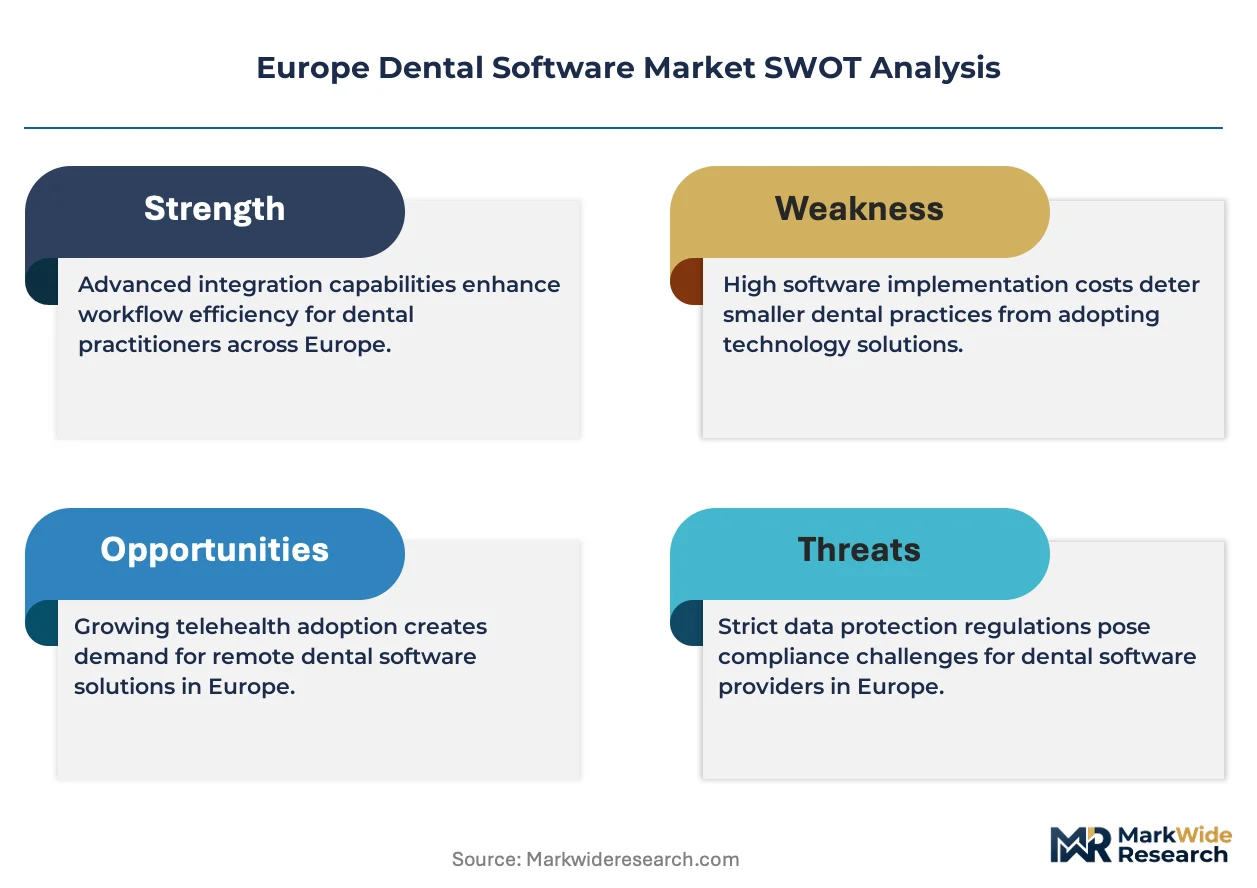
Cloud-native architectures are collapsing the traditional capital barrier between enterprise dental chains and independent practices across Europe, redistributing competitive advantage toward workflow integration depth rather than upfront IT spending power.
Growth Catalysts
- EU Medical Device Regulation:MDR's software validation requirements for diagnostic imaging tools are consolidating purchasing authority toward vendors with established CE-marking capabilities, accelerating replacement cycles for uncertified legacy systems.
- France's HDS certification:Health data hosting standards are removing migration friction for cloud-based patient management platforms, enabling dental networks in Paris and Lyon to consolidate multi-site operations.
- AI-powered radiographic analysis:Machine learning algorithms for caries detection and periodontal assessment are expanding addressable procedure volumes by embedding diagnostic support into routine hygiene appointments.
Market Restraints
- GDPR data-residency mandates:Cross-border patient data portability restrictions fragment cloud infrastructure economics, forcing vendors to maintain redundant hosting environments in Germany, France, and Benelux markets.
- Specialized dental informatics talent:Shortage of professionals fluent in both DICOM imaging protocols and HL7 FHIR interoperability standards constrains deployment velocity for integrated practice-management suites.
- Legacy on-premises sunk costs:Perpetual-license investments in server-based imaging archives create switching friction that delays SaaS migration timelines by two to four years for established clinics.
Strategic Opportunities
- Spain and Italy dental networks:Lower cloud penetration rates in Mediterranean markets present first-mover expansion potential for vendors with proven German BSI IT-Grundschutz certification pathways.
- Teledentistry platform convergence:Remote consultation tools integrated with intraoral scanner data streams are opening preventive care revenue models outside traditional clinic footprints.
- EU AI Act compliance frameworks:Early alignment with high-risk AI system requirements for diagnostic applications is creating differentiation moats against slower-adapting competitors.
Industry Challenges
- Interoperability certification timelines:EMA guidance on Software as a Medical Device creates ambiguous validation pathways for AI imaging modules, extending product launch cycles.
- Multi-generational system integration:Dental practices operate hybrid environments spanning 1990s radiography hardware, 2010s practice-management databases, and 2020s cloud analytics tools, demanding costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dental Software Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,854.04 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Management, Billing Software, Imaging Software, Practice Management Deployment: Cloud-based, On-premises, Hybrid, Mobile Solutions End User: Dentists, Dental Clinics, Research Institutions, Hospitals Technology: Artificial Intelligence, Teledentistry, Electronic Health Records, 3D Printing |
| Companies Covered | KaVo Dental GmbH, Elite Computer Italia, Carestream Health Inc, Open Dental, Dentrix, Dentsply Sirona, PLANMECA OY, MediSoft, Henry Schein Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dental Software Market Shifts & Advancements
Workflow automation and diagnostic augmentation technologies are compressing the traditional separation between clinical decision-making and administrative operations in European dental settings.
Intraoral scanning hardware paired with chairside CAD/CAM design software is fragmenting the conventional laboratory outsourcing model. Multi-chair clinics in Germany and the Netherlands are deploying these systems to deliver same-day crown and veneer procedures, compressing treatment timelines from two weeks to under three hours. This convergence is redistributing value capture from dental technicians toward practices with capital deployment capacity for integrated milling units.
MDR Article 10 clinical evaluation requirements for software with diagnostic claims are forcing vendors to maintain prospective clinical evidence portfolios. Manufacturers targeting pan-European distribution must now budget for notified body engagement and post-market surveillance infrastructure that exceeds pre-2021 regulatory burdens. French dental AI developers are responding by prioritizing Class IIa certification pathways before commercial launch.
Subscription pricing for imaging analytics is displacing perpetual-license procurement in Nordic dental chains. Copenhagen and Stockholm-based practice groups are unbundling hardware acquisition from software access, treating diagnostic algorithms as operational expenses rather than capital investments. This preference shift favors vendors with modular API architectures that permit feature-tier experimentation without full-platform commitments.
Europe Dental Software Market Segmentation
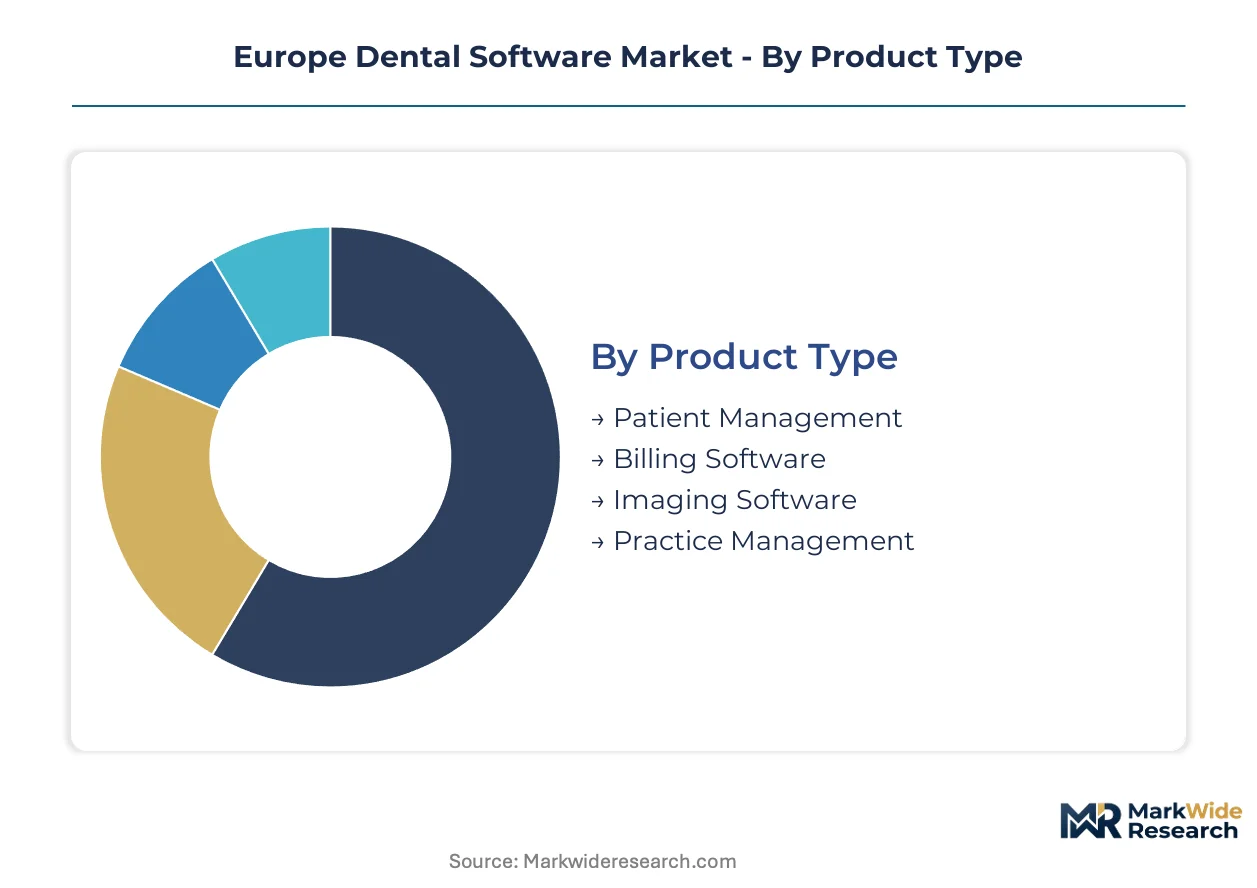
Software procurement patterns across European dental markets diverge sharply by practice scale and regulatory environment. Vendors must calibrate feature depth, deployment architecture, and compliance packaging to capture margin pools concentrated in multi-site clinic networks and AI-augmented diagnostic workflows.
Product Type:
Margin pools concentrate in imaging and practice management suites that command premium pricing through regulatory certification and workflow integration depth.
- Practice Management:Comprehensive platforms orchestrate scheduling, inventory, and regulatory reporting for multi-chair clinics. German dental chains in Munich and Hamburg prioritize BSI IT-Grundschutz certified systems that streamline cross-site patient transfers under GDPR frameworks.
- Imaging Software:DICOM-compliant diagnostic tools with AI-powered radiographic analysis embed directly into treatment planning workflows. French clinics pursuing HDS certification drive demand for cloud-native architectures that consolidate panoramic and CBCT data across metropolitan networks.
- Patient Management:Core demographic and medical history tracking modules form the foundational layer of clinic IT infrastructure.
- Billing Software:Claims processing and insurance reconciliation tools tailored to national reimbursement schemes in Benelux markets.
The dominant share belongs to Practice Management, while Imaging Software is closing the gap fastest through diagnostic AI integration.
Deployment:
Cloud economics are redistributing competitive advantage from capital-rich enterprise buyers toward workflow integration specialists serving independent practices.
- Cloud-based:Subscription models eliminate server maintenance burdens while enabling automatic regulatory updates. Nordic dental groups in Copenhagen and Stockholm treat diagnostic analytics as operational expenses, favoring vendors with modular API architectures for feature-tier experimentation.
- Hybrid:Mixed environments preserve on-premises imaging archives while migrating administrative functions to hosted platforms. German mid-market clinics leverage this architecture to satisfy data-residency requirements without full infrastructure replacement.
- On-premises:Legacy server installations retain presence in established practices with sunk perpetual-license investments.
- Mobile Solutions:Chairside tablet applications for intraoral scanner integration and patient education.
Cloud-based deployment commands the largest addressable base, though Hybrid configurations are climbing the fastest as transitional architectures for compliance-sensitive markets.
End User:
Procurement authority concentrates in dental clinic networks with centralized IT governance and cross-border standardization mandates.
- Dental Clinics:Multi-site networks across France and Germany consolidate purchasing power through standardized cloud platforms. These organizations demand CE-marked diagnostic modules and GDPR-compliant data architectures that support inter-clinic patient mobility.
- Dentists:Independent practitioners in Spain and Italy represent fragmented demand with price sensitivity and limited IT support capacity.
- Hospitals:Academic medical centers integrating dental services into broader health system EMR infrastructures.
- Research Institutions:Universities and clinical trial organizations requiring specialized data collection and analysis tools.
Dental Clinics hold the dominant procurement volume, while Hospitals are gaining share fastest through health system consolidation and enterprise EMR integration requirements.
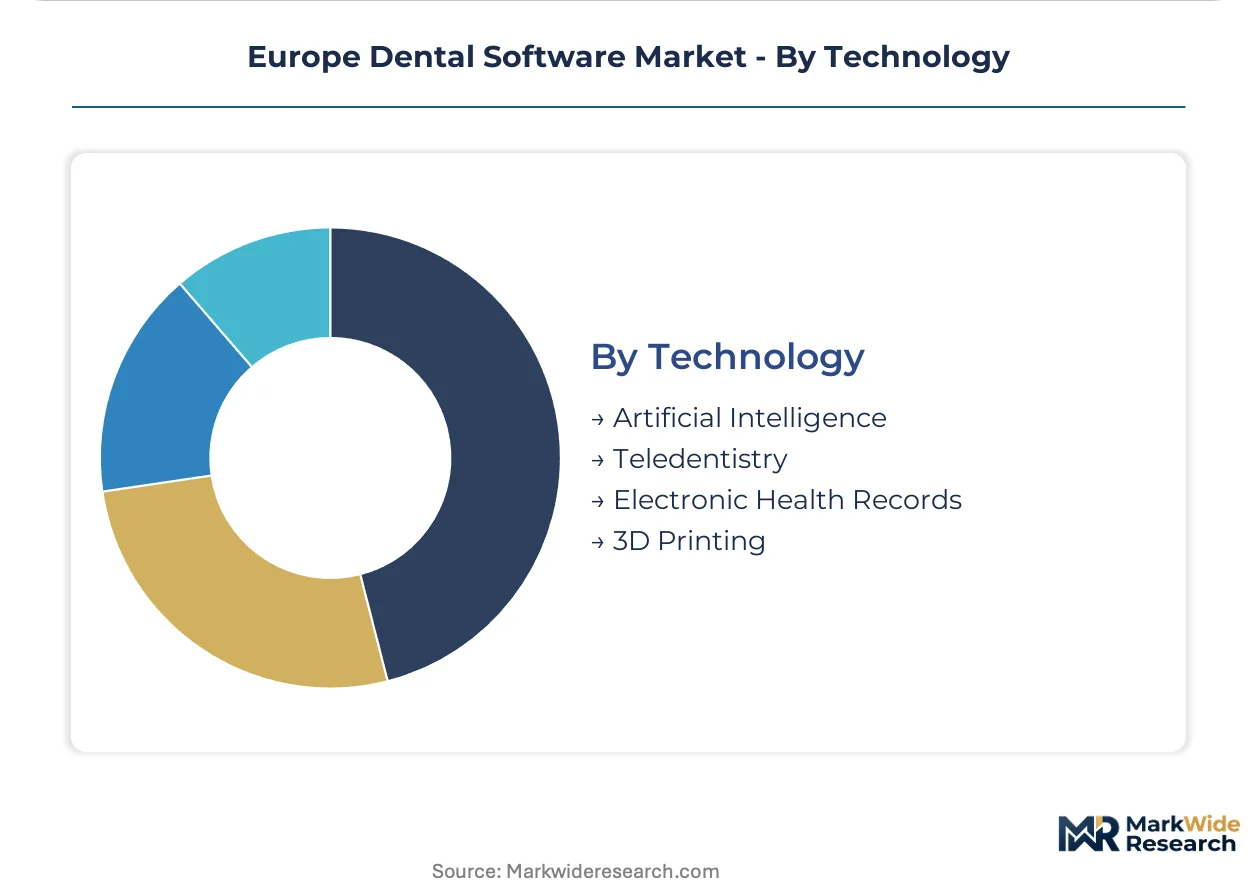
Technology:
AI and teledentistry platforms are capturing margin expansion through diagnostic augmentation and service model innovation beyond traditional clinic footprints.
- Artificial Intelligence:Machine learning algorithms for caries detection and periodontal assessment embed into routine hygiene appointments. French developers prioritize Class IIa MDR certification pathways before commercial launch, creating differentiation moats against uncertified competitors.
- Teledentistry:Remote consultation platforms integrated with intraoral scanner data streams enable preventive care delivery outside conventional clinic settings. Mediterranean markets with lower specialist density present first-mover expansion opportunities.
- Electronic Health Records:HL7 FHIR interoperability standards enabling cross-border data portability within the European Economic Area.
- 3D Printing:Chairside CAD/CAM design software paired with milling units for same-day crown and veneer procedures.
Artificial Intelligence claims the steepest expansion trajectory, while Teledentistry is gaining share fastest through preventive care model innovation and geographic access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental clinics consume software through centralized procurement frameworks that bundle compliance certification with workflow integration, whereas French networks prioritize modular cloud migration paths that separate administrative from diagnostic system upgrades.
Germany
Dental chains in Munich and Hamburg drive demand for BSI IT-Grundschutz certified platforms that enable cross-site patient transfers. The country's Federal Office for Information Security mandates baseline cybersecurity controls for health data processing. Berlin-Brandenburg hosts emerging teledentistry clusters where practices pilot remote consultation modules ahead of national reimbursement scheme updates.
France
Metropolitan networks in Paris and Lyon consolidate multi-site operations through HDS-certified cloud architectures. ANSM and CNIL jointly oversee health data hosting standards that remove migration friction for patient management platforms. The Île-de-France region concentrates AI imaging development studios pursuing Class IIa MDR certification before commercial deployment.
United Kingdom
NHS dental contracts create procurement concentration toward integrated practice management suites with standardized reporting formats. The UK Medicines and Healthcare products Regulatory Agency applies CE marking recognition with post-Brexit divergence monitoring. London and Southeast England dental groups lead SaaS adoption rates through private-equity backed clinic consolidation.
Italy
Independent practitioners in Lombardy and Emilia-Romagna represent fragmented demand with limited IT support capacity. The Italian Ministry of Health enforces GDPR-aligned data residency requirements through regional health authority oversight. Milan-based dental technology distributors are expanding software-as-a-service portfolios to capture latent cloud migration demand.
Spain
Lower cloud penetration rates in Madrid and Catalonia present first-mover expansion opportunities for certified vendors. The Spanish Agency for Medicines and Health Products maintains MDR implementation timelines that lag Northern European adoption curves. Barcelona dental networks are piloting hybrid deployment models that preserve on-premises imaging archives while migrating administrative functions.
Europe Dental Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on regulatory certification speed and workflow depth. The upper tier commands pricing power through bundled hardware-software contracts and established CE-marking capabilities. Mid-market specialists differentiate through German regulatory workflow calibration and Nordic distribution control. Competitive moves concentrate on M&A for cloud-native capability acquisition and strategic partnerships for AI imaging module integration.
Among Germany-based specialists, KaVo Dental GmbH exemplifies the regulatory-calibrated archetype with practice-management tools aligned to BSI certification pathways. Dentsply Sirona occupies a position in the integrated hardware-software tier, leveraging imaging equipment installed bases to anchor software contract renewals. Henry Schein Inc represents the distribution-controlled archetype, with Nordic and Benelux market presence that constrains competitor channel access.
| Leading Market Players |
|---|
| KaVo Dental GmbH |
| Elite Computer Italia |
| Carestream Health Inc |
| Open Dental |
| Dentrix |
| Dentsply Sirona |
| PLANMECA OY |
| MediSoft |
| Henry Schein Inc |
| Others |
Supply & Pricing Matrix
Multi-tenant cloud infrastructure economics in Germany and France compress per-seat software delivery costs below on-premises alternatives, concentrating pricing power among vendors with certified data-center footprints while establishing subscription floors that independent developers struggle to undercut. This scale dynamic shapes both procurement negotiations and vendor consolidation patterns across European dental networks.
Pricing Analysis
After-sales revenue from extended support contracts and regulatory compliance updates drives lifetime customer value beyond initial SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by CE-marking requirements and cross-border data portability needs. Pricing pressure stems from Nordic dental chains unbundling hardware from software procurement, treating diagnostic analytics as operational expenses. Independent practitioners in Spain and Italy exhibit highest price sensitivity, while German multi-site networks prioritize certification depth over cost minimization.
Supply Chain Analysis
Inbound logistics costs for intraoral scanner hardware through Rotterdam and Hamburg ports influence total cost of ownership calculations for integrated chairside systems. Software development concentrates in Germany, France, and the Netherlands, with cloud hosting infrastructure drawing from Irish and Swedish data-center clusters. Supply chain risk centers on single-source vulnerability for AI imaging modules awaiting MDR notified body clearance. Distribution runs through specialized dental technology distributors in Nordic and Benelux markets, with direct vendor relationships dominating German enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe dental software is approaching a platform-economics inflection where HL7 FHIR interoperability standards enable third-party diagnostic module integration, transforming standalone practice-management systems into extensible healthcare IT hubs.
For Market Incumbents: Compound installed-base advantages through API ecosystem development that locks in multi-site clinic networks. Threat from cloud-native entrants with modular architectures demands defensive certification investments in Class IIa MDR pathways. Prioritize backward integration into intraoral scanner hardware to anchor software contract renewals. For New Entrants and Emerging Players: AI-powered radiographic analysis workflows represent the most penetrable service layer where incumbents under-serve independent practitioners. Mediterranean markets with lower cloud penetration offer geographic white-space, while teledentistry platforms open preventive care revenue models. Pursue partnership-based go-to-market strategies with established Nordic distributors to bypass channel control barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with proven CE-marking capabilities and modular cloud architectures over legacy on-premises specialists. Long-term viability hinges on EU AI Act compliance infrastructure for diagnostic applications. Watch MDR notified body queue lengths as inflection indicator for competitive certification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR interoperability enables third-party diagnostic module ecosystems across German clinic networks. |
| CE Marking Pathway | Class IIa MDR certification unlocks diagnostic imaging claims in France and accelerates Nordic procurement cycles. |
| Strategic Partnership | Intraoral scanner manufacturer alliances anchor software distribution in Benelux and Mediterranean markets. |
| Acquisition of Specialist Firm | Cloud-native teledentistry capabilities fill portfolio gaps for incumbent hardware-software bundlers. |
| Geographic Expansion | BSI IT-Grundschutz certification pathways ease entry into Spanish and Italian dental networks. |
Research Methodology
The analysis maps practice-management platforms, imaging software suites, and AI diagnostic modules, each validated through dental clinic IT directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies. Primary interviews with these stakeholders combine with secondary validation against EMA guidance documents, ANSM certification registries, BSI audit reports, and hospital procurement databases. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates.
Consistency checks against external benchmarks validate projection outputs across the modeling period. Segmentation dimensions include deployment architecture, practice scale, regulatory certification tier, and regional adoption pattern. CAGRs derive from patient procedure volume trajectories, cloud migration velocity indicators, and MDR implementation timeline assumptions specific to dental software classification.
Forecasts assume regulatory continuity in EU MDR and GDPR enforcement regimes; material policy shifts would require re-modeling. Specific risks include EMA guidance revisions for Software as a Medical Device and national health data authority interpretations of cross-border portability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Healthcare IT Outsourcing Market