
 Healthcare Contact Center Solution Market | 2026-2036
Healthcare Contact Center Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Contact Center Solution Market Foresight
Subscription-based financing and managed service arrangements are reconfiguring how healthcare organizations procure contact center infrastructure without heavy capital outlay. Genesys leverages its cloud-native architecture to capture multi-year contracts from large hospital networks. NICE Systems anchors its position through workforce optimization tools that reduce agent attrition in high-stress medical call environments. Cisco Systems competes by bundling contact center software with its installed base of healthcare networking equipment.
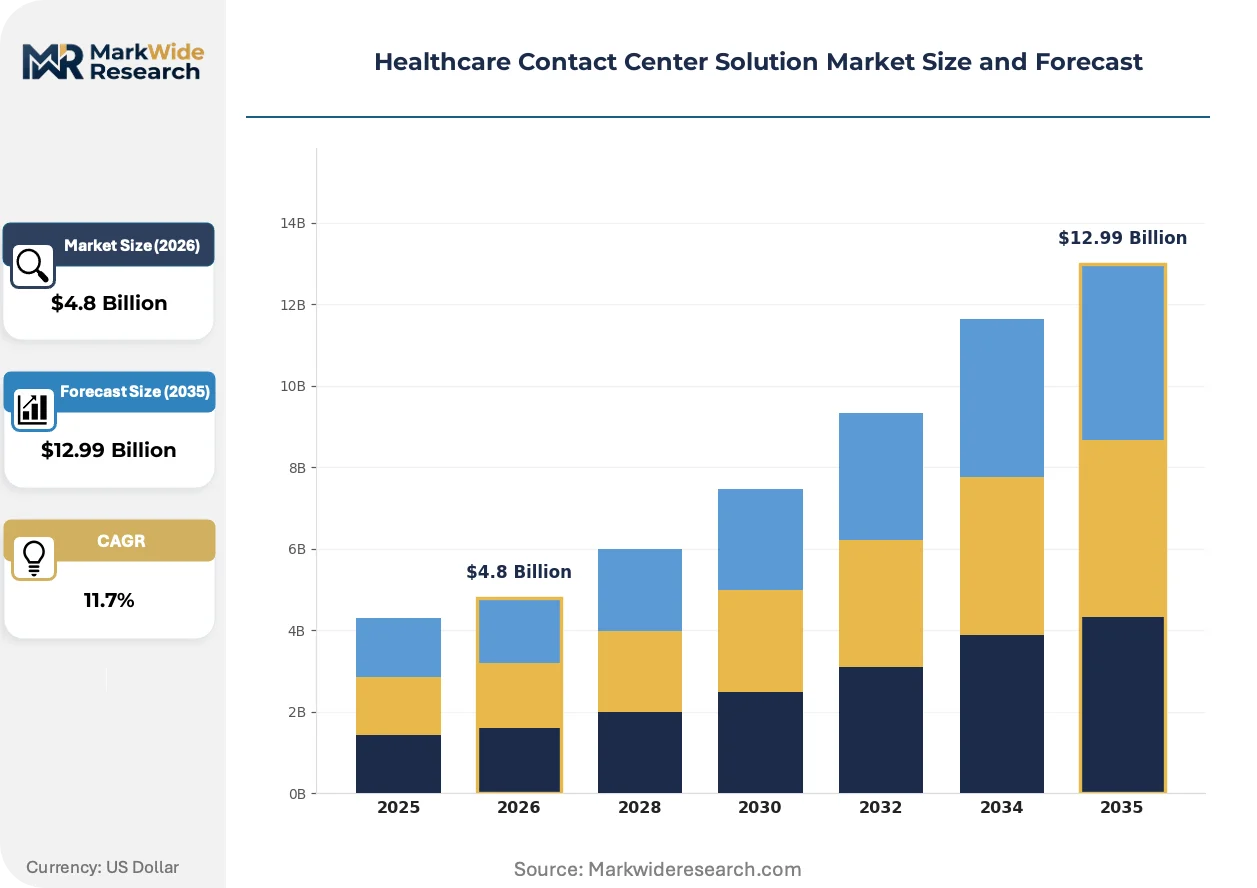
A healthcare contact center solution integrates telephony, digital channels, and patient data systems to route, manage, and analyze interactions between medical organizations and consumers, typically operating with sub-20-second average speed of answer targets and 99.99% uptime requirements to maintain care continuity. Cloud-based solutions now lead deployment preference as health systems retire legacy PBX infrastructure, while AI-powered systems represent the fastest-expanding margin pool through automated triage and symptom checking. Among end users, healthcare providers consume the largest solution volume, though telehealth services are generating the steepest adoption curve as virtual visit platforms require integrated scheduling and callback orchestration.
FDA oversight of software-as-a-medical-device intersects with HIPAA privacy mandates to shape product development roadmaps, particularly for AI-driven symptom assessment tools that must demonstrate clinical validation before deployment. State-level Medicaid agencies impose additional interoperability requirements that filter vendor eligibility for public program contracts. Stakeholders must monitor how CMS reimbursement policy for remote patient monitoring reshapes call volume patterns and channel mix requirements across their installed bases.
Market Dynamics
Cloud migration is compressing deployment timelines for healthcare contact center infrastructure as hospital systems retire on-premise PBX estates and reallocate capital toward AI-augmented patient engagement platforms.
Growth Catalysts
- HIPAA-aligned data governance mandates:Federal privacy requirements compel platform replacements that embed encryption-at-rest and audit logging, accelerating contract awards to compliant vendors.
- Telehealth volume expansion:Virtual visit platforms require integrated scheduling, callback orchestration, and post-visit survey automation, pulling contact center capacity into ambulatory workflows.
- Medicaid interoperability rules:State agencies impose real-time eligibility verification standards that filter vendor eligibility for public program contracts, concentrating demand among integrated suite providers.
Market Restraints
- AI validation bottlenecks:FDA software-as-a-medical-device pathways delay deployment of symptom-checking algorithms, extending product development cycles.
- Agent attrition economics:High-stress medical call environments drive workforce turnover above 45% annually, inflating recruitment and training costs for operators.
- Legacy integration debt:Proprietary EHR interfaces require custom middleware development, constraining vendor margins on initial deployments.
Strategic Opportunities
- Rural health network penetration:Critical Access Hospitals in underserved counties lack dedicated IT staff, creating managed service openings for remotely administered cloud platforms.
- Remote patient monitoring convergence:CMS reimbursement expansion for RPM devices is generating callback volume for biometric alert triage, requiring new workflow automation.
- Voice biometric authentication:Speaker recognition technology reduces verification friction for elderly populations, differentiating platforms in Medicare Advantage contract competitions.
Industry Challenges
- Clinical informatics staffing gaps:Health systems struggle to hire personnel who bridge nursing workflows with AI training data curation, slowing model refinement.
- Multi-cloud orchestration complexity:Hybrid deployments spanning AWS, Azure, and Google Cloud require specialized Site Reliability Engineering capabilities scarce in healthcare IT labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Contact Center Solution Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, AI-Powered Systems End User: Healthcare Providers, Insurance Companies, Telehealth Services, Specialty Clinics Technology: Voice over IP, Interactive Voice Response, Chatbot Integration, Predictive Dialing Service Type: Outbound Services, Inbound Services, Technical Support, Customer Service |
| Companies Covered | Genesys, NICE Systems, Avaya, Cisco Systems, IBM, RingCentral, 8x8, Nextiva, Talkdesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Contact Center Solution Market Shifts & Advancements
Intelligent automation is reconfiguring how patient interactions are triaged, routed, and resolved, compressing average handle times while elevating clinical escalation precision.
Conversational AI engines are virtualizing tier-one inquiry resolution across appointment scheduling, prescription refill requests, and billing clarification workflows. Large hospital networks in Texas and Florida are deploying these systems at scale, replacing interactive voice response trees with natural language understanding. The technology is virtualizing first-touch patient engagement, displacing live agent hours toward complex clinical consultations and care coordination tasks.
EU AI Act risk classification requirements are mandating clinical validation documentation for symptom assessment algorithms marketed in member states. Vendors must demonstrate conformity with CE marking under Medical Device Regulation annexes before commercial deployment. German and French hospital procurement committees now require algorithmic impact assessments as standard tender evaluation criteria, filtering non-compliant suppliers from shortlists.
Subscription-based consumption models are displacing perpetual license purchases as health system CFOs prioritize operational expenditure predictability. Multi-year managed service arrangements bundle platform access, agent staffing, and outcome-based performance guarantees, transferring technology risk to vendors. This shift concentrates contract value among integrated service providers in the United States, where payer-provider network complexity demands specialized operational expertise.
Healthcare Contact Center Solution Market Segmentation
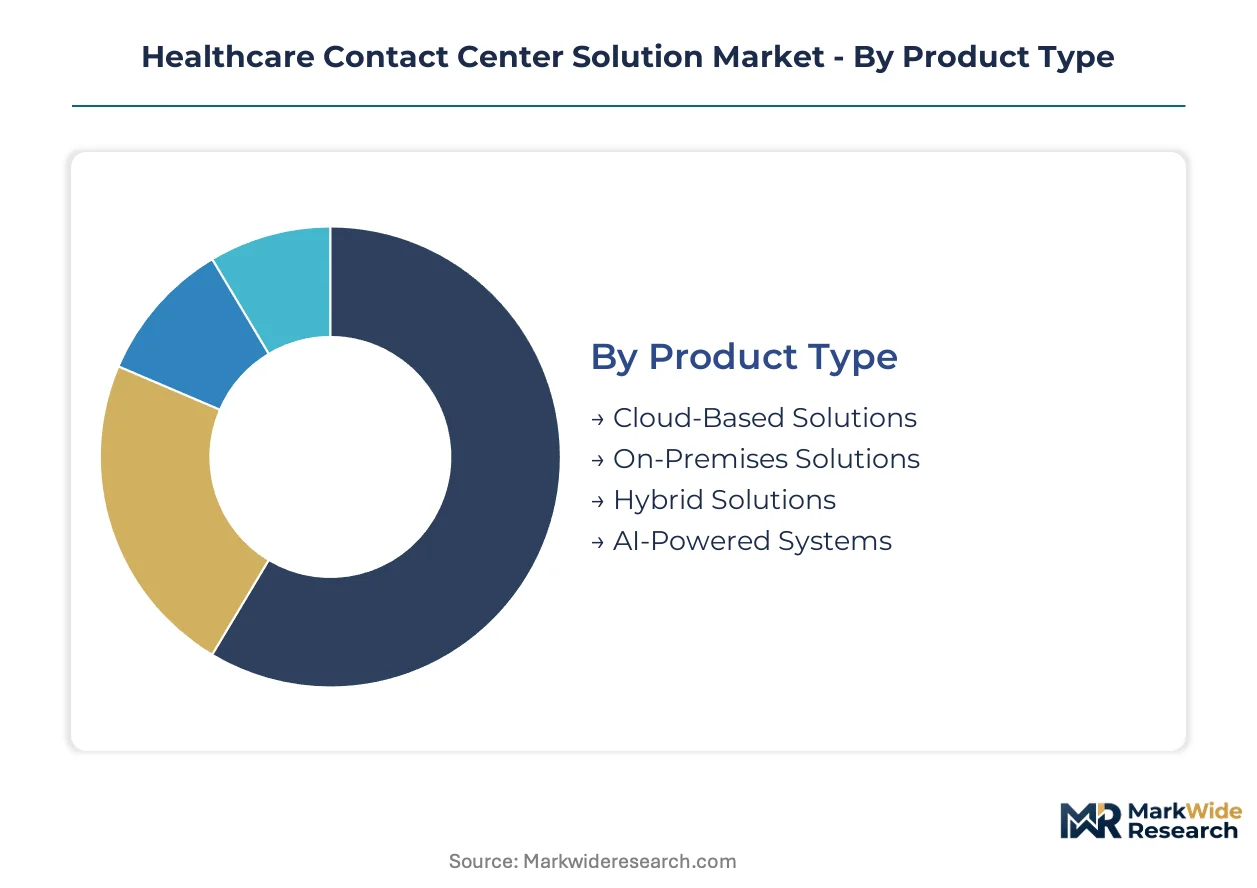
Healthcare contact center solutions segment across deployment models, user categories, and interaction technologies that determine compliance posture and integration complexity. Each dimension carries distinct procurement criteria tied to HIPAA governance, EHR connectivity, and care continuity requirements.
Product Type:
Mature on-premise estates coexist with emerging cloud-native architectures as health systems navigate migration timelines and capital allocation priorities.
- Cloud-Based Solutions:Multi-tenant platforms deliver elastic capacity scaling across patient volume spikes without data center capital expenditure. Large hospital networks in Texas and Florida favor these deployments for disaster recovery resilience and rapid telehealth integration.
- On-Premises Solutions:Legacy PBX infrastructure persists in security-sensitive environments requiring air-gapped patient data storage. Critical Access Hospitals in rural counties maintain these systems where broadband unreliability threatens cloud uptime.
- Hybrid Solutions:Split architectures preserve sensitive records on-site while routing routine inquiries through cloud orchestration layers.
- AI-Powered Systems:Natural language processing engines automate triage workflows and symptom assessment prior to clinical escalation.
Cloud-Based Solutions handle the majority of throughput; AI-Powered Systems are expanding most quickly on share as FDA validation pathways mature.
End User:
Customer type segmentation reveals divergent interaction volumes, with integrated payer-provider networks generating the most complex routing requirements.
- Healthcare Providers:Hospital systems and health networks manage appointment scheduling, discharge follow-up, and billing inquiry workflows at enterprise scale. These organizations drive demand for workforce optimization tools that reduce agent attrition in high-stress medical call environments.
- Telehealth Services:Virtual visit platforms require integrated callback orchestration and post-visit survey automation. Ambulatory workflow integration pulls contact center capacity into remote care delivery models.
- Insurance Companies:Payer operations concentrate on eligibility verification and claims status inquiries with strict SLA requirements.
- Specialty Clinics:Orthopedic, cardiology, and oncology practices deploy targeted solutions for procedure scheduling and pre-authorization support.
Healthcare Providers consume the largest solution volume; Telehealth Services are gaining share fastest as CMS reimbursement policy reshapes call volume patterns.
Technology:
Channel mix segmentation tracks the shift from voice-centric infrastructure toward multimodal patient engagement platforms.
- Interactive Voice Response:Touch-tone and speech-recognition menus route callers through self-service pathways for prescription refills and appointment management. Legacy IVR estates dominate installed bases but face displacement by conversational AI.
- Chatbot Integration:Text-based virtual assistants handle asynchronous patient inquiries across web portals and mobile applications. These systems reduce live agent burden for routine administrative requests.
- Voice over IP:Packet-switched telephony enables cost-efficient call transport and centralized agent pooling across distributed care sites.
- Predictive Dialing:Algorithmic outbound campaign management supports population health outreach and appointment reminder programs.
Interactive Voice Response retains the largest installed footprint; Chatbot Integration is climbing the fastest as digital-native patient demographics expand.
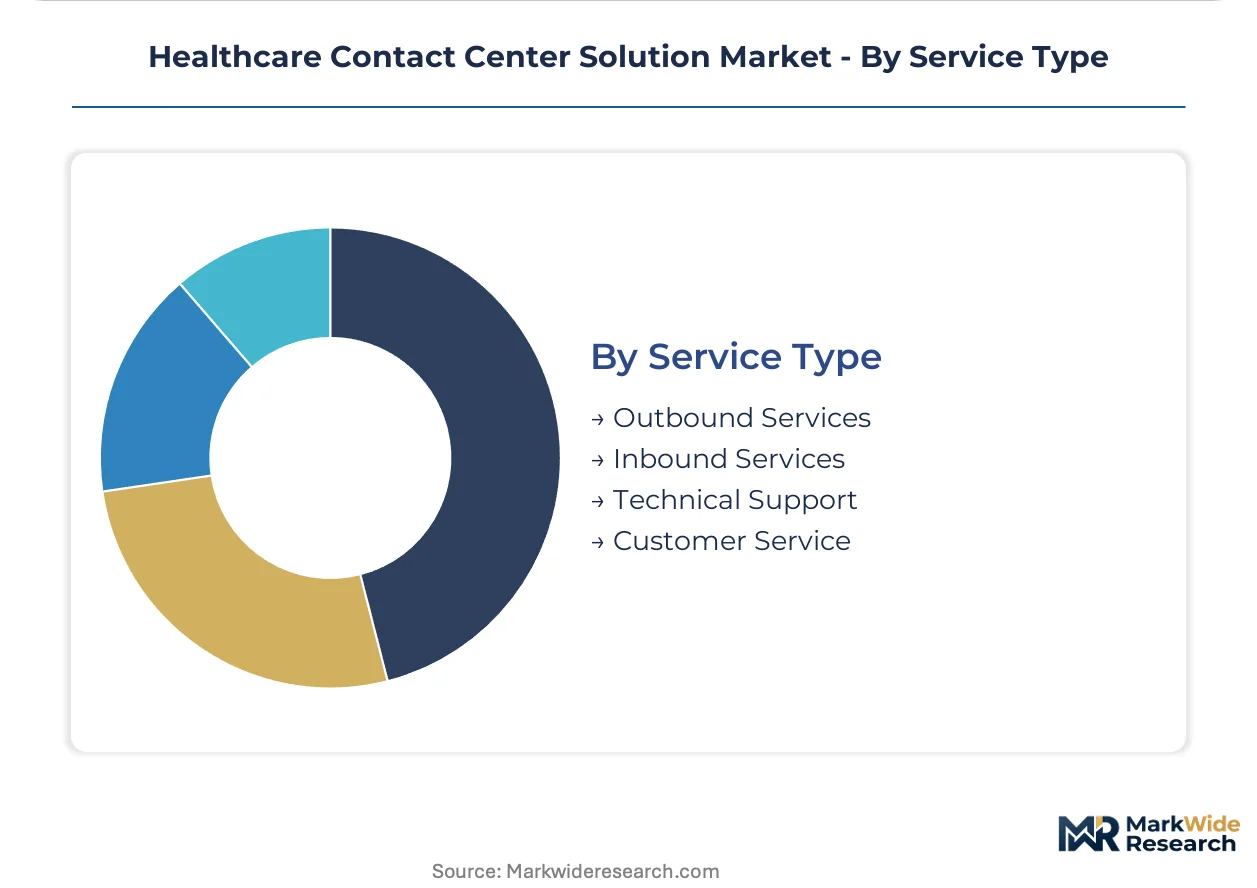
Service Type:
Directionality segmentation distinguishes inbound care continuity functions from proactive population health engagement workflows.
- Inbound Services:Patient-initiated contact handling spans scheduling, billing clarification, and clinical triage with sub-20-second answer targets. These functions demand 99.99% uptime guarantees to preserve care access.
- Outbound Services:Proactive outreach campaigns address appointment adherence, medication compliance, and post-discharge follow-up. CMS reimbursement expansion for remote patient monitoring is generating callback volume for biometric alert triage.
- Technical Support:Agent-facing systems administration and telephony troubleshooting maintain platform availability.
- Customer Service:General inquiry resolution handles non-clinical administrative requests across multiple channels.
Inbound Services manage the highest interaction volumes; Outbound Services are expanding most rapidly as value-based care contracts intensify population health accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial services trade surplus in healthcare contact center solutions, exporting cloud-native platforms and managed service expertise while importing limited specialized workforce optimization components from European vendors. Germany and the United Kingdom represent net importers of enterprise-grade infrastructure, sourcing multi-tenant architectures from North American providers. Japan maintains near-autonomous supply through domestic system integrators, though AI training data pipelines increasingly cross borders.
United States
Integrated payer-provider networks in Texas and Florida drive the steepest adoption curves for AI-powered triage and callback orchestration. HIPAA privacy mandates and FDA software-as-a-medical-device pathways shape vendor eligibility for federal contracts. Hospital networks across the Southeast and Southwest are retiring legacy PBX estates fastest, consolidating procurement among cloud-native platform providers with managed service capabilities.
Germany
University hospital systems in Bavaria and Baden-Württemberg demand conversational AI with CE marking under Medical Device Regulation annexes. The EU AI Act risk classification requirements filter non-compliant symptom assessment algorithms from procurement shortlists. Berlin-based health insurers are piloting voice biometric authentication for elderly Medicare-equivalent populations, creating reference architectures for Central European deployment.
United Kingdom
NHS Integrated Care Systems in England are consolidating contact center procurement across regional footprints, favoring vendors with ISO 27001 and NHS Digital compliance. GDPR and UK GDPR alignment requirements complicate data residency for cloud deployments. London health technology clusters are developing hybrid architectures that preserve sensitive records on-premise while routing routine inquiries through cloud orchestration layers.
Japan
Metropolitan hospital networks in Tokyo and Osaka are deploying AI-augmented patient engagement platforms to address aging demographics and nursing workforce shortages. PMDA consultation pathways guide clinical validation for symptom-checking algorithms before commercial deployment. Nagoya-based medical device manufacturers are integrating contact center modules into remote patient monitoring systems for export to Southeast Asian markets.
India
Corporate hospital chains in Maharashtra and Karnataka are adopting cloud-based solutions for medical tourism coordination and international patient scheduling. CDSCO and BIS standards for software-as-a-medical-device remain under development, creating regulatory uncertainty for AI-driven triage tools. Hyderabad and Bengaluru technology parks host development centers for global healthcare contact center vendors seeking cost-efficient engineering talent.
Healthcare Contact Center Solution Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with workforce optimization, voice biometrics, and EHR middleware modules. The vendor base clusters around three strategic archetypes: cloud-native suite providers with managed service wraps, legacy telephony incumbents defending installed bases through hybrid migration programs, and vertical specialists targeting telehealth-specific workflows. Dominant competitive moves include multi-year subscription contract captures with outcome-based performance guarantees and strategic partnerships with EHR vendors to reduce integration friction.
Within the cloud-native suite tier, Genesys and NICE Systems exemplify platform consolidation strategies, while Cisco Systems anchors the network-integrated positioning. These three entities represent divergent architectural bets: multi-tenant elasticity versus workforce optimization depth versus infrastructure bundling. Each occupies a distinct procurement consideration set based on health system legacy estate composition and capital expenditure preferences.
| Leading Market Players |
|---|
| Genesys |
| NICE Systems |
| Avaya |
| Cisco Systems |
| IBM |
| RingCentral |
| 8x8 |
| Nextiva |
| Talkdesk |
| Others |
Supply & Pricing Matrix
FDA software-as-a-medical-device validation bottlenecks determine both pricing tier spreads and supply chain shape, compressing margins on AI-powered triage modules while forcing vendors toward subscription-based consumption models that transfer clinical risk to platform providers.
Pricing Analysis
Hospital system CFOs anchor pricing structures around subscription-based SaaS tiers with outcome-based performance guarantees. Three-tier pricing stratifies across enterprise, mid-market, and critical access hospital levels, with differentiation driven by HIPAA compliance certification depth and EHR integration complexity. Cost compression in the mid-market tier intensifies because Genesys and NICE Systems compete aggressively for multi-year managed service contracts. Critical Access Hospitals in rural counties exhibit the highest price sensitivity due to constrained operating budgets, while integrated payer-provider networks in Texas and Florida demonstrate the least sensitivity given their scale-driven procurement advantages.
Supply Chain Analysis
Contract manufacturing for cloud infrastructure concentrates with AWS, Microsoft Azure, and Google Cloud Platform holding dominant capacity positions. Platform development draws from engineering talent pools in India, the United States, and Ireland, with AI training data curation resting on clinical informatics staffing in academic medical centers. Single-source vulnerability emerges from hyperscaler concentration for compute capacity, particularly for real-time symptom assessment workloads requiring sub-20-second latency. Distribution runs through direct enterprise sales teams and EHR vendor partnership channels, with Epic and Cerner integration partnerships filtering vendor eligibility for hospital system procurement shortlists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare contact center solutions sit at a platform-economics inflection where EHR-native workflow integration determines competitive viability, with Epic's App Orchard and Cerner's Code interoperability frameworks reshaping vendor selection criteria across hospital procurement committees.
For Market Incumbents: Entrench position by deepening EHR middleware capabilities that reduce custom integration friction for legacy PBX migrations. Acquire clinical informatics staffing capacity in nursing workflow domains to accelerate AI model refinement for symptom-checking algorithms. Defensive consolidation must address emerging cloud-native entrants targeting telehealth-specific callback orchestration workflows. For New Entrants and Emerging Players: Rural Critical Access Hospitals in the Southeastern United States represent the most penetrable entry point given their managed service gaps and limited IT staffing. Voice biometric authentication for Medicare Advantage elderly populations offers a second white-space target with differentiated procurement evaluation criteria. A go-to-market angle anchored through state Medicaid agency interoperability compliance bypasses incumbent lock-in at integrated payer-provider networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform providers with managed service wraps and EHR partnership density. Long-term viability across the next decade hinges on FDA software-as-a-medical-device pathway navigation for AI-driven triage tools. The signal to watch is CMS reimbursement policy expansion for remote patient monitoring, which would inflect callback volume requirements and channel mix specifications across installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA-Aligned Cloud Migration | Federal privacy mandates compel platform replacements embedding encryption-at-rest and audit logging capabilities. |
| AI Triage Clinical Validation | FDA software-as-a-medical-device pathways delay deployment but create regulatory moats for compliant vendors. |
| EHR Integration Partnership | Epic and Cerner middleware partnerships reduce custom development friction and filter procurement shortlists. |
| Managed Service Expansion | Multi-year subscription arrangements transfer technology risk to vendors while capturing hospital CFO preference. |
| Telehealth Workflow Orchestration | Virtual visit platforms require integrated scheduling and callback automation, pulling contact center capacity into ambulatory care. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, GPO contracts, CMS Medicare reimbursement filings, and FDA software-as-a-medical-device submission records. Primary interviews engaged contact center operations directors, hospital purchasing committee members, biomedical informatics leads, and EHR integration specialists across health systems in Texas, Florida, Germany, and the United Kingdom. Bottom-up triangulation of vendor contract values and top-down reconciliation against health system IT expenditure disclosures validated market sizing across deployment models and end-user categories.
Forecast inputs incorporate elastic capacity scaling assumptions, telehealth volume expansion trajectories, and Medicaid interoperability rule implementation timelines across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user organization type, interaction channel technology, and service directionality. CAGRs derive from compound growth modeling of hospital system cloud migration spend and AI-augmented patient engagement platform adoption curves, with sensitivity analysis around FDA validation pathway duration and agent attrition economics.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, CMS reimbursement policy, or hyperscaler pricing would shift the trajectory. Forecasts reflect assumptions about HIPAA enforcement continuity and EHR vendor partnership stability. Quarterly review of FDA software-as-a-medical-device submission approvals and state Medicaid agency procurement awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Aged Care Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
US Urgent Care Center Software Market