
 Healthcare Credentialing Software Market | 2026-2036
Healthcare Credentialing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Credentialing Software Market Outlook
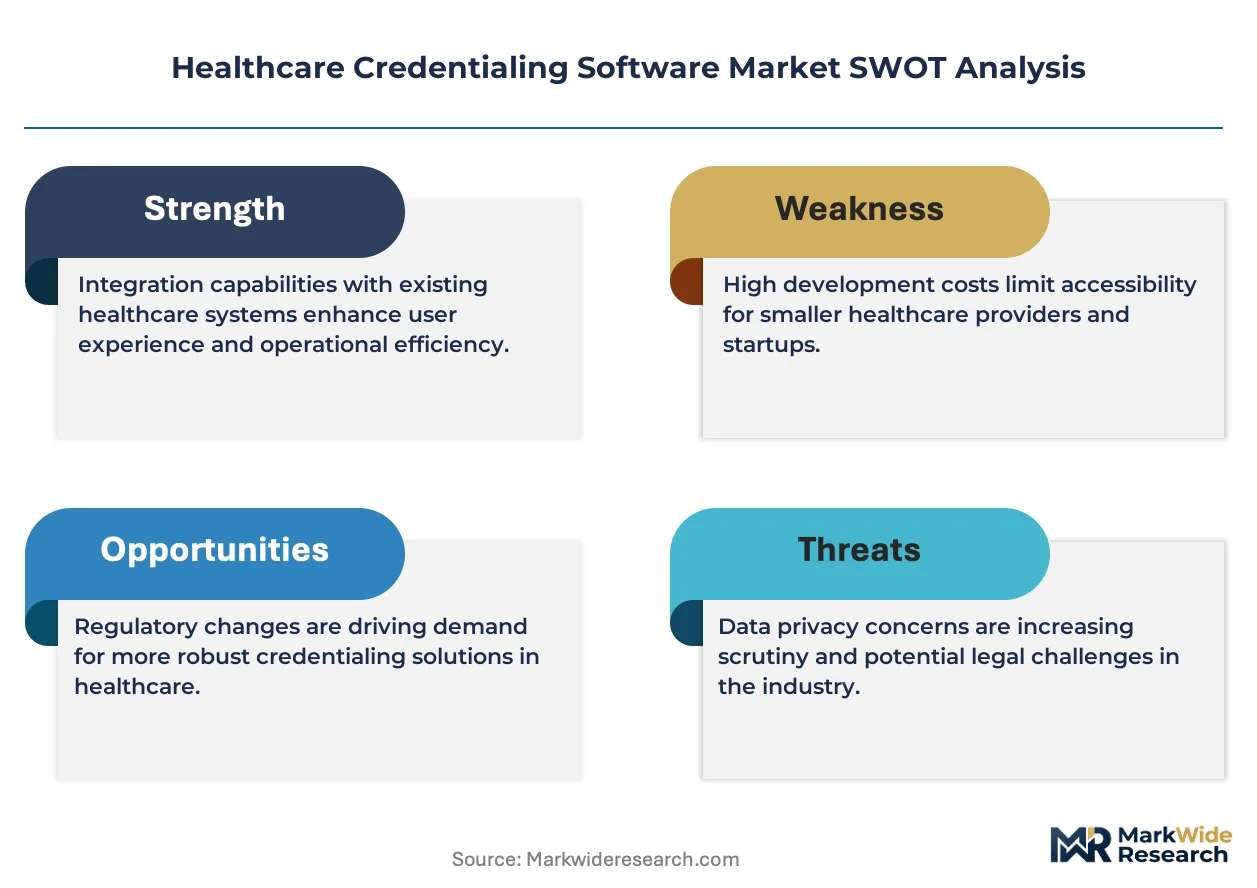
NCQA certification timelines are collapsing from eighteen months to under ninety days for health systems deploying automated platforms. symplr leverages its vertical integration across workforce management to sustain dominant positioning in enterprise hospital deployments. Verisys anchors its competitive stance through proprietary data verification networks spanning federal and state credentialing sources. Medallion differentiates by specializing in modular API-first architecture that competes directly with legacy monolithic systems.
Healthcare credentialing software automates the verification, monitoring, and management of clinician qualifications, privileges, and compliance status through configurable workflow engines integrating primary source data feeds. Cloud-based deployment dominates structural margins as health systems abandon on-premise infrastructure, while provider enrollment solutions capture disproportionate value within the solution stack due to CMS reimbursement gatekeeping requirements. License verification modules are maturing fastest as regulatory complexity multiplies across interstate telehealth licensing compacts.
The US Centers for Medicare & Medicaid Services, The Joint Commission, and state medical boards collectively shape product roadmaps through escalating audit frequency and electronic submission mandates. HIPAA security rule enforcement by the Office for Civil Rights is forcing encryption and access-control investments across all deployment architectures. Stakeholders must monitor interstate licensure compact expansions and artificial intelligence governance frameworks to anticipate workflow automation requirements.
Market Dynamics
CMS provider enrollment verification mandates are compressing credentialing timelines from months to weeks, forcing health systems to abandon manual verification workflows for automated primary-source data integration.
Growth Catalysts
- Interstate Medical Licensure Compact:The Interstate Medical Licensure Compact reduces multi-state licensing friction for telehealth providers, expanding addressable demand for cross-jurisdictional credentialing automation.
- HIPAA Security Rule Enforcement:OCR audit frequency escalation compels encryption and access-control investments, accelerating cloud migration away from on-premise credentialing infrastructure.
- Hospital Network Consolidation:Mega-mergers among US health systems create enterprise-scale procurement of unified credentialing platforms across dispersed facility footprints.
Market Restraints
- Primary Source Data Fragmentation:State medical boards maintain non-standardized verification protocols, forcing vendors to build costly jurisdiction-specific API integrations.
- Cloud Infrastructure Concentration:AWS, Microsoft Azure, and Google Cloud dominate health system hosting, creating vendor lock-in risk for credentialing SaaS providers.
- Legacy System Entrenchment:Decades-old HRIS and privileging databases resist API connectivity, requiring expensive middleware development for data synchronization.
Strategic Opportunities
- Behavioral Health Credentialing Gap:Substance abuse counselors and mental health practitioners face patchwork state licensing, creating demand for specialized verification workflows.
- AI-Assisted Document Processing:Machine learning extraction of credentials from unstructured PDFs and scanned certificates reduces manual data entry labor by health system staff.
- Federated Identity Networks:Blockchain-verified credential wallets enable portable provider profiles across competing health systems without redundant reverification.
Industry Challenges
- Primary Source Verification Specialist Shortage:Health systems struggle to hire staff capable of navigating state board websites, DEA databases, and OIG exclusion lists with sufficient speed.
- Multi-System Integration Complexity:Credentialing platforms must synchronize with privileging committees, payer enrollment portals, and malpractice carriers simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Credentialing Software Market |
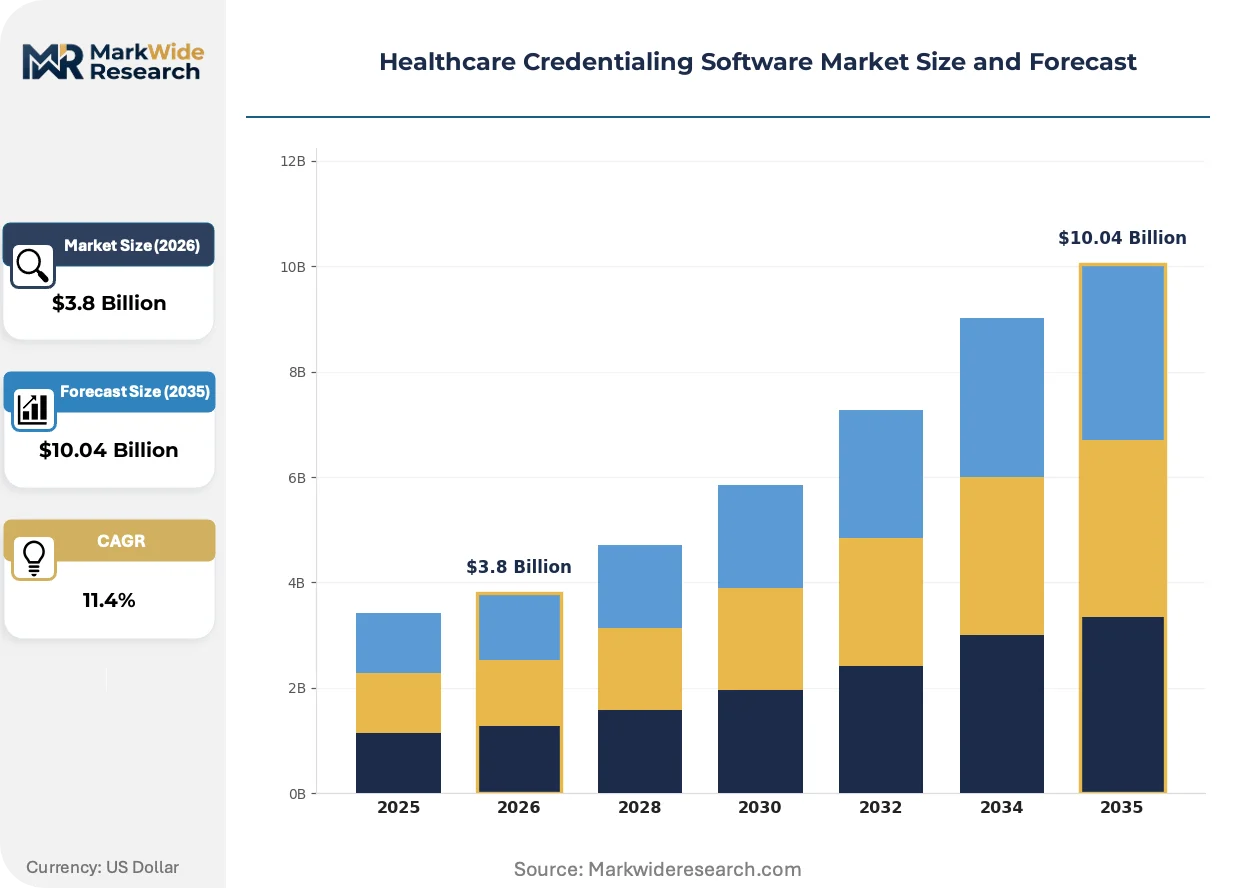
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile End User: Hospitals, Clinics, Health Systems, Credentialing Organizations Deployment: Public Cloud, Private Cloud, Community Cloud, Dedicated Servers Solution: Provider Enrollment, License Verification, Privileging Management, Compliance Tracking |
| Companies Covered | symplr, Verisys, OmniMD, Medallion, Medversant, CureMD, VerityStream, nCred, Atlas Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Credentialing Software Market Strategic Shifts
Workflow automation is collapsing the traditional separation between credentialing, privileging, and payer enrollment functions into unified provider data management architectures.
API-first modular credentialing platforms are fragmenting the monolithic software stack that dominated health system IT for two decades. Mid-sized hospitals now procure license verification, exclusion monitoring, and enrollment management as discrete microservices rather than integrated suites. This modularity enables faster deployment cycles and reduces vendor switching costs.
The Joint Commission's expanded focus on continuous professional practice evaluation is tightening privileging oversight requirements. Hospital medical staff offices must now document ongoing competence monitoring rather than periodic recredentialing alone. This shifts software requirements toward real-time performance data integration from quality registries and patient safety event systems.
Subscription pricing for credentialing software is displacing perpetual license models across US health systems. CFOs prefer operational expenditure classification for SaaS deployments amid capital budget constraints. This preference concentrates vendor revenue into annual recurring metrics, reshaping sales compensation and product roadmap prioritization toward retention features over new logo acquisition.
Healthcare Credentialing Software Market Segmentation
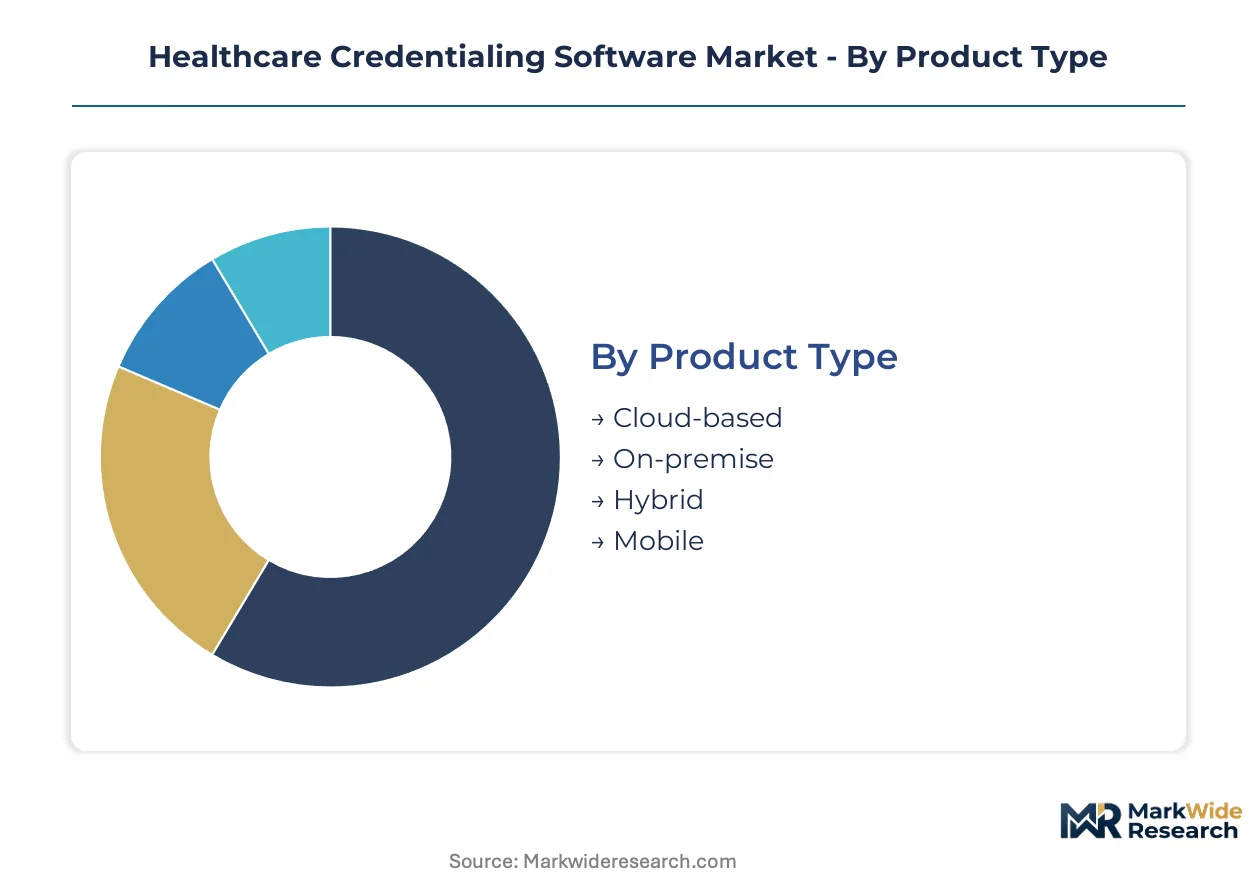
Credentialing software segmentation reveals where health systems allocate procurement budgets amid infrastructure migration pressures. Deployment architecture and solution specialization determine vendor selection criteria across acute care networks and ambulatory settings.
Product Type:
Substitution pressure intensifies for on-premise installations as health systems accelerate decommissioning of data center assets and redirect capital toward cloud-native alternatives.
- Cloud-based:Multi-tenant SaaS architectures deliver automatic updates and elastic scaling without health system IT overhead. Hospital networks in the United States favor these platforms for rapid NCQA certification timelines and reduced compliance burden.
- On-premise:Legacy server installations persist in isolated rural health systems with unreliable connectivity or stringent data sovereignty requirements. Maintenance costs and security patch responsibility increasingly disadvantage this model against cloud alternatives.
- Hybrid:Split architectures retain sensitive provider data on local servers while leveraging cloud analytics for reporting and monitoring workflows.
- Mobile:Native iOS and Android credentialing apps enable field-based verification specialists to capture documentation and check exclusion lists remotely.
Cloud-based retains volume leadership; mobile holds the steepest expansion curve.
End User:
Procurement authority concentrates in integrated delivery networks with centralized workforce management functions spanning dozens of facilities.
- Hospitals:Academic medical centers and community hospitals deploy comprehensive credentialing suites covering thousands of physicians and allied health professionals. The Joint Commission accreditation requirements drive investment in continuous monitoring capabilities beyond periodic recredentialing cycles.
- Health Systems:Multi-hospital networks standardize credentialing workflows across acquired facilities to eliminate redundant verification labor. Enterprise procurement favors vendors with proven interoperability across Epic, Cerner, and Meditech EHR environments.
- Clinics:Ambulatory surgery centers and specialty practices prioritize cost-efficient license verification modules over full privileging management suites.
- Credentialing Organizations:Third-party verification services and managed service organizations aggregate credentialing functions for multiple client health systems under service-level agreements.
Health systems command the largest contract values; clinics represent the most price-sensitive segment.
Deployment:
Margin structure varies sharply by infrastructure control level, with dedicated environments capturing premium pricing for compliance-sensitive workloads.
- Public Cloud:Shared AWS, Azure, and Google Cloud instances deliver lowest unit economics for mid-sized hospitals with standard security requirements. HIPAA Business Associate Agreements are standardized across major hyperscalers.
- Private Cloud:Single-tenant virtualized environments isolate credentialing data for health systems with elevated breach risk tolerance or specialized audit requirements.
- Community Cloud:Collaborative infrastructure shared among affiliated health systems enables cost pooling while maintaining sector-specific compliance certifications.
- Dedicated Servers:Bare-metal hosting for maximum performance isolation appeals to large health systems with predictable workload volumes and dedicated security operations centers.
Public Cloud dominates transaction volume; private cloud configurations expand most quickly among consolidated health systems.
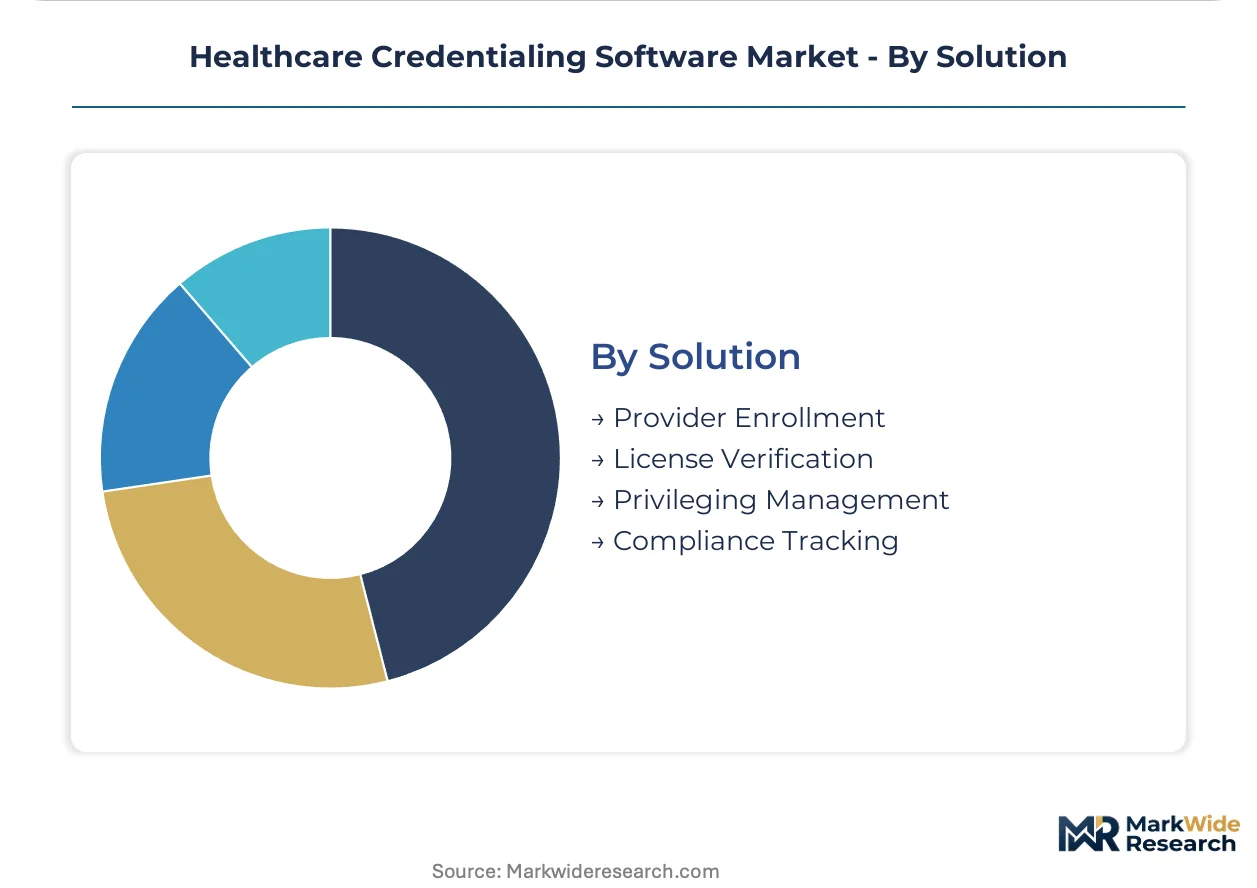
Solution:
Application depth determines pricing tier, with enrollment management capturing disproportionate value due to direct revenue linkage.
- Provider Enrollment:Automated submission to CMS Medicare and Medicaid programs, plus commercial payer portals, accelerates revenue recognition for newly hired clinicians. The US Centers for Medicare & Medicaid Services mandates for timely enrollment verification make this module indispensable for CFO oversight.
- License Verification:Primary source automation for state medical boards, DEA registrations, and interstate compact status reduces manual staff hours. Interstate Medical Licensure Compact expansion multiplies cross-jurisdictional verification complexity and software demand.
- Privileging Management:Workflow engines for medical staff committees document competency assessments and procedural authority grants with audit trails for accreditation surveys.
- Compliance Tracking:Continuous monitoring of OIG exclusions, sanctions databases, and malpractice history triggers automated alerts for credential status changes.
Provider enrollment generates the highest per-seat pricing; license verification is gaining share fastest among telehealth-intensive organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS tightening of provider enrollment verification timelines is accelerating health system procurement of automated credentialing platforms across mature healthcare markets. Hospital networks in North America and Western Europe dominate initial deployment, while Asia-Pacific health systems are beginning to digitize workforce qualification management.
United States
Academic medical centers and consolidated health systems drive enterprise-scale adoption of cloud-native credentialing suites. The US Centers for Medicare & Medicaid Services mandates for timely enrollment verification compress implementation timelines from months to weeks. The Boston-Cambridge corridor anchors specialized vendor development, with multiple workforce management technology clusters concentrated in Massachusetts and California.
Germany
University hospitals and regional health networks are standardizing credentialing workflows amid digital hospital initiatives. The EU Medical Device Regulation and GDPR compliance requirements shape platform security architectures. The Rhine-Ruhr metropolitan region hosts established healthcare IT vendors expanding into credentialing automation for cross-border provider mobility.
United Kingdom
NHS Trust consolidation is creating procurement demand for unified workforce verification across integrated care systems. NHS England's workforce standards and the Care Quality Commission inspection regime mandate systematic qualification tracking. London's health technology cluster supports emerging credentialing specialists serving both public and private hospital groups.
Canada
Provincial health authorities are migrating from fragmented credentialing processes toward centralized digital platforms. Health Canada oversight of medical device regulation and provincial college licensing requirements create multi-layered compliance complexity. Toronto's health informatics sector is developing credentialing solutions tailored to interprovincial physician mobility.
Australia
State-based hospital networks are adopting automated privileging management amid workforce shortage pressures. The Australian Health Practitioner Regulation Agency's national registration scheme enables standardized verification protocols across jurisdictions. Sydney and Melbourne health technology clusters are building credentialing modules for telehealth provider onboarding.
Healthcare Credentialing Software Market Competitive Environment
Listed leaders compete with private specialists across deployment architecture and vertical integration depth. The vendor landscape organizes into three distinct tiers: enterprise-suite incumbents with workforce management breadth, pure-play credentialing specialists with primary-source data networks, and modular API-first challengers attacking specific workflow components. Consolidation pressure intensifies as health systems demand unified platforms spanning credentialing, privileging, and enrollment functions. Strategic moves concentrate on vertical integration into adjacent workforce management modules and geographic expansion through health system network consolidation.
Within the enterprise-suite tier, symplr exemplifies vertical integration across hospital workforce management, while Verisys anchors a position through proprietary data verification infrastructure. Medallion occupies a specialist position with modular API-first architecture competing against legacy monolithic deployments. These three patterns—suite breadth, data network control, and architectural modularity—define the competitive vectors reshaping procurement decisions among consolidated US health systems.
| Leading Market Players |
|---|
| symplr |
| Verisys |
| OmniMD |
| Medallion |
| Medversant |
| CureMD |
| VerityStream |
| nCred |
| Atlas Systems |
| Others |
Value Chain & Pricing Dynamics
Ninety-day implementation timelines for NCQA-certified deployments compress vendor cash conversion cycles and concentrate pricing power with platforms bearing pre-built primary-source data integrations. Health system procurement committees exploit this urgency to extract subscription concessions from challengers lacking federal verification network access, while incumbent suite providers defend annual recurring revenue through workforce management module bundling.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with HIPAA-compliant cloud architectures commanding subscription premiums over on-premise alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, integration depth, and primary-source data coverage breadth. Cost compression in the economy tier is intensifying because mid-sized hospitals now procure license verification and exclusion monitoring as discrete microservices rather than integrated suites. Clinics represent the most price-sensitive segment, deferring privileging management investments until accreditation surveys mandate compliance documentation.
Supply Chain Analysis
Implementation timelines stretching from contract signature to live verification average fourteen weeks for cloud-native deployments, extending to twenty-six weeks where legacy HRIS middleware is required. Software development concentrates in the United States, India, and Israel, with primary-source data aggregation resting on jurisdiction-specific API integrations maintained across state medical boards and federal exclusion databases. Single-source vulnerability pervades the DEA registration verification layer, where controlled substance authority checks depend on a single federal database endpoint. Distribution runs through direct enterprise sales teams for health systems exceeding five hundred beds, while smaller facilities access platforms through GPO contracts and regional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare credentialing software sits in early-cycle expansion as hospital network consolidation accelerates enterprise-scale procurement of unified workforce qualification platforms. CMS reimbursement gatekeeping requirements and Interstate Medical Licensure Compact expansion create durable tailwinds for automated verification adoption.
For Market Incumbents: Compound defensive positioning through backward integration into primary-source data networks and continuous monitoring analytics that substitute for periodic recredentialing workflows. Acquire specialized telehealth credentialing modules to neutralize API-first challengers attacking cross-jurisdictional verification complexity. Prioritize retention engineering over new logo acquisition as CFOs reclassify SaaS procurement under operational expenditure budgets. For New Entrants and Emerging Players: NCQA certification fast-tracks for behavioral health credentialing gaps unlock white-space penetration where substance abuse counselors and mental health practitioners face patchwork state licensing without established automation vendors. Target ambulatory surgery centers and specialty practices with modular license verification microservices priced below comprehensive suite alternatives. Pursue channel partnerships with Epic and Cerner implementation specialists to bypass direct health system sales cycle friction. For Investors and Strategic Acquirers: Carve-out targets emerge from health system IT departments maintaining legacy credentialing databases resistant to API connectivity, where middleware development capabilities command strategic premiums. Five-to-ten year viability favors vendors with proven interoperability across dominant EHR environments and pre-built payer enrollment portal integrations. Monitor Interstate Medical Licensure Compact ratification velocity as the signal to watch for telehealth credentialing automation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Primary-Source Data Network Expansion | Proprietary federal and state verification API integrations create switching costs against modular challengers. |
| Continuous Monitoring Platform Development | Joint Commission expanded focus on ongoing competence documentation shifts software requirements toward real-time quality registry integration. |
| Behavioral Health Credentialing Specialization | Patchwork state licensing for mental health practitioners creates unmet demand for specialized verification workflows. |
| Epic-Cerner Interoperability Certification | Enterprise procurement committees mandate proven EHR environment compatibility for consolidated health system deployments. |
| Blockchain-Verified Credential Wallet Pilot | Federated identity networks enable portable provider profiles across competing health systems without redundant reverification labor. |
Study Parameters
Desk research of CMS Medicare enrollment databases, state medical board verification protocols, and hospital procurement contract filings preceded structured interviews with health system CIOs, medical staff office directors, credentialing verification specialists, and GPO contracts managers. Primary fieldwork captured implementation timeline benchmarks, subscription pricing bands, and integration complexity assessments across cloud-native and legacy deployment architectures. Secondary validation drew from The Joint Commission accreditation survey data, NCQA certification timelines, and healthcare IT vendor SEC disclosures where available. Bottom-up health system procurement modeling triangulated against top-down market sizing from workforce management software spend allocation.
Variance decomposition across deployment architecture, solution specialization, and end-user scale segments shaped the analytical framework over the projection horizon. Modeled dimensions included cloud versus on-premise infrastructure control, provider enrollment versus license verification versus privileging management application depth, and hospital versus health system versus clinic procurement authority. CAGRs were derived from segment-level adoption curves weighted by health system consolidation velocity and regulatory mandate compliance deadlines. Forecast inputs incorporated Interstate Medical Licensure Compact expansion trajectories and OCR HIPAA enforcement escalation patterns.
The analysis sits within stated boundaries; outcomes outside sustained hospital network consolidation, CMS reimbursement policy stability, or hyperscaler cloud infrastructure availability would require recalibration. Forecasts reflect documented assumptions regarding telehealth licensing compact ratification timelines and health system IT capital expenditure reclassification toward operational budgets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Operating Room Management Software Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Epharmacy Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Europe Outpatient Software Market