
 Healthcare Ediscovery Market | 2026-2036
Healthcare Ediscovery Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Ediscovery Market Outlook
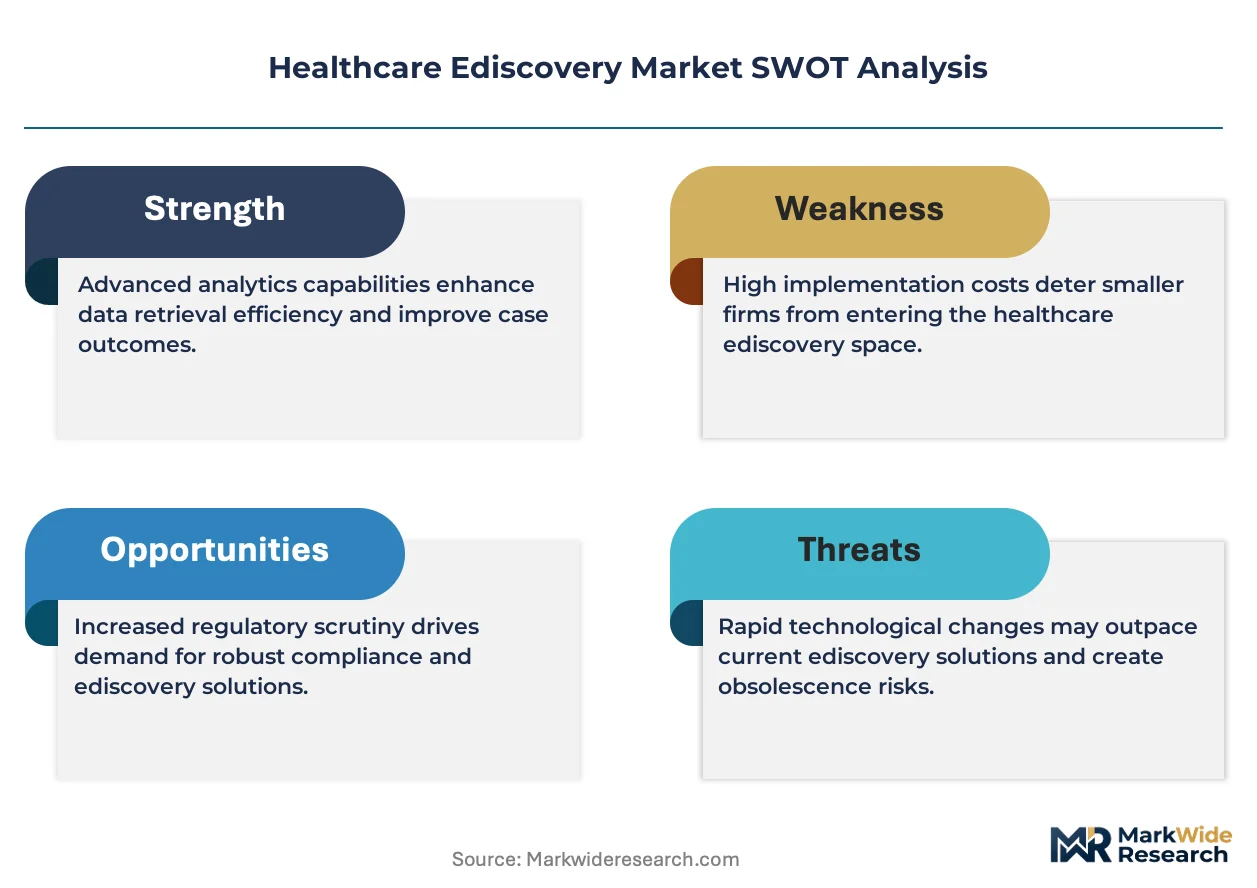
Modular SaaS bundling is realigning how hospital legal departments procure ediscovery capabilities, shifting from standalone software licenses toward integrated managed services. OpenText Corporation leverages its information management heritage to anchor enterprise healthcare contracts. Epiq Systems competes through specialized legal service workflows tailored to provider litigation. Nuix Limited differentiates via advanced analytics engines that process unstructured clinical data at scale.
Healthcare ediscovery encompasses the identification, preservation, collection, processing, review, and production of electronically stored information within clinical, administrative, and financial systems, typically operating across HL7 FHIR data formats, DICOM imaging archives, and EMR audit logs to satisfy legal hold obligations and regulatory disclosure requirements. The software solutions segment dominates current revenue as hospitals modernize legacy on-premises archives, while cloud services represent the fastest-expanding deployment category as IT security teams gain confidence in vendor-hosted environments. Managed services capture concentrated margin pools where law firms and insurance companies outsource entire litigation response workflows.
FDA 21 CFR Part 11, HIPAA, and the HITECH Act collectively shape product standards by mandating immutable audit trails, access controls, and breach notification protocols that ediscovery platforms must embed to serve US healthcare clients. The SEC and DOJ healthcare fraud enforcement posture further tightens preservation requirements for financial and operational records. Stakeholders must monitor how state-level privacy laws fragment compliance architectures and force platform vendors to architect jurisdiction-specific data residency controls.
Market Dynamics
Cloud migration of clinical archives is forcing hospital legal departments to re-architect data retention policies around vendor-hosted environments rather than on-premises infrastructure. HIPAA audit obligations now extend to third-party subprocessors, tightening vendor selection criteria.
Growth Catalysts
- HIPAA Enforcement Intensification:The HITECH Act's breach notification mandates compel healthcare providers to invest in automated litigation hold systems that flag protected health information across EMR audit logs.
- Malpractice Litigation Volume:United States courts process elevated medical liability cases requiring comprehensive electronic health record reconstruction, driving demand for specialized clinical data processing tools.
- HL7 FHIR Standardization:Interoperability protocols enable seamless extraction of structured clinical data for legal discovery, reducing manual chart review costs for hospital legal teams.
Market Restraints
- Data Residency Fragmentation:State-level privacy laws in California, New York, and Texas impose conflicting storage location requirements that complicate multi-jurisdictional litigation support deployments.
- Legacy Archive Conversion Costs:DICOM imaging archives and proprietary EMR formats require expensive normalization before ediscovery platforms can process them for legal review.
- Cybersecurity Insurance Exclusions:Ransomware incidents targeting cloud-hosted litigation databases face coverage gaps that deter risk-averse hospital IT departments from SaaS adoption.
Strategic Opportunities
- Rural Health Network Expansion:Critical access hospitals in the United States remain underpenetrated by managed ediscovery services, presenting white-space opportunity for subscription-based legal support models.
- Artificial Intelligence Convergence:Natural language processing engines paired with clinical concept extraction reduce attorney review hours for unstructured physician notes and nursing documentation.
- Telehealth Record Preservation:CMS reimbursement rules now mandate retention of video consultation metadata, creating new data categories requiring specialized collection and processing workflows.
Industry Challenges
- Forensic Nursing Expertise Scarcity:Clinical informaticists who understand both EMR data structures and legal hold protocols command premium salaries that strain hospital legal department budgets.
- Multi-Vendor EMR Integration:Health systems running Epic, Cerner, and Meditech simultaneously face complex data harmonization requirements when responding to enterprise-wide litigation.
- 21 CFR Part 11 Validation:FDA-regulated clinical trial sites must maintain separate ediscovery architectures for research data, duplicating infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Ediscovery Market |
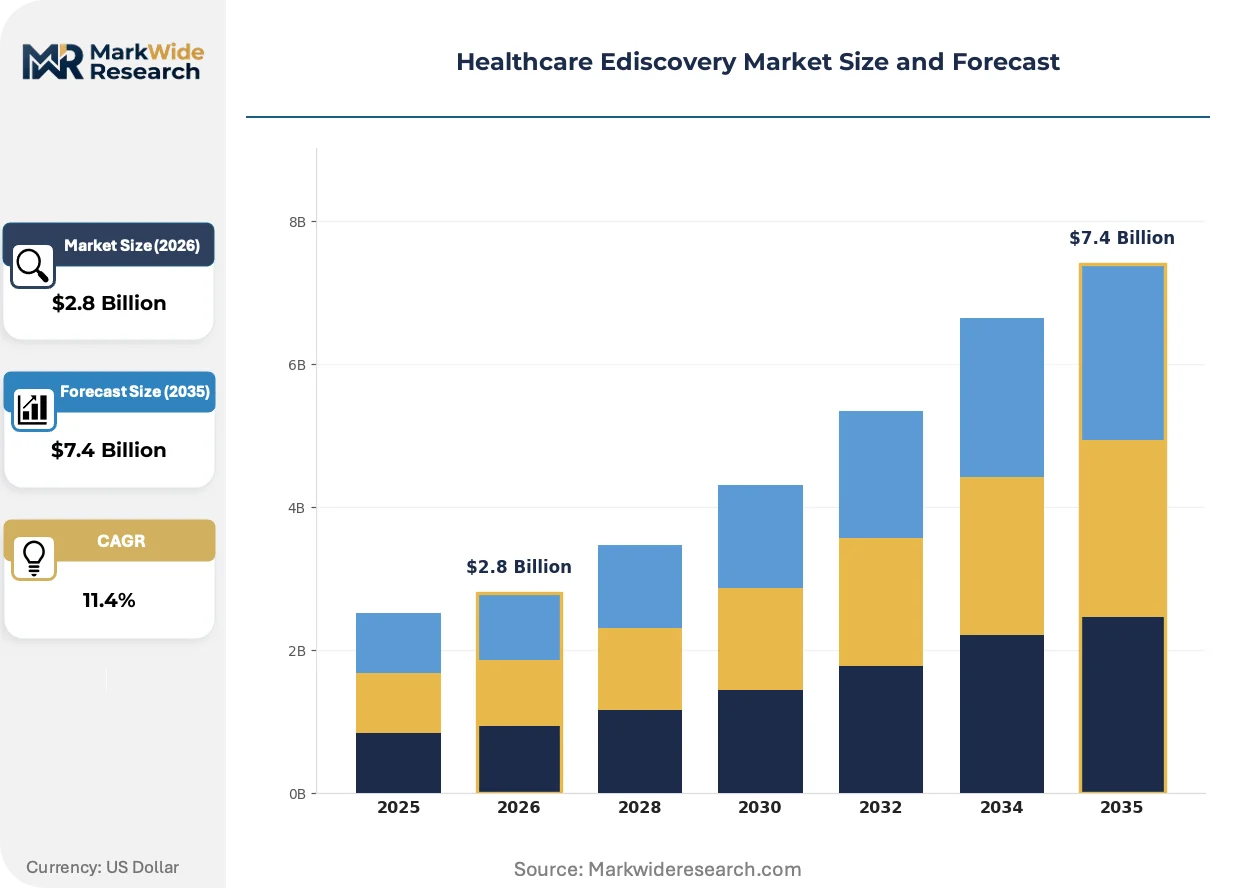
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Services, Analytics Tools, Data Storage End User: Hospitals, Law Firms, Healthcare Providers, Insurance Companies Deployment: On-Premises, SaaS, Hybrid, Managed Services Application: Litigation Support, Compliance, Regulatory Investigations, Risk Management |
| Companies Covered | Relativity, OpenText Corporation, Epiq Systems, Microsoft Corporation, Nuix Limited, IBM Corporation, Everlaw, ZyLAB, Logikcull, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Ediscovery Market Strategic Shifts
Healthcare ediscovery is pivoting from reactive litigation response toward proactive information governance, embedding legal hold capabilities directly into clinical workflow systems rather than bolt-on software modules.
Natural language processing is expanding into clinical concept extraction from unstructured physician dictation and nursing notes. Hospital legal departments at academic medical centers are adopting these engines to accelerate privilege review timelines. The technology is expanding into predictive coding workflows that prioritize documents requiring attorney eyes, compressing review costs for high-volume malpractice matters.
The SEC and DOJ healthcare fraud enforcement posture has tightened preservation requirements for financial and operational records beyond clinical data alone. Hospital systems now face simultaneous obligations to retain billing system logs, supply chain procurement records, and executive communications. Compliance officers are responding by consolidating ediscovery governance across previously siloed legal, compliance, and IT functions.
Law firm procurement patterns are consolidating vendor relationships from point solutions toward integrated managed services contracts. Insurance carriers underwriting hospital liability policies increasingly mandate approved ediscovery vendor panels as a condition of coverage. This concentration is most visible in the United States, where malpractice defense costs drive purchasing decisions for the largest health systems.
Healthcare Ediscovery Market Segmentation
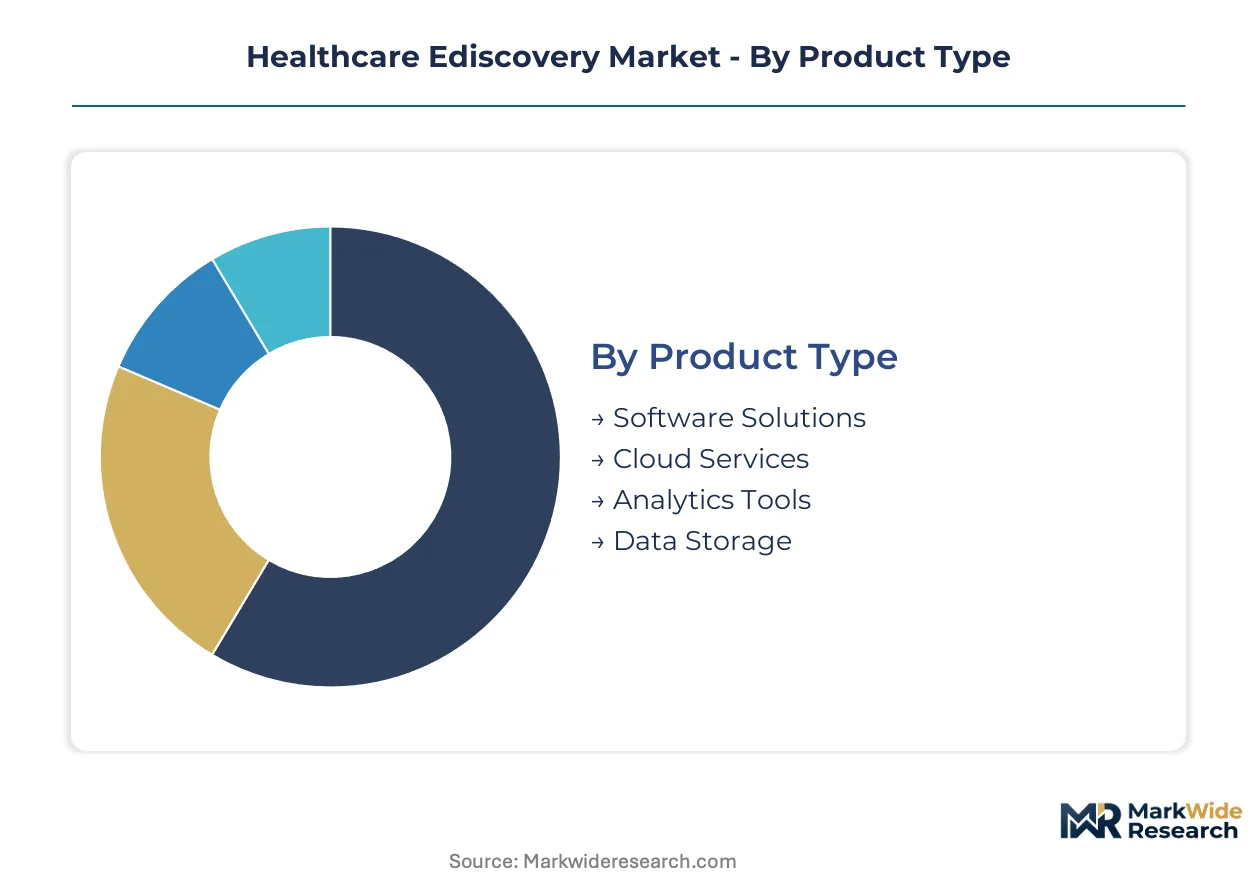
Healthcare ediscovery procurement patterns diverge sharply by organizational capability and risk exposure. Hospital legal departments prioritize integrated platforms that embed directly into clinical workflows, while external counsel demand specialized tools for multi-matter management.
Product Type:
Replacement cycles in this market accelerate as HIPAA audit mandates force retirement of legacy on-premises archives that cannot generate immutable logs. Cloud-native architectures displace installed software faster than in adjacent legal technology sectors.
- Software Solutions:Enterprise platforms process HL7 FHIR feeds, DICOM imaging archives, and EMR audit logs through unified ingestion pipelines. Hospital systems in the United States dominate procurement, driven by malpractice litigation volumes and federal fraud enforcement requirements that demand comprehensive electronic health record reconstruction capabilities.
- Cloud Services:Vendor-hosted environments eliminate capital expenditure for rural health networks while satisfying HIPAA business associate agreement requirements through certified subprocessors. Demand concentrates among critical access hospitals seeking to outsource infrastructure management without sacrificing audit trail integrity.
- Analytics Tools:Natural language processing engines extract clinical concepts from unstructured physician dictation.
- Data Storage:Immutable object storage tiers satisfy 21 CFR Part 11 retention mandates for FDA-regulated trial sites.
Volume placements concentrate in Software Solutions; the faster expansion belongs to Cloud Services.
End User:
Procurement authority shifts based on litigation funding sources and insurance policy structures. Self-insured health systems retain direct vendor relationships, while carriers increasingly mandate approved panels.
- Hospitals:Academic medical centers deploy enterprise-wide governance frameworks spanning Epic, Cerner, and Meditech environments simultaneously. Legal departments at these institutions command budgets for predictive coding engines that compress privilege review timelines for high-volume malpractice matters.
- Law Firms:Defense boutiques serving hospital liability practices consolidate from point solutions toward managed services contracts with guaranteed cost caps. Firms in the United States process elevated medical liability caseloads requiring specialized clinical data processing expertise that generalist ediscovery vendors cannot supply.
- Healthcare Providers:Physician practice groups and ambulatory surgery centers adopt lighter-weight SaaS tiers.
- Insurance Companies:Carriers embed ediscovery vendor approval as a condition of professional liability coverage.
Revenue concentration sits with Hospitals; Insurance Companies are climbing the fastest as policy language tightens.
Deployment:
IT security confidence in vendor-hosted environments determines adoption velocity more than feature differentiation. Ransomware insurance exclusions create friction that hybrid architectures attempt to resolve.
- On-Premises:Legacy installations persist where health systems operate air-gapped research networks subject to FDA 21 CFR Part 11 validation requirements. These deployments duplicate infrastructure costs for clinical trial sites that must maintain separate architectures for research data versus operational records.
- SaaS:Multi-tenant platforms with HITRUST certification reduce compliance overhead for mid-market health systems. Adoption accelerates among organizations seeking to shift capital expenditure to operational budgets while maintaining HIPAA-compliant audit trails through certified business associate agreements.
- Hybrid:Sensitive litigation data remains on-premises while processing workloads burst to cloud.
- Managed Services:Law firms outsource entire litigation response workflows to specialized legal service providers.
Installed base dominance remains with On-Premises; SaaS is gaining share fastest among new deployments.
Application:
Use case priority reflects enforcement posture from the SEC, DOJ, and HHS Office for Civil Rights. Financial record preservation now rivals clinical data in strategic importance.
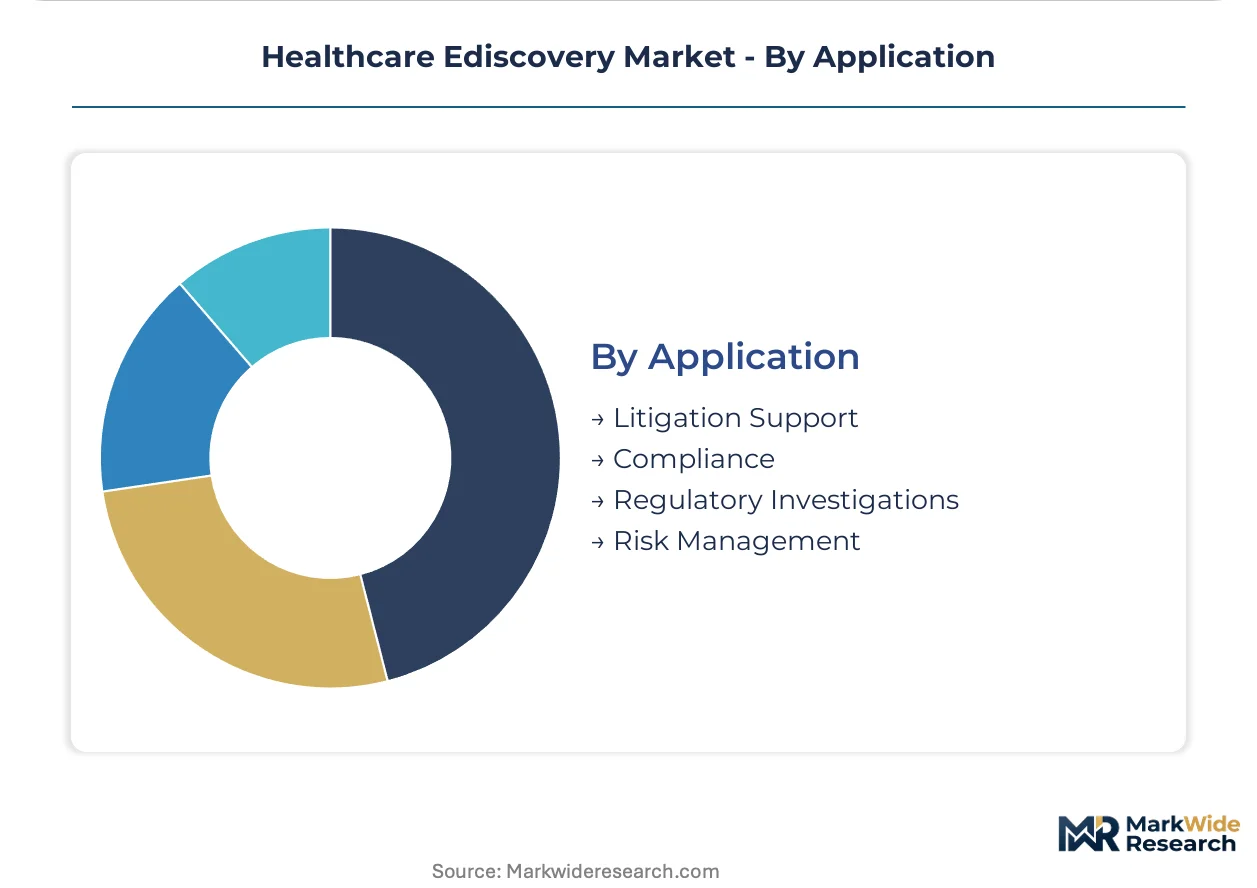
- Litigation Support:Comprehensive matter management spans identification through production, with specialized workflows for EMR reconstruction in medical malpractice defense. Hospital legal departments in the United States deploy these capabilities most intensively where federal healthcare fraud enforcement and liability litigation volumes remain elevated.
- Compliance:Proactive information governance embeds legal hold capabilities into clinical workflow systems rather than relying on bolt-on modules. Health systems respond to HITECH Act breach notification mandates by automating protected health information flagging across EMR audit logs.
- Regulatory Investigations:SEC and DOJ healthcare fraud inquiries require preservation of billing system logs and executive communications.
- Risk Management:Insurance underwriting integration drives vendor consolidation toward approved panels.
Budget allocation skews toward Litigation Support; Compliance shows the steepest expansion trajectory as governance matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of healthcare ediscovery solutions while production concentrates among North American software vendors serving domestic hospital systems. Regulatory complexity and litigation volume create geographic demand asymmetry that favors established legal technology clusters.
United States
Federal healthcare fraud enforcement and elevated malpractice litigation volumes drive hospital investment in specialized clinical data processing tools. HIPAA and the HITECH Act mandate immutable audit trails and breach notification protocols that shape vendor product standards. The Boston and New York metropolitan corridors host dense concentrations of academic medical centers deploying enterprise-wide governance frameworks across Epic and Cerner environments.
Germany
University hospital networks and statutory health insurers generate demand for GDPR-compliant litigation support architectures. The EU AI Act and national data protection frameworks impose strict processing limitations on clinical analytics engines. Frankfurt and Munich anchor the vendor ecosystem serving central European health systems with hybrid on-premises and cloud-hosted deployment models.
United Kingdom
NHS litigation authority frameworks and clinical negligence claims processing create structured procurement channels for ediscovery services. The UK Information Commissioner's Office enforces strict health data handling standards that influence platform design. London-based legal technology consultancies serve private hospital groups and medical defense organizations with managed services contracts.
Canada
Provincial health authority litigation and medical malpractice defense drive adoption of cloud-based legal hold systems. Health Canada and PIPEDA establish retention and privacy requirements that parallel HIPAA frameworks with Canadian data residency constraints. Toronto and Vancouver health technology clusters host regional vendor operations serving Ontario and British Columbia hospital systems.
Australia
State-based health department litigation and coronial inquiry procedures generate specialized demand for EMR reconstruction capabilities. The Therapeutic Goods Administration and Office of the Australian Information Commissioner regulate clinical data handling and breach reporting. Sydney and Melbourne academic medical centers deploy predictive coding engines for high-volume medical liability matters.
Healthcare Ediscovery Market Competitive Environment
The competitive structure tilts toward enterprise information management specialists with healthcare-specific legal service workflows. Consolidation pressure concentrates procurement authority among hospital legal departments and insurance carrier panels. Two archetypes dominate: integrated software-platform vendors and specialized legal process outsourcing providers. Horizontal integration through managed services acquisitions and vertical capability expansion into clinical data analytics represent the primary competitive vectors.
Within the enterprise-platform tier, OpenText Corporation and Microsoft Corporation anchor positions through information management heritage and cloud infrastructure scale respectively. Epiq Systems exemplifies the legal services archetype with specialized workflows for provider litigation. Nuix Limited occupies a distinct position through advanced analytics engines processing unstructured clinical data. Relativity and Everlaw represent cloud-native entrants competing on deployment flexibility and user experience design for mid-market health systems.
| Leading Market Players |
|---|
| Relativity |
| OpenText Corporation |
| Epiq Systems |
| Microsoft Corporation |
| Nuix Limited |
| IBM Corporation |
| Everlaw |
| ZyLAB |
| Logikcull |
| Others |
Value Chain & Pricing Dynamics
Hospital legal department consolidation onto managed services contracts is forcing vendors to absorb infrastructure costs upfront, compressing SaaS margins while shifting revenue toward long-term subscription commitments. Cloud-native entrants undercut established platform pricing to win mid-market health systems, triggering defensive bundling from incumbent information management specialists.
Pricing Analysis
Margin tightening in enterprise SaaS tiers reflects procurement officers demanding HITRUST-certified environments without corresponding price premiums. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with predictive coding budgets from critical access hospitals seeking basic legal hold automation. Price differentiation hinges on HL7 FHIR processing depth and DICOM archive normalization capabilities. Rural health networks exhibit highest price sensitivity, deferring upgrades despite HIPAA audit mandates.
Supply Chain Analysis
Clinical informaticist scarcity in the United States, Germany, and United Kingdom constrains vendor delivery capacity and inflates implementation timelines. Platform development draws from specialized NLP engineering talent pools concentrated in Boston, London, and Sydney metropolitan corridors. Supply chain risk centers on single-source dependency for FDA 21 CFR Part 11 validation consultants. Distribution runs through direct enterprise sales teams for hospital systems, with channel partners serving law firm defense boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare ediscovery sits at a technology-transition inflection where cloud-native architectures displace legacy on-premises archives that cannot satisfy immutable audit trail mandates. Natural language processing engines for clinical concept extraction represent the capability gap separating incumbent platform vendors from emerging competitors.
For Market Incumbents: Acquire specialized NLP engineering teams to close the clinical analytics capability gap against cloud-native entrants. Consolidate managed services contracts with insurance carrier panels before policy language hardens vendor approval requirements. Defensive patent positioning around HL7 FHIR data extraction workflows protects against horizontal platform expansion from hyperscale cloud providers. For New Entrants and Emerging Players: Law firm defense boutiques serving hospital liability practices represent the most penetrable channel, as these firms consolidate from point solutions toward integrated managed services with guaranteed cost caps. Critical access hospitals in rural United States markets remain underpenetrated by subscription-based legal support models lacking capital expenditure requirements. White-space opportunity concentrates on telehealth record preservation workflows where CMS reimbursement rules mandate new metadata retention categories. For Investors and Strategic Acquirers: The window for entry favors clinical analytics specialists with proven FDA 21 CFR Part 11 validation experience and existing hospital legal department relationships. Long-term viability rests on platforms that embed legal hold capabilities directly into Epic and Cerner workflow systems rather than bolt-on modules. Watch for insurance carrier panel consolidation announcements as inflection signals for vendor market share concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding legal hold capabilities into Epic and Cerner clinical workflows reduces bolt-on friction for hospital legal departments. |
| Acquisition of Specialist Firm | Clinical NLP engineering teams accelerate privilege review timelines for unstructured physician dictation and nursing notes. |
| Strategic Partnership | Insurance carrier panel inclusion mandates vendor consolidation toward approved ediscovery service providers. |
| Geographic Expansion | Critical access hospital networks in rural United States markets lack capital for on-premises archive modernization. |
| Product Launch | Telehealth metadata preservation tools address CMS reimbursement rule requirements for video consultation retention. |
Study Parameters
SEC filings, hospital procurement databases, and CMS Medicare reimbursement records formed the secondary backbone for market sizing and vendor revenue estimation. Primary interviews with hospital legal department directors, health system compliance officers, and law firm litigation support managers validated platform adoption timelines and procurement authority shifts. Bottom-up triangulation across EMR audit log volume estimates and top-down validation against healthcare fraud enforcement expenditure data anchored the forecast framework.
Historical trendline analysis of HIPAA enforcement actions and malpractice litigation filing volumes informed the projection approach across the modeling period. Segmentation modeling incorporated deployment architecture, organization size tier, EMR vendor environment, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of cloud migration velocity and managed services contract penetration rates. Forecast inputs included HL7 FHIR standardization adoption curves and insurance carrier panel consolidation announcements.
Several conditions sit outside the modeled scope, including state-level privacy law fragmentation effects on multi-jurisdictional deployment costs and ransomware insurance exclusion evolution for cloud-hosted litigation databases. Forecasts reflect assumptions regarding HITRUST certification maintenance and FDA 21 CFR Part 11 validation burden stability. Material deviation in HIPAA enforcement intensity or federal healthcare fraud prosecution posture warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Assisted Living Software Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
E-Prescribing Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
US Long Term Care Software Market