
 Italy Dental Practice Management Software Market | 2026-2036
Italy Dental Practice Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Dental Practice Management Software Market Foresight
Italian dental software vendors is rebalancing capacity toward cloud-native architectures after years of on-premise dominance. Henry Schein leverages its distribution network to sustain hardware-software bundling across the peninsula. Carestream Dental anchors its position through imaging-integrated workflow suites. Dental Opera specializes in modular platforms tailored to independent practitioners.
Dental practice management software encompasses clinical scheduling, patient record administration, billing automation, and regulatory compliance modules designed for oral healthcare providers. Systems typically integrate with digital radiography equipment and electronic health record standards to streamline chair-time utilization and reimbursement accuracy. Cloud-based deployment now leads growth trajectories as multi-practice groups prioritize centralized data access across locations. Patient Management functionality captures concentrated margin pools where interoperability with national health card systems differentiates vendors. On-premise solutions retain residual share among single-practice operators with limited IT infrastructure.
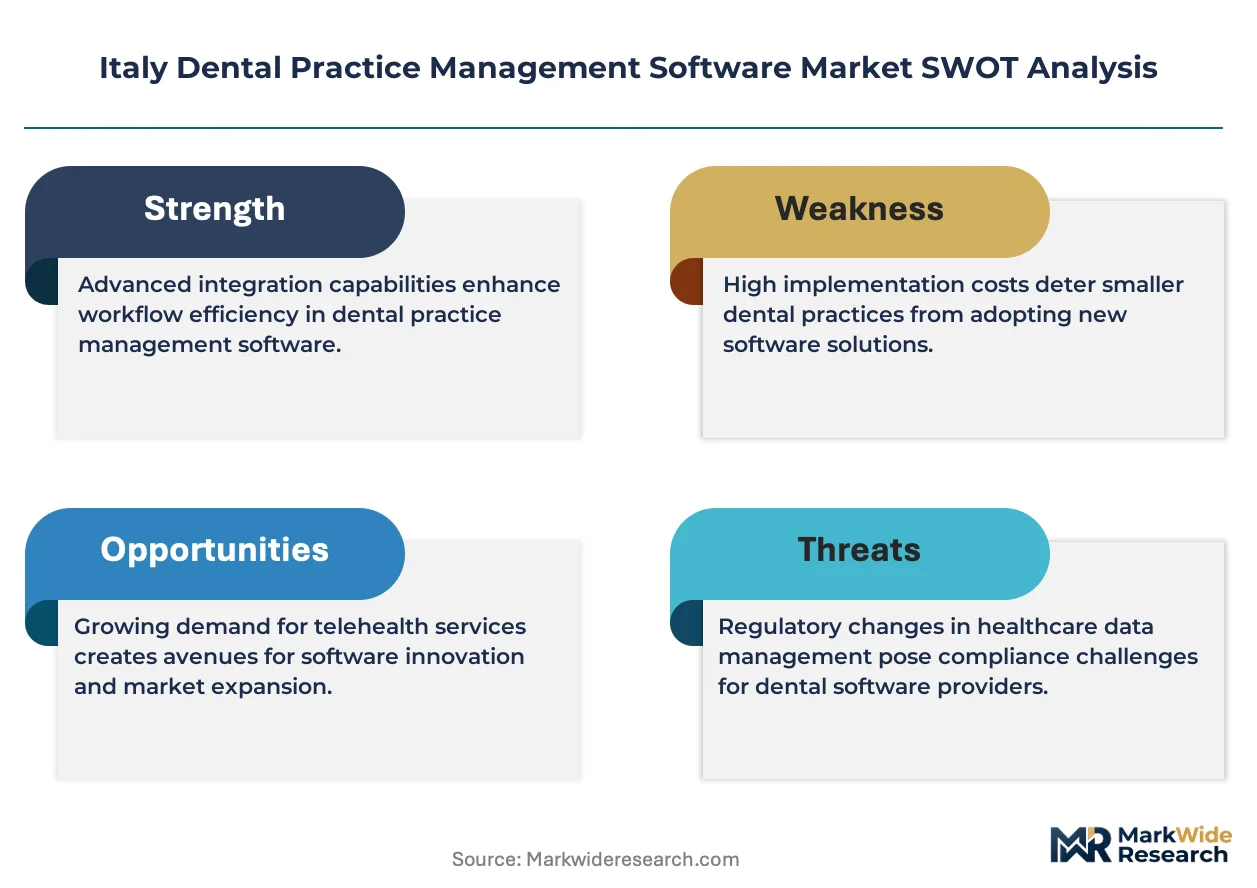
Italy's data protection framework under CNIL-equivalent oversight and the Agenzia per l'Italia Digitale's healthcare interoperability mandates shape software certification requirements. The EU Medical Device Regulation and GDPR compliance obligations constrain market access for non-certified platforms. Stakeholders must weigh cloud migration timing against lingering connectivity gaps in southern regions and evolving reimbursement digitization rules.
Market Dynamics
Cloud-native architecture migration is compressing deployment cycles across Italian dental practices as multi-location groups demand centralized data access and real-time interoperability with regional health systems.
Growth Catalysts
- PNRR Digitization Incentives:Italy's National Recovery and Resilience Plan allocates dedicated funding streams for healthcare software procurement, accelerating procurement timelines for private clinics in Lombardy and Veneto.
- Multi-Practice Network Expansion:Dental groups operating across northern Italy require unified patient record systems that integrate with the Tessera Sanitaria national health card infrastructure.
- Interoperability Mandates:Agenzia per l'Italia Digitale certification requirements for healthcare data exchange are forcing legacy system upgrades and opening vendor switching windows.
Market Restraints
- Connectivity Infrastructure Gaps:Southern regions including Sicily and Calabria exhibit inconsistent broadband reliability that degrades cloud platform performance and extends on-premise residual demand.
- GDPR Compliance Burden:Stringent data localization and patient consent management requirements under EU regulation constrain vendor market access and inflate certification costs for non-European platforms.
- Specialized Integration Costs:Proprietary digital radiography equipment from legacy imaging manufacturers demands expensive custom API development for seamless workflow integration.
Strategic Opportunities
- Central-Southern Regional Penetration:Abruzzo, Molise, and Basilicata exhibit software adoption rates substantially below northern benchmarks, presenting first-mover expansion potential for cloud-native vendors.
- AI-Assisted Diagnostic Modules:Machine learning integration with intraoral scanning and radiographic analysis is electrifying clinical workflow automation and creating premium pricing tiers for integrated suites.
- Tele-Dentistry Channel Development:Remote consultation modules aligned with regional health authority reimbursement protocols are opening new patient acquisition channels beyond traditional chair-side service.
Industry Challenges
- Cybersecurity Competency Scarcity:Dental practices lack in-house IT security expertise to manage threat detection, incident response, and penetration testing required under GDPR Article 32 technical measures.
- Legacy Data Migration Complexity:Decades of unstructured patient records in proprietary formats resist automated extraction, forcing manual validation workflows that extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Dental Practice Management Software Market |
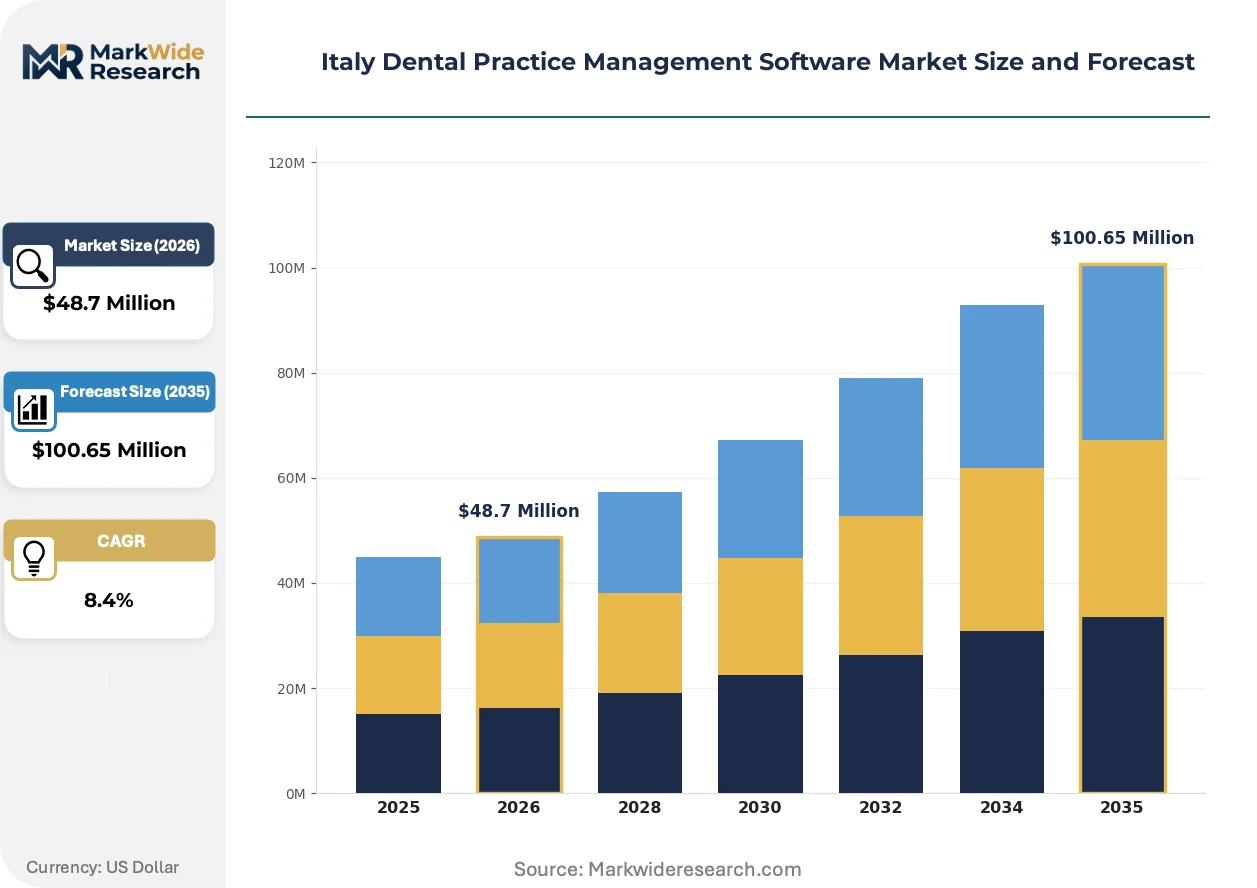
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-premise, Cloud-based, Hybrid, Mobile End User: Dentists, Orthodontists, Clinics, Laboratories Deployment: Single Practice, Multi-practice, Group Practice, Enterprise Software Features: Appointment Scheduling, Billing, Reporting, Patient Management |
| Companies Covered | Henry Schein, Carestream Dental, Dental Opera, Dental Monitoring, AGE Solutions, Dentsply Sirona, CompuGroup Medical, CASTELLINI, Orisdent, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Dental Practice Management Software Market Shifts & Advancements
Workflow automation and regulatory compliance technology are reshaping competitive differentiation in Italian dental software, with vendors racing to embed AI diagnostics and real-time reimbursement verification before reimbursement rules harden.
Cloud-native practice management platforms are electrifying operational scalability for multi-location dental groups. These systems enable centralized scheduling, inventory management, and financial reporting across dispersed clinics. Groups operating in Milan, Turin, and Bologna are migrating fastest, compressing the traditional 18-month implementation cycle to under 90 days.
EU Medical Device Regulation classification of diagnostic software modules is tightening quality management system requirements for algorithm-based radiographic analysis tools. Vendors must now maintain technical documentation and post-market surveillance comparable to Class IIa medical devices. Smaller developers lacking notified body relationships are exiting the diagnostic AI segment or partnering with established imaging manufacturers.
Subscription pricing models are displacing perpetual license structures as the dominant procurement format. Independent practitioners in Rome and Naples increasingly favor monthly SaaS payments that bundle software, security updates, and basic support. This shift compresses upfront vendor revenue recognition while extending customer lifetime value through automatic renewal mechanisms and modular feature upsells.
Italy Dental Practice Management Software Market Segmentation
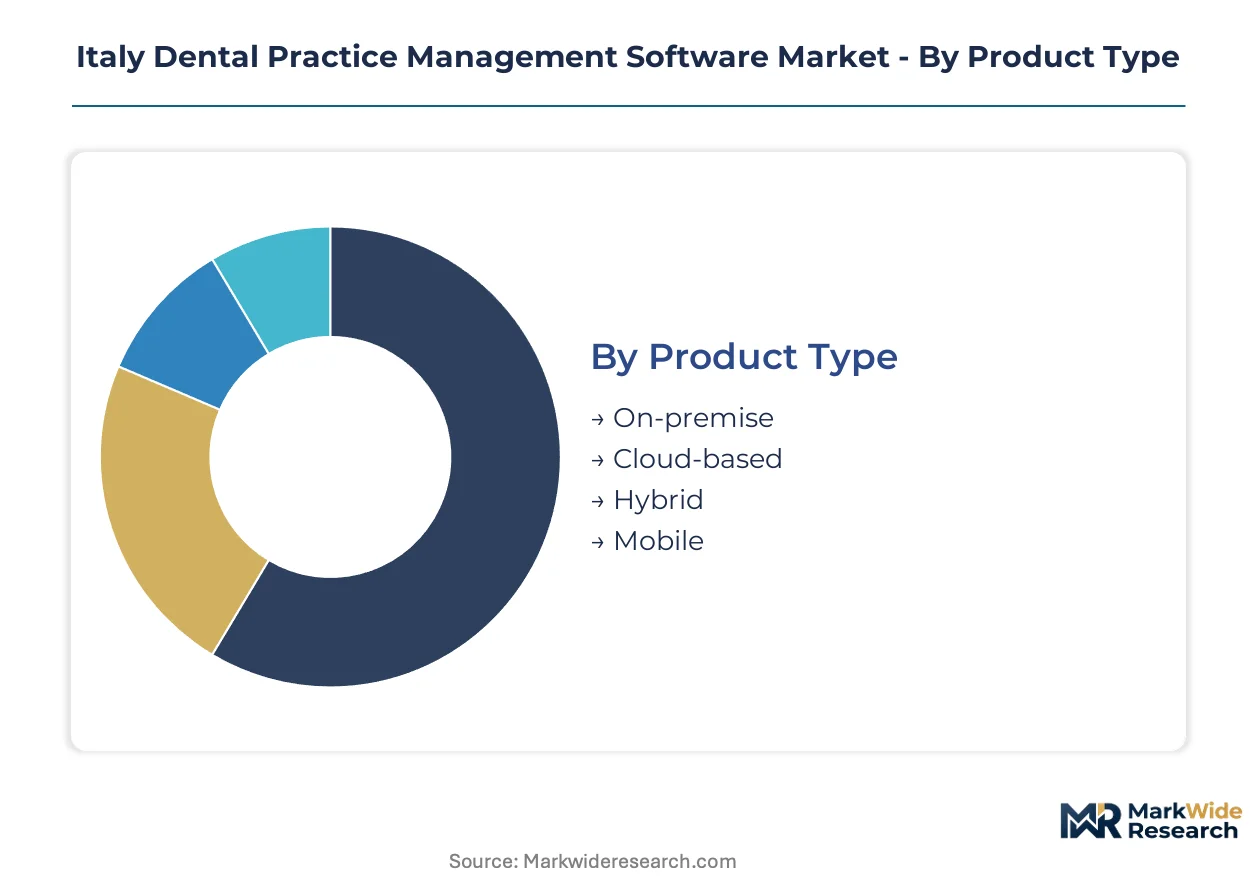
Segmentation in Italy's dental software market reveals distinct upgrade cycles across deployment models and practice scales. Replacement timelines vary from 3-year cloud refresh cycles to decade-long on-premise legacy holds, shaping vendor revenue predictability and customer acquisition costs.
Product Type:
Upgrade cycles compress most dramatically for cloud-native platforms as multi-practice groups demand continuous feature delivery without on-site maintenance windows.
- Cloud-based:Browser-accessible architectures with automatic security patching and API-driven interoperability. Lombardy and Veneto dental groups prioritize these platforms for centralized patient record access across Milan, Brescia, and Verona locations. PNRR digitization incentives accelerate procurement timelines for practices seeking Tessera Sanitaria integration.
- On-premise:Locally installed server systems requiring dedicated IT infrastructure and manual update cycles. Southern regions including Sicily and Calabria retain residual demand due to broadband reliability constraints that degrade cloud performance.
- Hybrid:Mixed architectures with sensitive data stored locally and collaborative tools delivered via cloud. Appeals to mid-sized practices in Emilia-Romagna balancing GDPR data localization with remote access needs.
- Mobile:Smartphone-optimized interfaces for chair-side charting and emergency consultation management. Gaining traction among Rome and Naples practitioners prioritizing patient communication workflows.
Cloud-based sits at the top of the volume ranking, with Hybrid climbing the fastest as practices navigate connectivity gaps without sacrificing modernization.
End User:
Cost tier differentiation separates specialized orthodontic workflow suites from generalist dental platforms, with laboratories representing a distinct procurement channel driven by case volume pricing.
- Dentists:General practitioners managing restorative, preventive, and emergency procedures through integrated scheduling and billing modules. Independent operators in Turin and Bologna favor subscription pricing that bundles security updates with core functionality.
- Clinics:Multi-chair facilities requiring inventory management, staff scheduling, and insurance pre-authorization automation. Northern Italian clinic networks drive demand for real-time interoperability with regional health authorities.
- Orthodontists:Specialists needing treatment planning integration with intraoral scanners and cephalometric analysis tools. Workflow complexity justifies premium pricing tiers for AI-assisted diagnostic modules.
- Laboratories:Dental prosthesis manufacturers requiring case tracking, digital impression management, and dentist communication portals. Integration with practice management systems determines vendor selection for large-volume Italian labs.
Clinics generate the highest absolute revenue concentration, with Orthodontists showing the steepest expansion trajectory as AI diagnostic adoption accelerates.
Deployment:
Customer type segmentation aligns procurement sophistication with practice governance structures, from solo practitioners to private equity-backed dental service organizations.
- Multi-practice:Regional and national groups operating 5-50 locations with unified data architecture requirements. Centralized financial reporting and cross-clinic patient transfer capabilities differentiate vendor offerings for these buyers.
- Single Practice:Solo operators with localized decision-making and limited IT support capacity. Price sensitivity and implementation simplicity dominate procurement criteria for this segment.
- Group Practice:2-5 location partnerships sharing ownership but requiring graduated permission structures. Abruzzo and Molise represent underpenetrated territory for vendors targeting this scaling segment.
- Enterprise:Dental service organizations with 50+ locations and dedicated procurement functions. Custom integration demands and SLA requirements create vendor switching costs that entrench incumbent platforms.
Multi-practice deployments command the largest deal sizes, with Group Practice gaining share fastest as partnership structures proliferate across central Italy.
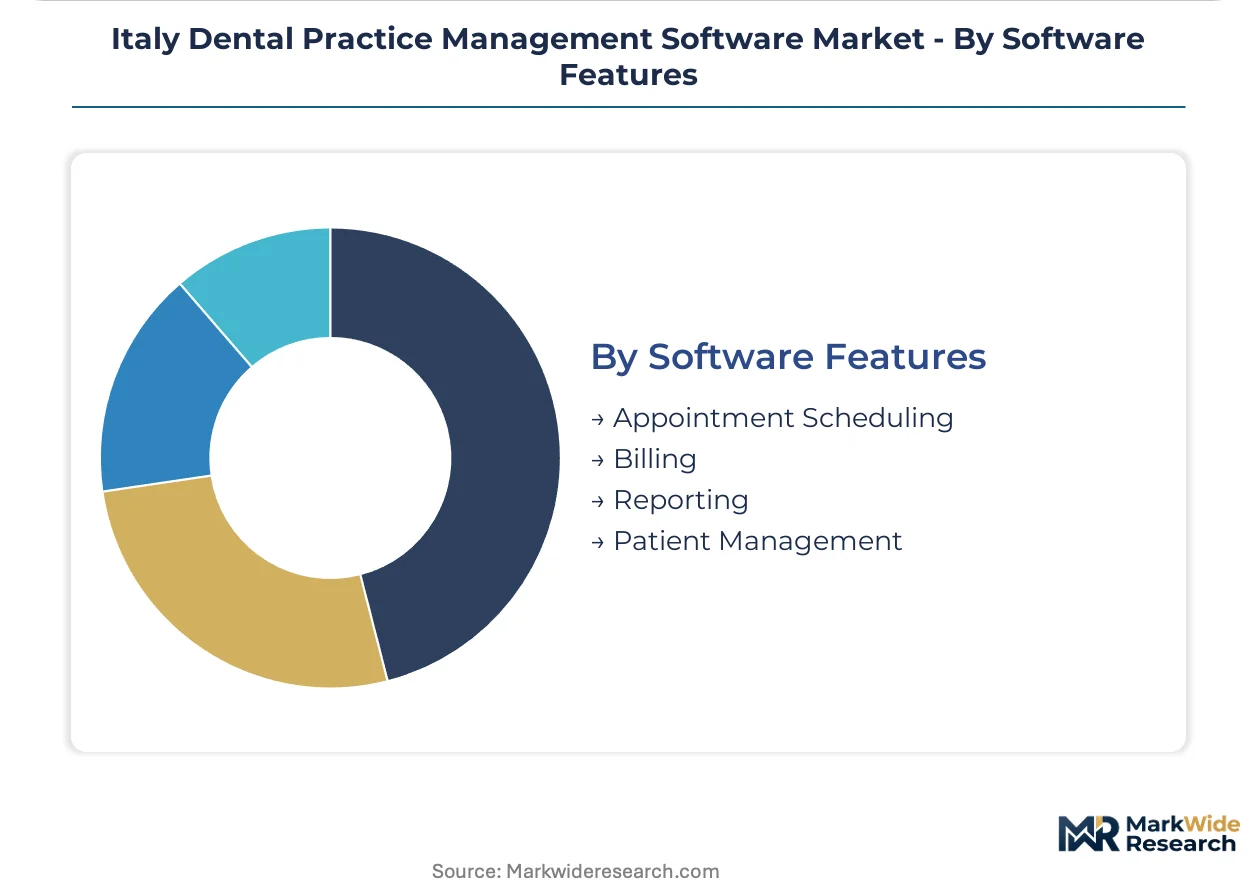
Software Features:
Margin concentration pools around patient-facing modules where interoperability with national health infrastructure creates vendor differentiation.
- Patient Management:Electronic health records, treatment history tracking, and consent documentation aligned with GDPR Article 32 technical measures. Tessera Sanitaria integration represents the critical capability for Italian market access.
- Billing:Automated claims submission, payment plan administration, and insurance verification workflows. Reimbursement digitization rules from regional health authorities reshape functional requirements continuously.
- Appointment Scheduling:Chair-time optimization, automated reminders, and waitlist management. Basic functionality commoditizes quickly without tele-dentistry channel integration.
- Reporting:Financial analytics, clinical outcome dashboards, and regulatory compliance documentation. Enterprise buyers prioritize customizable BI tools over standard templates.
Patient Management anchors vendor profitability, with Billing expanding most quickly as reimbursement digitization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor footprints as cloud-native platforms exploit compliance-cost gaps between northern Italy's digitization incentives and southern regions' lingering infrastructure constraints.
Lombardy
Multi-practice dental groups in Milan and Brescia drive concentrated demand for Tessera Sanitaria-integrated platforms. PNRR healthcare digitization funds accelerate procurement cycles for private clinics. The Milan metropolitan corridor hosts the densest cluster of cloud migration projects among Italian dental networks.
Veneto
Verona and Padua dental clinics prioritize real-time interoperability with regional health authority systems. Agenzia per l'Italia Digitale certification requirements force legacy system replacements. The Veneto dental software market exhibits the fastest cloud adoption velocity outside Lombardy.
Piedmont
Turin-based independent practitioners favor subscription pricing models bundling security updates with core functionality. GDPR Article 32 technical measures shape vendor selection criteria. The Turin-Biella axis shows emerging demand for hybrid deployment architectures balancing data localization with remote access.
Emilia-Romagna
Bologna dental partnerships require graduated permission structures for 2-5 location networks. Regional health authority reimbursement digitization rules reshape billing module requirements. The Emilia-Romagna corridor represents a scaling segment for group practice software vendors.
Lazio
Rome practitioners show rising interest in mobile-optimized interfaces for chair-side charting and patient communication. Connectivity infrastructure gaps constrain pure cloud adoption compared to northern benchmarks. The Rome metropolitan area exhibits strongest residual demand for on-premise solutions among major Italian cities.
Italy Dental Practice Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-assisted diagnostic modules and tele-dentistry channel development. Market structure consolidates around three archetypes: imaging-integrated workflow suite providers, modular platform specialists for independent practitioners, and hardware-software bundlers leveraging distribution networks. Dominant competitive moves include strategic partnerships with digital radiography manufacturers and geographic expansion into underpenetrated central-southern regions.
Within the imaging-integrated tier, Henry Schein and Carestream Dental exemplify contrasting approaches to market access. Henry Schein leverages its peninsula-wide distribution infrastructure to sustain hardware-software bundling relationships. Carestream Dental anchors its competitive position through workflow suites that embed diagnostic imaging capabilities. Dental Opera occupies a distinct specialization niche with modular architectures tailored to independent practitioner requirements.
| Leading Market Players |
|---|
| Henry Schein |
| Carestream Dental |
| Dental Opera |
| Dental Monitoring |
| AGE Solutions |
| Dentsply Sirona |
| CompuGroup Medical |
| CASTELLINI |
| Orisdent |
| Others |
Supply & Pricing Matrix
GDPR Article 32 technical measures gate both qualified supply and premium-tier pricing access in Italy's dental software market, as vendors must maintain EU-certified data infrastructure to serve Tessera Sanitaria-integrated clinics in Lombardy and Veneto. Compliance-certified platforms command subscription premiums while non-certified developers face exclusion from procurement pipelines funded by PNRR digitization incentives.
Pricing Analysis
Distributor margins in Henry Schein's peninsula-wide hardware-software bundling compress net pricing for integrated suites compared to standalone SaaS procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by Tessera Sanitaria interoperability depth and AI diagnostic module inclusion. Pricing pressure stems from subscription fatigue among Rome and Naples independent practitioners migrating from perpetual licenses. Single-practice operators in southern regions exhibit highest price sensitivity, while multi-practice networks in Milan prioritize interoperability over cost.
Supply Chain Analysis
Italy's National Recovery and Resilience Plan local-content preferences reshape sourcing toward EU-based cloud infrastructure providers and domestic integration specialists. Software development draws from Ireland, Germany, and Poland for GDPR-compliant data center capacity. Critical dependencies include digital radiography APIs from legacy imaging manufacturers, encryption modules certified under EU Medical Device Regulation, and real-time health authority connectivity protocols. Single-source vulnerability concentrates in proprietary imaging equipment integration. Distribution runs through Henry Schein's dental supply network and direct SaaS sales to clinic procurement officers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's dental software market represents a late-cycle quality story as multi-practice networks prioritize Tessera Sanitaria interoperability and AI-assisted diagnostic specifications over basic scheduling functionality. Premium-tier vendors capturing PNRR-funded procurement in northern regions are consolidating position while price-competitive entrants face margin compression.
For Market Incumbents: Acquire cloud-native development teams to accelerate feature delivery cycles below 90 days for multi-practice buyers. Consolidate position through exclusive imaging equipment API partnerships that lock out modular competitors from Carestream Dental and Dentsply Sirona install bases. Defensive certification investment in EU Medical Device Regulation Class IIa quality systems creates switching costs against emerging AI diagnostic entrants. For New Entrants and Emerging Players: AI-assisted radiographic analysis modules serve as a technology-first wedge into the orthodontic specialist segment where workflow complexity justifies premium pricing. White-space targets include Abruzzo and Molise group practices scaling from 2-5 locations without legacy system baggage. Tele-dentistry channel development aligned with regional health authority reimbursement protocols offers the most penetrable go-to-market angle for Rome-based independent practitioners. For Investors and Strategic Acquirers: Roll-up economics work for dental service organizations with 50+ locations because centralized procurement functions create vendor switching costs that entrench incumbent platforms. Long-term viability favors platforms with notified body relationships for EU Medical Device Regulation diagnostic AI classification. Acquisition target archetype: modular specialists with Tessera Sanitaria certification and southern Italy customer bases. Watch PNRR funding disbursement velocity as the inflection signal for procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Compresses implementation cycles from 18 months to 90 days for Lombardy multi-practice networks. |
| AI Diagnostic Module Development | Triggers EU Medical Device Regulation Class IIa certification requirements that smaller developers cannot satisfy. |
| Tessera Sanitaria Integration Partnership | Unlocks PNRR-funded procurement pipelines and differentiates vendors in Veneto regional health authority tenders. |
| Central-Southern Geographic Expansion | Captures first-mover advantage in Abruzzo, Molise, and Basilicata where software adoption trails northern benchmarks. |
| Subscription Pricing Model Transition | Extends customer lifetime value through automatic renewal mechanisms for Rome and Naples independent practitioners. |
Research Methodology
Multiple input streams — dental practice management software procurement databases, Agenzia per l'Italia Digitale certification registries, and PNRR healthcare digitization fund disbursement records — were reconciled through bottom-up and top-down triangulation. Primary interviews with dental clinic IT directors, regional health authority procurement officers, GPO contracts managers, and biomedical engineers validated functional requirements and pricing benchmarks. Secondary sources included SEC filings from listed dental supply distributors, EU Medical Device Regulation notified body certification databases, and Lombardy-Veneto regional health system integration specifications.
Data-stream reconciliation across deployment model, practice scale, software feature set, and regional adoption pattern dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from installed base growth trajectories and replacement cycle compression in cloud-native segments. Forecast inputs incorporated PNRR funding allocation schedules, broadband infrastructure rollout timelines in Sicily and Calabria, and evolving GDPR enforcement patterns from Italy's data protection authority.
The model holds under continued PNRR healthcare digitization disbursement and stable GDPR enforcement intensity; deviation in regional connectivity infrastructure investment or EU Medical Device Regulation diagnostic AI reclassification would shift vendor competitive positioning and procurement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Femtech Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Metabolic Rate Analysis System Market