
 Converged Cable Access Platform (CCAP) Market | 2026-2036
Converged Cable Access Platform (CCAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Converged Cable Access Platform (CCAP) Market Outlook
Market Context
Cable operator procurement is tilting toward converged architectures that collapse edge routing and CMTS functions into unified platforms. CommScope leverages its broadband access portfolio to sustain leadership in integrated chassis solutions for tier-one operators. Cisco Systems anchors enterprise relationships through software-defined extensions that bridge legacy QAM and IP video domains. Casa Systems competes with compact, power-optimized designs targeting mid-size operators and emerging markets.
Technical Definition and Segment Structure
A Converged Cable Access Platform combines cable modem termination system functionality with edge QAM video processing in a single hardware or virtualized chassis, typically supporting downstream capacities exceeding 10 Gbps per port to enable unified broadband and video service delivery. Modular CCAP dominates capital expenditure among incumbent operators upgrading node-by-node, while Remote PHY Devices represent the fastest-growing product category as operators disaggregate MAC and PHY layers to push optics deeper into access networks. DOCSIS 3.1 technology commands the largest installed base, though Full Duplex DOCSIS attracts disproportionate R&D investment for its symmetric gigabit potential.
Regulatory Environment
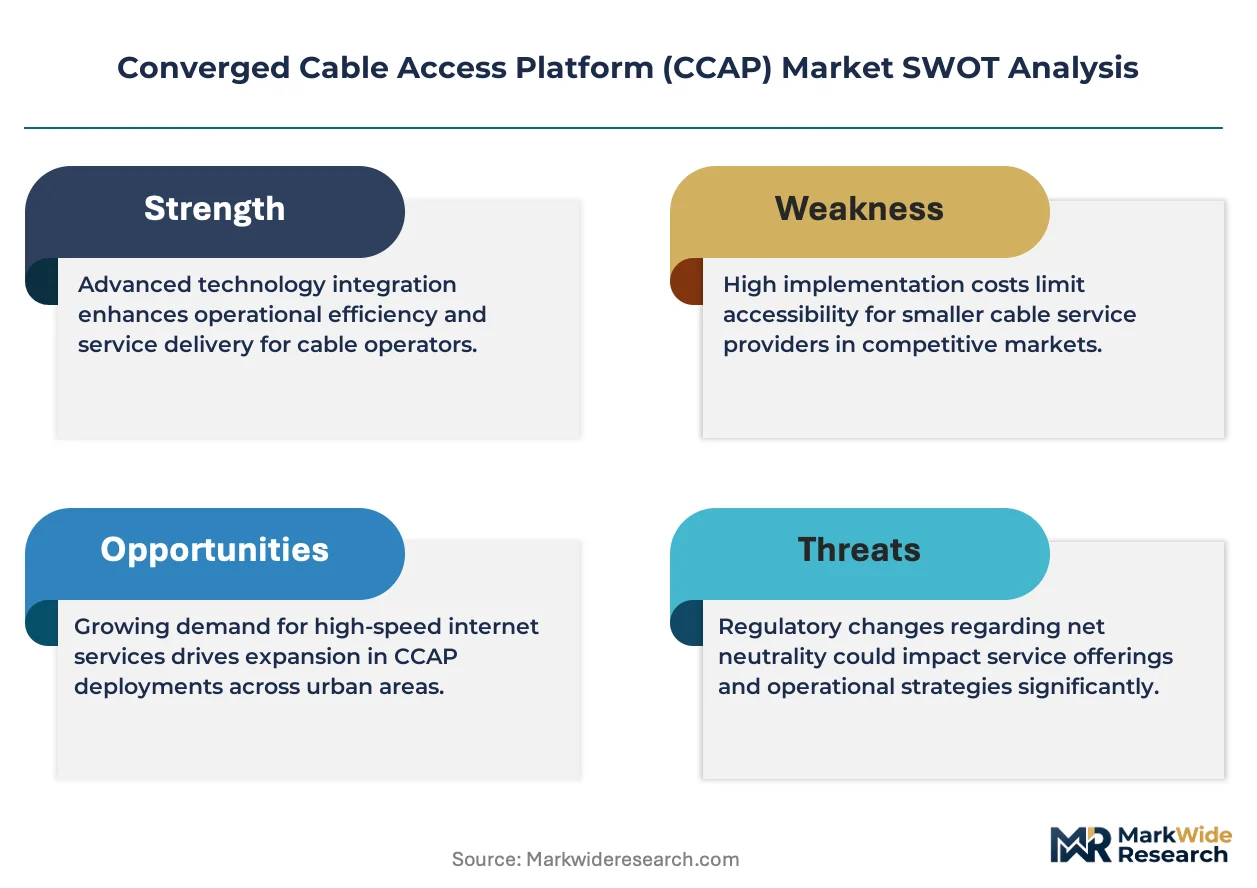
FCC broadband deployment mandates and EU Green Deal energy-efficiency standards shape equipment certification requirements on both sides of the Atlantic. ETSI interoperability frameworks and CableLabs DOCSIS specifications govern product compliance, creating barrier-to-entry effects for non-certified vendors. Stakeholders must monitor spectrum reallocation proceedings and emerging net-neutrality rulings that could alter traffic-management feature requirements in next-generation platform designs.
Market Dynamics
DOCSIS 3.1 migration is compressing hardware refresh cycles as cable operators dismantle siloed CMTS and edge-QAM infrastructures in favor of unified chassis architectures that collapse video and broadband delivery into single platforms.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:The regulation compels European operators to replace legacy power-hungry chassis with converged platforms that cut energy consumption per subscriber served.
- Remote PHY disaggregation:This architecture pushes optics deeper into access networks, enabling fiber-deep topologies that extend gigabit service reach without full fiber-to-the-home overbuilds.
- Mid-size operator densification:Regional cable providers across Brazil and Mexico are accelerating CCAP procurement to compete with fiber entrants and mobile fixed-wireless offerings.
Market Restraints
- GaN-on-SiC substrate supply concentration:High-frequency power amplifier substrates depend on a concentrated supply base in East Asia, creating input cost volatility for Remote PHY device manufacturers.
- CableLabs certification timelines:The interoperability testing framework imposes 12-18 month validation cycles that delay vendor market entry and compress first-mover windows.
- Passive optical network substitution:Municipal fiber overbuilds and utility fiber deployments in Germany and the Netherlands threaten CCAP addressable market in greenfield developments.
Strategic Opportunities
- Virtualized CCAP (vCCAP) software licensing:Containerized MAC cores running on merchant silicon create recurring revenue streams distinct from chassis hardware sales.
- India's BharatNet rural broadband mandate:The government subsidy program for rural connectivity creates demand for cost-optimized, thermally hardened Remote PHY nodes.
- Full Duplex DOCSIS convergence:Symmetric gigabit capability positions cable operators to compete directly with fiber for enterprise and teleworker segments previously ceded to PON.
Industry Challenges
- Distributed access architecture (DAA) skill scarcity:Network engineering teams lack expertise in IP/MPLS transport and timing synchronization for Remote PHY deployments, forcing expensive contractor reliance or training cycles.
- Legacy backoffice integration:Billing and provisioning systems built for DOCSIS 3.0 require middleware development to support DAA's SNMP and YANG data models, extending deployment timelines.
Report Scope
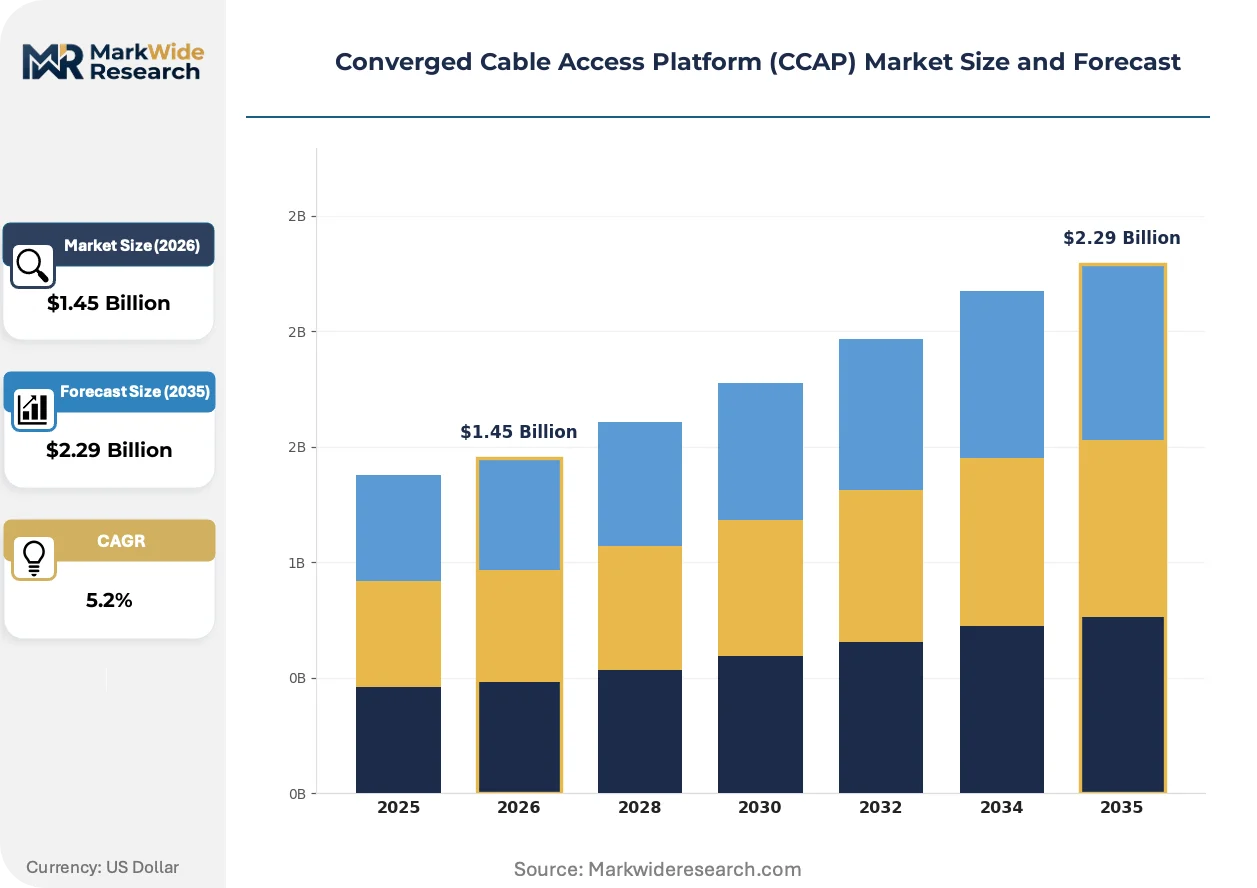
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converged Cable Access Platform (CCAP) Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular CCAP, Integrated CCAP, Remote PHY Devices, Converged RPD, Digital Edge QAM Technology: DOCSIS 3.0, DOCSIS 3.1, Full Duplex DOCSIS, Remote MACPHY, Fiber Deep Application: Video Broadcasting, Broadband Internet, VoIP Services, IPTV, Data Services End User: Telecom Operators, Content Providers, System Integrators, Network Equipment Vendors |
| Companies Covered | CommScope, Cisco Systems, Casa Systems, Harmonic, Nokia, Huawei Technologies, Broadcom, Juniper Networks, Vecima Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converged Cable Access Platform (CCAP) Market Strategic Shifts
Software-defined disaggregation is fragmenting the traditional integrated chassis market, with functionality migrating from centralized hardware to distributed software components running on commodity compute.
Remote MAC-PHY architectures separate the MAC layer from physical layer functions, enabling cable operators to push intelligence to the network edge while centralizing processing. Tier-one operators in the United States and Canada are deploying these architectures at node-plus-zero topologies. This topology shift is rendering obsolete the centralized CMTS chassis that dominated cable headends for two decades.
The FCC's updated broadband deployment reporting requirements now mandate granular location-level coverage data, forcing equipment vendors to embed geolocation telemetry directly into CCAP platforms. This regulatory pressure accelerates software development cycles and creates compliance differentiation among vendors. Operators serving rural census blocks face the steepest certification burdens as they must demonstrate service availability at the address level.
Service providers are consolidating vendor relationships around integrated platform suppliers capable of delivering chassis, optics, and professional services through single master agreements. This consolidation displaces the multi-vendor procurement patterns that characterized earlier DOCSIS generations. The shift is most pronounced among mid-size North American operators seeking to reduce integration risk and simplify sparing strategies.
Converged Cable Access Platform (CCAP) Market Segmentation
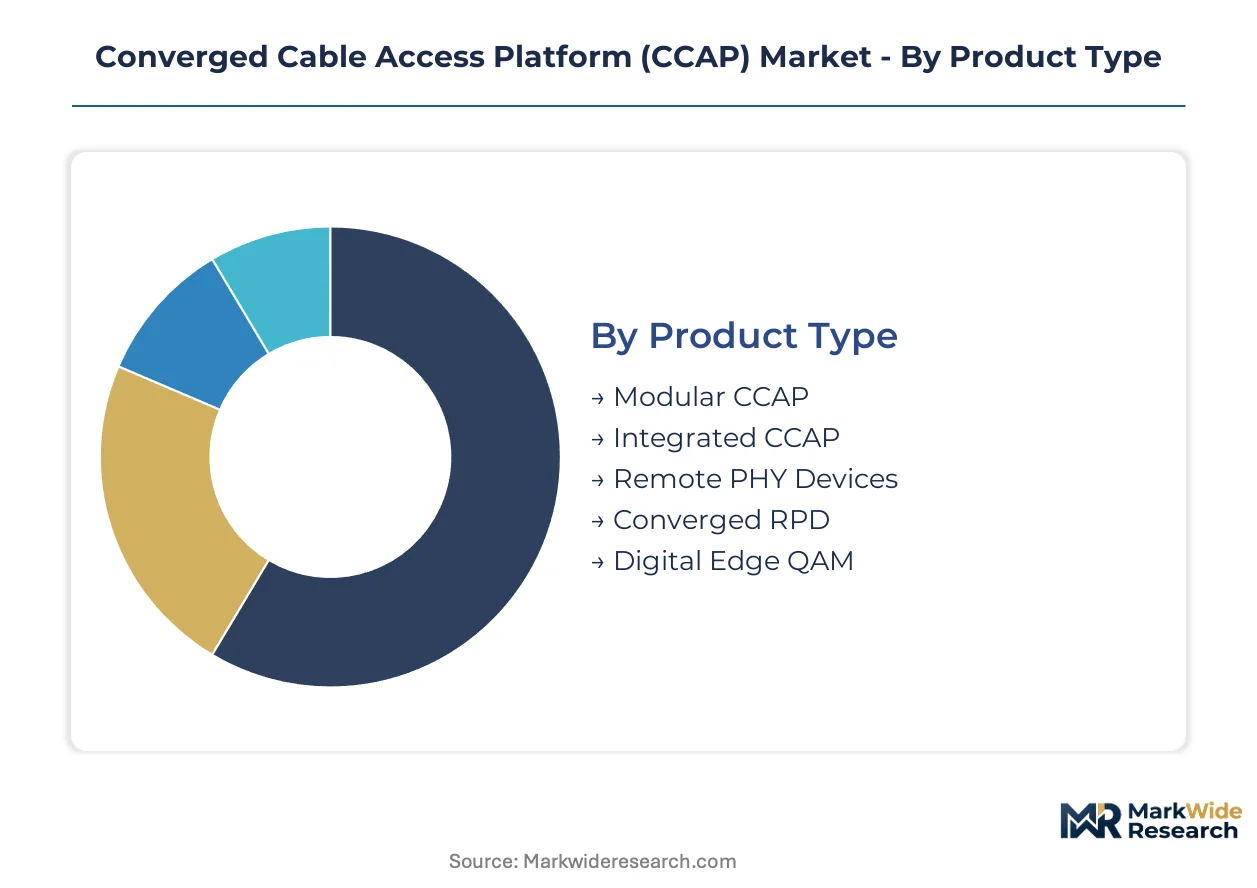
CCAP procurement patterns diverge sharply across deployment scales and technology readiness, with tier-one operators favoring disaggregated architectures while regional providers prioritize integrated chassis for faster time-to-market. Understanding these segment boundaries clarifies where vendor R&D investments concentrate and which equipment categories face substitution risk from fiber alternatives.
Product Type:
Mature integrated chassis designs coexist with emerging disaggregated form factors as operators navigate divergent upgrade timelines and fiber-deep strategies.
- Modular CCAP:Hot-swappable line cards in centralized chassis configurations support incremental capacity expansion without full system replacement. Demand concentrates among incumbent United States operators upgrading node-by-node in suburban markets where stranded CMTS assets still carry depreciation.
- Remote PHY Devices:Disaggregated optics modules push physical layer functions to the network edge, collapsing headend real estate requirements. Operators in Canada and Germany deploy these devices at node-plus-zero topologies to extend gigabit reach without full fiber-to-the-home overbuilds, though GaN-on-SiC substrate supply constraints periodically disrupt procurement schedules.
- Integrated CCAP:Single-chassis platforms combining CMTS and edge QAM for smaller headends.
- Converged RPD:Unified remote devices supporting both video and data PHY processing.
- Digital Edge QAM:Legacy video modulation platforms transitioning toward IP convergence.
Modular CCAP retains volume leadership among depreciation-constrained operators; Remote PHY Devices hold the steepest expansion curve as fiber-deep architectures gain operational validation.
Technology:
Cost tier separation distinguishes mature broadband standards from emerging symmetric-capability specifications still absorbing heavy R&D investment.
- DOCSIS 3.1:Orthogonal frequency-division multiplexing enables downstream capacities exceeding 10 Gbps with 4096-QAM modulation. Cable operators across the United States and Brazil have standardized procurement on this technology for residential gigabit tiers, though equipment refresh cycles compress as Full Duplex capabilities mature.
- Full Duplex DOCSIS:Simultaneous upstream and downstream spectrum utilization delivers symmetric gigabit throughput previously exclusive to fiber. Enterprise and teleworker segments in Germany and the Netherlands drive pilot deployments as cable operators seek to recapture customers lost to municipal fiber overbuilds.
- DOCSIS 3.0:Legacy 32×8 channel bonding standard approaching end-of-life in developed markets.
- Remote MACPHY:Distributed architecture separating MAC processing from physical layer functions at the node.
- Fiber Deep:Topology strategy pushing optical distribution closer to subscriber premises.
DOCSIS 3.1 dominates current capital expenditure; Full Duplex DOCSIS is gaining share fastest among operators targeting enterprise substitution of fiber.
Application:
Customer type fragmentation separates high-margin converged service bundles from single-purpose infrastructure deployments.
- Broadband Internet:High-speed data delivery represents the primary revenue justification for CCAP platform investment. Tier-one operators in the United States report that broadband ARPU growth funds node-splitting and Remote PHY migration programs that video revenue alone cannot support.
- Video Broadcasting:Linear QAM video processing consolidates onto converged platforms as operators dismantle standalone edge-QAM silos. Content providers in Brazil and Mexico maintain demand for broadcast-capable chassis as they negotiate retransmission agreements with regional sports networks.
- VoIP Services:Voice-over-IP termination on converged cable infrastructure.
- IPTV:Packetized video delivery replacing traditional broadcast QAM.
- Data Services:Business Ethernet and backhaul transport over DOCSIS.
Broadband Internet anchors platform procurement volume; Video Broadcasting is expanding most quickly in Latin American markets where linear television retains subscriber loyalty.
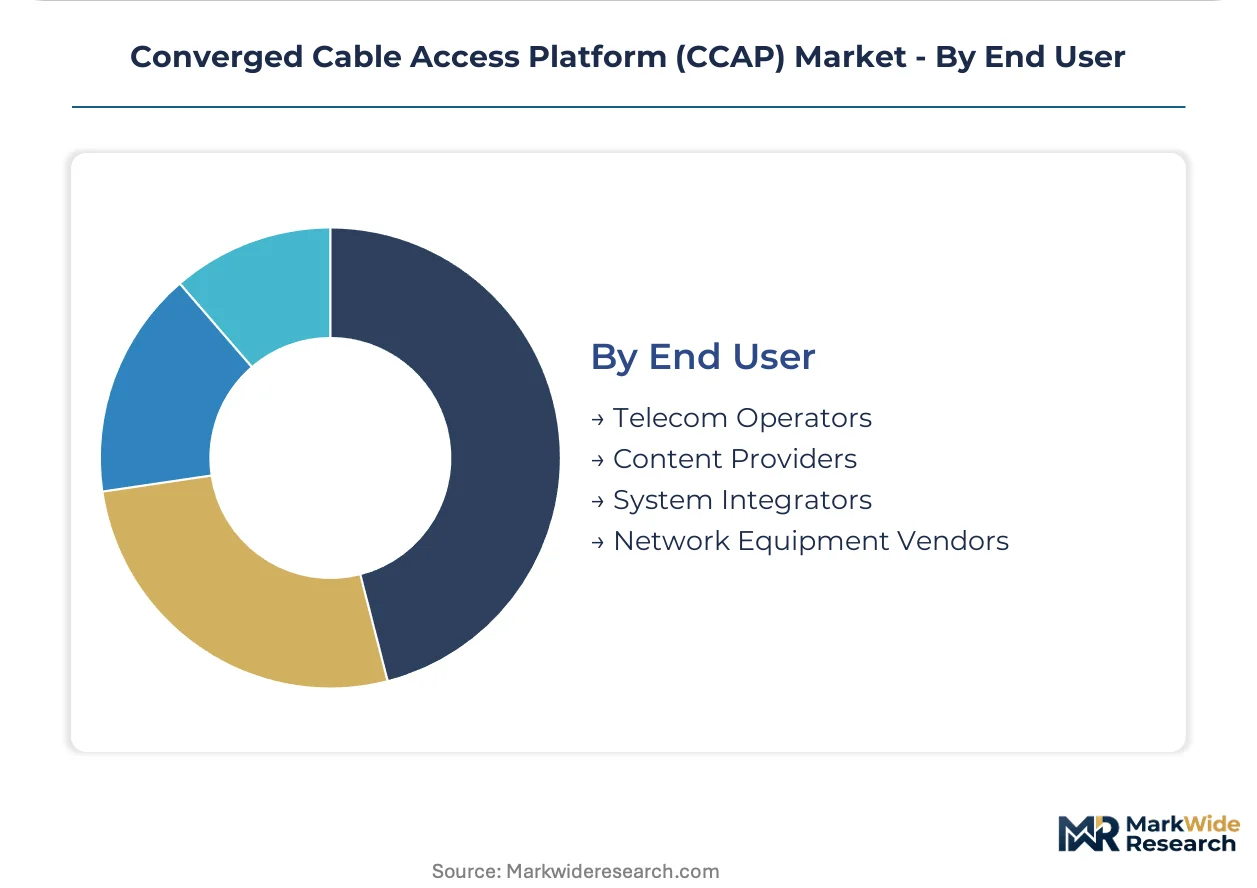
End User:
Supply concentration characterizes procurement patterns among vertically integrated operators versus fragmented demand from systems integrators serving heterogeneous network estates.
- Telecom Operators:Cable multiple-system operators and converged telcos constitute the dominant equipment purchasers. United States operators including Comcast and Charter Communications negotiate multi-year master agreements that consolidate chassis, optics, and professional services under single-vendor relationships.
- System Integrators:Third-party deployment specialists address skill scarcity in Remote PHY and DAA architectures. Mid-size operators in India and Brazil rely on these integrators to supplement internal engineering teams lacking IP/MPLS transport and timing synchronization expertise.
- Content Providers:Broadcasters and streaming platforms procuring edge capacity.
- Network Equipment Vendors:OEMs sourcing subsystems for branded platform integration.
Telecom Operators command procurement volume leadership; System Integrators are climbing the fastest as distributed access architectures expose internal capability gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC broadband deployment mandates anchor procurement intensity in the United States, while EU Green Deal energy-efficiency standards and India's BharatNet rural subsidy program shape divergent regional equipment specifications and certification timelines.
United States
Comcast and Charter Communications drive node-splitting programs to extend gigabit service reach in suburban markets. FCC reporting requirements now mandate granular location-level coverage data, forcing geolocation telemetry integration into platform designs. Atlanta and Denver anchor Remote PHY deployment clusters where tier-one operators validate fiber-deep topologies.
Germany
Vodafone Deutschland and regional cable operators pursue Full Duplex DOCSIS pilots to recapture enterprise customers from municipal fiber overbuilds. EU Green Deal energy-efficiency mandates compel chassis replacement cycles that cut power consumption per subscriber. The Cologne-Düsseldorf corridor concentrates R&D validation for symmetric gigabit architectures.
Brazil
Regional cable providers accelerate procurement to compete with fiber entrants and mobile fixed-wireless offerings in São Paulo and Rio de Janeiro. ANVISA equipment certification frameworks govern import compliance for converged platforms. The São Paulo metropolitan area anchors Latin America's largest CCAP deployment cluster for broadcast-capable chassis.
India
The BharatNet rural broadband mandate creates demand for cost-optimized, thermally hardened Remote PHY nodes in underserved districts. TRAI spectrum allocation proceedings influence equipment feature requirements for traffic management. Karnataka and Maharashtra host the primary systems integrator clusters addressing skill scarcity in distributed access architectures.
Canada
Rogers Communications and Shaw Communications deploy Remote PHY Devices at node-plus-zero topologies to collapse headend real estate requirements. Health Canada equipment certification aligns with FCC interoperability frameworks for cross-border vendor qualification. The Toronto-Ottawa corridor anchors validation programs for disaggregated MAC-PHY architectures.
Converged Cable Access Platform (CCAP) Market Competitive Environment
Integrated chassis specialists and disaggregated software vendors split the market between depreciation-constrained incremental upgrades and greenfield fiber-deep deployments. The vendor base concentrates around three strategic archetypes: diversified telecommunications equipment conglomerates, pure-play broadband access specialists, and semiconductor subsystem suppliers. Consolidation through multi-year master agreements and vertical integration into optical component sourcing represent the dominant competitive moves reshaping procurement relationships.
Within the diversified equipment tier, CommScope and Cisco Systems exemplify integrated platform suppliers capable of delivering chassis, optics, and professional services through single master agreements. Casa Systems occupies a position among compact, power-optimized design specialists targeting mid-size operators and emerging markets with faster time-to-market requirements.
| Leading Market Players |
|---|
| CommScope |
| Cisco Systems |
| Casa Systems |
| Harmonic |
| Nokia |
| Huawei Technologies |
| Broadcom |
| Juniper Networks |
| Vecima Networks |
| Others |
Value Chain & Pricing Dynamics
GaN-on-SiC substrate fabrication concentrates in East Asian foundries, anchoring margin pools with Remote PHY device manufacturers who pass through input volatility to cable operators locked into multi-year fiber-deep deployment schedules. Equipment vendors with captive substrate sourcing or long-term offtake agreements capture pricing power as supply constraints periodically disrupt procurement timelines for disaggregated optics modules.
Pricing Analysis
North American chassis procurement commands 15-25% premiums over equivalent Latin American contracts due to CableLabs certification requirements and embedded professional services bundles. Three-tier pricing structure across premium, standard, and economy levels separates tier-one operators with master agreements from mid-size providers purchasing through systems integrators and emerging-market buyers procuring thermally hardened nodes. Pricing pressure stems from municipal fiber substitution in Germany and the Netherlands, where cable operators compress equipment margins to defend residential subscriber bases. Regional operators in Brazil and Mexico exhibit highest price sensitivity, while United States tier-one operators prioritize single-vendor relationships and integration risk reduction over unit cost minimization.
Supply Chain Analysis
Export control regimes restricting high-frequency semiconductor manufacturing equipment to Chinese fabs have concentrated GaN-on-SiC substrate supply among Taiwanese, Japanese, and South Korean suppliers, creating single-source vulnerability for Remote PHY amplifier modules. CCAP chassis assembly draws from Mexican and Malaysian contract manufacturing for integrated platforms, while optical component sourcing rests on German and Danish laser diode specialists. Tariff exposure runs through legacy CMTS chassis imported from Chinese production facilities. Distribution runs through direct master agreements with tier-one operators and systems integrator channels addressing skill scarcity in mid-size and emerging-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CCAP adoption sits in early-cycle expansion as fiber-deep architectures validate operational economics and Remote PHY deployments accelerate beyond pilot phases. Full Duplex DOCSIS R&D investment and vCCAP software licensing create recurring revenue streams distinct from hardware refresh cycles.
For Market Incumbents: Harden supply chain resilience through backward integration into GaN-on-SiC substrate sourcing or long-term offtake agreements with East Asian foundries. Consolidate vendor relationships around integrated platform suppliers capable of delivering chassis, optics, and professional services through single master agreements to reduce integration risk and simplify sparing strategies for tier-one operators.
For New Entrants and Emerging Players: Build out compact, power-optimized designs targeting India's BharatNet rural broadband mandate and Latin American mid-size operators seeking faster time-to-market than tier-one integrated chassis procurement cycles permit. White-space concentrates in thermally hardened Remote PHY nodes for underserved districts and cost-optimized vCCAP software licensing for operators with merchant silicon infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed broadband access specialists holding strong CableLabs certification pipelines but limited geographic diversification. Long-term viability frames around 5-10 year fiber-deep deployment windows as cable operators extend gigabit service reach without full fiber-to-the-home overbuilds. Watch Full Duplex DOCSIS pilot conversion rates in Germany and the Netherlands as inflection indicators for symmetric gigabit enterprise market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Remote PHY Device Certification | CableLabs validation compresses vendor entry timelines and consolidates procurement around pre-qualified suppliers. |
| GaN-on-SiC Supply Agreement | Long-term substrate offtakes insulate Remote PHY margins from East Asian foundry concentration volatility. |
| vCCAP Software Licensing | Containerized MAC cores on merchant silicon create recurring revenue streams distinct from chassis hardware cycles. |
| Systems Integrator Partnership | Channel relationships address DAA skill scarcity among mid-size operators lacking IP/MPLS transport expertise. |
| Full Duplex DOCSIS R&D Investment | Symmetric gigabit capability positions cable operators to recapture enterprise customers from municipal fiber overbuilds. |
Study Parameters
Initial hypotheses were tested against primary input from cable operator network engineering directors, equipment procurement managers, systems integrator deployment specialists, and semiconductor component sourcing leads and refined through secondary validation against CableLabs DOCSIS specifications, FCC broadband deployment reports, ETSI interoperability frameworks, SEC 10-K filings of publicly traded equipment vendors, and customs trade data for GaN-on-SiC substrate flows. Bottom-up equipment shipment modeling triangulated against top-down operator capex disclosure analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including product type architecture, DOCSIS technology generation, application service bundle, and end-user procurement scale. CAGRs derived from equipment replacement cycle analysis, fiber-deep deployment pace assumptions, and technology migration curves. Industry-specific forecast inputs incorporated Remote PHY adoption rates and vCCAP software penetration assumptions.
Sensitivities concentrate around GaN-on-SiC substrate supply disruptions, CableLabs certification timeline extensions, and municipal fiber substitution acceleration in European markets. Forecasts reflect documented assumptions regarding operator upgrade schedules and technology standardization timelines. Material shifts in export control regimes, spectrum reallocation proceedings, or net-neutrality rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Data Center Switches Market
Network Technology
Network Telemetry Market
Network Technology
Open RAN Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Self-Healing Networks Market
Network Technology
Passive Optical Network Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Fiber to the Premises Market
Network Technology
CPE Router Market
Network Technology
Global Internet Transit Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global 5G Smart Antenna Market