
 Global Intrapartum Monitoring Devices Market | 2026-2036
Global Intrapartum Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intrapartum Monitoring Devices Market Foresight
Asset-light leasing models for multiparameter monitor fleets is rewriting competitive entry barriers for mid-tier birthing centers. Koninklijke Philips N.V. leverages its installed base in North American hospital systems to sustain service contract renewals. Medtronic PLC anchors its position through deep integration of maternal hemodynamic sensors with existing critical care platforms. GE Healthcare differentiates via manufacturing scale that controls per-unit costs across wireless telemetry production lines.
Intrapartum monitoring devices comprise electronic systems that track fetal heart rate, uterine contraction frequency, and maternal vital signs during labor, typically operating at 1-30 Hz signal acquisition with ultrasonic transducers or tocodynamometer pressure sensors. Their primary purpose is to detect fetal distress patterns and guide obstetric intervention timing. Fetal monitors occupy the largest revenue pool given their ubiquity in hospital labor wards, while wireless monitoring represents the fastest-expanding technology segment as facilities prioritize maternal mobility during active labor. Telemetry systems command premium positioning where real-time remote data transmission to nursing stations reduces staffing ratios without compromising surveillance.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) establish divergent compliance pathways that fragment product development roadmaps for manufacturers serving both jurisdictions. ISO 13485 quality management standards further shape supplier qualification criteria for hospital procurement committees across Germany, Japan, and Australia. Stakeholders must weigh regulatory divergence against the cost of maintaining parallel technical files when selecting market entry sequencing.
Market Dynamics
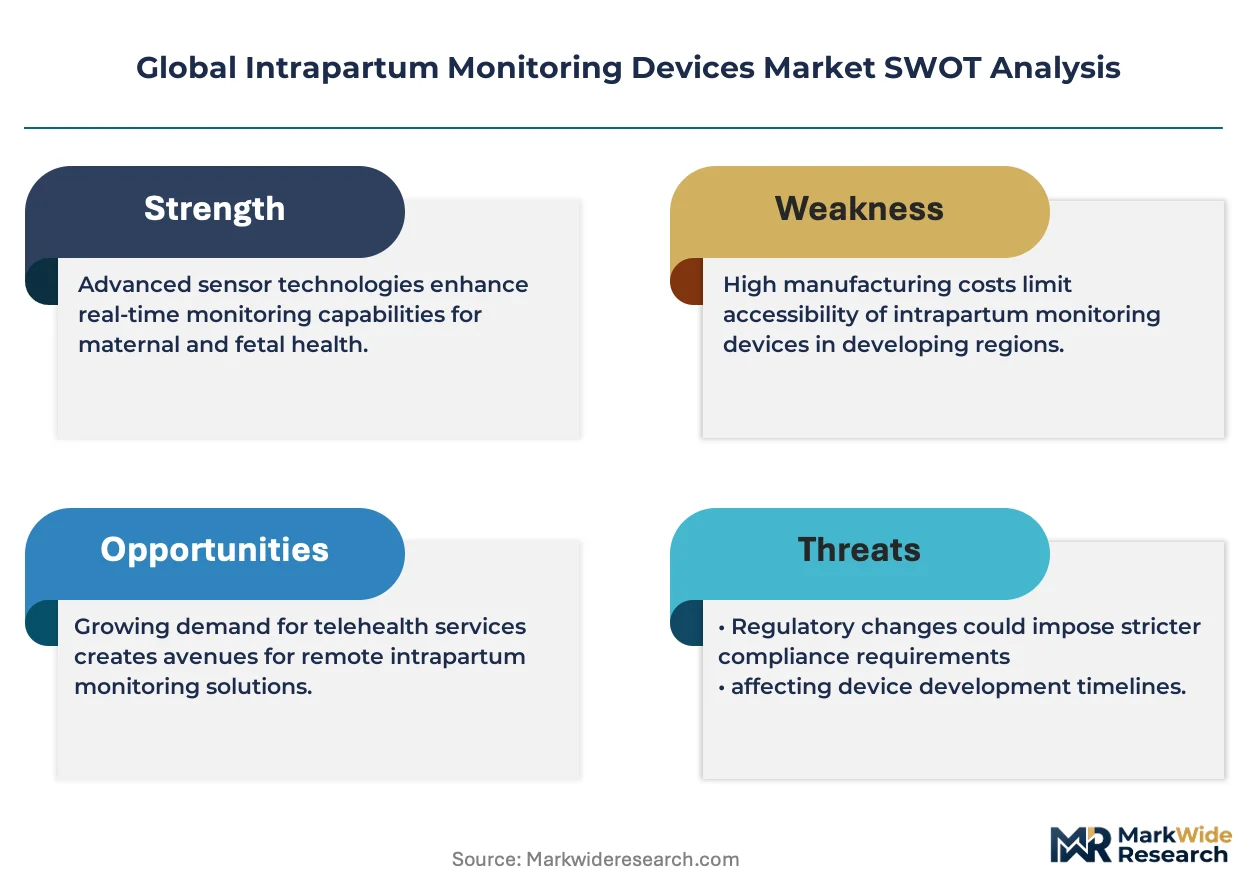
Wireless telemetry systems are compressing capital deployment cycles for birthing centers while FDA 510(k) clearance requirements force smaller manufacturers into costly regulatory partnerships with established device firms.
Growth Catalysts
- MDR compliance deadlines in Germany:Hospital procurement committees now mandate ISO 13485 certification for all new maternal monitor suppliers, elevating quality thresholds and locking out uncertified vendors.
- Ultrasonic transducer miniaturization:Smaller form factors enable ambulatory monitoring during active labor, expanding addressable demand beyond traditional bed-bound configurations.
- Consolidated US health system purchasing:Bulk procurement of integrated monitoring platforms by merged hospital networks concentrates order volumes with vendors offering full-platform solutions.
Market Restraints
- Piezoelectric sensor supply concentration:Japanese and German component specialists control 70% of high-precision pressure sensor output, exposing manufacturers to input bottlenecks.
- FDA 510(k) pathway friction:Predicate device requirements for fetal monitors create multi-year approval timelines that deter novel signal processing architectures.
- Disposable electrode cost volatility:Silver chloride prices fluctuate with precious metals markets, compressing margins on consumable-heavy monitoring systems.
Strategic Opportunities
- India's expanding tertiary maternity infrastructure:Government hospital upgrades in Maharashtra and Tamil Nadu create first-time demand for wireless telemetry in public sector wards.
- AI-enhanced cardiotocography pattern recognition:Machine learning integration with existing Doppler ultrasound hardware offers differentiation without full device replacement.
- Direct-to-facility leasing channels:Mid-tier birthing centers in Australia bypass distributor markups through manufacturer-managed equipment-as-a-service arrangements.
Industry Challenges
- Biomedical signal processing expertise scarcity:Fetal heart rate variability analysis requires specialized engineering talent concentrated in Boston and Zurich medical device clusters.
- Legacy wired infrastructure integration:Hospital IT departments face technical debt when retrofitting nursing station software to accept wireless telemetry data streams.
- CE-MDR technical documentation burden:Clinical evidence requirements for Class IIa maternal monitors strain regulatory affairs teams at mid-size manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intrapartum Monitoring Devices Market |
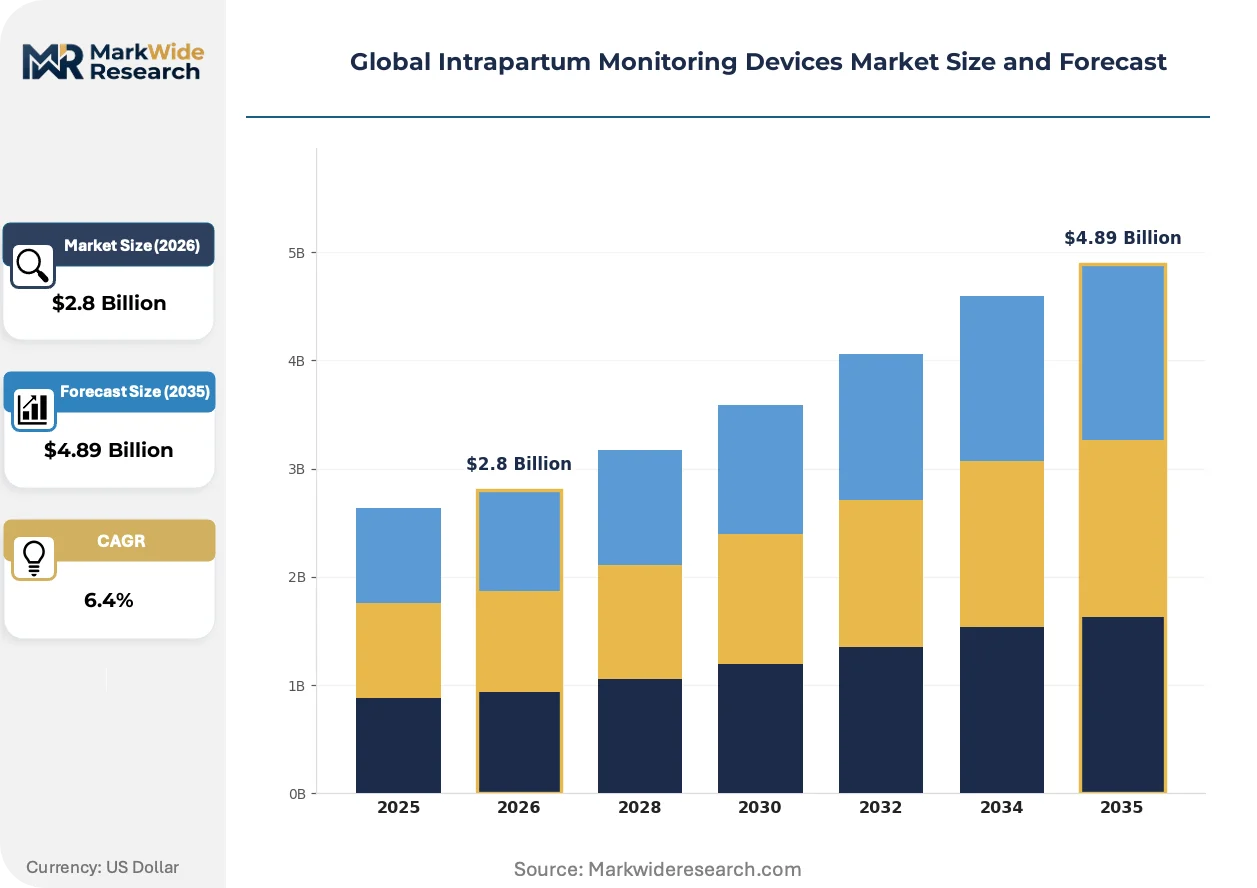
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fetal Monitors, Uterine Monitors, Maternal Monitors, Multiparameter Monitors Technology: Electronic Fetal Monitoring, Doppler Ultrasound, Electrocardiography, Telemetry Systems, Wireless Monitoring Application: Labor & Delivery Units, Maternity Clinics, Ambulatory Care, Home Care End User: Hospitals, Birthing Centers, Obstetrician Clinics, Midwifery Services |
| Companies Covered | Koninklijke Philips N.V., Medtronic PLC, Cardinal Health, GE Healthcare, The Cooper Companies, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Natus Medical Incorporated, Huntleigh Healthcare Limited, Analogic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intrapartum Monitoring Devices Market Shifts & Advancements
Patch-based fetal ECG monitors are eliminating belt-and-transducer setups while cloud-native data architectures enable real-time remote specialist consultation during high-risk deliveries.
Non-invasive fetal electrocardiography using abdominal patch arrays captures direct cardiac electrical signals rather than processed ultrasound Doppler shifts. Academic medical centers in Sweden and the Netherlands are piloting these systems for gestational diabetes cohorts where continuous monitoring improves glycemic-labor correlation. Direct ECG acquisition is rendering obsolete the signal artifact problems that plague ultrasonic methods during maternal movement.
The EU Medical Device Regulation's 2024-2025 transition deadlines force manufacturers to resubmit technical files for existing fetal monitor portfolios. German notified bodies are prioritizing reviews for devices with post-market clinical follow-up protocols already established. MDR compliance costs are compressing R&D budgets at European mid-tier firms, accelerating partnership discussions with US-based telemetry specialists.
Hospital procurement committees now unbundle hardware acquisition from service contracts, negotiating multi-vendor maintenance agreements separately from device purchases. This disintermediation pressures original equipment manufacturers to defend recurring revenue through proprietary sensor compatibility rather than captive servicing. The shift is most visible in California and Texas health systems where consolidated purchasing groups publish transparent total-cost-of-ownership scorecards.
Global Intrapartum Monitoring Devices Market Segmentation
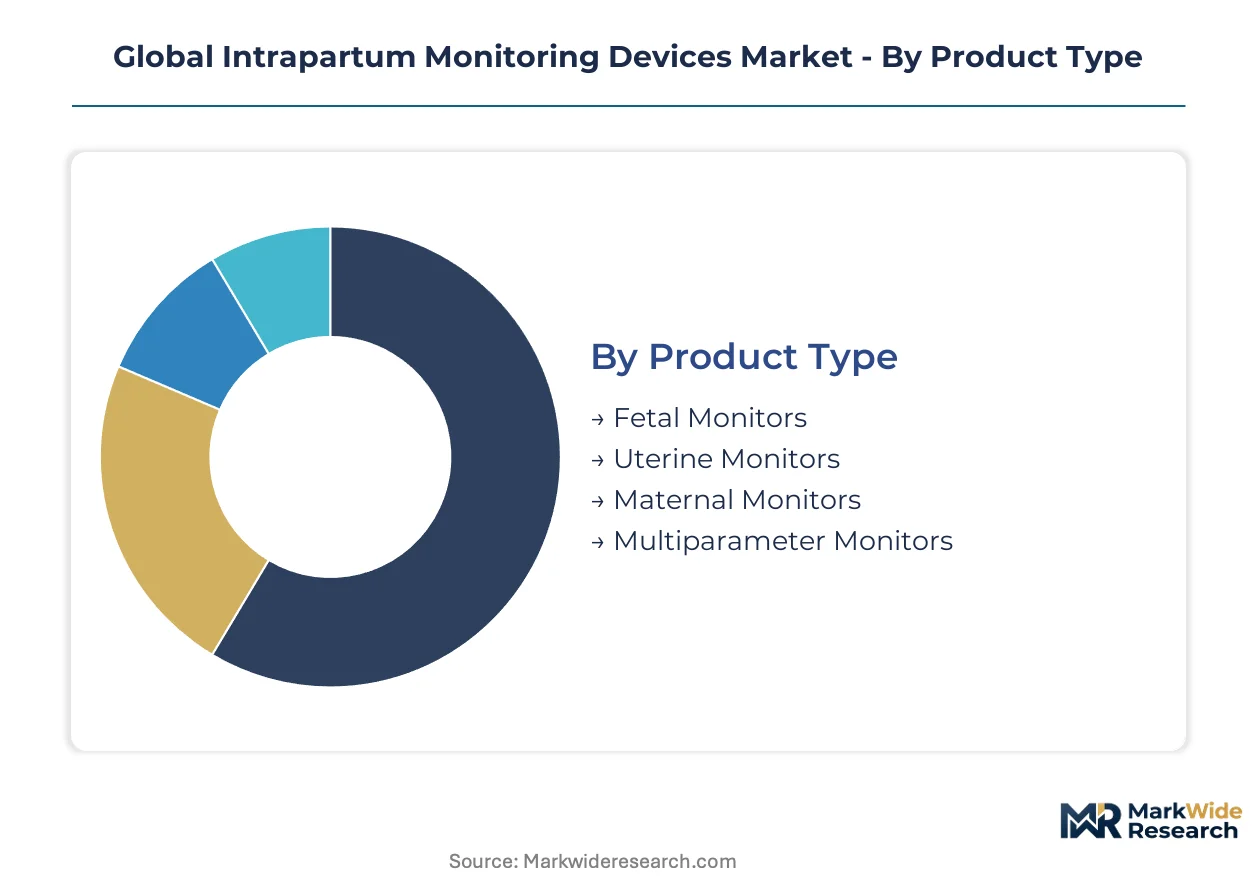
Intrapartum monitoring devices fragment across four distinct taxonomies that determine procurement patterns and technology roadmaps. Product type and technology dimensions dominate capital allocation decisions, while application and end-user categories shape regional go-to-market strategies.
Product Type:
Mature hardware platforms anchor hospital procurement budgets while emerging multiparameter configurations capture birthing center expansion cycles.
- Fetal Monitors:Electronic systems acquire fetal heart rate via ultrasonic transducers or scalp electrodes at 1-30 Hz sampling rates. United States hospital labor wards concentrate replacement demand as health system consolidation drives bulk purchasing of integrated platforms.
- Uterine Monitors:Tocodynamometer pressure sensors measure contraction frequency and intensity through strain gauge or piezoelectric transduction. German maternity units prioritize ISO 13485-certified devices under MDR compliance deadlines, elevating quality thresholds for new suppliers.
- Maternal Monitors:Track maternal vital signs including blood pressure, pulse oximetry, and temperature during active labor.
- Multiparameter Monitors:Consolidate fetal, uterine, and maternal parameters into single-platform architectures. These units are gaining share fastest in Australia's mid-tier birthing centers through manufacturer-managed leasing arrangements.
Fetal monitors handle the majority of throughput; multiparameter monitors are expanding most quickly on share.
Technology:
Cost tiers separate legacy electronic platforms from premium wireless architectures that command service contract premiums.
- Electronic Fetal Monitoring:Cardiotocography systems process Doppler ultrasound signals into paper or digital trace outputs. Japanese and German component specialists control sensor supply, exposing manufacturers to input bottlenecks.
- Doppler Ultrasound:Continuous wave or pulsed-wave systems operating at 1-2 MHz detect fetal heart motion through maternal abdominal wall. India's Maharashtra and Tamil Nadu public hospital upgrades create first-time demand for these platforms in tertiary maternity wards.
- Electrocardiography:Direct fetal ECG acquisition via scalp electrodes or abdominal patch arrays eliminates ultrasonic signal artifacts during maternal movement.
- Telemetry Systems:Enable real-time remote data transmission to nursing stations, reducing staffing ratios without compromising surveillance coverage.
- Wireless Monitoring:Bluetooth or proprietary RF protocols transmit physiological data without tethering patients to bedside units. This segment climbs the fastest as facilities prioritize maternal mobility during active labor.
Electronic fetal monitoring dominates installed base volume; wireless monitoring shows the steepest expansion trajectory.
Application:
Customer type stratification separates high-acuity hospital environments from distributed outpatient and residential settings.
- Labor & Delivery Units:Hospital-based acute care environments requiring continuous surveillance during active labor and delivery. FDA 510(k) clearance requirements enforce predicate device standards that prolong approval timelines for novel architectures.
- Maternity Clinics:Outpatient facilities providing prenatal and limited intrapartum services. Sweden and the Netherlands academic medical centers pilot patch-based fetal ECG systems for gestational diabetes cohorts.
- Ambulatory Care:Mobile or walk-in settings supporting low-risk deliveries without overnight admission.
- Home Care:Residential monitoring for planned home births or high-risk pregnancy surveillance. California and Texas health systems experiment with cloud-native architectures enabling remote specialist consultation.
Labor and delivery units absorb the bulk of capital deployment; home care is gaining share fastest among alternative settings.
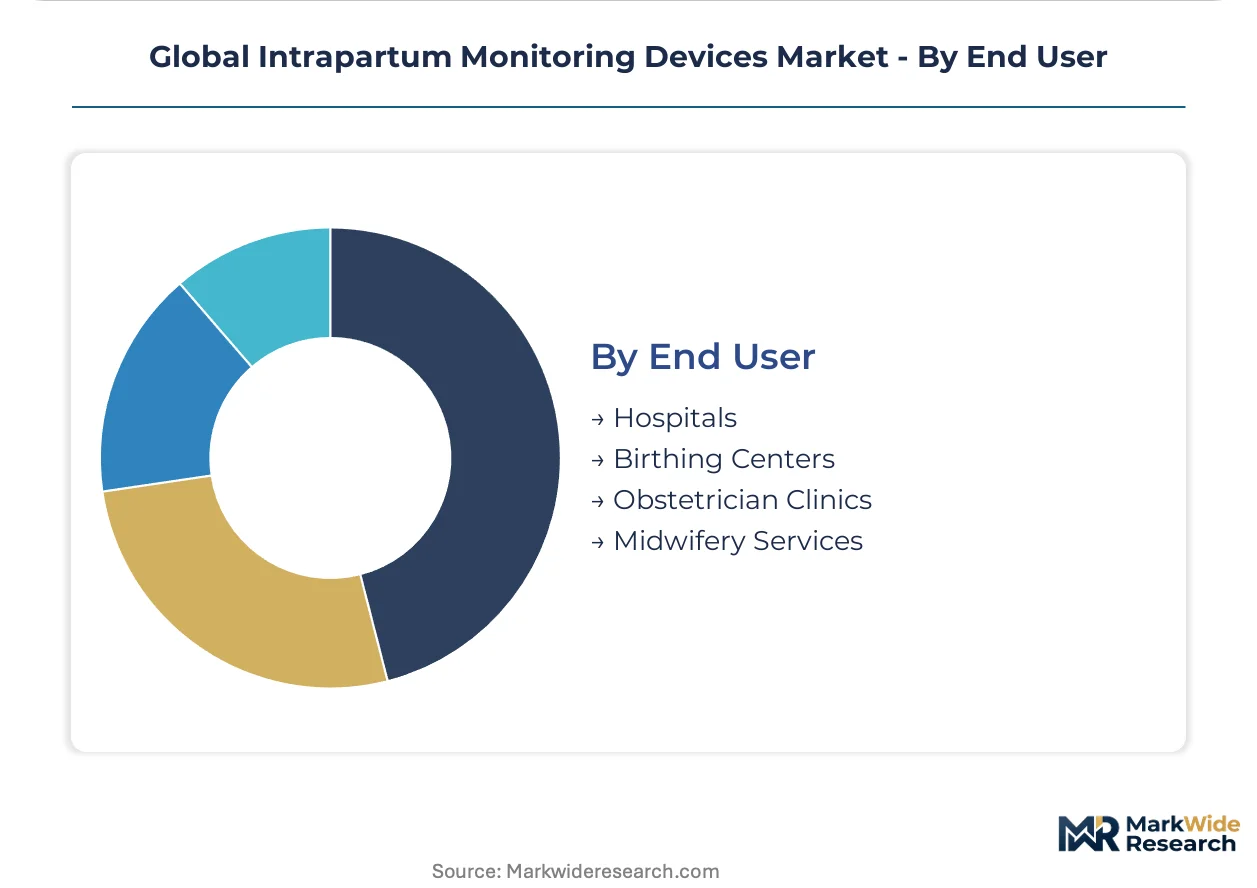
End User:
Volume concentration among consolidated hospital networks contrasts with margin opportunities in fragmented midwifery channels.
- Hospitals:Integrated health systems with centralized procurement committees negotiating multi-vendor maintenance agreements. United States consolidation concentrates order volumes with vendors offering full-platform solutions.
- Birthing Centers:Freestanding facilities emphasizing low-intervention deliveries. Australian mid-tier centers bypass distributor markups through direct-to-facility leasing channels.
- Obstetrician Clinics:Physician-owned practices providing prenatal care and limited delivery services.
- Midwifery Services:Independent or hospital-affiliated practitioners managing normal pregnancies and births. EU MDR technical documentation burdens strain regulatory affairs capacity at mid-size manufacturers serving this channel.
Hospitals command the dominant share of device throughput; birthing centers are expanding most rapidly as addressable endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance requirements in the United States are elevating product standards while hospital consolidation drives bulk purchasing of integrated monitoring platforms. The EU Medical Device Regulation's transition deadlines reshape procurement criteria across German maternity units. Japanese and German component specialists control sensor supply chains, creating input bottlenecks for manufacturers worldwide.
United States
Health system consolidation concentrates order volumes with vendors offering full-platform solutions across California and Texas health networks. FDA enforcement of 510(k) clearance requirements for fetal monitors creates multi-year approval timelines that deter novel signal processing architectures. The Boston medical device cluster hosts specialized biomedical signal processing engineering talent for fetal heart rate variability analysis.
Germany
Hospital procurement committees mandate ISO 13485 certification for all new maternal monitor suppliers under MDR compliance deadlines, elevating quality thresholds and locking out uncertified vendors. German notified bodies prioritize reviews for devices with post-market clinical follow-up protocols already established. The country's industrial base concentrates high-precision piezoelectric pressure sensor production, exposing manufacturers to input concentration risk.
Japan
PMDA regulatory frameworks align with international standards while domestic manufacturers control 70% of high-precision pressure sensor output for tocodynamometer applications. METI industrial policy supports miniaturization research for ultrasonic transducer form factors. Tokyo and Osaka medical device clusters maintain captive supply relationships with component specialists serving global monitor manufacturers.
India
Government hospital upgrades in Maharashtra and Tamil Nadu create first-time demand for wireless telemetry in public sector tertiary maternity wards. CDSCO medical device regulations establish quality management requirements for imported monitoring equipment. The country's expanding tertiary maternity infrastructure attracts manufacturer-managed equipment-as-a-service arrangements for mid-tier birthing centers.
Australia
Mid-tier birthing centers bypass distributor markups through direct-to-facility leasing channels managed by manufacturers. TGA medical device standards align with international ISO frameworks while maintaining specific post-market surveillance requirements. Sydney and Melbourne health systems experiment with cloud-native architectures enabling remote specialist consultation during high-risk deliveries.
Global Intrapartum Monitoring Devices Market Competitive Landscape
On the supply side, the industry is consolidating around full-platform solution providers capable of servicing merged hospital networks with integrated hardware and service contracts. Three strategic archetypes dominate: diversified medical technology conglomerates with installed base leverage, specialized maternal-fetal health pure-plays with regulatory expertise, and emerging Asian manufacturers competing on manufacturing scale. Competitive moves center on strategic partnerships to navigate FDA 510(k) pathway friction and geographic expansion into India's public hospital upgrade cycle.
Within the diversified conglomerate tier, Koninklijke Philips N.V. and Medtronic PLC exemplify players leveraging installed base relationships to sustain service contract renewals and integrate maternal hemodynamic sensors with existing critical care platforms. GE Healthcare occupies a position representing manufacturing scale advantages that control per-unit costs across wireless telemetry production lines. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies the emerging manufacturer archetype competing on production efficiency and direct-to-facility leasing channel development in Asia-Pacific markets.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic PLC |
| Cardinal Health |
| GE Healthcare |
| The Cooper Companies |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Natus Medical Incorporated |
| Huntleigh Healthcare Limited |
| Analogic Corporation |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors connecting Japanese sensor foundries to North American assembly plants transmit cost volatility directly into downstream price tiers, amplifying spreads between ISO 13485-certified premium units and uncertified alternatives while compressing margins on mid-tier configurations.
Pricing Analysis
Certification level creates the primary spread between market tiers, with FDA 510(k)-cleared and MDR-compliant devices commanding substantial premiums over uncertified alternatives. Pricing stratifies across premium, standard, and economy tiers based on wireless telemetry capability and service bundling intensity. Cost compression in the standard tier is intensifying because hospital procurement committees now unbundle hardware from maintenance contracts. Mid-tier birthing centers exhibit highest price sensitivity, while consolidated US health systems leverage volume scale for preferential terms.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates supply chain risk calculations for piezoelectric pressure sensor procurement. Manufacturing draws from Japanese component specialists, German precision sensor foundries, and Chinese assembly operations for disposable electrodes. Single-source vulnerability concentrates in high-precision tocodynamometer transducers, where two Japanese suppliers control captive output. Distribution runs through manufacturer-direct leasing channels in Asia-Pacific and distributor-mediated hospital procurement in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intrapartum monitoring is approaching a platform-economics inflection where interoperability standards and cloud-native data architectures determine competitive survival, much as electronic health record integration reshaped hospital IT procurement.
For Market Incumbents: Entrench installed base relationships through proprietary sensor compatibility locks and multi-year service contract structures that resist unbundling pressures. Deepen backward integration into ultrasonic transducer manufacturing to offset Japanese supply concentration. Prioritize MDR technical file resubmissions ahead of notified body queue bottlenecks.
For New Entrants and Emerging Players: India's Maharashtra and Tamil Nadu public hospital upgrade cycles present first-mover opportunities for wireless telemetry platforms in budget-constrained tertiary wards. Target direct-to-facility equipment-as-a-service arrangements that bypass distributor markups and align with government procurement flexibility. Lead with AI-enhanced cardiotocography software that layers onto existing hardware without full device replacement.
For Investors and Strategic Acquirers: Specialized maternal-fetal health pure-plays with established FDA 510(k) predicate libraries and European MDR technical files represent the most defensible acquisition profile. Long-term viability hinges on regulatory asset scarcity rather than manufacturing scale. Watch for CDSCO quality management enforcement in India as the signal indicating when to accelerate Asia-Pacific distribution buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Resubmission | German notified bodies prioritize reviews for devices with post-market clinical follow-up protocols established. |
| Hospital System Partnership | Consolidated US health systems concentrate order volumes with vendors offering full-platform solutions across California and Texas networks. |
| Software Companion Development | AI-enhanced cardiotocography pattern recognition offers differentiation without requiring full hardware replacement cycles. |
| Reimbursement Strategy | CMS coding alignment for remote maternal monitoring expands addressable demand beyond traditional labor ward settings. |
| CE Marking Pathway | ISO 13485 certification mandates from German procurement committees elevate quality thresholds and lock out uncertified vendors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers; and secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and customs records for sensor component trade flows. Bottom-up triangulation across product-type shipment estimates and top-down reconciliation against health system capital expenditure disclosures anchored volume figures.
Forecast inputs span product type, technology architecture, application setting, and end-user channel across the analysis window, with regional regulatory clusters treated as distinct adoption environments. CAGRs derive from logistic growth curve fitting against historical replacement cycles and procurement pipeline visibility. Wireless telemetry penetration rates and AI software attach rates constitute industry-specific demand drivers in the projection framework.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets, precious metals pricing for silver chloride electrodes, or transoceanic freight rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory deadline adherence and health system consolidation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Global Biomedical Sensor Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market