
 Preeclampsia Therapeutics Market | 2026-2036
Preeclampsia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Preeclampsia Therapeutics Market Analysis
Hospital-based maternal-fetal medicine units is bifurcating away from general obstetric clinics as the primary buyer archetype for advanced preeclampsia interventions. Sera Prognostics leverages proteomic diagnostic platforms to identify at-risk pregnancies before symptom onset. DiaMedica Therapeutics anchors its position through recombinant protein therapies targeting vascular endothelial dysfunction. F. Hoffmann-La Roche sustains competitive presence via integrated diagnostics-to-therapeutics workflows in high-volume perinatal centers.
Preeclampsia therapeutics comprise pharmacologic agents designed to modulate maternal vascular function, reduce endothelial injury, and prevent eclamptic seizures through mechanisms including vasodilation, anti-inflammatory action, and antioxidant protection. These interventions primarily serve to prolong gestation, reduce maternal organ damage, and improve neonatal outcomes in hypertensive disorders of pregnancy. Antihypertensives and corticosteroids occupy the mature core of the product portfolio with established clinical protocols, while calcium channel blockers capture expanding share in acute management settings where rapid blood pressure control proves critical. Injectable and intravenous delivery modes dominate hospital revenue pools, though transdermal formats represent an emerging vector for ambulatory monitoring integration.
The FDA's pregnancy labeling standards and EMA's pharmacovigilance requirements for maternal therapies jointly elevate clinical evidence thresholds for market authorization. ISO 14155-compliant trial frameworks govern investigational device and biologic studies across North American and European jurisdictions, extending development timelines but reducing post-market safety liabilities. Stakeholders must monitor how evolving FDA guidance on inclusive pregnancy trial design reshapes pipeline economics and competitive entry barriers.
Market Dynamics
Biomarker-guided risk stratification is reshaping how maternal-fetal medicine specialists allocate therapeutic resources, shifting from reactive symptom management to preemptive intervention protocols in high-risk obstetric populations.
Growth Catalysts
- FDA Pregnancy Labeling Standards:Revised guidance on inclusive trial design expands eligible patient populations for pharmacologic studies, accelerating pipeline maturation for vascular-modulating agents.
- Recombinant Protein Platforms:Advances in recombinant protein manufacturing reduce batch-to-batch variability for endothelial-targeting biologics, improving supply reliability for tertiary care infusion centers.
- United States:Developed reimbursement frameworks for high-risk obstetrics concentrate demand in tertiary hospitals with maternal-fetal medicine specialization, creating predictable revenue pools for novel therapeutic entrants.
Market Restraints
- EMA Pharmacovigilance Requirements:Stringent post-authorization safety monitoring for maternal therapies extends regulatory timelines and elevates clinical evidence thresholds beyond what smaller developers can sustain.
- Placental Perfusion Modeling:Technical limitations in predicting human placental transfer of novel compounds create uncertainty in fetal safety profiles, constraining candidate selection for development programs.
- Specialized Infusion Infrastructure:Concentration of hospital-based maternal-fetal medicine units in urban academic centers limits geographic reach for intravenous biologic therapies requiring controlled administration environments.
Strategic Opportunities
- Transdermal Delivery Convergence:Integration of microneedle arrays with continuous hemodynamic monitoring enables ambulatory blood pressure management, extending therapeutic access beyond inpatient settings.
- ISO 14155-Compliant Trial Networks:Harmonized investigational device and biologic study frameworks across North American and European jurisdictions reduce redundant regulatory filings for multi-center development programs.
- Proteomic Diagnostic Integration:Pairing predictive biomarker platforms with therapeutic decision algorithms creates closed-loop care pathways that pharmaceutical developers can capture through diagnostic-therapeutic bundling.
Industry Challenges
- Maternal-Fetal Toxicology Expertise:Scarce specialist capacity in developmental and reproductive toxicology creates bottlenecks in preclinical safety assessment, delaying IND-enabling studies for novel vascular targets.
- Legacy EHR Integration:Disparate electronic health record architectures across obstetric care networks complicate real-world evidence collection for post-market safety surveillance required by maternal therapy regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preeclampsia Therapeutics Market |
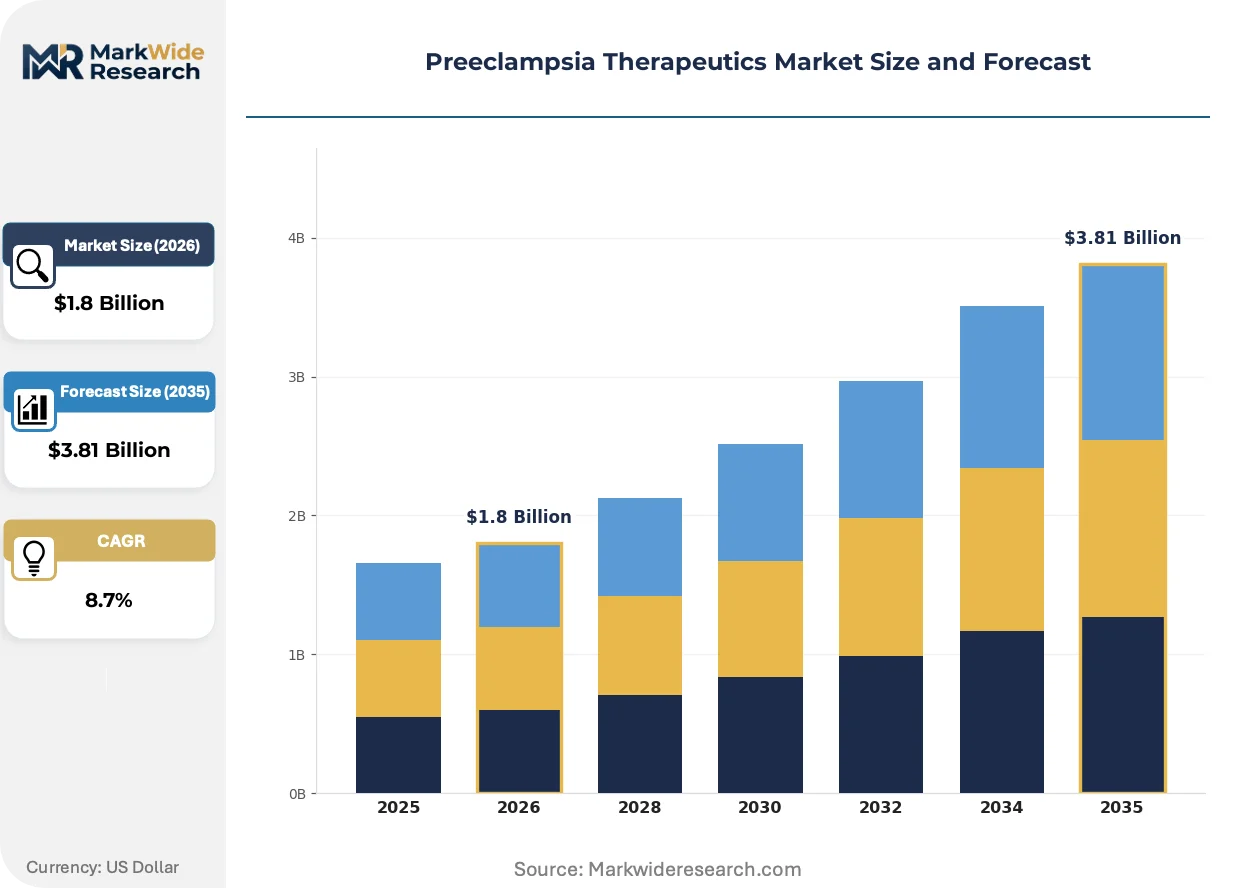
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihypertensives, Corticosteroids, Calcium Channel Blockers, Antioxidants Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Homecare, Ambulatory Surgery Centers Treatment Stage: Preventive Care, Acute Management, Postpartum Care, Long-term Follow-up |
| Companies Covered | Sera Prognostics, DiaMedica Therapeutics, Comanche Biopharma, F. Hoffmann-La Roche, AMAG Pharmaceuticals, Gmax Biopharm, A1M Pharma, ASKA Pharmaceutical, Corion Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preeclampsia Therapeutics Market Emerging Trajectories
Precision medicine architectures are penetrating obstetric pharmacology, replacing empiric dosing protocols with individualized risk-adjusted interventions that align therapeutic intensity with predicted disease trajectory.
Continuous hemodynamic monitoring via wearable photoplethysmography is bifurcating ambulatory preeclampsia management from traditional office-based surveillance. Maternal-fetal medicine clinics in integrated health systems are piloting these platforms for home-based blood pressure titration. This technology is bifurcating the historical inpatient-versus-outpatient boundary, compressing hospital admission thresholds while expanding pharmaceutical intervention windows.
REACH-compliant substance safety dossiers are elevating documentation requirements for excipients and process impurities in parenteral obstetric formulations. Manufacturers must now characterize reproductive toxicity profiles for all formulation components, not just active pharmaceutical ingredients. European contract development organizations report extended timeline quotations for maternal therapy programs as a direct response to these expanded obligations.
Academic medical centers are consolidating procurement authority for high-cost biologic therapies under centralized pharmacy and therapeutics committees. Individual obstetric service lines lose autonomous purchasing discretion as institutions implement value-based formulary placement criteria. This concentration is most visible in United States tertiary hospitals participating in bundled payment pilots for high-risk pregnancy episodes.
Preeclampsia Therapeutics Market Segmentation
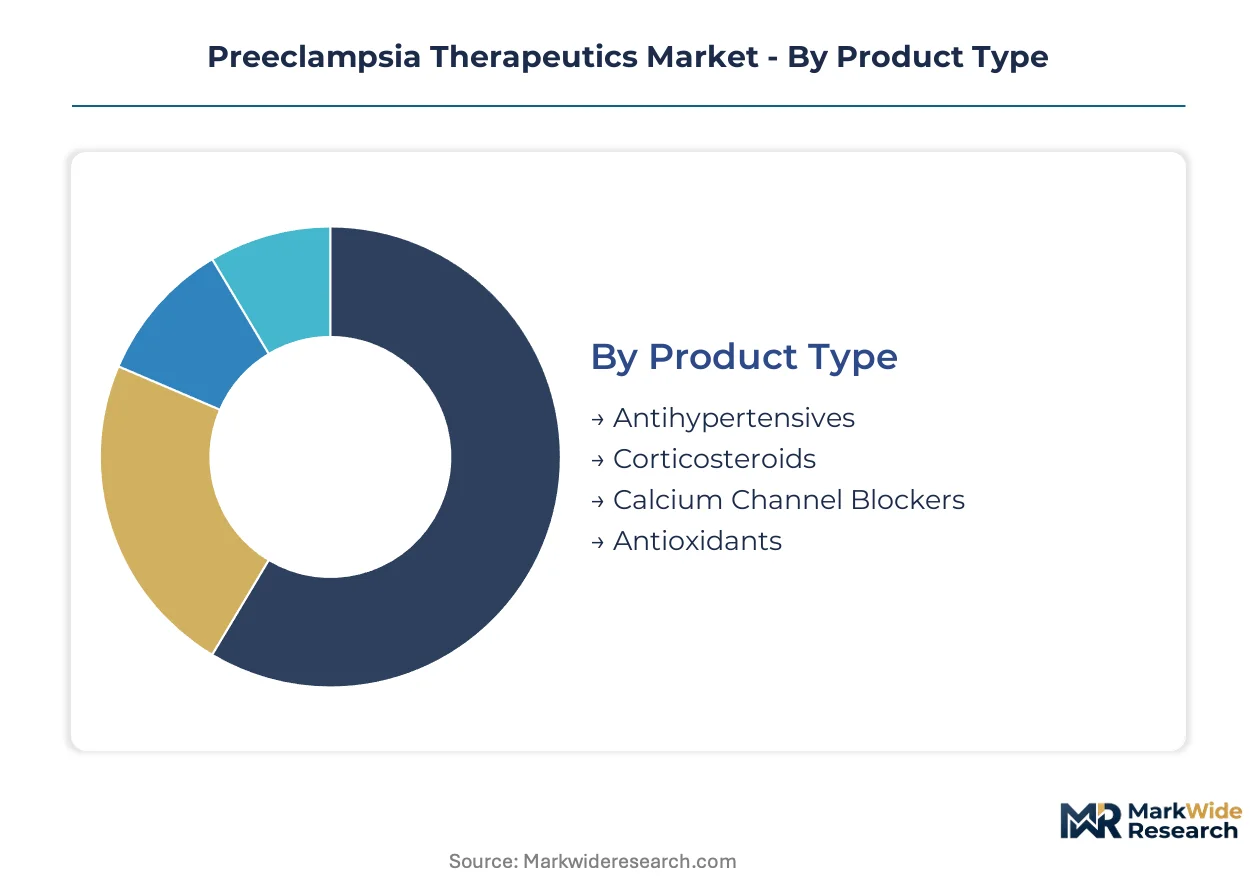
Therapeutic allocation across preeclampsia treatment pathways follows distinct channel logics. Product type determines reimbursement tier, while delivery mode shapes site-of-care economics and patient access boundaries.
Product Type:
Hospital pharmacies and outpatient infusion centers split procurement authority differently across pharmacologic classes, with formulary placement governed by maternal-fetal medicine committee protocols.
- Antihypertensives:First-line agents including labetalol and methyldopa dominate maintenance protocols for chronic hypertension in pregnancy. United States tertiary hospitals with bundled payment contracts concentrate procurement volume for these agents, prioritizing agents with established fetal safety profiles over newer entrants.
- Corticosteroids:Betamethasone and dexamethasone protocols for fetal lung maturation anchor acute preeclampsia management workflows. Demand clusters in academic medical centers with level III NICU capabilities, where gestational age thresholds for administration trigger automated order sets.
- Calcium Channel Blockers:Nifedipine occupies acute hypertensive emergency protocols with rapid onset characteristics.
- Antioxidants:Emerging vitamin-based interventions target endothelial dysfunction biomarkers in research protocols.
By volume, antihypertensives lead. By growth pace, calcium channel blockers are expanding most quickly in acute management settings.
Delivery Mode:
Cost tier stratification separates inpatient biologic infusions from ambulatory maintenance therapies, with reimbursement differentials of 3-5x between parenteral and oral equivalents.
- Oral:Tablet and capsule formulations enable outpatient blood pressure management for stable patients. United States Medicaid programs and commercial insurers favor oral step-down protocols to reduce hospital readmission penalties, concentrating volume in community pharmacy networks.
- Injectable:Subcutaneous and intramuscular delivery supports rapid therapeutic intervention without vascular access requirements. Maternal-fetal medicine clinics in integrated delivery networks deploy injectable magnesium sulfate for seizure prophylaxis, with procurement centralized under hospital pharmacy and therapeutics committees.
- Transdermal:Microneedle patch technologies enable ambulatory hemodynamic monitoring integration.
- Intravenous:Continuous infusion capabilities remain restricted to tertiary hospital labor and delivery units with anesthesia coverage.
Intravenous formats command the highest unit economics. Transdermal platforms are gaining share fastest in pilot programs.
End User:
Customer type determines protocol standardization versus individualized therapeutic intensity, with hospital systems enforcing pathway compliance that smaller sites cannot replicate.
- Hospitals:Tertiary academic centers with maternal-fetal medicine specialization manage the highest-acuity preeclampsia presentations. These sites capture novel biologic trials and FDA-expanded access programs, with pharmacy budgets exceeding $50 million annually for high-risk obstetric therapeutics.
- Clinics:Community obstetric practices and generalist offices handle stable chronic hypertension surveillance. Reimbursement constraints limit therapeutic repertoire to generic antihypertensives with established pregnancy labeling.
- Homecare:Post-discharge blood pressure monitoring and oral medication management extend therapeutic windows.
- Ambulatory Surgery Centers:Limited obstetric procedure volume restricts preeclampsia therapeutic allocation.
Hospitals dominate value capture. Homecare represents the steepest expansion trajectory as remote monitoring platforms mature.
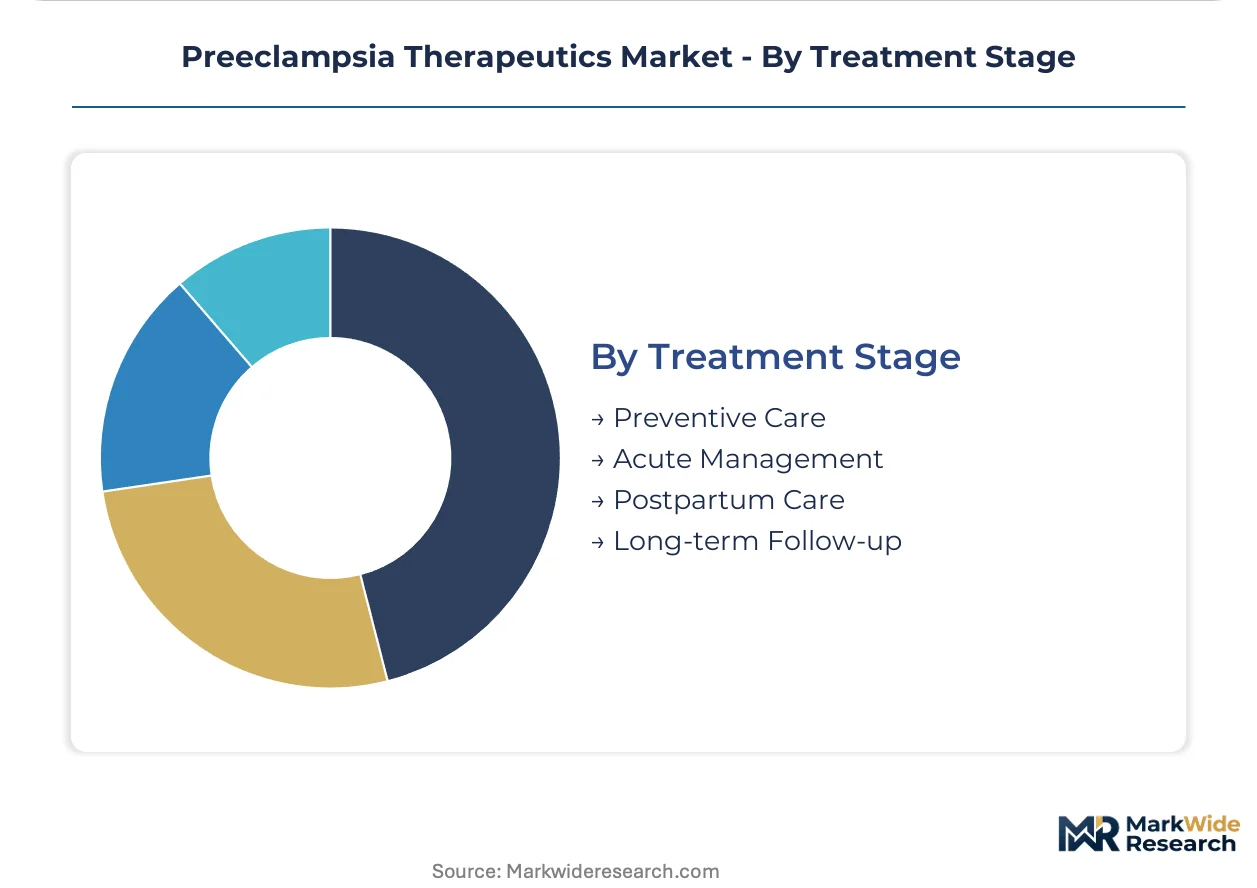
Treatment Stage:
Application timing segments therapeutic investment across gestational risk windows, with preventive protocols requiring biomarker infrastructure that acute management does not.
- Preventive Care:Low-dose aspirin and calcium supplementation target high-risk nulliparous patients with predictive screening. United States health systems with proteomic diagnostic partnerships pilot risk-stratified intervention protocols, though coverage determination remains inconsistent across state Medicaid programs.
- Acute Management:Hospital-based seizure prophylaxis, blood pressure control, and delivery timing decisions concentrate therapeutic expenditure. These episodes generate the highest per-patient pharmaceutical costs in the treatment pathway.
- Postpartum Care:Blood pressure monitoring and antihypertensive tapering address delayed-onset maternal complications.
- Long-term Follow-up:Cardiovascular risk modification extends therapeutic engagement beyond the obstetric episode.
Acute management leads by expenditure concentration. Preventive care is climbing the fastest as predictive diagnostics achieve regulatory validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biopharma exports supply maternal-fetal medicine units across Central European hospital networks. Swiss diagnostic platforms reach United States academic medical centers through specialized distribution agreements.
United States
Tertiary hospitals with bundled payment contracts for high-risk obstetrics drive demand concentration for novel biologic therapies. FDA pregnancy labeling standards accelerate clinical trial enrollment through inclusive trial design guidance. Boston and San Francisco academic medical centers host the highest density of maternal-fetal medicine specialization and expanded access programs.
Germany
University hospitals with perinatal centers anchor procurement volume for recombinant protein therapies targeting vascular endothelial dysfunction. EMA pharmacovigilance requirements elevate post-authorization safety monitoring standards for maternal therapies. The Rhine-Ruhr metropolitan region concentrates contract manufacturing capacity for parenteral obstetric formulations.
Switzerland
Integrated diagnostics-to-therapeutics workflows command premium positioning in high-volume perinatal centers. Swissmedic regulatory frameworks align with ISO 14155-compliant trial structures for multi-center biologic studies. Basel and Zurich host concentrated pharmaceutical R&D infrastructure for pregnancy pharmacology.
United Kingdom
NHS England specialized commissioning frameworks concentrate funding for severe pre-eclampsia management in designated tertiary centers. MHRA guidance on pregnancy trial design harmonizes with FDA standards for transatlantic development programs. London teaching hospitals pilot proteomic diagnostic integration with therapeutic decision algorithms.
Japan
PMDA consultation pathways for maternal therapy development reduce regulatory uncertainty for novel vascular-modulating agents. Aging demographics elevate clinical priority for hypertensive disorders of pregnancy research. Tokyo and Osaka academic medical centers concentrate perinatal intensive care capacity and biologic infusion infrastructure.
Preeclampsia Therapeutics Market Vendor Landscape
Player mix skews toward specialized biopharma developers with recombinant protein platforms and proteomic diagnostic capabilities. Market structure fragments across early-stage therapeutic innovators, established pharmaceutical manufacturers with integrated diagnostics portfolios, and contract development organizations with maternal-fetal toxicology expertise. Strategic archetypes include biomarker-guided intervention specialists, vascular-targeting biologic developers, and full-stack perinatal care platform builders. Competitive moves concentrate on diagnostic-therapeutic bundling partnerships and ISO 14155-compliant trial network expansion.
Among United States-based developers, Sera Prognostics and DiaMedica Therapeutics occupy positions within the biomarker-guided and vascular-targeting archetypes respectively. F. Hoffmann-La Roche represents the integrated diagnostics-to-therapeutics model through its positioning in high-volume perinatal center workflows. These three companies exemplify the strategic divergence between predictive risk stratification platforms and direct therapeutic intervention development.
| Leading Market Players |
|---|
| Sera Prognostics |
| DiaMedica Therapeutics |
| Comanche Biopharma |
| F. Hoffmann-La Roche |
| AMAG Pharmaceuticals |
| Gmax Biopharm |
| A1M Pharma |
| ASKA Pharmaceutical |
| Corion Biotech |
| Others |
Supply Flow & Price Mechanics
Ninety-to-one-hundred-twenty-day safety stock requirements for recombinant protein biologics concentrate procurement leverage in tertiary hospital pharmacy committees, amplifying their negotiating position against developers of endothelial-targeting therapies. This inventory burden cascades into pricing power asymmetries where maternal-fetal medicine units extract volume discounts in exchange for formulary placement security.
Pricing Analysis
Next-generation recombinant protein therapies command 40-60% premiums over mature antihypertensive equivalents, while prior-generation corticosteroids face commoditization pressure from automated order-set standardization. Three-tier pricing structure across premium biologics, standard small-molecule protocols, and economy generic maintenance separates academic medical centers with bundled payment contracts from community hospitals on fee-for-service models. Pricing pressure stems from Medicaid reimbursement compression for maternal health episodes, with United States state programs tightening prior authorization thresholds. Community obstetric clinics exhibit highest price sensitivity due to formulary restriction to generic antihypertensives, while tertiary maternal-fetal medicine units prioritize fetal safety profiles over acquisition cost.
Supply Chain Analysis
Seventy-five-day average lead times for recombinant protein manufacturing anchor supply planning for endothelial-targeting biologics, constraining just-in-sequence delivery to infusion centers. Contract manufacturing concentrates in Switzerland, Germany, and the United States for parenteral obstetric formulations, with active pharmaceutical ingredient sourcing drawing from Irish and Singaporean fermentation facilities. Supply chain risk centers on single-source dependency for specialized maternal-fetal toxicology assessment capacity, creating bottlenecks in IND-enabling studies. Distribution runs through hospital-centric pharmacy and therapeutics committees with centralized procurement authority, bypassing traditional wholesale channels for high-cost biologic therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preeclampsia therapeutics represent an early-cycle expansion story where FDA pregnancy labeling standardization accelerates clinical trial enrollment velocity and compresses development timelines for vascular-modulating agents.
For Market Incumbents: Compound diagnostic-therapeutic bundling partnerships with proteomic platform developers to lock in referral channel control before predictive risk stratification achieves mainstream reimbursement. Acquire or in-license transdermal delivery technologies to extend therapeutic reach beyond infusion-dependent inpatient settings, defending against ambulatory monitoring convergence that threatens hospital-centric revenue pools. For New Entrants and Emerging Players: Homecare blood pressure management services represent the most penetrable white-space where incumbent biopharma developers under-serve post-discharge maternal surveillance. Target United States Medicaid-managed care organizations with value-based contracting proposals that align therapeutic outcomes with readmission penalty avoidance, using remote monitoring integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because maternal-fetal medicine specialization concentrates in academic medical centers with predictable procurement patterns and multi-year formulary commitments. Acquisition target archetype: mid-cap biopharma developers with ISO 14155-compliant trial networks and recombinant protein manufacturing capacity. Signal to watch: FDA breakthrough therapy designation density in preeclampsia vascular targets as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundling | Pairs Sera Prognostics' proteomic platforms with pharmaceutical interventions to capture closed-loop care pathways. |
| ISO 14155 Trial Network Expansion | Harmonizes investigational protocols across FDA and EMA jurisdictions, reducing redundant regulatory filings for biologic developers. |
| Transdermal Delivery Development | Enables ambulatory blood pressure management beyond controlled infusion settings, extending addressable patient populations. |
| Recombinant Protein Manufacturing Scale-Up | Improves batch-to-batch consistency for endothelial-targeting therapies, securing supply reliability for tertiary care centers. |
| Proteomic Diagnostic Integration | Creates predictive risk-stratification infrastructure that triggers preemptive intervention protocols before symptom onset. |
Methodological Framework
A standing panel of maternal-fetal medicine specialists, hospital pharmacy and therapeutics committee chairs, regulatory affairs leads at biopharma developers, and payer access specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA pregnancy labeling guidance documents, EMA pharmacovigilance submissions, ClinicalTrials.gov enrollment data, and United States hospital procurement databases. Bottom-up therapeutic volume estimates triangulated against top-down market sizing from reimbursement claims analysis.
Consistency checks validated projection outputs against external benchmarks including historical biologic adoption curves in obstetric indications and comparable vascular-targeting therapy penetration patterns. Segmentation modeling spanned product type, delivery mode, end user archetype, and treatment stage across the analysis window, with CAGRs derived from slope-matching to regulatory approval velocity and reimbursement expansion trajectories. Forecast inputs incorporated FDA guidance evolution timelines and EMA post-authorization safety monitoring burden estimates.
Underlying assumptions cover sustained FDA pregnancy trial design liberalization and stable United States Medicaid maternal health funding, with deviation risk concentrated in state-level coverage determination variability for predictive diagnostics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market