
 Patient Monitoring and Ultrasound Devices Display Market | 2026-2036
Patient Monitoring and Ultrasound Devices Display Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Monitoring and Ultrasound Devices Display Market Analytics
OLED and mini-LED panel technology is repositioning cost structures across premium diagnostic displays, displacing legacy LCD dominance in cardiology and radiology workstations. GE Healthcare leverages in-house display calibration protocols to sustain color accuracy leadership in ultrasound visualization. Siemens Healthineers anchors its hospital contracts with integrated monitoring-display ecosystems that reduce interoperability friction. Philips Healthcare differentiates through automated brightness stabilization algorithms that comply with evolving diagnostic imaging standards.
Patient monitoring and ultrasound devices displays are high-resolution medical-grade screens engineered to render real-time physiological data and acoustic imaging with luminance consistency exceeding 500 cd/m² and DICOM calibration for grayscale precision; they serve critical diagnostic decision-making in acute care, perioperative settings, and ambulatory imaging suites. Bedside monitors and portable ultrasound systems command the largest installed base, while wireless connectivity integration represents the fastest-expanding technology dimension as hospitals prioritize untethered workflow flexibility. Digital imaging platforms capture the dominant margin pool due to software-locked upgrade architectures and recurring calibration service contracts.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and regional market access conditions for display-embedded diagnostic devices. The EPA ENERGY STAR program and IEC 60601-1 third-edition electrical safety standards further constrain hardware design choices and supplier qualification criteria. Stakeholders must monitor evolving cybersecurity mandates for networked monitoring displays and assess whether in-house production of display modules or strategic sourcing from specialized panel fabricators offers superior cost control and supply assurance.
Market Dynamics
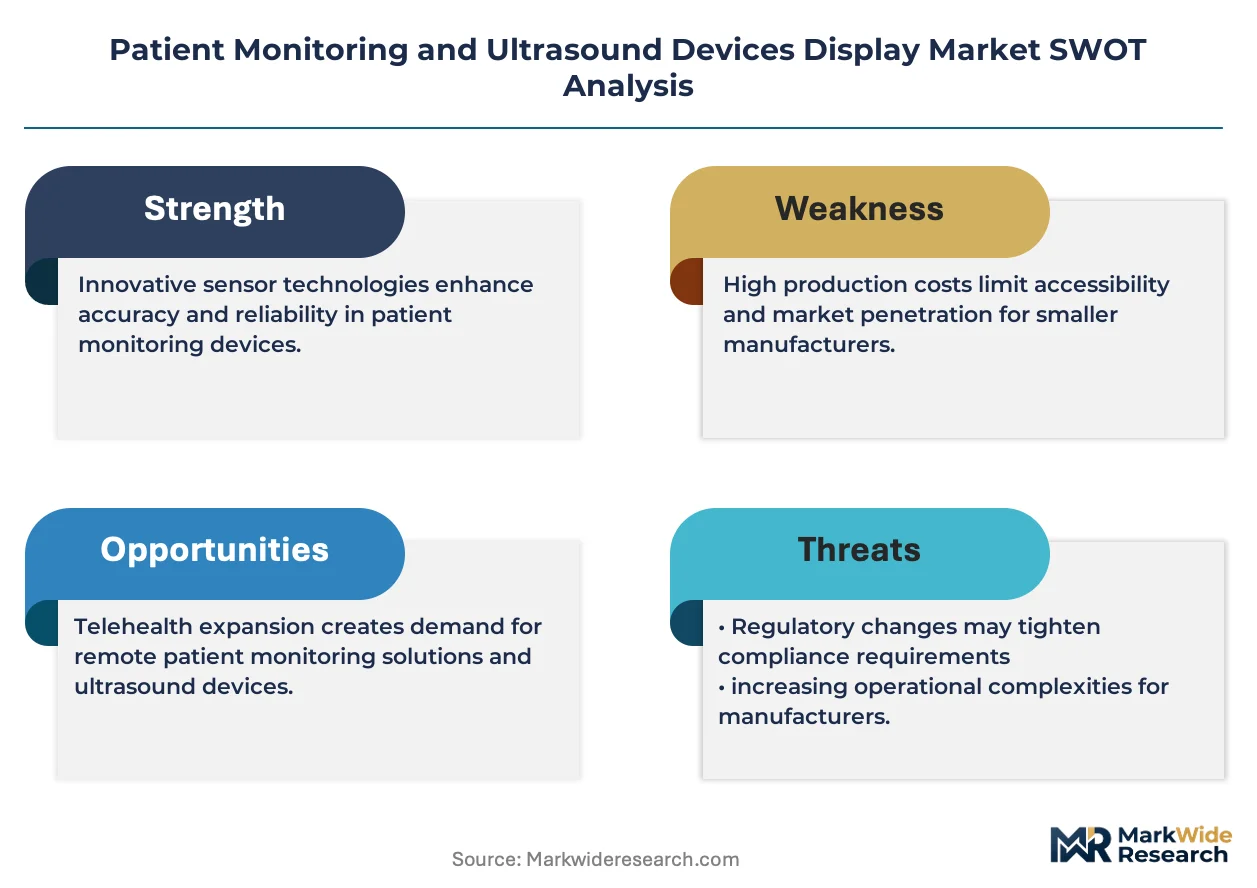
OLED and mini-LED backlighting architectures are restructuring procurement economics across diagnostic display tiers, compressing LCD price premiums in cardiology workstations while elevating luminance floor requirements for grayscale calibration.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for predicate-equivalent display-embedded devices accelerates product refresh cycles in US acute care networks.
- EU MDR Class IIa certification harmonization:Mutual recognition agreements reduce duplicate testing burdens for manufacturers serving European hospital procurement consortia.
- Point-of-care imaging expansion:Emergency departments and ambulatory surgical centers drive demand for portable ultrasound displays with wireless DICOM transmission capability.
Market Restraints
- Indium supply concentration:OLED electrode fabrication depends on Chinese rare earth processing infrastructure subject to export quota volatility.
- IEC 60601-1 third-edition compliance costs:Electrical safety retesting for existing display product lines absorbs 12-18 month redesign windows.
- Tablet-based diagnostic substitution:Consumer-grade high-resolution screens with software calibration threaten premium medical display attach rates in cost-constrained clinics.
Strategic Opportunities
- Home-based patient monitoring:Post-acute care reimbursement shifts in Germany and Japan create demand for consumer-facing displays with clinical-grade telemetry.
- AI-embedded visualization:Real-time acoustic enhancement algorithms fused with mini-LED local dimming enable new diagnostic decision-support workflows.
- Refurbishment channel formalization:Third-party recertification services for retired hospital displays unlock secondary markets in Southeast Asian outpatient networks.
Industry Challenges
- DICOM calibration technician scarcity:Grayscale standardization expertise concentrates in legacy radiology departments, constraining deployment velocity for decentralized imaging.
- Legacy PACS integration friction:New wireless display architectures require middleware development for compatibility with decade-old hospital archive systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Monitoring and Ultrasound Devices Display Market |
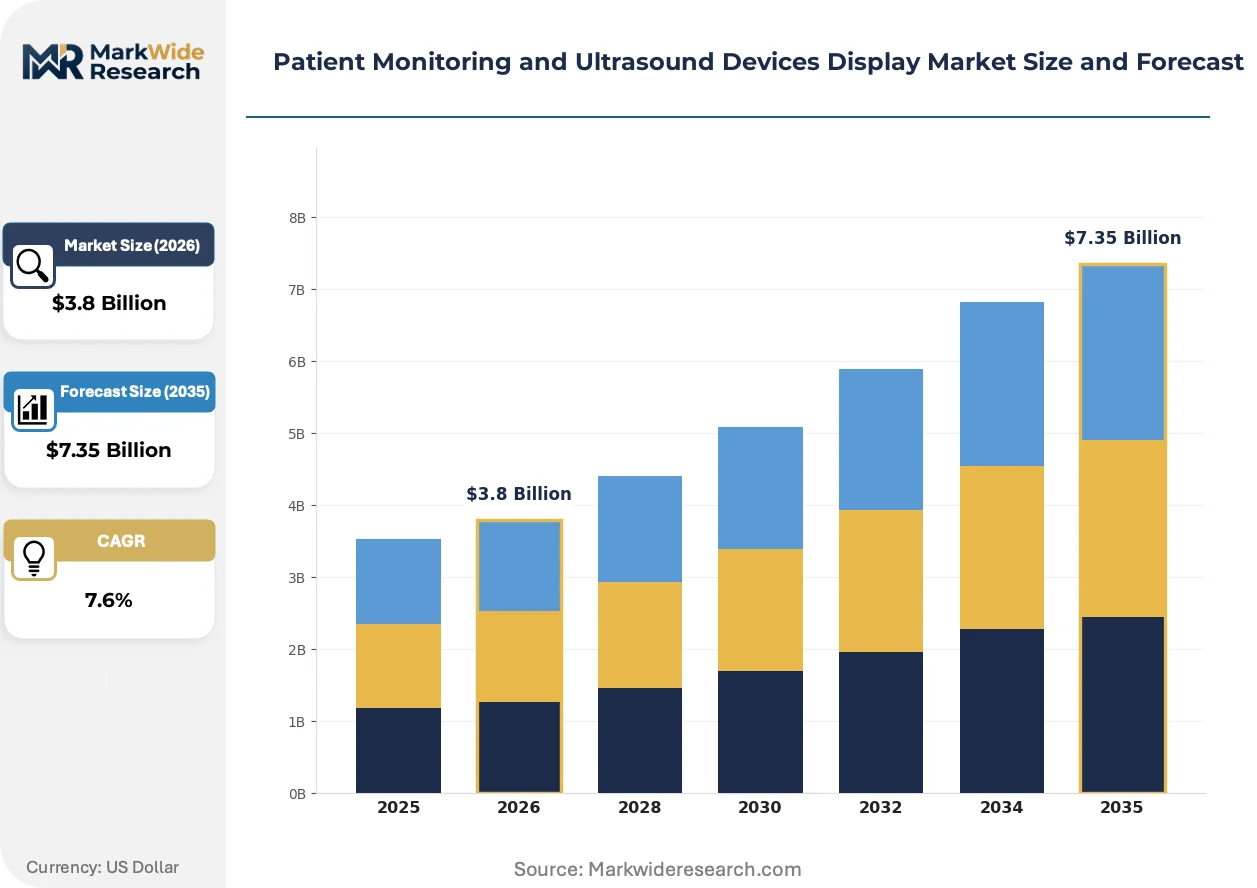
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Monitors, Bedside Monitors, Portable Ultrasound, Stationary Ultrasound Technology: Digital Imaging, Analog Imaging, Wireless Connectivity, Automated Monitoring End User: Hospitals, Outpatient Clinics, Home Care, Emergency Services Application: Cardiology, Obstetrics, Emergency Medicine, General Surgery |
| Companies Covered | FUJIFILM, Hitachi Medical, GE Healthcare, Barco, Hologic, Philips Healthcare, Canon Medical Systems, Masimo Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Monitoring and Ultrasound Devices Display Market Evolving Landscape
Display technology migration, regulatory recalibration, and procurement model fragmentation are simultaneously reshaping competitive positioning across the patient monitoring and ultrasound visualization value chain.
Mini-LED local dimming arrays are absorbing the luminance precision requirements previously reserved for full-array OLED backplanes in cardiac ultrasound workstations. Interventional cardiology departments at tertiary US hospitals are adopting these configurations at replacement-cycle velocity. The cost compression this enables is absorbing margin pressure from LCD panel oversupply while preserving diagnostic grayscale fidelity.
EU MDR technical documentation requirements for electromagnetic compatibility are extending product development timelines for display-embedded devices seeking European market access. Manufacturers must demonstrate conformity with harmonized EN 60601-1-2 standards through notified body assessment. German and Swiss hospital procurement groups are prioritizing suppliers with pre-validated MDR technical files, compressing vendor shortlists.
Subscription-based calibration service contracts are displacing perpetual-license maintenance agreements in US health system purchasing. Integrated delivery networks in Texas and Florida are consolidating display fleets under single-source managed service arrangements. This consolidation concentrates purchasing leverage with procurement officers while marginalizing independent service organizations.
Patient Monitoring and Ultrasound Devices Display Market Segmentation
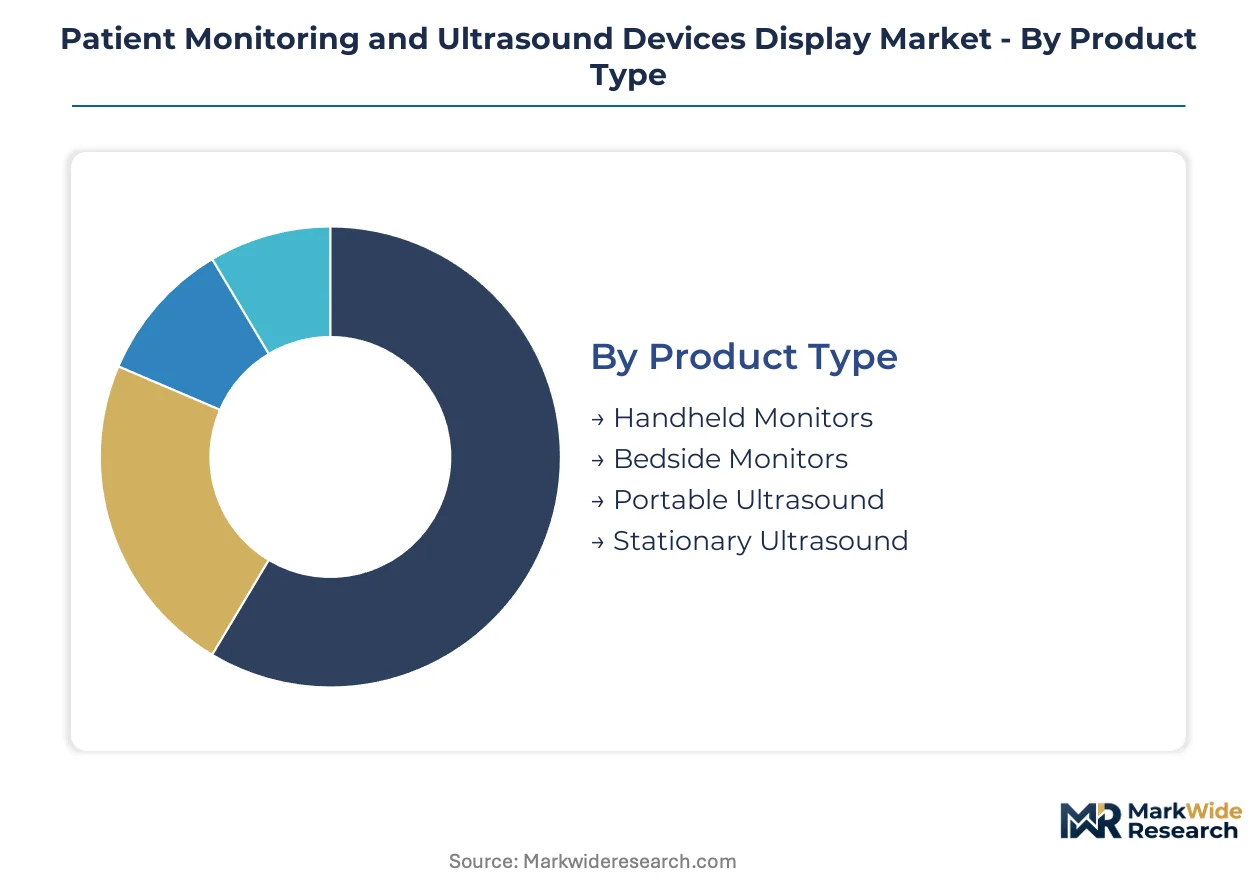
Procurement patterns across patient monitoring and ultrasound displays diverge sharply by clinical setting, with acute care networks prioritizing DICOM-calibrated luminance while ambulatory operators trade grayscale precision for wireless portability. Understanding these segment-specific trade-offs illuminates where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Hospital procurement officers weight capital allocation against workflow flexibility, with tethered systems commanding higher unit margins and portable configurations driving replacement frequency.
- Handheld Monitors:Compact battery-powered displays engineered for spot-check vital sign capture in ward rounds and transport scenarios. Demand concentrates in German emergency departments where corridor-to-bedside mobility reduces nurse station bottlenecks. FDA 510(k) predicate pathways for handheld form factors compress clearance timelines versus stationary equivalents.
- Bedside Monitors:Wall-mounted or cart-based high-luminance panels with continuous telemetry integration and alarm management interfaces. Japanese tertiary hospitals sustain replacement cycles here as aging demographics expand ICU bed counts. IEC 60601-1 third-edition compliance costs absorb 12-18 month redesign windows for legacy product lines.
- Portable Ultrasound:Tablet-sized displays with probe-integrated acoustic processing and wireless DICOM transmission. US point-of-care expansion in emergency medicine sustains attach rates.
- Stationary Ultrasound:Console-mounted diagnostic workstations with full-array grayscale calibration for radiology departments. European hospital procurement consortia prioritize MDR-validated technical files here.
Bedside monitors lead on scale; handheld monitors lead on momentum.
Technology:
Software-locked architectures capture recurring service revenue while hardware-agnostic connectivity standards threaten incumbent margin structures.
- Digital Imaging:Pixel-dense panels with embedded GPU processing for real-time acoustic rendering and AI-enhanced visualization. Cardiology departments in US integrated delivery networks anchor demand here. Subscription-based calibration contracts displace perpetual licenses in Texas and Florida health systems.
- Wireless Connectivity:Untethered data transmission protocols enabling point-of-care imaging without PACS workstation dependency. Ambulatory surgical centers in Japan adopt these configurations fastest as reimbursement shifts favor same-day discharge.
- Analog Imaging:Legacy CRT and early flat-panel architectures retained in cost-constrained secondary care settings. Replacement pressure intensifies.
- Automated Monitoring:Algorithm-driven alarm suppression and trend analysis with display-integrated decision support. EU MDR cybersecurity mandates extend development timelines here.
Digital imaging dominates revenue capture; wireless connectivity climbs the fastest.
End User:
Capital availability and regulatory scrutiny intensity segment procurement sophistication, with acute care networks demanding full certification stacks and home care operators accepting calibrated consumer alternatives.
- Hospitals:Multi-department display fleets requiring centralized fleet management and enterprise PACS integration. German and Swiss procurement groups consolidate vendor shortlists around pre-validated MDR technical files.
- Home Care:Consumer-facing displays with clinical-grade telemetry for post-acute monitoring. Germany and Japan reimbursement shifts create demand acceleration here.
- Outpatient Clinics:Cost-optimized configurations with essential grayscale calibration for routine diagnostics. Tablet-based substitution threats concentrate in this tier.
- Emergency Services:Ruggedized portable displays with rapid boot times and field-appropriate battery endurance. Pre-hospital adoption lags hospital point-of-care.
Hospitals anchor volume concentration; home care gains share fastest.
Application:
Diagnostic precision requirements vary by specialty, with cardiac imaging demanding highest luminance consistency and emergency medicine prioritizing acquisition speed over grayscale fidelity.
- Cardiology:Mini-LED local dimming arrays preserving diagnostic grayscale fidelity at compressed price points versus OLED. Interventional cardiology departments at tertiary US hospitals drive replacement velocity here.
- Emergency Medicine:Rapid-acquisition ultrasound with abbreviated calibration protocols for triage decision support. Point-of-care expansion in US emergency departments sustains portable display demand.
- Obstetrics:Specialized presets for fetal biometric measurement with thermal output constraints for prolonged exposure safety.
- General Surgery:Intraoperative displays with fluid resistance and sterilization compatibility for perioperative imaging integration.
Cardiology commands premium pricing; emergency medicine shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge medical technology cluster anchors procurement sophistication for diagnostic display systems, with Massachusetts General Hospital and Brigham and Women's Hospital setting calibration standards that diffuse through US integrated delivery networks.
United States
FDA 510(k) pathway streamlining accelerates product refresh cycles across Texas and Florida health systems. The EPA ENERGY STAR program constrains hardware design choices for hospital procurement officers. The Mayo Clinic in Rochester, Minnesota validates next-generation mini-LED configurations for interventional cardiology workstations.
Germany
EU MDR Class IIa certification harmonization reduces duplicate testing burdens for manufacturers serving Bavarian hospital procurement consortia. The national reimbursement authority's post-acute care shifts create demand acceleration for home-based monitoring displays. Siemens Healthineers anchors integrated monitoring-display ecosystems from its Erlangen headquarters.
Japan
Aging demographics expand ICU bed counts and sustain replacement cycles for bedside monitors in Tokyo metropolitan tertiary hospitals. METI industrial standards shape electrical safety requirements under IEC 60601-1 third-edition compliance. The Osaka-Kobe medical device cluster concentrates manufacturing for portable ultrasound display modules.
Switzerland
Swissmedic pre-validation requirements compress vendor shortlists for German and Swiss hospital procurement groups seeking MDR-compliant technical files. The country's precision manufacturing heritage supports high-luminance panel calibration expertise. The Zurich-West healthcare technology corridor hosts specialized display recertification services.
China
NMPA regulatory pathways for Class II medical devices extend development timelines for display-embedded diagnostic equipment seeking domestic market access. The country's rare earth processing infrastructure concentrates indium supply for OLED electrode fabrication. Shenzhen's electronics manufacturing ecosystem produces cost-optimized panel assemblies for secondary care export markets.
Patient Monitoring and Ultrasound Devices Display Market Competitive Landscape
Strategic partnerships dominate the current landscape as tier-one manufacturers secure calibration service contracts with integrated delivery networks. The market structure concentrates around three to five diversified health technology conglomerates with captive display divisions, flanked by specialized medical imaging firms and industrial display fabricators. Two archetypes prevail: vertically integrated hospital solution providers and component-specialist panel calibration houses. Portfolio diversification and technology licensing represent the dominant competitive vectors as firms bundle software-locked upgrade architectures with hardware sales.
Among diversified health technology conglomerates, GE Healthcare and Philips Healthcare exemplify the integrated solution archetype, while Siemens Healthineers anchors the European hospital contract vector. Barco occupies a position within the specialized medical display calibration tier. These three firms represent distinct geographic and capability concentrations that shape procurement officer vendor shortlists across US and European acute care networks.
| Leading Market Players |
|---|
| FUJIFILM |
| Hitachi Medical |
| GE Healthcare |
| Barco |
| Hologic |
| Philips Healthcare |
| Canon Medical Systems |
| Masimo Corporation |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA 510(k)-cleared diagnostic displays and uncertified consumer alternatives splits procurement economics across US hospital networks and cost-constrained outpatient settings. This tier divergence concentrates margin capture in subscription-anchored calibration service contracts for premium tiers while commodity panel assemblies feed price-sensitive ambulatory demand.
Pricing Analysis
Input-cost pass-through from indium electrode materials and mini-LED backlighting arrays shapes tiered pricing across DICOM-calibrated product lines. Subscription-based calibration contracts displace perpetual licenses in Texas and Florida health systems, with price differentiation driven by grayscale precision certification and enterprise fleet scale. Pricing pressure stems from tablet-based diagnostic substitution threats in outpatient clinics. Cost-constrained ambulatory operators exhibit highest price sensitivity; tertiary cardiology departments show lowest.
Supply Chain Analysis
OLED electrode fabrication rests on Chinese rare earth processing infrastructure for indium supply, while mini-LED chip production concentrates in Taiwan and South Korea. Panel module assembly draws from Shenzhen's electronics manufacturing ecosystem, with specialized calibration services anchored in Germany and Switzerland. Single-source vulnerability in indium supply creates structural exposure to export quota volatility. Distribution runs through hospital procurement consortia and integrated delivery network managed service arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Class IIa certification harmonization compounds procurement complexity for display-embedded devices, creating sustained demand for pre-validated technical files across European hospital networks.
For Market Incumbents: Deepen backward integration into mini-LED backlighting supply to offset indium cost volatility and compress OEM dependency. Anchor hospital contracts with integrated monitoring-display ecosystems that reduce interoperability friction from legacy PACS systems. Defend against tablet-based substitution by locking calibration service subscriptions into multi-year managed service arrangements. For New Entrants and Emerging Players: Home-based patient monitoring operators in Germany and Japan represent an underserved buyer archetype with reimbursement tailwinds and lower certification barriers than acute care networks. Target post-acute telemetry displays with consumer-facing form factors and clinical-grade wireless connectivity. Pursue white-label partnerships with established reimbursement strategy holders to bypass direct hospital procurement consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration service expertise concentrates in legacy radiology departments and third-party recertification channels. Long-term viability favors specialized panel calibration houses with DICOM standardization capabilities and MDR pre-validation assets. Acquisition targets should demonstrate recurring revenue density from software-locked upgrade architectures. Watch FDA cybersecurity mandate timing for networked monitoring displays as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Pre-validation | Swissmedic-aligned documentation compresses vendor shortlists for German procurement consortia. |
| Calibration Service Subscription Conversion | Perpetual-license displacement locks recurring revenue into Texas and Florida health systems. |
| Mini-LED Backlighting Integration | Local dimming arrays preserve diagnostic fidelity at compressed price points versus OLED. |
| Wireless DICOM Transmission Capability | Untethered workflow flexibility anchors point-of-care expansion in US emergency departments. |
| Home Care Reimbursement Strategy | German and Japanese post-acute shifts create demand acceleration for consumer-facing telemetry displays. |
Research Methodology
Direct dialogue with hospital procurement officers, biomedical engineers, GPO contracts managers, and diagnostic imaging department heads grounded qualitative findings in acute care workflow realities. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and IEC 60601-1 third-edition compliance records. Bottom-up and top-down triangulation reconciled unit shipment estimates with health system capital expenditure patterns.
Bottom-up modeling aggregated segment-specific adoption curves across product type, technology, and end-user dimensions, while top-down validation cross-checked aggregate market scale against reimbursement authority expenditure data. The projection horizon spans bedside monitor replacement cycles, portable ultrasound attach rates, and home care telemetry penetration. CAGRs derived from logistic diffusion curves calibrated to historical health system digitization patterns and regulatory compliance timeline impacts.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than home care estimates where consumer-electronics crossover blurs category boundaries. Forecasts reflect assumptions about EU MDR mutual recognition agreement stability and indium supply quota continuity. Regulatory timeline delays, cybersecurity mandate acceleration, and tablet-based diagnostic substitution velocity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market