
 Smart Medication Adherence Sensors Market | 2026-2036
Smart Medication Adherence Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Medication Adherence Sensors Market Analytics
Buyer concentration among integrated delivery networks is realigning procurement criteria for adherence monitoring programs. AdhereTech specializes in cloud-connected smart bottles for specialty pharmacy dispensing. Koninklijke Philips N.V. leverages its clinical informatics footprint to bundle sensors with remote patient monitoring platforms. Cardinal Health controls distribution channels that determine which sensor brands reach hospital formularies.
Smart medication adherence sensors comprise electronic devices that detect, record, and transmit patient dosing behavior through accelerometers, capacitive sensing, or pressure-sensitive microswitches, typically operating via Bluetooth Low Energy with battery lifespans exceeding twelve months. These systems generate timestamped adherence data for clinical decision support and payer reimbursement validation. Wearable devices and smart pill bottles capture the dominant share of hardware revenue, while mobile applications represent the fastest-expanding segment due to minimal per-unit deployment cost. Bluetooth-enabled products lead unit shipments, though NFC-based systems command premium positioning in European hospital settings where data security requirements are stringent.
The FDA digital health pre-certification program and HIPAA interoperability rules shape product development timelines and data architecture requirements for US market participants. EMA guidance on software as a medical device and GDPR data governance standards create parallel compliance obligations for European deployments. Stakeholders must monitor evolving payer reimbursement codes for remote therapeutic monitoring, as coverage determinations will determine which sensor form factors achieve sustainable adoption at scale.
Market Dynamics
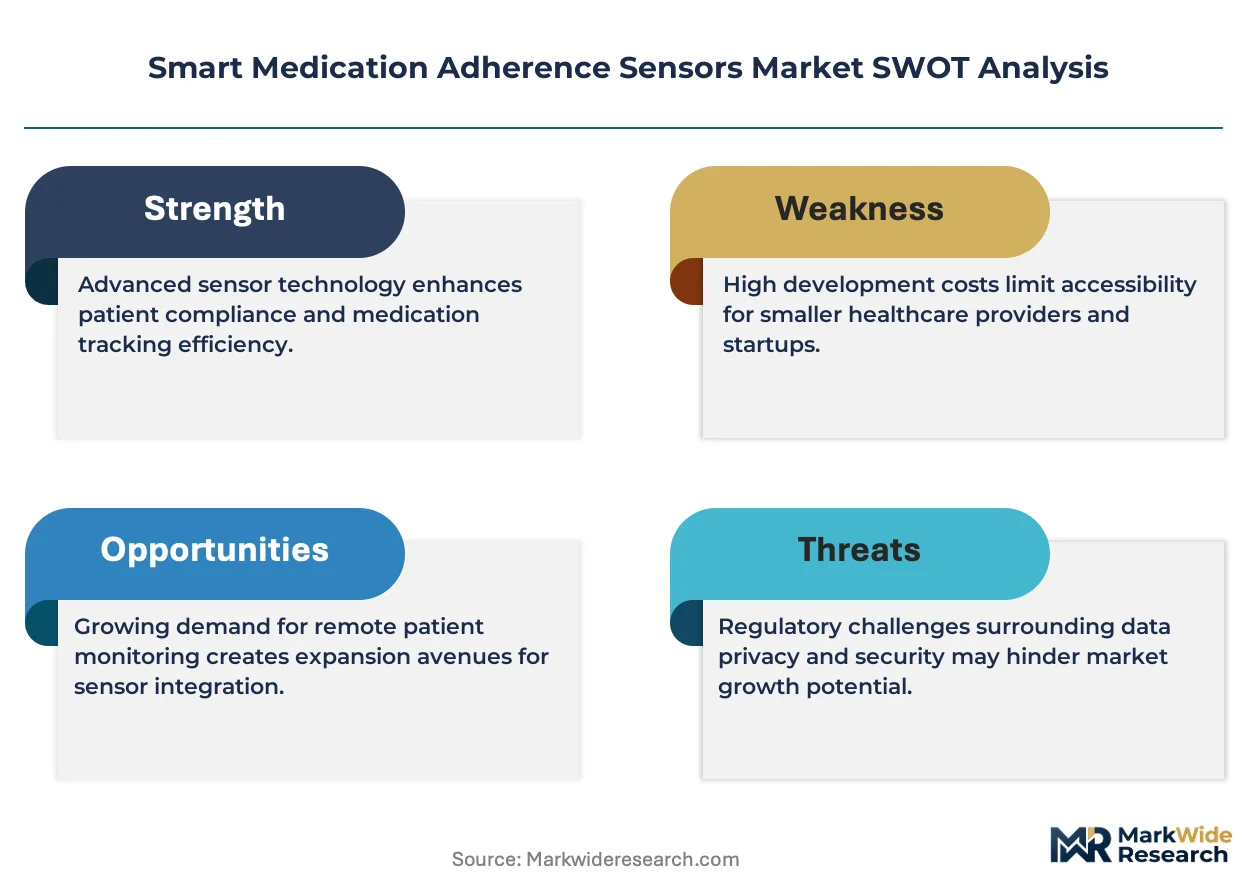
Medicare Advantage reimbursement rules now tie capitated payments to medication compliance metrics, forcing integrated delivery networks to deploy sensor-enabled adherence programs as infrastructure rather than pilot projects.
Growth Catalysts
- FDA Digital Health Pre-Certification:The streamlined clearance pathway compresses time-to-market for Bluetooth-enabled dosing monitors, accelerating hospital procurement cycles.
- Capacitive Sensing Miniaturization:Advances in microelectromechanical systems reduce per-unit sensor costs below the reimbursement threshold for remote therapeutic monitoring codes.
- Germany:EMA software-as-medical-device guidance creates regulatory clarity that hospital pharmacies in Bavaria and North Rhine-Westphalia use to justify sensor formulary inclusion.
Market Restraints
- Lithium Battery Supply Concentration:Twelve-month battery lifespans depend on cylindrical cell supply chains centered in East Asian manufacturing zones, exposing hardware vendors to input volatility.
- GDPR Data Localization:European deployments face structural cost penalties from server infrastructure requirements that fragment cloud architectures across national boundaries.
- Capacitive Interference:Humidity-sensitive microswitches in tropical climates generate false-positive dosing events, limiting hardware reliability in specific geographic bands.
Strategic Opportunities
- Brazil:ANVISA's nascent digital health framework creates first-mover positioning for NFC-based systems in São Paulo's private hospital networks before regulatory harmonization.
- Accelerometer-AI Fusion:Convergence of motion-sensing hardware with on-device inference enables pill-recognition without pharmacy repackaging, opening direct-to-patient channels.
- Remote Therapeutic Monitoring Reimbursement:CMS coverage expansion for CPT codes 98975-98978 creates sustainable revenue streams for continuous adherence data transmission.
Industry Challenges
- Embedded Firmware Talent Scarcity:Bluetooth Low Energy stack optimization requires specialized engineering capabilities concentrated in semiconductor hubs, constraining vendor scaling.
- HIPAA Interoperability Certification:Health data exchange protocols demand eighteen-month validation timelines that delay platform launches and compress effective patent windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Medication Adherence Sensors Market |
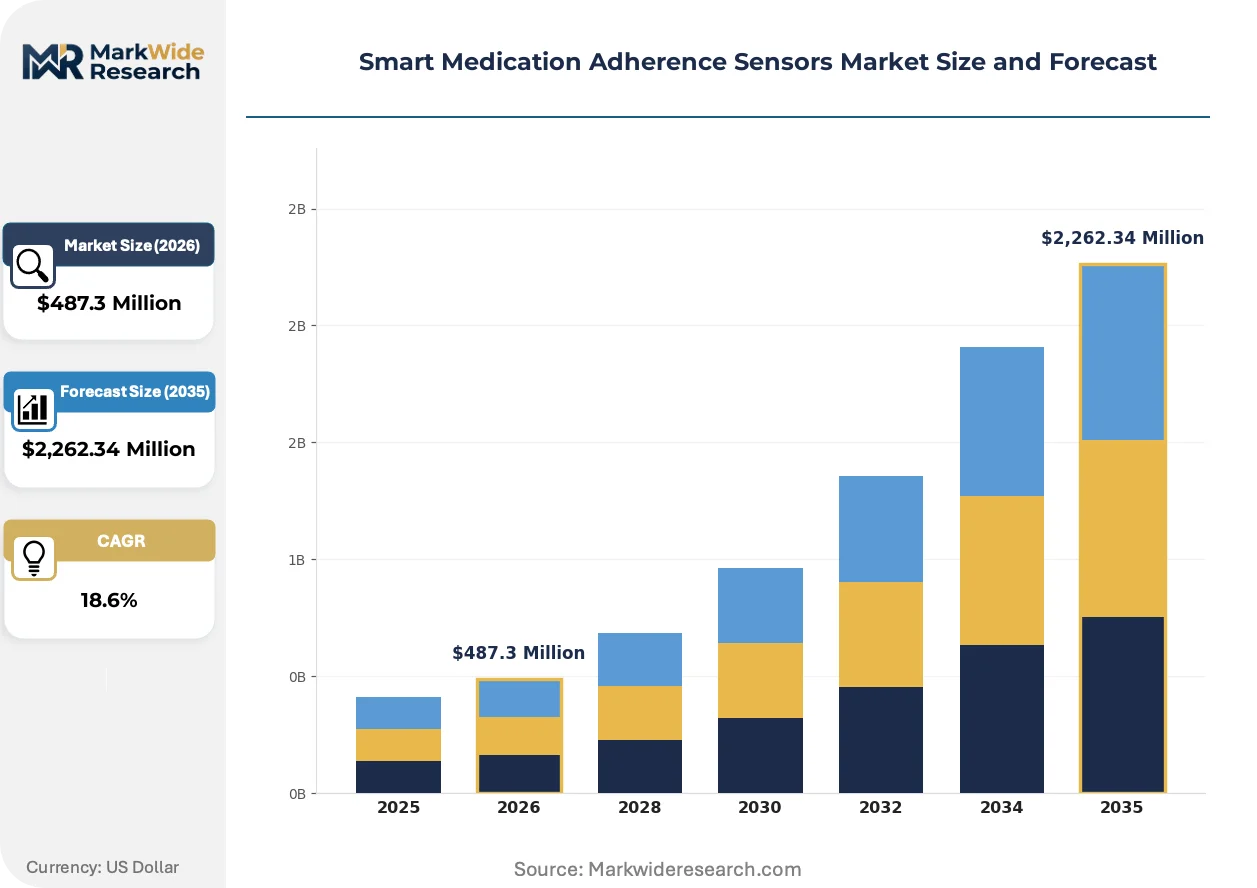
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Smart Pill Bottles, Connected Inhalers Technology: Bluetooth, RFID, NFC, IoT End User: Patients, Healthcare Providers, Pharmacies, Caregivers Application: Chronic Disease Management, Medication Management, Telehealth, Health Monitoring |
| Companies Covered | Proteus Digital Health, AdhereTech, Koninklijke Philips N.V., MedMinder Systems, PillDrill, Vitality GlowCap, Omnicell, Cardinal Health, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Medication Adherence Sensors Market Evolving Landscape
Hardware-software convergence is collapsing the traditional separation between dosing detection and clinical decision support, enabling real-time intervention loops that alter how payers measure value.
On-device machine learning inference is rewriting the economics of medication adherence monitoring. Edge-deployed neural networks now classify pill removal events without cloud transmission, reducing latency for high-acuity therapeutic areas. Oncology infusion centers in Texas and California deploy these systems to catch missed oral chemotherapy doses within four hours. The compression of data gravity toward the sensor is rewriting vendor business models from SaaS subscriptions toward hardware-plus-software bundles.
EMA's 2023 software-as-medical-device guidance clarifies classification boundaries for algorithm-driven adherence alerts. Manufacturers must now submit clinical validation data for dosing-pattern analytics that trigger caregiver notifications. German hospital systems in Baden-Württemberg delay procurement decisions pending notified body interpretations, while Dutch digital health startups accelerate MDR conformity assessments to capture first-mover positioning in the Benelux cluster.
Integrated delivery networks now unbundle adherence monitoring from specialty pharmacy contracts, creating direct procurement relationships with sensor vendors. This disintermediation bypasses traditional distribution intermediaries that controlled hospital formulary access. The purchasing behavior shift is most visible in United States Medicare Advantage regions where risk-bearing entities seek data ownership for HEDIS quality scoring.
Smart Medication Adherence Sensors Market Segmentation
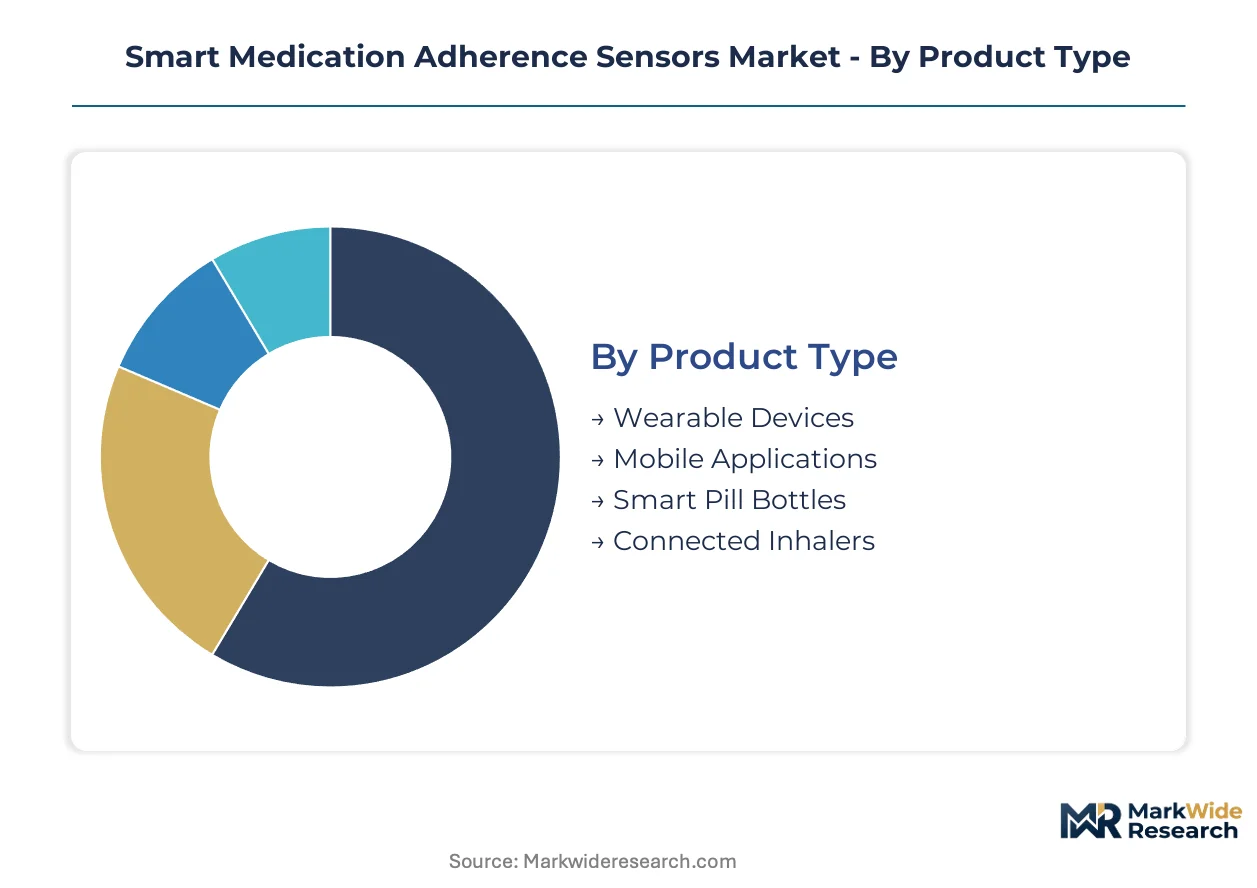
Segmentation in smart medication adherence sensors reflects divergent hardware economics and reimbursement pathways. Product form factors determine battery requirements, connectivity protocols, and deployment costs. End-user concentration shapes procurement channels and data ownership models across health systems.
Product Type:
Product architecture dictates sensor placement, power consumption, and patient interaction patterns. Wearable and bottle-based systems dominate hardware revenue due to tangible component costs and pharmacy integration workflows.
- Wearable Devices:Wrist-worn or patch-based accelerometers detect pill-handling motions through Bluetooth Low Energy transmission. Demand concentrates in Medicare Advantage regions where risk-bearing entities require continuous ambulatory monitoring for HEDIS compliance scoring.
- Smart Pill Bottles:Capacitive-sensing containers with pressure microswitches timestamp bottle openings for cloud transmission. Hospital systems in Texas and California deploy these for oral chemotherapy tracking where four-hour intervention windows are clinically critical.
- Mobile Applications:Camera-based pill recognition running on-device inference eliminates hardware procurement entirely. These solutions expand fastest in direct-to-patient channels where minimal per-unit deployment cost accelerates adoption.
- Connected Inhalers:Dose-counters with Bluetooth modules track bronchodilator usage patterns for asthma and COPD populations. These devices face longer FDA clearance timelines due to combined drug-device classification requirements.
Wearable devices lead on scale; mobile applications lead on momentum.
Technology:
Connectivity specifications determine transmission range, power draw, and security architecture for hospital network integration. Protocol selection shapes cloud infrastructure requirements and cross-border data governance compliance.
- Bluetooth:Low Energy stacks dominate unit shipments through twelve-month battery lifespans and ubiquitous smartphone pairing. German hospital pharmacies in Bavaria specify Bluetooth for EMA software-as-medical-device conformity assessments.
- NFC:Near-field protocols command premium positioning in European deployments where GDPR data localization requirements favor short-range, offline-capable systems with minimal cloud exposure.
- RFID:Passive tag systems enable bulk medication tracking through pharmacy dispensing workflows without patient smartphone dependency. These solutions concentrate in institutional settings where IT support capacity is limited.
- IoT:Cellular-connected sensors bypass smartphone intermediaries entirely, transmitting adherence data through dedicated data plans. Hardware vendors face lithium battery supply concentration risks from East Asian cylindrical cell manufacturers.
Bluetooth leads on scale; NFC leads on momentum.
End User:
Customer type determines procurement authority, data access rights, and reimbursement claim submission pathways. Integrated delivery networks are disintermediating traditional specialty pharmacy contracts to establish direct vendor relationships.
- Healthcare Providers:Hospital systems and accountable care organizations procure sensor-enabled adherence programs as infrastructure tied to capitated Medicare Advantage reimbursement. These buyers prioritize EHR interoperability and clinical decision support integration.
- Pharmacies:Specialty pharmacy dispensing operations bundle sensors with high-cost oral oncology and immunology therapies. Cardinal Health distribution channel control determines which sensor brands reach hospital formularies.
- Patients:Direct-to-consumer channels accelerate where on-device AI eliminates pharmacy repackaging requirements. Accelerometer-pill recognition fusion enables standalone deployment without healthcare system intermediation.
- Caregivers:Family members and home health aides receive automated dosing alerts through delegated mobile application access. EMA 2023 guidance requires clinical validation data for algorithm-driven notifications triggering caregiver intervention.
Healthcare providers lead on scale; patients lead on momentum.
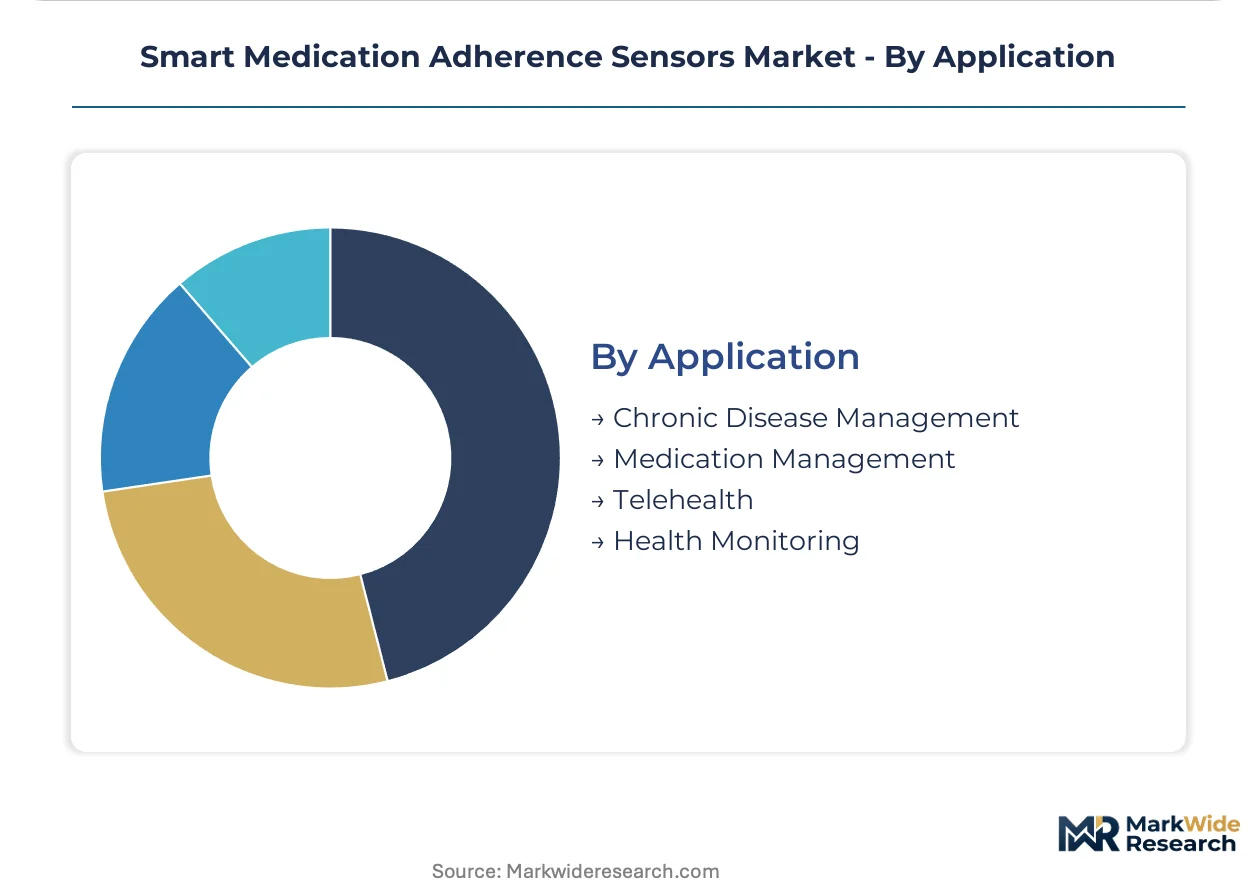
Application:
Use case specificity determines sensor accuracy requirements, alert urgency thresholds, and payer reimbursement code eligibility. Chronic conditions with high non-adherence costs justify premium hardware procurement.
- Chronic Disease Management:Diabetes, hypertension, and hyperlipidemia populations generate sustained demand through long-term medication regimens. Remote therapeutic monitoring CPT codes 98975-98978 create sustainable revenue streams for continuous data transmission.
- Medication Management:Polypharmacy coordination across multiple prescribers drives demand for unified dosing dashboards. Dutch digital health startups accelerate MDR conformity assessments to capture Benelux positioning for multi-drug adherence platforms.
- Telehealth:Virtual care models integrate sensor data for asynchronous provider review between video consultations. Humidity-sensitive capacitive microswitches generate false positives in tropical climates, limiting reliability for geographic expansion.
- Health Monitoring:General wellness applications without specific therapeutic claims face lighter regulatory burden but reduced reimbursement coverage. These solutions compete on consumer electronics margins rather than medical device economics.
Chronic disease management leads on scale; medication management leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded firmware engineers specializing in Bluetooth Low Energy stack optimization concentrate in semiconductor hubs across the United States, Germany, and Taiwan, anchoring regional development capacity for sensor-enabled adherence programs.
United States
Medicare Advantage plans tie capitated payments to medication compliance metrics, forcing integrated delivery networks to deploy sensor infrastructure. FDA digital health pre-certification compresses clearance timelines for connected dosing monitors. Texas oncology infusion centers deploy accelerometer-AI fusion systems to catch missed oral chemotherapy within four-hour intervention windows.
Germany
Hospital pharmacies in Bavaria and North Rhine-Westphalia justify sensor formulary inclusion using EMA software-as-medical-device guidance. GDPR data localization requirements favor NFC-based systems with minimal cloud exposure. Baden-Württemberg health systems delay procurement pending notified body interpretations of algorithm-driven adherence alerts.
China
NMPA medical device classification rules shape product registration pathways for Bluetooth-enabled sensors targeting hospital procurement. Domestic lithium cylindrical cell manufacturers supply twelve-month battery components. Yangtze River Delta electronics clusters produce capacitive-sensing microswitches for smart pill bottle assembly.
Netherlands
Digital health startups accelerate MDR conformity assessments to capture first-mover positioning in the Benelux cluster for multi-drug adherence platforms. Remote therapeutic monitoring reimbursement codes create sustainable revenue streams for continuous data transmission. Amsterdam health data exchanges pilot HIPAA-interoperable architectures for cross-border patient monitoring.
Brazil
ANVISA's nascent digital health framework creates positioning opportunities for NFC-based systems in São Paulo's private hospital networks. Humidity-sensitive capacitive microswitches face reliability constraints in tropical climates, limiting hardware deployment in northern states. Rio de Janeiro specialty pharmacies test direct-to-patient mobile applications with on-device pill recognition.
Smart Medication Adherence Sensors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels for sensor-enabled adherence programs. The vendor base separates into three strategic archetypes: clinical informatics platforms bundling sensors with remote monitoring, specialty pharmacy distributors controlling hospital formulary access, and hardware-software fusion specialists targeting direct-to-patient channels. Dominant competitive moves include disintermediation of traditional distribution intermediaries and backward integration into cloud-connected device manufacturing.
Among clinical informatics platforms, Koninklijke Philips N.V. and Cardinal Health occupy positions representing divergent approaches to market access—one leveraging integrated monitoring ecosystems, the other commanding distribution channels determining formulary placement. AdhereTech exemplifies the hardware-software fusion archetype, anchoring the specialist tier focused on cloud-connected smart bottles for specialty pharmacy dispensing workflows.
| Leading Market Players |
|---|
| Proteus Digital Health |
| AdhereTech |
| Koninklijke Philips N.V. |
| MedMinder Systems |
| PillDrill |
| Vitality GlowCap |
| Omnicell |
| Cardinal Health |
| McKesson Corporation |
| Others |
Value Network & Pricing Analysis
Lithium cylindrical cell costs from East Asian manufacturers cascade through three distinct pricing tiers for Bluetooth-enabled adherence hardware, with premium NFC-based systems in European hospital settings capturing margin spreads that reflect GDPR-compliant server infrastructure investments.
Pricing Analysis
Bundled hardware-plus-software subscriptions dominate hospital procurement, while unbundled per-unit transactional sales concentrate in direct-to-patient channels. Price differentiation hinges on FDA pre-certification tier and volume scale, with Medicare Advantage-integrated delivery networks commanding standard-tier rates below specialty pharmacy bundle premiums. Pricing pressure stems from capacitive sensing miniaturization compressing per-unit sensor costs below remote therapeutic monitoring reimbursement thresholds. Healthcare providers exhibit lowest price sensitivity due to capitated risk-bearing structures; individual patients in direct-to-consumer channels show highest elasticity.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta feed hub-and-spoke patterns into North American and European hospital networks. Manufacturing concentrates in China, Taiwan, and South Korea for lithium cylindrical cells, capacitive microswitches, and Bluetooth Low Energy chipsets. Raw material dependencies span lithium carbonate, rare-earth magnets for accelerometers, and medical-grade polymers for pill bottle housings. Single-source vulnerability in East Asian battery cell supply chains exposes hardware vendors to input volatility. Distribution runs through Cardinal Health-controlled channels that determine formulary placement for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA software-as-medical-device clarity in Germany enables faster procurement cycles than FDA pre-certification timelines in the United States, compressing time-to-revenue for European-focused entrants.
For Market Incumbents: Hedge against disintermediation by integrated delivery networks through backward integration into cloud-connected device manufacturing, capturing data ownership that specialty pharmacy distributors currently control. Invest in HIPAA interoperability certification to defend against emerging pure-play AI inference specialists threatening hardware-software bundle margins.
For New Entrants and Emerging Players: Accelerometer-AI fusion without pharmacy repackaging requirements offers the most penetrable wedge into direct-to-patient channels, bypassing Cardinal Health distribution gatekeeping entirely. Target Brazil's São Paulo private hospital networks before ANVISA regulatory harmonization closes first-mover positioning. Lead with mobile-first deployment to minimize per-unit capital requirements.
For Investors and Strategic Acquirers: Roll-up economics work for clinical informatics platforms because integrated delivery networks are unbundling adherence monitoring from specialty pharmacy contracts, creating fragmented vendor relationships ripe for consolidation. Target hardware-software fusion specialists with FDA-cleared devices and existing hospital formulary placement. Watch CMS remote therapeutic monitoring reimbursement code expansion as the inflection signal for sustainable revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification Pathway | Compresses clearance timelines for Bluetooth-enabled dosing monitors in Medicare Advantage regions. |
| CE Marking and MDR Conformity Assessment | Unlocks Bavarian and North Rhine-Westphalia hospital pharmacy formulary inclusion under EMA guidance. |
| Hospital System Direct Procurement Partnership | Bypasses Cardinal Health distribution intermediaries controlling traditional formulary access channels. |
| Software Companion Development | Enables real-time intervention loops that alter how payers measure value in risk-bearing contracts. |
| Reimbursement Strategy for Remote Therapeutic Monitoring | Captures sustainable revenue streams through CMS CPT codes 98975-98978 coverage expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and specialty pharmacy dispensing directors with secondary validation against FDA 510(k) filings, EMA software-as-medical-device guidance documents, CMS reimbursement code determinations, and hospital procurement database records. Bottom-up sensor shipment estimates and top-down adherence program spending analysis were triangulated for convergence.
Comparable-period anchoring used historical adoption curves from remote patient monitoring and connected inhaler categories to inform projection parameters across the analysis window. Segmentation dimensions modeled include product form factor, connectivity protocol, end-user procurement authority, and therapeutic application area. CAGRs were derived from logistic diffusion curves fitted to early-adopter hospital system deployment patterns and Medicare Advantage plan expansion trajectories. Forecast inputs incorporated lithium battery supply concentration risk and EMA notified body interpretation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement code coverage determinations, GDPR data localization cost penalties, and capacitive sensor reliability in tropical climate deployments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market