
 Respiratory Monitoring Devices Market | 2026-2036
Respiratory Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Monitoring Devices Market Outlook
The capability gap between capital-intensive platform players and focused device specialists is redrawing competitive boundaries in respiratory monitoring. Philips Healthcare leverages integrated hospital systems to sustain dominance in acute care installations. ResMed anchors its position through sleep apnea specialization and home care channel control.
Respiratory monitoring devices encompass instruments that measure pulmonary function, gas exchange, and airway mechanics through sensors detecting oxygen saturation, airflow volume, exhaled carbon dioxide, or respiratory rate with precision thresholds typically within two percent error margins. These systems serve to detect respiratory compromise, titrate therapeutic interventions, and enable longitudinal disease management across clinical and ambulatory environments. Oximeters and capnometers capture the dominant share of product-type revenue due to their ubiquity in perioperative and emergency protocols, while telehealth solutions represent the fastest-expanding technology segment as remote patient monitoring reimbursement frameworks mature. Sleep apnea and COPD applications generate the deepest margin pools among indication categories because of recurring device replacement cycles and consumable attachment revenue.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers seeking multi-regional distribution. ISO 80601-2-55 and IEC 60601-1 third editions define electrical safety and alarm performance standards that constrain design architecture for capnometers and portable monitors. Stakeholders must weigh regulatory capital commitments against the margin compression risk from emerging wearable sensor platforms that bypass traditional hardware certification pathways.
Market Dynamics
The transition from hospital-centric acute care to distributed home monitoring is restructuring capital allocation across the respiratory device value chain. Reimbursement codes for remote patient monitoring in the United States and Germany are pulling sensor manufacturers toward wireless form factors and cloud-integrated platforms.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter clinical evidence requirements for Class IIa and IIb devices are accelerating consolidation among manufacturers with robust quality management systems, favoring established players with dedicated regulatory affairs infrastructure.
- Japan's aging demographic profile:METI-backed regional care hubs in Hokkaido and Kyushu are deploying portable capnometers for post-surgical home recovery, creating dedicated procurement channels for lightweight monitoring hardware.
- Pulse oximetry miniaturization:Reflectance-mode sensors embedded in wearable patches are enabling continuous SpO2 tracking during sleep and physical therapy, expanding addressable indications beyond perioperative monitoring.
Market Restraints
- Semiconductor component concentration:Specialized analog-to-digital converters and MEMS pressure sensors source predominantly from Taiwanese and South Korean foundries, exposing device assemblers to geopolitical supply disruptions.
- EU MDR notified body capacity constraints:Limited designated organizations for respiratory device certification are extending technical file review timelines from 12 to 24 months, freezing product launches for mid-tier manufacturers.
- Consumer-grade pulse oximeter substitution:Uncertified fingertip devices retailing below $30 on e-commerce platforms are eroding price floors for clinical-grade monitors in cash-pay ambulatory settings.
Strategic Opportunities
- India's Ayushman Bharat digital health infrastructure:The national health stack's remote monitoring modules create first-mover advantages for cloud-native respiratory platforms that integrate with government-mandated electronic health record standards.
- Telehealth-integrated COPD management bundles:Payers in Germany and the Netherlands are piloting per-member-per-month contracts combining spirometers, pulse oximeters, and virtual pulmonologist access, shifting revenue from device sales to recurring platform fees.
- AI-enabled breath sound analysis:Machine learning models trained on smartphone microphone inputs are converging with traditional acoustic sensors to detect wheeze and crackle patterns without dedicated hardware.
Industry Challenges
- Biomedical signal processing expertise scarcity:Firmware engineers capable of implementing IEC 60601-1-8 alarm prioritization algorithms and motion artifact rejection protocols command premium compensation, constraining R&D expansion for regional device specialists.
- Legacy hospital IT integration complexity:HL7 FHIR interoperability requirements and proprietary electronic medical record architectures in the United States force device manufacturers to maintain fragmented software development tracks for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Monitoring Devices Market |
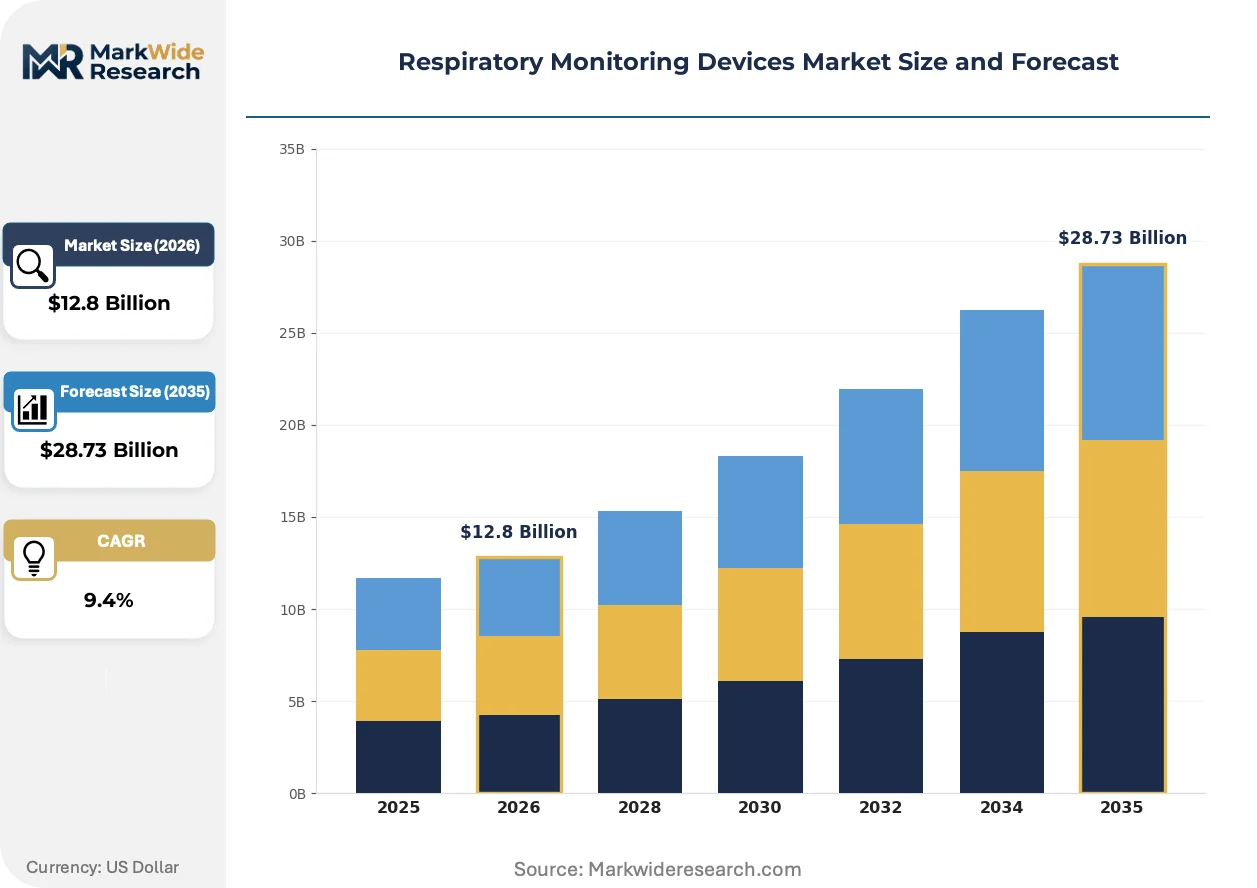
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oximeters, Spirometers, Peak Flow Meters, Capnometers End User: Hospitals, Home Care, Clinics, Rehabilitation Centers Technology: Wearable Devices, Portable Monitors, Digital Sensors, Telehealth Solutions Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Sleep Apnea, Lung Function Testing |
| Companies Covered | Philips Healthcare, ResMed, Medtronic, GE Healthcare, Drägerwerk, Masimo, Siemens Healthineers, Nihon Kohden Corporation, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Monitoring Devices Market Strategic Shifts
Sensor fusion architectures and algorithmic biomarker extraction are redefining what constitutes a respiratory monitoring device, blurring hardware boundaries between discrete instruments and software-embedded platforms.
Reflectance pulse oximetry is bifurcating the traditional transmittance-dominated market. Wearable patch manufacturers in California and Bavaria are embedding multi-wavelength LED arrays into flexible substrates for continuous monitoring during exercise and sleep. Hospital procurement committees are bifurcating their vendor rosters between established bedside monitor suppliers and emerging patch-based platforms, creating parallel certification tracks for equivalent clinical indications.
EU MDR post-market surveillance requirements are forcing manufacturers to maintain active clinical follow-up registries for devices with greater than five-year service lives. Capnometer producers must now submit periodic safety update reports to EUDAMED, increasing ongoing compliance costs. German and French notified bodies are prioritizing technical documentation for devices with embedded machine learning components, creating regulatory bottlenecks for AI-enhanced respiratory rate detection algorithms.
Home care equipment distributors are unbundling device sales from consumable provisioning and technical service contracts. Sleep apnea patients in Japan and the United States now source masks and tubing through subscription channels separate from their original diagnostic device purchase. This channel fragmentation is compressing distributor margins while creating direct-to-patient opportunities for manufacturers with established e-commerce logistics capabilities.
Respiratory Monitoring Devices Market Segmentation
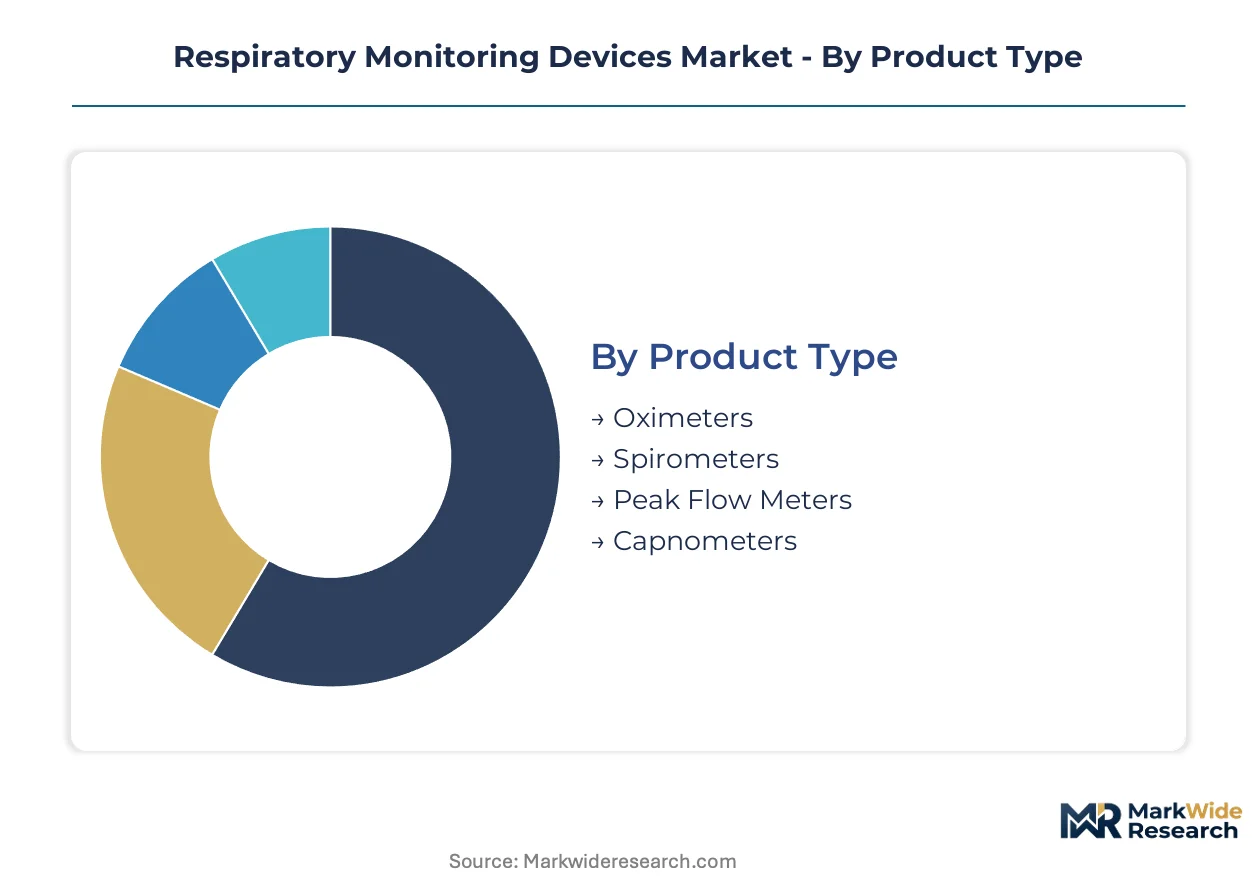
Respiratory monitoring devices fragment across four critical dimensions that determine regulatory pathways, reimbursement eligibility, and procurement channel access. Each segmentation axis carries distinct margin profiles and technical certification requirements that shape manufacturer competitive positioning.
Product Type:
FDA 510(k) clearance timelines and EU MDR technical documentation burdens vary sharply across device categories, with pulse oximetry facing streamlined review while capnometers encounter extended clinical evidence demands.
- Oximeters:Transmittance-mode fingertip sensors dominate perioperative and emergency protocols with sub-two-percent SpO2 error margins. Demand concentrates in United States hospital systems upgrading to wireless-connected bedside units, though consumer-grade substitutes erode price floors in cash-pay ambulatory settings.
- Capnometers:Sidestream and mainstream configurations measuring end-tidal CO2 require ISO 80601-2-55 electrical safety compliance and IEC 60601-1-8 alarm prioritization firmware. Japanese METI-backed regional care hubs in Hokkaido and Kyushu deploy lightweight portable variants for post-surgical home recovery, creating dedicated procurement channels.
- Spirometers:Volume-displacement and flow-sensing instruments for forced vital capacity measurement face calibration-intensive maintenance protocols.
- Peak Flow Meters:Mechanical and digital variants for asthma exacerbation detection occupy the lowest price tier with minimal regulatory burden.
Established volume favors oximeters; emerging adoption favors capnometers.
End User:
Procurement authority and reimbursement coding structures diverge fundamentally across care settings, with hospital capital budgets operating on replacement cycles while home care channels depend on durable medical equipment billing codes.
- Hospitals:Integrated health systems in Germany and the United States prioritize HL7 FHIR interoperability and proprietary EMR connectivity, forcing device manufacturers to maintain fragmented software development tracks. Acute care installations demand centralized alarm management and nurse station integration.
- Home Care:Remote patient monitoring reimbursement frameworks in the United States and Germany pull sensor manufacturers toward wireless form factors and cloud-integrated platforms. Subscription-based consumable provisioning now separates mask and tubing resupply from original diagnostic device purchase in Japan and the United States.
- Clinics:Physician office-based pulmonary function testing requires portable yet calibration-stable instrumentation.
- Rehabilitation Centers:Post-acute respiratory therapy programs demand durable equipment with simplified user interfaces for non-clinical operators.
Capital allocation tilts toward hospitals; steepest expansion trajectory belongs to home care.
Technology:
Component sourcing concentration in Taiwanese and South Korean foundries for specialized analog-to-digital converters and MEMS pressure sensors exposes device assemblers to geopolitical supply disruptions across all hardware categories.
- Wearable Devices:Reflectance-mode pulse oximetry patches embedding multi-wavelength LED arrays into flexible substrates enable continuous SpO2 tracking during exercise and sleep. Bavarian and Californian manufacturers drive form factor innovation, with hospital procurement committees now maintaining parallel vendor rosters against established bedside suppliers.
- Telehealth Solutions:Cloud-native platforms integrating with government-mandated electronic health record standards capture first-mover advantages in India's Ayushman Bharat digital health infrastructure. Per-member-per-month contracts combining spirometers, pulse oximeters, and virtual pulmonologist access are piloting in Germany and the Netherlands.
- Portable Monitors:Battery-operated capnometers and multi-parameter units serve mobile emergency response and regional care hub deployment.
- Digital Sensors:Smartphone microphone inputs converging with machine learning models for wheeze and crackle detection bypass traditional hardware certification pathways.
Hardware revenue concentrates in portable monitors; platform economics favor telehealth solutions.
Application:
Disease-specific reimbursement codes and device replacement cycles create divergent margin pools, with recurring consumable attachment revenue deepest in indications requiring longitudinal management.
- Sleep Apnea:Continuous positive airway pressure companion diagnostics and ongoing adherence monitoring generate recurring device replacement cycles and mask resupply revenue. Channel fragmentation into direct-to-patient e-commerce compresses traditional distributor margins while rewarding manufacturers with captive logistics capabilities.
- Chronic Obstructive Pulmonary Disease:Telehealth-integrated management bundles shift revenue from device sales to recurring platform fees as payers experiment with outcomes-based contracting. Spirometry and pulse oximetry combinations support exacerbation prediction algorithms.
- Asthma Management:Peak flow monitoring and trigger identification tools target pediatric and adolescent populations with lower per-patient revenue intensity.
- Lung Function Testing:Occupational health screening and pre-surgical assessment applications demand calibration traceability and regulatory documentation.
Recurring revenue depth favors sleep apnea; policy innovation momentum favors COPD.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement channels. United States hospital systems absorb premium pricing for integrated platforms, while Indian ambulatory clinics prioritize sub-$50 fingertip oximeters. German payers occupy the middle ground, balancing outcomes-based contracting with hardware durability requirements.
United States
Hospital capital budgets drive demand for wireless-connected bedside monitors with centralized alarm management. FDA 510(k) clearance pathways shape product development timelines for multi-regional manufacturers. The Boston-Cambridge corridor hosts concentrated R&D operations for reflectance-mode sensor startups.
Germany
Telehealth-integrated COPD management bundles are piloting per-member-per-month contracts combining spirometers and virtual pulmonologist access. EU MDR technical documentation requirements extend certification timelines for capnometer producers. Bavarian wearable patch manufacturers drive multi-wavelength LED array innovation.
Japan
METI-backed regional care hubs in Hokkaido and Kyushu deploy portable capnometers for post-surgical home recovery. PMDA alignment with international standards streamlines approval for devices with prior FDA clearance. Tokyo-Osaka corridor concentrates sleep apnea diagnostic device distribution.
India
Ayushman Bharat digital health infrastructure creates first-mover advantages for cloud-native respiratory platforms integrating with government-mandated electronic health record standards. CDSCO device registration requirements apply increasing scrutiny to imported pulse oximeters. Karnataka and Maharashtra host emerging telehealth platform development clusters.
China
NMPA Class II medical device registration drives domestic manufacturers toward in-house sensor production to reduce Taiwanese foundry dependency. Dual carbon goals accelerate battery technology requirements for portable monitors. Shenzhen and Shanghai concentrate contract manufacturing for export-oriented pulse oximetry.
Respiratory Monitoring Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in respiratory monitoring. Hospital systems procurement favors vendors with established EMR connectivity and centralized service networks. Three archetypes dominate: diversified health technology conglomerates with platform breadth, sleep-focused specialists with home care channel control, and component-scale sensor manufacturers with foundry relationships. Competitive moves concentrate on regulatory capacity building for EU MDR compliance and cloud platform integration for remote patient monitoring reimbursement capture.
Within the integrated health technology tier, Philips Healthcare and GE Healthcare exemplify platform-scale positioning through acute care installation dominance and health system IT integration. ResMed occupies a distinct specialist position anchored in sleep apnea verticalization and home care logistics control. Siemens Healthineers represents the European-centered archetype with regulatory affairs infrastructure optimized for EUDAMED compliance and notified body relationships.
| Leading Market Players |
|---|
| Philips Healthcare |
| ResMed |
| Medtronic |
| GE Healthcare |
| Drägerwerk |
| Masimo |
| Siemens Healthineers |
| Nihon Kohden Corporation |
| Fisher & Paykel Healthcare |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and EU MDR technical documentation requirements simultaneously gate supplier qualification and stratify price tiers across the respiratory monitoring landscape. Manufacturers bearing these certification burdens capture premium positioning in hospital procurement channels, while uncertified consumer-grade alternatives erode price floors in cash-pay ambulatory segments.
Pricing Analysis
Consumable attachment revenue and extended service contracts drive lifetime value in respiratory monitoring, with sleep apnea mask resupply subscriptions and capnometer calibration programs generating recurring income streams. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wireless bedside monitors from basic fingertip oximeters and uncertified e-commerce imports. Cost compression in the consumer-tier segment is intensifying because sub-$30 fingertip devices from unbranded manufacturers bypass clinical-grade certification costs. Hospital systems in the United States absorb the highest price points for HL7 FHIR-integrated platforms, while Indian ambulatory clinics exhibit acute price sensitivity favoring disposable-grade instrumentation.
Supply Chain Analysis
Taiwan and South Korea anchor production of specialized analog-to-digital converters and MEMS pressure sensors that device assemblers draw from for capnometer and pulse oximetry fabrication. Chinese contract manufacturers in Shenzhen and Shanghai concentrate final assembly for export-oriented fingertip oximeters, while German and Japanese facilities handle precision calibration for clinical-grade spirometers. Single-source vulnerability concentrates in Taiwanese foundry capacity for biomedical-grade ADCs, exposing device producers to geopolitical disruption. Distribution runs through hospital GPO contracts in the United States, specialized durable medical equipment distributors in Germany, and direct-to-patient e-commerce channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineers capable of implementing IEC 60601-1-8 alarm prioritization algorithms command premium compensation, constraining R&D expansion and consolidating advantage among incumbents with captive biomedical signal processing expertise.
For Market Incumbents: Compound regulatory affairs infrastructure investments to extend EU MDR certification timelines as a competitive moat against mid-tier challengers. Deepen backward integration into MEMS sensor production to reduce Taiwanese foundry dependency. Prioritize cloud platform integration for remote patient monitoring reimbursement capture in Germany and the United States. For New Entrants and Emerging Players: FDA 510(k) clearance for predicate devices offers accelerated pathways into hospital procurement channels without full clinical trial burdens. Target India's Ayushman Bharat digital health infrastructure as the most penetrable geography, where cloud-native platforms integrating with government-mandated electronic health record standards capture first-mover positioning. Pursue direct-to-patient e-commerce logistics as the primary go-to-market angle to bypass fragmented distributor networks in sleep apnea consumables. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled respiratory rate detection algorithms as German and French notified bodies prioritize technical documentation for embedded machine learning components. Long-term viability over the coming decade rests on acquiring specialist firms with established notified body relationships and active EUDAMED registries. Watch EU MDR notified body capacity constraints as the critical inflection signal—extended technical file review timelines from 12 to 24 months freeze product launches and compress valuations for mid-tier manufacturers awaiting certification.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates consolidation by favoring manufacturers with dedicated regulatory affairs infrastructure and quality management systems. |
| Cloud-Native Platform Development | Captures remote patient monitoring reimbursement codes in the United States and Germany through wireless form factor integration. |
| Reflectance-Mode Sensor Miniaturization | Enables continuous SpO2 tracking during sleep and physical therapy, expanding addressable indications beyond perioperative monitoring. |
| Backward Integration into MEMS Production | Reduces exposure to Taiwanese and South Korean foundry concentration for specialized pressure sensors and analog converters. |
| AI-Enabled Breath Sound Analysis | Converges smartphone microphone inputs with machine learning models to detect wheeze patterns without dedicated hardware certification. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR EUDAMED registries, hospital GPO contract filings, and CMS Medicare reimbursement code updates. Clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided qualitative input on procurement criteria and interoperability requirements. Bottom-up unit economics triangulate against top-down market sizing from regulatory filing volumes and import-export customs data.
Segmentation dimensions modeled span product type, end user setting, technology platform, and application indication across the projection horizon. CAGRs derive from fitted growth curves applied to historical shipment data and reimbursement code expansion trajectories. Forecast inputs incorporate EU MDR certification timeline assumptions and remote patient monitoring policy evolution in Germany and the United States.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement code expansion and stable foundry supply conditions would require recalibration. Forecasts reflect documented assumptions regarding regulatory capacity and procurement channel evolution. Recalibration cycles align with material shifts in EU MDR notified body capacity and CMS remote monitoring policy frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
South America Respiratory Monitoring Market