
 Asia Pacific Rail Freight Transport Market | 2026-2036
Asia Pacific Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Rail Freight Transport Market Outlook
Heavy-haul specification upgrades is bifurcating the Asia Pacific rail freight landscape into high-capacity mineral corridors and precision-scheduled intermodal networks. China State Railway Group Co. Ltd. leverages its monopoly over trunk lines to dominate bulk coal and ore movements across the PRC interior. Aurizon Holdings Ltd. anchors Queensland's metallurgical coal export chain through vertically controlled track and terminal assets. Japan Freight Railway Co. competes on time-definite container services between Tokyo and Osaka manufacturing belts.
Rail freight transport encompasses the movement of goods via steel-wheel-on-rail systems operating at axle loads ranging from 25 to 40 tonnes, utilizing diesel-electric, pure electric, or hybrid traction across standard, broad, and narrow gauge networks to serve industrial supply chains. The primary commercial purpose centers on lowering tonne-kilometer costs for bulk commodities and reducing highway congestion for containerized manufactured goods. Intermodal services now capture the fastest expansion as manufacturers and retailers shift container volumes from road to rail for cost and emissions compliance. Bulk transport retains the largest revenue pool, particularly across Australian iron ore and Indonesian coal corridors where dedicated heavy-haul infrastructure locks in long-term contracts. Container services show margin concentration at port-rail interface terminals where Qube Holdings Ltd. and Pacific National Group battle for stevedoring and landside control.
MIIT dual carbon targets in China mandate progressive electrification of mainline freight routes, while India's CEA grid integration standards shape locomotive procurement for the Dedicated Freight Corridor. Australia's national rail safety regulator enforces fatigue management and track access protocols that determine operator licensing across interstate networks. Stakeholders must monitor how Indonesia's PT Kereta Api Indonesia navigates gauge standardization across the Trans-Sumatra and Trans-Java corridors to unlock agricultural and mining hinterlands previously served only by road.
Market Dynamics
China's MIIT dual carbon mandates are forcing wholesale electrification of heavy-haul corridors, while India's Dedicated Freight Corridor network locks in decades of infrastructure investment that reshapes operator economics across the subcontinent.
Growth Catalysts
- MIIT Electrification Mandates:China's dual carbon goals mandate progressive diesel-to-electric locomotive conversion across coal and ore trunk lines, accelerating fleet turnover and grid-tied infrastructure deployment.
- Iron Ore Export Expansion:Western Australian mining majors are extending contracted rail haulage volumes to port terminals, cementing heavy-haul as the dominant mode for bulk mineral export chains.
- Dedicated Freight Corridor Network:India's Delhi-Mumbai and Delhi-Kolkata freight-only lines eliminate passenger conflicts, cutting transit times and attracting containerized manufacturing cargo from road.
Market Restraints
- Copper and Rare Earth Input Volatility:Traction motor and battery supply chains concentrate in Chinese processing facilities, exposing operators to price swings in lithium and permanent magnet materials.
- Gauge Fragmentation:Indonesia's Trans-Sumatra and Trans-Java networks operate mixed narrow and standard gauge, forcing transshipment costs that erode rail's cost advantage over road for agricultural commodities.
- Last-Mile Road Substitution:Container movements under 500 kilometers face persistent competition from flexible trucking networks, particularly in Japan's fragmented domestic distribution.
Strategic Opportunities
- Philippines Agricultural Corridors:Mindanao and Luzon rail rehabilitation presents first-mover advantages for bulk grain and fertilizer movements currently captive to inter-island trucking and short-sea shipping.
- Battery-Electric Hybrid Traction:Convergence of lithium-ion storage and regenerative braking systems enables partial electrification of non-wired branch lines without full catenary investment.
- CEA Grid Integration Standards:India's Central Electricity Authority protocols create procurement preference for domestically manufactured electric locomotives, favoring local assembly joint ventures.
Industry Challenges
- Locomotive Technician Scarcity:Traction motor maintenance and high-voltage systems repair skills lag fleet expansion across Indian and Southeast Asian operator workforces.
- Intermodal Terminal Integration:Legacy port-rail interfaces require synchronized crane and track upgrades to handle longer container trains without dwell time penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Rail Freight Transport Market |
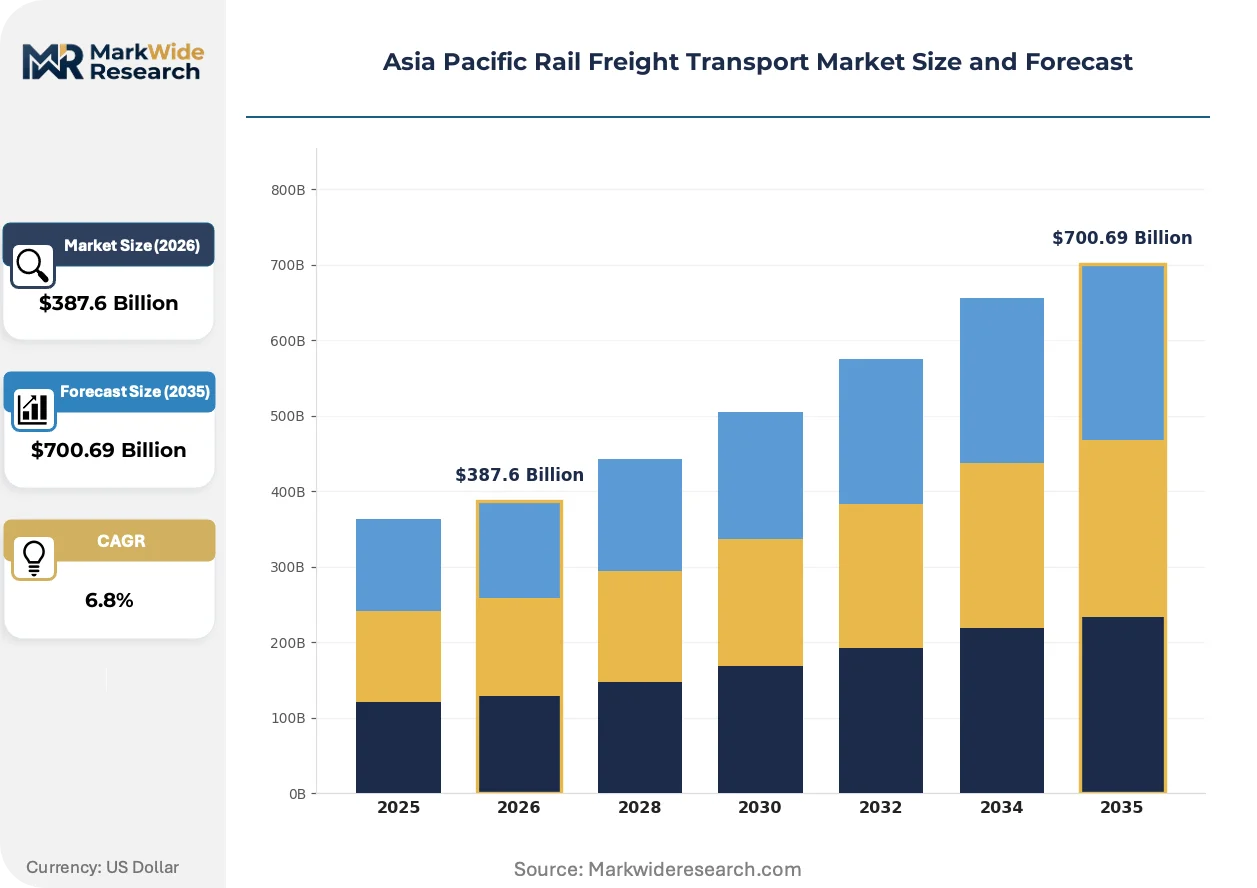
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Intermodal, Bulk Transport, Container Services, Freight Forwarding End User: Manufacturers, Distributors, Retailers, E-commerce Cargo Type: Automotive Parts, Machinery, Building Materials, Chemicals Fuel Type: DIESEL, Electricity, Hybrid, LNG |
| Companies Covered | China State Railway Group Co. Ltd., Aurizon Holdings Ltd., Japan Freight Railway Co., Indian Railways, Pacific National Group, PT Kereta Api Indonesia, Qube Holdings Ltd., KiwiRail Ltd., Korea Railroad Corporation (KORAIL), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Rail Freight Transport Market Strategic Shifts
Automation and energy transition technologies are compressing operating costs while regulatory carbon budgets force asset replacement cycles shorter than historical locomotive lifespans.
Autonomous heavy-haul operation is supplanting two-person crew configurations across Australian iron ore and Queensland coal networks. Rio Tinto and BHP have deployed driverless electric locomotives on dedicated mine-to-port lines since 2019. This shift is compressing labor cost structures and enabling 24-hour continuous operation without fatigue-protocol interruptions.
MIIT dual carbon targets in China mandate complete electrification of designated heavy freight corridors by 2030, with diesel locomotives restricted to emergency backup and non-electrified branch lines. Coal transport volumes dominate affected routes, pushing China State Railway Group to accelerate procurement of 25-tonne axle-load electric units. Suppliers are responding with localized battery-electric hybrid designs for last-mile segments beyond catenary reach.
Shipper consolidation around large retail and manufacturing accounts is consolidating procurement power at the expense of fragmented freight forwarders. Direct rail contracts now bypass traditional intermediaries on major corridors. This concentration is most visible in South Korea's Busan-Seoul manufacturing belt, where Samsung and Hyundai affiliates negotiate dedicated block train schedules directly with Korail.
Asia Pacific Rail Freight Transport Market Segmentation
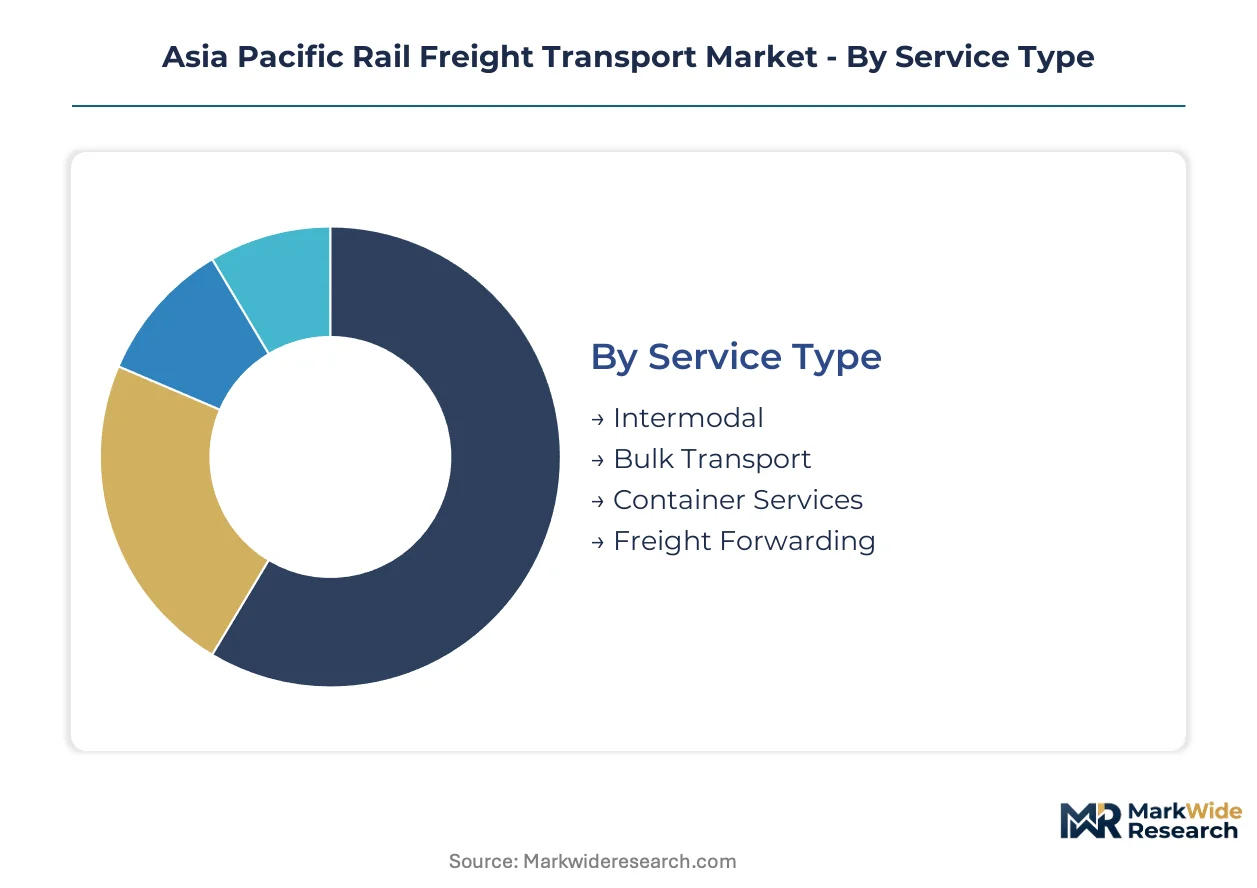
Segmentation reveals how margin pools concentrate differently across heavy-haul bulk corridors versus precision-scheduled container networks. Each dimension exposes distinct procurement patterns and infrastructure investment priorities.
Service Type:
Margin concentration diverges sharply between long-term contracted bulk movements and spot-priced intermodal services.
- Intermodal:Combines rail trunk haul with drayage and short-sea feeder connections through standardized container units. Demand concentrates in South Korea's Busan-Seoul manufacturing belt where Samsung and Hyundai affiliates negotiate dedicated block train schedules directly with Korail.
- Bulk Transport:Moves unpackaged commodities via dedicated hopper cars and gondolas at 32-40 tonne axle loads across heavy-haul infrastructure. Western Australian iron ore corridors and Queensland metallurgical coal chains lock in decades of contracted volume through vertically controlled track and terminal assets.
- Container Services:Unitized cargo movements in standard ISO containers compete aggressively at port-rail interface terminals where crane synchronization determines dwell time penalties.
- Freight Forwarding:Third-party logistics coordination aggregates fragmented shipper demand into trainload consignments across shared rail infrastructure.
The dominant share belongs to Bulk Transport, while Intermodal is closing the gap fastest.
End User:
Customer scale determines contract structure and pricing leverage across the Asia Pacific rail freight network.
- Manufacturers:Automotive and electronics producers source components through time-definite rail schedules synchronized with just-in-line assembly plants. Japan Freight Railway Co. competes on precision container services between Tokyo and Osaka manufacturing belts.
- Distributors:Wholesale intermediaries consolidate less-than-trainload shipments into block trains through freight forwarding arrangements.
- Retailers:Big-box and grocery chains shift domestic container volumes from road to rail for cost and emissions compliance.
- E-commerce:Parcel and small-package networks require last-mile road substitution for final delivery, limiting pure rail capture.
Manufacturers command the largest contract values, though Retailers are expanding rail procurement most aggressively.
Cargo Type:
Commodity density and handling requirements shape equipment specification and corridor economics.
- Automotive Parts:High-value, time-sensitive components move in covered wagons with shock-absorbing suspension across dedicated automotive logistics corridors.
- Machinery:Oversized and heavy-lift equipment demands specialized flatcars with distributed loading configurations and route clearance planning.
- Building Materials:Cement, steel, and construction aggregates move in open-top wagons with pneumatic unloading systems across India's Dedicated Freight Corridor network linking Delhi to Mumbai and Kolkata.
- Chemicals:Hazardous and temperature-controlled liquids require tank cars meeting pressure vessel standards and emergency response protocols.
Building Materials generates the highest tonnage volumes, while Automotive Parts delivers the steepest margin per tonne-kilometer.
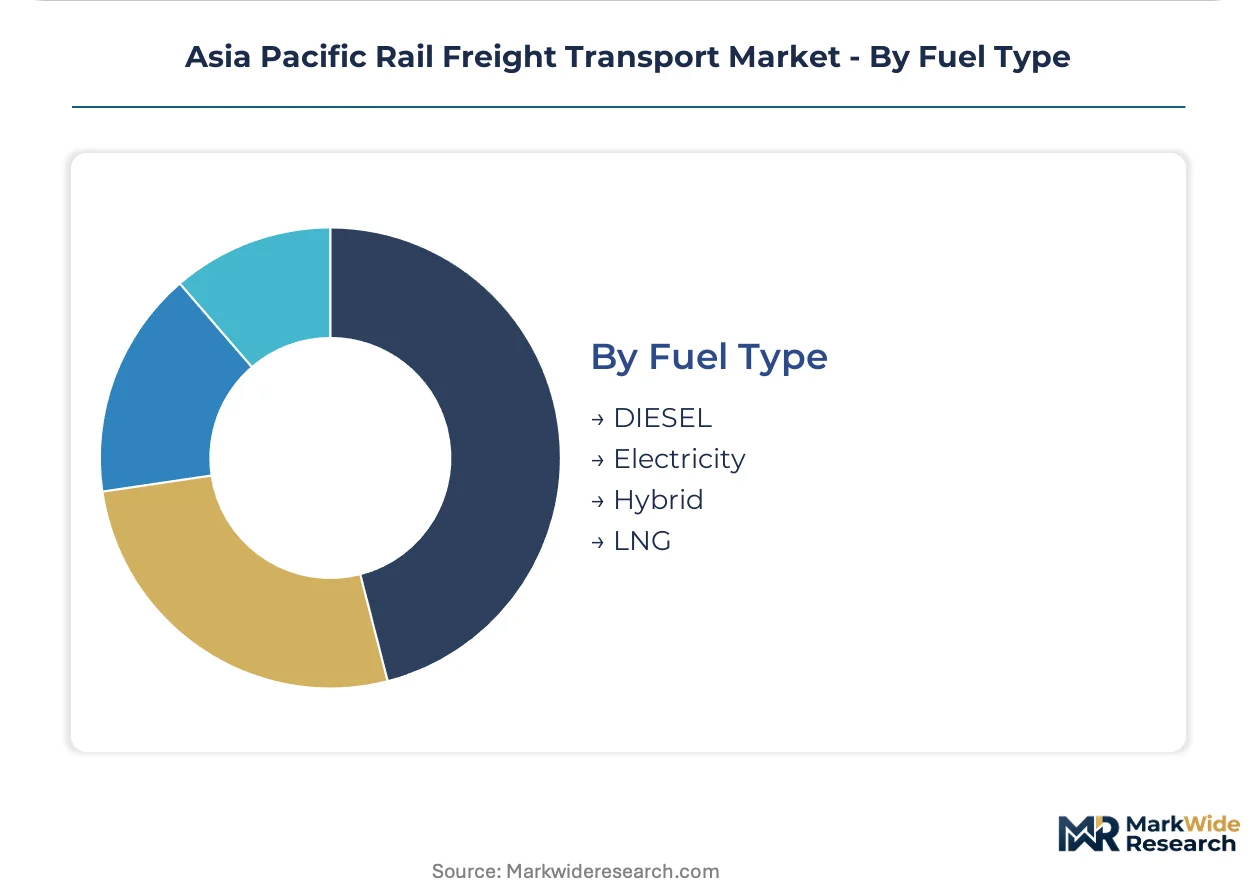
Fuel Type:
Energy transition mandates are reconfiguring fleet procurement and infrastructure investment timelines.
- DIESEL:Compression-ignition locomotives with 3,000-4,500 horsepower ratings retain dominance across non-electrified branch lines and emergency backup roles.
- Electricity:Grid-tied catenary systems power 25-tonne axle-load freight units across China's coal and ore trunk lines under MIIT dual carbon mandates mandating complete corridor electrification.
- Hybrid:Battery-electric configurations with regenerative braking enable partial electrification of non-wired segments without full catenary investment.
- LNG:Liquefied natural gas traction reduces particulate emissions across long-haul corridors where electrification remains uneconomic.
Electricity holds the dominant installed base, though Hybrid systems are gaining procurement preference fastest for branch line modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail freight infrastructure concentrates along mineral export corridors and manufacturing belts across the Asia Pacific. State-controlled operators dominate trunk line access, while private contractors battle for terminal and last-mile services.
China
Coal transport volumes from Shanxi and Inner Mongolia drive electrification investment across 25-tonne axle-load corridors. MIIT dual carbon mandates mandate complete diesel-to-electric conversion on designated heavy freight routes by 2030. The Beijing-Tianjin-Hebei cluster anchors steel and construction material movements through grid-tied catenary systems.
Australia
Western Australian iron ore majors extend contracted rail haulage volumes to port terminals, cementing heavy-haul dominance for bulk mineral exports. The national rail safety regulator enforces fatigue management protocols that determine operator licensing across interstate networks. Queensland's metallurgical coal chains lock in decades of volume through vertically controlled track and terminal assets.
India
The Dedicated Freight Corridor network linking Delhi to Mumbai and Kolkata eliminates passenger conflicts, cutting transit times for containerized manufacturing cargo. CEA grid integration standards shape electric locomotive procurement preferences favoring domestic assembly joint ventures. Gujarat and Maharashtra industrial zones anchor automotive component and building material movements across the western dedicated corridor.
Japan
Precision-scheduled container services between Tokyo and Osaka manufacturing belts compete on time-definite reliability for automotive and electronics producers. METI industrial policy supports modal shift incentives that reduce highway congestion for containerized manufactured goods. The Kanto and Kansai clusters dominate high-value component logistics requiring shock-absorbing suspension wagons.
Indonesia
Trans-Sumatra and Trans-Java corridor rehabilitation targets agricultural and mining hinterlands previously served only by road. Mixed narrow and standard gauge networks force transshipment costs that erode rail's cost advantage for bulk commodities. PT Kereta Api Indonesia navigates gauge standardization challenges to unlock captive freight volumes across the archipelago.
Asia Pacific Rail Freight Transport Market Competitive Environment
Concentration sits with state-controlled trunk line operators who control access to heavy-haul corridors and intermodal terminals. The competitive structure bifurcates between integrated mineral export chains and precision container networks serving manufacturing belts. Two archetypes dominate: vertically integrated heavy-haul specialists controlling track and terminal assets, and precision intermodal operators competing on schedule reliability. Capacity expansion and strategic partnerships constitute the primary competitive moves, particularly around port-rail interface terminals.
Among Asia Pacific operators, China State Railway Group Co. Ltd. and Aurizon Holdings Ltd. exemplify the heavy-haul archetype through control of mineral export corridors. Japan Freight Railway Co. occupies a distinct position in precision-scheduled container services. These three entities anchor competitive positioning across the region's divergent freight segments without overlapping strategic territories.
| Leading Market Players |
|---|
| China State Railway Group Co. Ltd. |
| Aurizon Holdings Ltd. |
| Japan Freight Railway Co. |
| Indian Railways |
| Pacific National Group |
| PT Kereta Api Indonesia |
| Qube Holdings Ltd. |
| KiwiRail Ltd. |
| Korea Railroad Corporation (KORAIL) |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Western Australian iron ore miners and dedicated rail operators lock in both supply access and price visibility across heavy-haul corridors, insulating bulk transport from spot market volatility while binding operators to fixed asset utilization commitments. China's MIIT dual carbon mandates further cement this structure by mandating electrification investments that embed cost recovery into decade-long tariff agreements.
Pricing Analysis
CEA grid integration standards dictate the pricing tier structure for India's Dedicated Freight Corridor network, separating premium electrified slots from diesel-backup schedules. Three-tier pricing structure across premium, standard, and economy levels reflects locomotive axle-load capacity, transit time guarantees, and terminal priority access. Cost compression in standard-tier container services is intensifying because Pacific National Group and Qube Holdings Ltd. battle for port-rail interface control. Manufacturers command the least price sensitivity due to just-in-line assembly dependencies, while agricultural distributors exhibit highest elasticity to rate fluctuations.
Supply Chain Analysis
Strait of Malacca transit underwrites critical mineral feedstock flows for traction motor manufacturing across the Asia Pacific rail freight network. Permanent magnet materials concentrate in Chinese processing facilities, lithium-ion cell production clusters in South Korea and Japan, and steel rail fabrication anchors in India and China. Single-source vulnerability in rare earth separation exposes operators to supply disruption. Distribution runs through vertically controlled mine-to-port chains in Australia and state-monopolized trunk line access in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific rail freight market sits at a platform-economics inflection where interoperability standards across India's Dedicated Freight Corridor and China's MIIT-mandated electrification protocols reshape competitive moats around data-integrated scheduling systems rather than pure asset ownership.
For Market Incumbents: Fortify contract renewal cycles by embedding predictive maintenance telemetry into long-term offtake agreements with Western Australian mining majors, while accelerating backward integration into battery-electric hybrid locomotive assembly through joint ventures with Chinese suppliers to counter emerging technology displacement from autonomous rail platforms.
For New Entrants and Emerging Players: Lead with terminal-centric business models targeting underdeveloped port-rail interfaces in Indonesia's Trans-Sumatra corridor, where gauge standardization delays create white-space for flexible intermodal operators willing to absorb transshipment complexity in exchange for agricultural commodity volume capture.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated heavy-haul specialists with captive mineral export chains over fragmented freight forwarders. Long-term viability hinges on exposure to electrification capex cycles rather than diesel fleet residual value. Watch for CEA procurement preference shifts toward domestic assembly joint ventures as the inflection signal for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Infrastructure Partnership | MIIT mandates accelerate grid-tied corridor deployment across Shanxi coal routes. |
| Autonomous Operations Licensing | Rio Tinto's driverless locomotive protocols establish regulatory precedent for Australian networks. |
| Terminal Interface Modernization | Crane synchronization investments at Brisbane and Port Hedland reduce dwell time penalties. |
| Gauge Standardization Consortium | PT Kereta Api Indonesia coordinates Trans-Java agricultural corridor interoperability. |
| Battery-Electric Hybrid Procurement | CEA standards favor domestic assembly joint ventures for branch line modernization. |
Study Parameters
A spread of perspectives from rail operator fleet managers, mining company logistics directors, port terminal operators, and CEA regulatory officials converged on the working assumptions driving this analysis. Primary interviews across these stakeholder categories combined with secondary validation from Indian Railways annual reports, Australian Rail Track Corporation safety filings, China State Railway Group procurement disclosures, and MIIT electrification directives. Bottom-up volume modeling across corridor-specific tonnage and top-down macroeconomic triangulation anchored the market sizing framework.
Segmentation dimensions modeled include service type, cargo category, fuel technology, and end-user scale across the projection horizon. CAGRs derived from historical volume trajectories weighted against infrastructure investment pipelines and regulatory mandate timelines. Specific forecast inputs incorporated Dedicated Freight Corridor completion schedules and Western Australian iron ore export expansion commitments.
The analysis sits within stated boundaries; outcomes outside sustained mineral demand and electrification subsidy continuity would require recalibration. Forecasts reflect assumptions around gauge standardization progress and rare earth supply chain stability. Practitioners should keep alternative scenarios live as Indonesia's Trans-Sumatra corridor development and Philippines agricultural rail rehabilitation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global Train Control and Management Systems Market
Railway
Railway Overhead Catenary System Market
Railway
Hydrogen Trains Market
Railway
India Rail Freight Transport Market
Railway
Solar Powered Train Market
Railway
Check Rails Market
Railway
Automatic Train Operation System Market
Railway
Railway Automated Inspection Equipment Market
Railway
Railway System Market
Railway
Train Bogie Market
Railway
Automatic Train Control Market
Railway
Rail Brace Market
Railway
Railcar Vehicle Toilet Market
Railway
Train Suspension System Market
Railway
Rolling Stocks Market
Railway
South Africa Rail Freight Transport Market