
 Asia-Pacific Industrial Centrifuge Market | 2026-2036
Asia-Pacific Industrial Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Centrifuge Market Outlook
Direct distribution from OEMs to large chemical and pharmaceutical processors is rewriting how industrial centrifuge procurement flows across the Asia-Pacific region. Alfa Laval AB leverages its disc-stack technology leadership to sustain premium positioning in biopharma applications. Jiangsu Huada Centrifuge Co., Ltd. anchors its competitive stance through manufacturing scale and cost-optimized decanter systems for China's domestic wastewater sector. KUBOTA Corporation dominates sludge dewatering segments with specialized equipment engineered for municipal treatment plants.
An industrial centrifuge is a rotating mechanical device that generates centrifugal force typically between 1,000 and 20,000 G to separate components of differing densities within a fluid mixture. The equipment serves essential functions in solid-liquid separation, liquid-liquid extraction, and clarification across process industries where gravitational settling proves impractical. Decanter centrifuges command the largest installed base due to continuous-flow operational efficiency in high-volume wastewater and chemicals processing. Disc-stack technology leads pharmaceutical applications where cell harvesting and protein purification demand precise separation control. Basket centrifuges retain relevance in batch-oriented food processing despite slower throughput characteristics.
Japan's METI enforces JIS standards governing mechanical vibration limits and energy efficiency ratings for industrial rotating equipment sold domestically. China's SAMR administers GB standards for pressure vessel integrity and environmental emissions that determine market access for centrifuge manufacturers. India's CEA imposes electrical safety and energy consumption benchmarks on industrial equipment deployed in pharmaceutical and chemical facilities. Stakeholders must monitor evolving certification requirements across these jurisdictions while aligning product development with sector-specific separation demands in bioprocessing and environmental remediation.
Market Dynamics
China's tightening GB standards for mechanical safety and environmental compliance are forcing equipment certification upgrades across the Asia-Pacific industrial centrifuge supply base. Pharmaceutical manufacturers expanding bioprocessing capacity in India and China are driving demand for precision separation equipment that meets evolving regulatory thresholds.
Growth Catalysts
- Biosimilar manufacturing scale-up:Pharmaceutical clusters around Hyderabad and Ahmedabad are installing high-capacity disc-stack centrifuges for cell harvesting and protein purification operations.
- GB standards enforcement:China's SAMR-administered pressure vessel integrity and emissions requirements are mandating equipment replacement cycles in chemicals and wastewater processing.
- Municipal wastewater investment:Sludge dewatering capacity expansion across Southeast Asian urban centers is pulling continuous-flow decanter centrifuge deployments.
Market Restraints
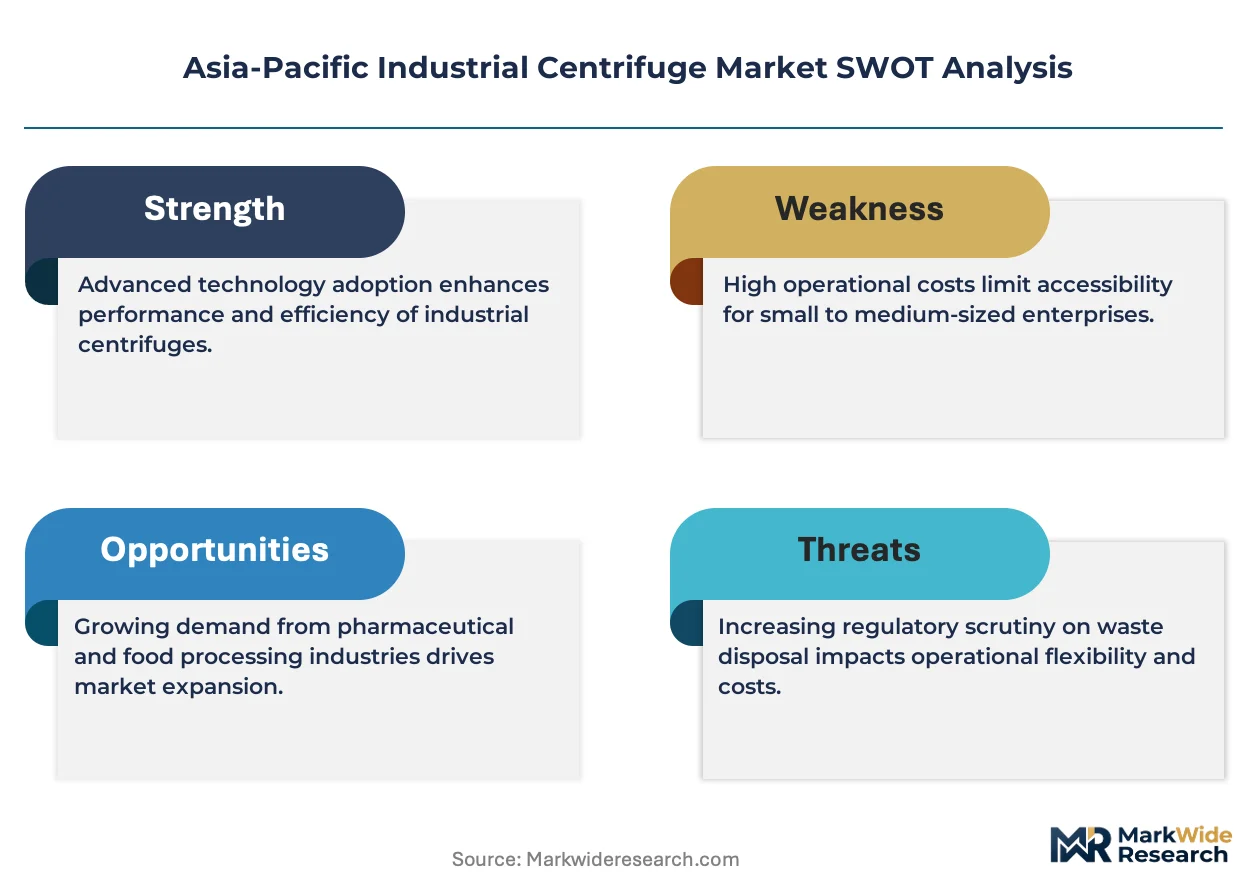
- Stainless steel alloy volatility:Centrifuge bowl and scroll fabrication depends on specialty austenitic grades subject to nickel and molybdenum price swings.
- Core component import concentration:High-precision bearings and variable frequency drives for pharmaceutical-grade equipment concentrate in German and Japanese supplier networks.
- Disc-stack throughput ceilings:Cell culture densities beyond certain thresholds exceed conventional disc-stack separation efficiency, creating processing bottlenecks.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing:Greenfield API facilities in Ho Chi Minh City industrial zones lack established centrifuge service infrastructure, creating first-mover positioning potential.
- Dual carbon alignment:China's MEE energy efficiency mandates for rotating equipment are accelerating demand for regenerative drive systems and heat recovery integration.
- Remote monitoring convergence:Vibration analysis telemetry married to predictive maintenance platforms is enabling service contract unbundling for municipal wastewater operators.
Industry Challenges
- Certification timeline compression:China's evolving GB standards for environmental emissions require re-validation of existing equipment certifications, extending sales cycles.
- Bioprocessing integration complexity:Single-use upstream technologies in cell therapy manufacturing demand centrifuge systems compatible with disposable fluid paths, complicating legacy equipment retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Centrifuge Market |
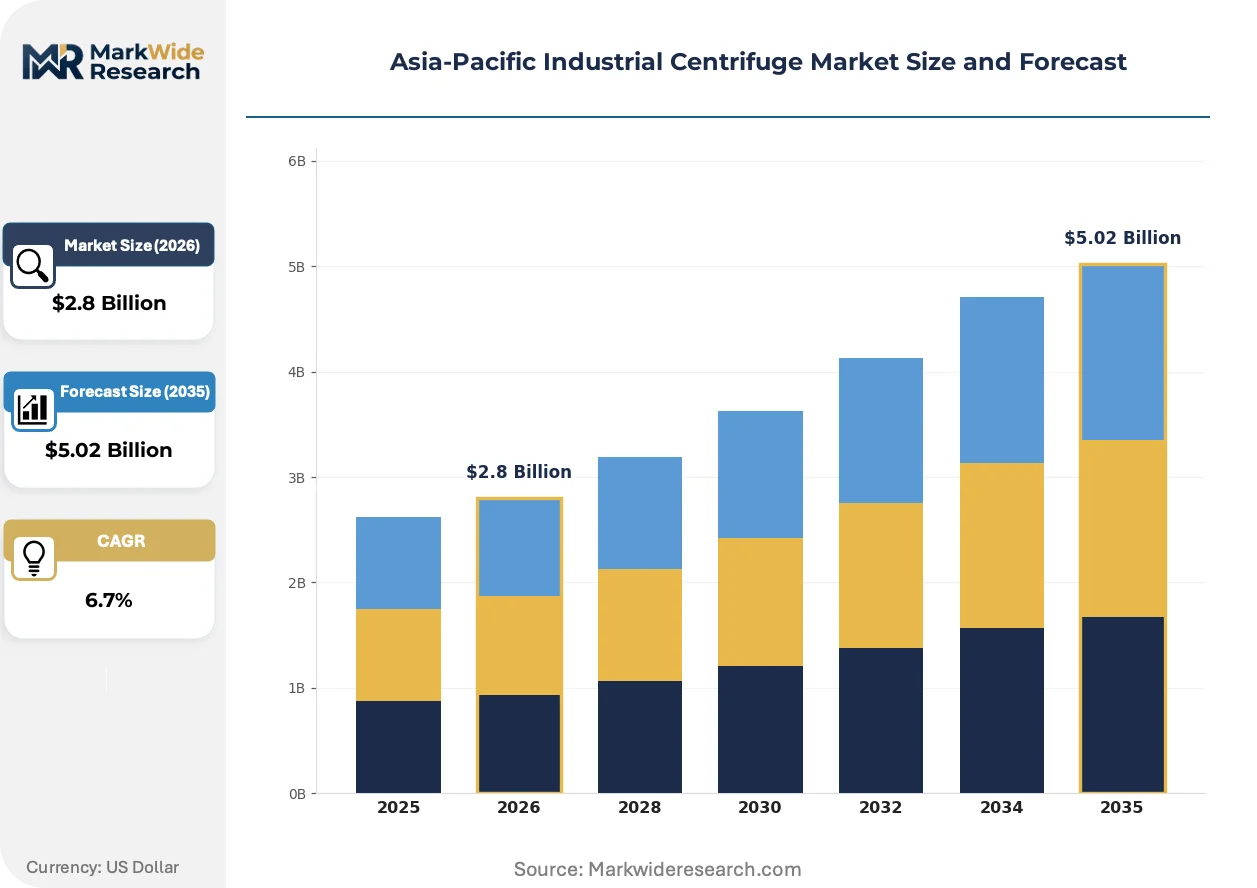
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basket, Peeler, Decanter, Tubular End User: Chemicals, Pharmaceuticals, Food & Beverage, Wastewater Treatment Technology: Disc Stack, Continuous Flow, Batch, Variable Speed Application: Solid-Liquid Separation, Liquid-Liquid Separation, Clarification, Concentration |
| Companies Covered | TOMOE Engineering Co., Ltd., KUBOTA Corporation, Alfa Laval AB, Jiangsu Huada Centrifuge Co., Ltd., Hiller Separation & Process GmbH, Andritz AG, Flottweg SE, Ace Industries India Pvt Ltd, GEA Group AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Centrifuge Market Strategic Shifts
Active separation technologies are converging with digital control systems to redefine operational efficiency benchmarks across pharmaceutical and environmental applications. Equipment differentiation now hinges on energy recovery capabilities and real-time process optimization rather than mechanical specifications alone.
Disc-stack centrifuge technology is hybridizing with computational fluid dynamics modeling to optimize bowl geometry for specific cell density profiles. Biopharma manufacturers in South Korea and Singapore are adopting these simulation-validated designs for monoclonal antibody production. The convergence is compressing development timelines for application-specific separation protocols while reducing empirical testing requirements.
Japan's METI has tightened JIS mechanical vibration limits and introduced mandatory energy efficiency ratings for industrial rotating equipment sold domestically. Domestic manufacturers must now submit third-party validated performance data to secure market access. Pharmaceutical and chemical processors in Osaka and Nagoya industrial corridors are prioritizing certified equipment to preempt operational audit failures.
Direct technical engagement between OEM engineering teams and large pharmaceutical processors is displacing traditional distributor-mediated specification processes. End-users in India's Hyderabad cluster now require vendor participation in process validation protocols before contract award. This behavioral shift is most pronounced in high-value bioprocessing applications where separation performance directly correlates with batch yield economics.
Asia-Pacific Industrial Centrifuge Market Segmentation
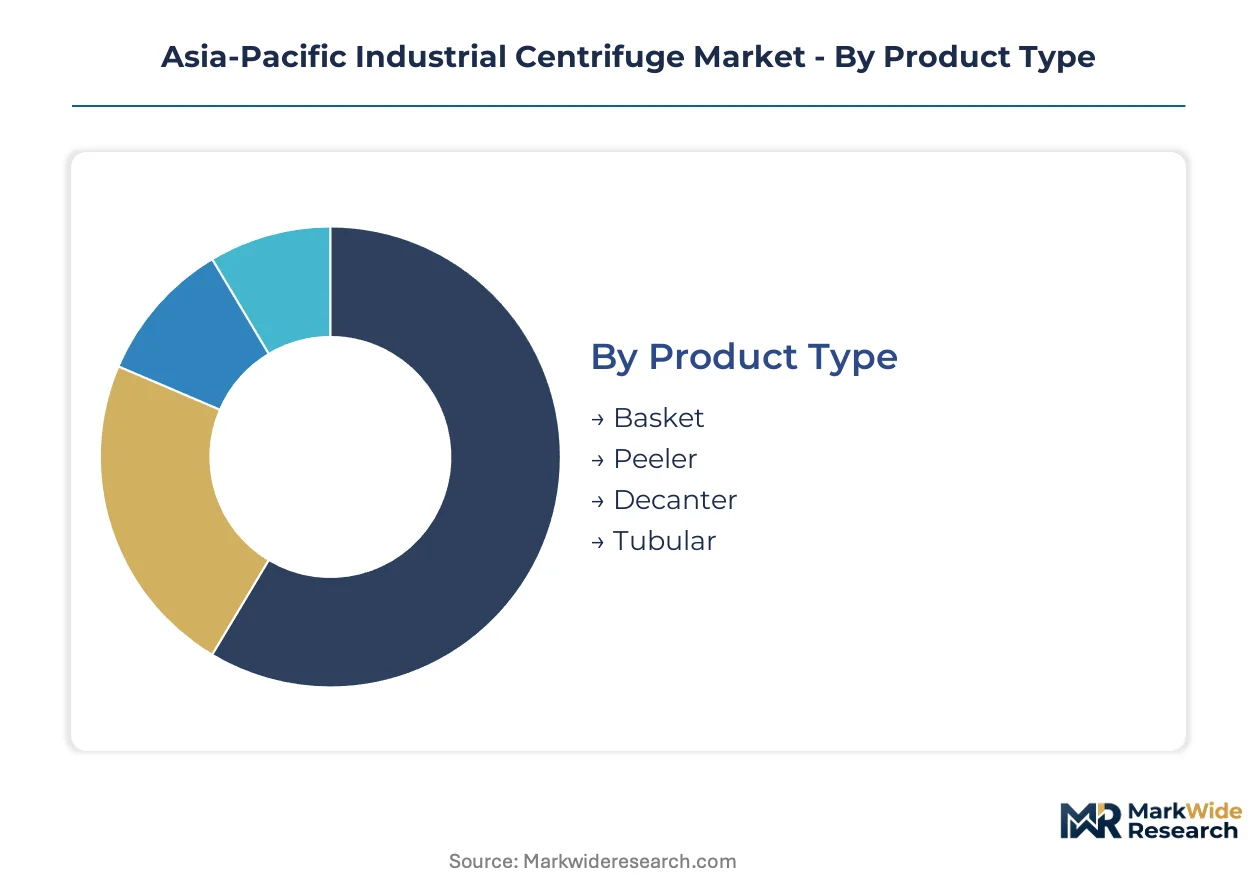
Industrial centrifuge procurement across the Asia-Pacific region varies sharply by operational intensity and service infrastructure requirements. Equipment specification decisions hinge on separation precision demands, batch versus continuous processing economics, and regulatory compliance thresholds specific to pharmaceutical and environmental applications.
Product Type:
After-sales service intensity diverges substantially across centrifuge architectures, with continuous-duty systems demanding predictive maintenance contracts and batch equipment requiring periodic bowl refurbishment programs.
- Decanter:Continuous-flow scroll discharge systems handle high-solids slurries through differential speed control between bowl and conveyor. Municipal wastewater plants in Ho Chi Minh City and Jakarta are expanding decanter deployments for sludge dewatering under tightening effluent standards.
- Basket:Vertical-axis batch centrifuges with perforated bowls enable cake washing and drying cycles for crystalline products. Pharmaceutical API manufacturers in Hyderabad retain basket systems for solvent-wet crystal recovery despite longer cycle times.
- Peeler:Horizontal discharge systems automate cake removal through mechanical peeling action. Chemical processors in China's Yangtze River Delta specify peeler centrifuges for abrasive inorganic salt separation.
- Tubular:High-speed vertical bowl designs generate extreme centrifugal force for fine particle clarification. Biotechnology labs in Singapore deploy tubular units for viral vector purification in cell therapy development.
Decanter centrifuges hold the largest share; momentum sits with peeler systems as chemical processors automate batch operations.
End User:
Margin structures and procurement authority patterns vary markedly across customer verticals, with pharmaceutical buyers demanding validation documentation and wastewater operators prioritizing total cost of ownership metrics.
- Pharmaceuticals:cGMP-compliant separation equipment for cell harvesting and protein purification requires documented cleaning validation and material traceability. India's CDSCO inspection protocols are driving disc-stack upgrades in Ahmedabad manufacturing clusters.
- Wastewater Treatment:Sludge thickening and dewatering applications demand abrasion-resistant scroll designs and polymer optimization systems. Thailand's Metropolitan Waterworks Authority is expanding decanter capacity for Bangkok municipal sludge processing.
- Chemicals:Corrosive process streams and explosive atmospheres mandate specialized alloys and ATEX certification. Petrochemical complexes in South Korea's Ulsan industrial park specify hastelloy bowl constructions for acid slurry separation.
- Food & Beverage:Hygienic design standards and CIP compatibility govern edible oil refining and dairy clarification equipment. Palm oil processors in Malaysia's Johor region are retrofitting continuous disc-stack systems for crude oil purification.
Pharmaceuticals command premium pricing tiers; wastewater treatment represents the steepest expansion trajectory as urban infrastructure investment accelerates.
Technology:
Volume throughput and energy recovery potential differentiate technology platforms, with variable-speed drives gaining share against fixed-speed alternatives in electricity-intensive municipal applications.
- Disc Stack:Conical plate assemblies create thin-layer separation paths for liquid-liquid and solid-liquid clarification. Monoclonal antibody producers in South Korea's Songdo biocluster specify disc-stack systems with hermetic seals to prevent product oxidation.
- Continuous Flow:Uninterrupted feed and discharge operations maximize throughput for high-volume process streams. China's MEE energy efficiency mandates are accelerating regenerative drive adoption in continuous decanter installations.
- Batch:Cyclical loading, separation, and discharge sequences suit multi-product pharmaceutical campaigns. Contract manufacturing organizations in Australia's Melbourne biotech corridor retain batch flexibility for diversified product portfolios.
- Variable Speed:Frequency-controlled bowl and scroll drives enable real-time process optimization and energy recovery. Japanese municipal operators in Osaka prefecture specify variable-speed decanters to meet METI efficiency ratings.
Disc stack technology retains dominant share in value terms; variable speed configurations are climbing the fastest as electricity costs reshape operating economics.
Application:
Customer technical specifications and performance validation requirements concentrate differently across separation objectives, with clarification demanding tighter particle cut-point guarantees than bulk solid-liquid separation.
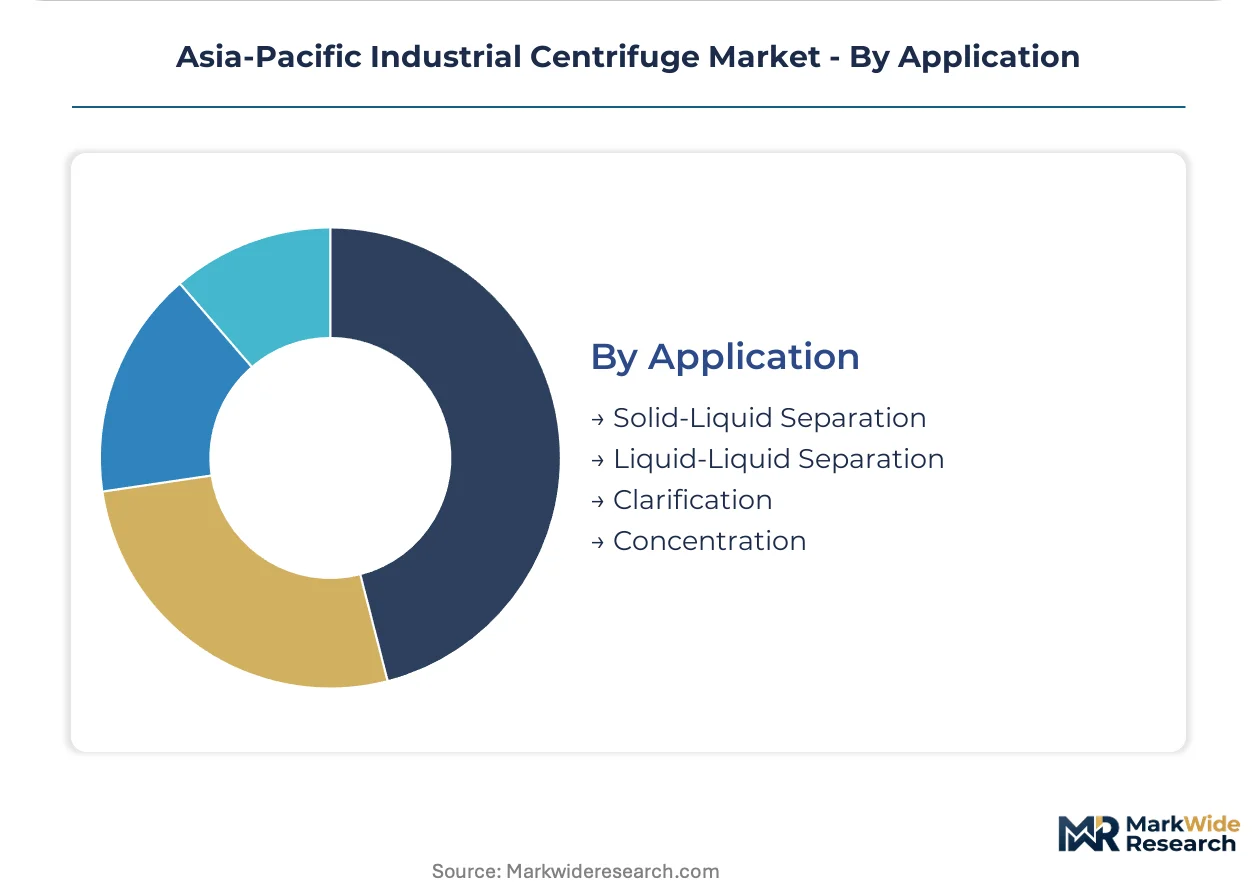
- Solid-Liquid Separation:Density differential exploitation removes suspended solids from process liquids across mining, chemical, and environmental applications. Iron ore processors in Western Australia's Pilbara region deploy high-capacity decanters for tailings dewatering under water scarcity constraints.
- Liquid-Liquid Separation:Immiscible phase separation extracts valuable products or removes contaminants from process streams. Indonesia's palm oil refineries specify disc-stack centrifuges for oil-water separation in crude degumming operations.
- Clarification:Fine particle removal achieves optical clarity or sterility in pharmaceutical and beverage applications. Japanese sake breweries in Nada district retain traditional tubular clarification while monitoring automated alternatives.
- Concentration:Solids thickening reduces downstream processing volumes and disposal costs. Vietnam's emerging pharmaceutical sector lacks established concentration equipment service networks, creating vendor positioning opportunities.
Solid-liquid separation dominates installed base; liquid-liquid separation is gaining share fastest as biofuel and edible oil processing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese pharmaceutical-grade equipment while Chinese domestic fabricators compete on throughput economics. India's API manufacturing clusters generate equipment demand at intermediate price points. Southeast Asian municipal utilities prioritize total cost of ownership over capital expenditure minimization.
China
Wastewater treatment capacity expansion and petrochemical complex upgrades drive decanter centrifuge procurement. SAMR-administered GB standards for pressure vessel integrity and environmental emissions mandate equipment recertification cycles. Yangtze River Delta chemical processors specify automated peeler systems for inorganic salt separation under tightening MEE enforcement.
India
Biosimilar manufacturing scale-up and domestic API production expansion fuel disc-stack centrifuge demand. CDSCO inspection protocols and CEA electrical safety benchmarks govern equipment validation requirements. Pharmaceutical clusters around Hyderabad and Ahmedabad install high-capacity cell harvesting systems as contract development manufacturing organizations expand bioprocessing suites.
Japan
Precision biopharma applications and monoclonal antibody production sustain premium equipment pricing. METI-enforced JIS mechanical vibration limits and mandatory energy efficiency ratings determine market access. Osaka and Nagoya industrial corridors prioritize certified rotating equipment to preempt operational audit failures in cGMP facilities.
South Korea
Cell therapy manufacturing and viral vector purification drive specialized tubular centrifuge adoption. MFDS biologics licensing requirements align with international ICH guidelines for separation equipment validation. Songdo biocluster facilities specify hermetic-seal disc-stack systems to prevent product oxidation in monoclonal antibody campaigns.
Vietnam
Greenfield API manufacturing investments and edible oil processing expansion create equipment demand without established service infrastructure. The country's national pharmaceutical regulator is developing GMP inspection capacity for imported separation equipment. Ho Chi Minh City industrial zones lack vendor service networks, creating first-mover positioning potential for OEMs with local technical support capabilities.
Asia-Pacific Industrial Centrifuge Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision bearings and variable frequency drives. Market structure consolidates around multinational equipment houses with full validation documentation capabilities and regional fabricators competing on delivery speed. Three archetypes dominate: European-Japanese premium system houses, Chinese scale manufacturers, and Indian service-integrated distributors. Competitive moves concentrate on predictive maintenance platform deployment and regenerative drive technology licensing to meet efficiency mandates.
Among premium-tier system integrators, Alfa Laval AB and GEA Group AG exemplify the European-Japanese archetype with documented bioprocess validation protocols. KUBOTA Corporation anchors Japanese municipal specialization. Jiangsu Huada Centrifuge Co., Ltd. represents Chinese manufacturing scale. These named entities occupy positions across the pricing spectrum without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| TOMOE Engineering Co., Ltd. |
| KUBOTA Corporation |
| Alfa Laval AB |
| Jiangsu Huada Centrifuge Co., Ltd. |
| Hiller Separation & Process GmbH |
| Andritz AG |
| Flottweg SE |
| Ace Industries India Pvt Ltd |
| GEA Group AG |
| Others |
Value Chain & Pricing Dynamics
German and Japanese precision bearing suppliers anchor the high-value component tier, concentrating margin capture upstream while downstream equipment assemblers compete on configured-to-order pricing spreads. Pharmaceutical-grade centrifuge procurement in Osaka and Hyderabad validates this structure, where certified subsystems command premiums that standard wastewater equipment cannot match.
Pricing Analysis
Configured-to-order pricing spreads 40-60% above standard decanter configurations for pharmaceutical applications requiring CDSCO or MFDS validation documentation. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling intensity. Pricing pressure stems from Chinese domestic fabricators scaling automated peeler production for Yangtze River Delta chemical processors. Wastewater treatment operators in Southeast Asia exhibit highest price sensitivity, while monoclonal antibody producers in Songdo accept premium positioning for hermetic-seal disc-stack systems.
Supply Chain Analysis
Contract manufacturing for precision bowls and scroll assemblies concentrates in Germany, Japan, and select Chinese coastal provinces with pressure vessel certification capabilities. Specialty austenitic stainless steel grades draw from nickel and molybdenum supply networks subject to commodity volatility. Single-source vulnerability sits with high-precision bearings and variable frequency drives for pharmaceutical-grade equipment. Distribution runs through OEM direct technical engagement for large pharmaceutical processors, displacing traditional distributor-mediated specification processes in India's Hyderabad cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration and single-use downstream technologies pose credible substitution threats to conventional centrifuge separation in cell therapy manufacturing, forcing incumbents to defend integration value.
For Market Incumbents: Build switching-cost moats through predictive maintenance platform deployment and regenerative drive technology licensing to meet China's MEE efficiency mandates. Anchor service contract unbundling for municipal wastewater operators to preempt Japanese and Korean component suppliers expanding downstream. Defend against membrane filtration substitution by embedding centrifuge systems within continuous bioprocessing validation protocols. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's greenfield API manufacturing corridor where vendor service networks remain undeveloped. Target edible oil processing expansion in Johor and Ho Chi Minh City industrial zones lacking established aftermarket infrastructure. Penetrate through remote monitoring convergence partnerships with local engineering contractors rather than direct OEM competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade disc-stack manufacturing as hermetic sealing and CFD-validated bowl geometries demand specialized fabrication assets. Prioritize acquisition targets with documented bioprocess validation protocols and existing METI or CDSCO certification relationships. Monitor China's evolving GB standards timeline as inflection indicator for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Drive Integration | China's MEE mandates accelerate energy recovery adoption in municipal decanter deployments. |
| Predictive Maintenance Platform Launch | Vibration telemetry unbundles service contracts for Bangkok and Jakarta wastewater operators. |
| Hermetic Seal Technology Licensing | Songdo monoclonal antibody producers specify oxidation-prevention systems for protein purity. |
| Local Technical Support Expansion | Ho Chi Minh City API facilities lack established centrifuge service infrastructure. |
| CFD-Validated Bowl Geometry Development | South Korean biopharma manufacturers compress separation protocol development timelines. |
Study Parameters
The analysis maps decanter, disc-stack, basket, peeler, and tubular centrifuge architectures, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across the Asia-Pacific region. Primary interviews with pharmaceutical process validation leads and municipal wastewater operations managers combined with secondary triangulation against SAMR GB standard filings, METI JIS certification databases, CDSCO inspection protocols, and customs trade data for specialty alloy imports. Bottom-up equipment deployment tracking and top-down industrial capacity expansion analysis converge across the analysis window.
Forecast assumptions held fixed China's dual carbon enforcement trajectory and India's PLI scheme for API manufacturing while varying stainless steel alloy price scenarios and pharmaceutical outsourcing intensity. Segmentation dimensions span product type, end-user vertical, technology platform, and application objective, with regional regulatory cluster as an additional modeled layer. CAGRs derive from equipment replacement cycle analysis and greenfield capacity expansion pipelines, incorporating MEE energy efficiency mandate compliance costs and CDSCO inspection protocol evolution as industry-specific inputs.
Sensitivities concentrate around nickel and molybdenum commodity volatility, GB standards recertification timeline compression, and membrane filtration substitution rates in cell therapy applications. Forecasts reflect these documented assumptions with acknowledged revision triggers from regulatory enforcement acceleration or upstream alloy supply disruption. Quarterly review of SAMR certification bulletin releases and METI efficiency rating updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Micro Motor Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
UV Conveyor Systems Market