
 Press-Insertion Systems Market | 2026-2036
Press-Insertion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Press-Insertion Systems Market Analytics
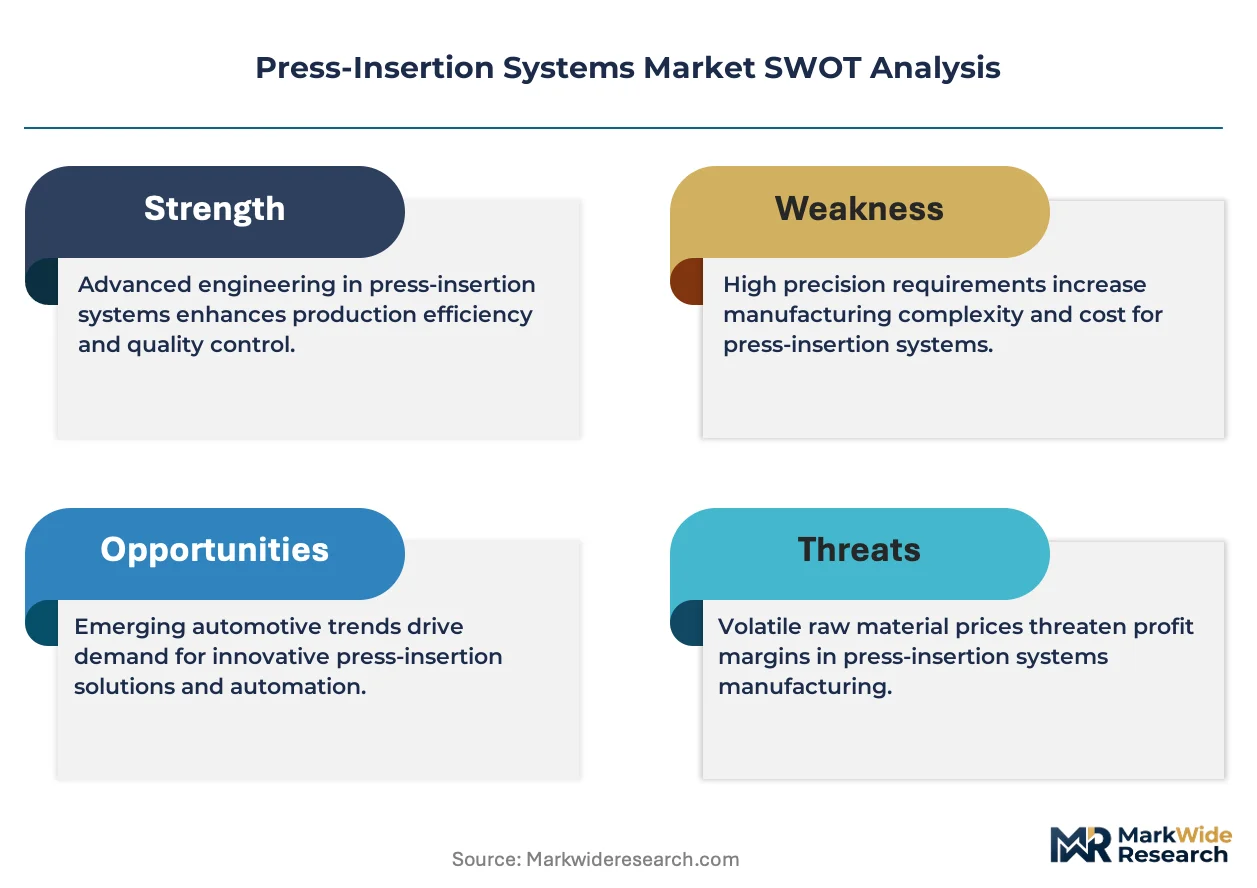
Aftermarket service revenue is reconfiguring margin capture away from pure equipment sales in the press-insertion systems sector. TE Connectivity leverages its connector ecosystem to anchor recurring service contracts across automotive and electronics clients. Schleuniger AG specializes in precision wire processing equipment, occupying a defensible niche in medical device and aerospace applications. ShinMaywa Industries competes through integrated manufacturing scale in Asian electronics supply chains.
Press-insertion systems are electromechanical or fluid-powered machines designed to drive pins, terminals, or components into substrates with controlled force, typically operating at insertion forces between 50 N and 50 kN depending on application. These systems serve primarily to automate critical joining operations in high-volume manufacturing where manual placement risks inconsistency or damage. Electric insert systems are gaining share in electronics and medical device applications where programmable force profiles reduce component fracture rates. Pneumatic insert equipment still dominates automotive tier-1 supplier floors where cycle speed and capital cost sensitivity favor proven compressed-air architectures. Robotics-based insertion lines represent the fastest-expanding technology segment as contract manufacturers retrofit flexible cells for mixed-model EV component programs.
The EU Machinery Directive and CE marking requirements shape product design standards for equipment sold into European automotive and medical device facilities. China's SAMR and GB standards for industrial automation equipment enforce local certification protocols that influence market access timelines for non-domestic suppliers. ISO quality management frameworks and sector-specific automotive standards from Germany's KBA add layered compliance obligations across export-oriented manufacturing bases. Stakeholders must weigh regional certification roadmaps against platform standardization strategies when allocating R&D and production capacity.
Market Dynamics
Automotive OEMs are retrofitting assembly floors for EV battery pack architectures, forcing press-insertion system suppliers to reengineer force-control algorithms and cycle-time parameters around new substrate materials and terminal geometries.
Growth Catalysts
- EU Machinery Directive:CE marking requirements for precision assembly equipment are compelling tier-1 automotive suppliers in Germany and Italy to replace legacy pneumatic systems with programmable electric insertion platforms.
- EV battery pack assembly:Cell-to-pack architectures require terminal insertion forces exceeding 30 kN, pulling demand toward servo-electric systems with real-time force feedback.
- Medical device manufacturing clusters:Switzerland's precision engineering corridor around Solothurn is expanding catheter and implant assembly lines that demand sub-Newton force resolution.
Market Restraints
- Neodymium magnet supply:Servo-electric insertion systems depend on rare-earth permanent magnet motors, with processing concentrated in China's Jiangxi and Inner Mongolia provinces.
- Compressed air infrastructure lock-in:Automotive tier-1 floors in Stuttgart and Wolfsburg retain sunk costs in pneumatic distribution networks that slow electric system migration.
- GB certification timelines:China's SAMR local-type approval for industrial automation equipment extends market access lead times by 8-14 months for non-domestic suppliers.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are drawing mobile phone and component assembly investments to Noida and Sri City, creating first-mover openings for insertion system vendors.
- Wire-to-board miniaturization:0.3 mm pitch connector insertion in wearables and hearables demands micro-force systems below 50 N that incumbent automotive suppliers have not addressed.
- Carbon border adjustments:EU CBAM implementation is pressuring contract manufacturers to document assembly equipment energy efficiency, favoring electric over pneumatic architectures.
Industry Challenges
- Mechatronics engineering scarcity:Programming force-velocity curves for heterogeneous substrates requires combined mechanical and software expertise that German and Japanese vocational pipelines produce insufficiently.
- Legacy MES integration:Brownfield automotive plants operate 15-20 year-old manufacturing execution systems that resist API connectivity with modern insertion equipment data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Press-Insertion Systems Market |
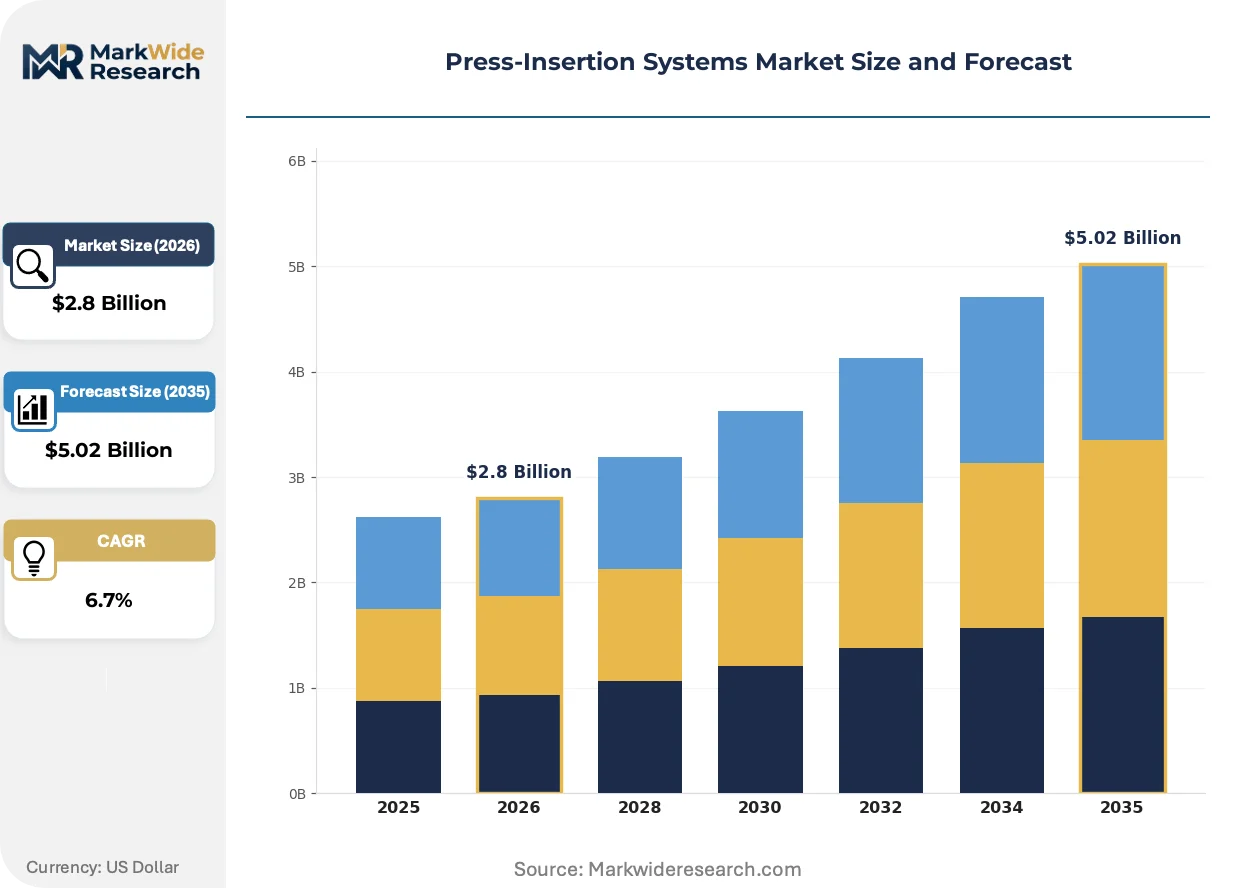
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Insert, Manual Insert, Electric Insert, Hydraulic Insert Application: Automotive, Electronics, Aerospace, Medical Devices End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Aftermarket Providers Technology: Mechanical, Servo Drives, Robotics, Automation |
| Companies Covered | TE Connectivity, Autosplice, ShinMaywa Industries, Weber Assembly Systems, Arburg, ASM Assembly Systems, Fischer Connectors, Schleuniger AG, BDM Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Press-Insertion Systems Market Evolving Landscape
Control architectures and force-feedback mechanisms are undergoing fundamental redesign as end-users demand traceable insertion data for quality systems and predictive maintenance.
Servo-electric press technology is migrating from automotive terminal insertion toward medical device and electronics applications. Swiss and German catheter manufacturers are adopting programmable force profiles that pneumatic systems cannot replicate. This migration is compressing the addressable market for legacy pneumatic vendors in precision assembly segments.
REACH substance restrictions on lubricants and coatings are reshaping press-insertion system maintenance protocols. Equipment suppliers must qualify alternative low-friction surface treatments for tooling that contacts sensitive substrates. Medical device manufacturers in Ireland and the Netherlands are fastest to mandate REACH-compliant maintenance schedules, forcing service contract renegotiations.
Buyers are unbundling equipment purchases from captive service agreements. Contract manufacturers in Mexico's Baja California electronics corridor now source insertion systems from one vendor and preventive maintenance from regional specialists. This unbundling is fragmenting vendor revenue streams and compressing gross margins on pure equipment sales.
Press-Insertion Systems Market Segmentation
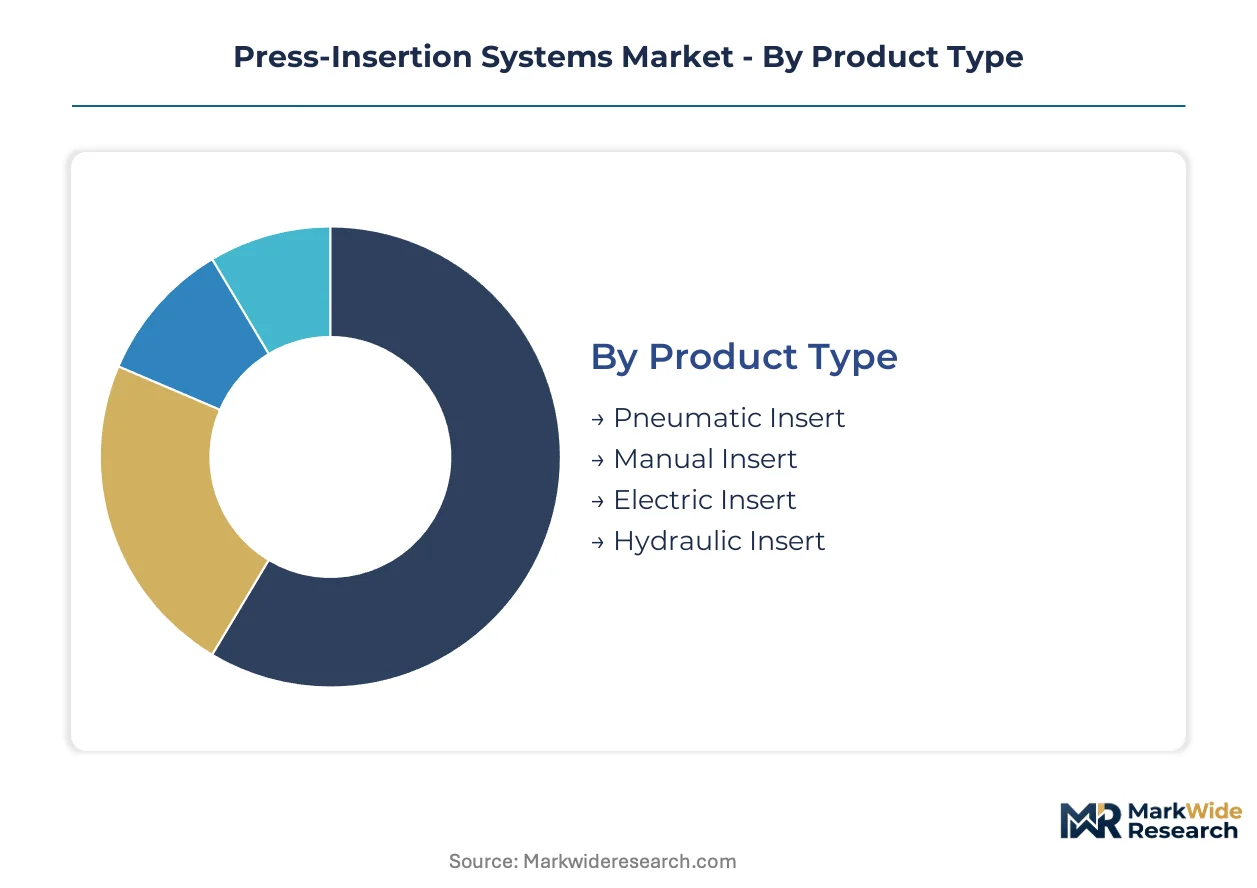
Press-insertion systems span divergent force ranges and control architectures that map directly to substrate fragility and cycle-time requirements. Segmentation reveals where electric precision is displacing pneumatic brute force, and which end-user structures capture margin through captive integration versus outsourced flexibility.
Product Type:
The use-case spectrum stretches from delicate medical catheter assembly requiring sub-Newton resolution to EV battery terminal insertion demanding 30+ kN with real-time force feedback.
- Electric Insert:Servo-electric architectures deliver programmable force-velocity curves with closed-loop feedback at 0.1 N resolution. Swiss catheter manufacturers around Solothurn and German implant producers are migrating to these systems as REACH restrictions eliminate pneumatic lubricants and CE marking demands traceable process data.
- Pneumatic Insert:Compressed-air systems dominate Stuttgart and Wolfsburg automotive floors where 50-500 N insertion forces and sub-second cycle times prioritize capital efficiency over precision. Sunk costs in plant air infrastructure and proven maintenance protocols slow displacement despite EU energy efficiency directives.
- Hydraulic Insert:Fluid-power systems address extreme force applications above 50 kN in heavy-gauge electrical busbar and industrial connector assembly.
- Manual Insert:Hand-operated bench presses persist in prototype shops and low-volume medical device validation lines where automation economics fail.
The dominant share belongs to Pneumatic Insert, while Electric Insert is closing the gap fastest.
Application:
Cost tier stratification separates high-mix, low-volume precision segments from capital-intensive automotive scale operations.
- Automotive:Cell-to-pack battery architectures are redefining insertion parameters around aluminum-copper dissimilar metal joining and ceramic-coated cell terminals. OEMs in Germany's manufacturing corridor demand force feedback at 10 kHz sampling rates for weld-quality correlation.
- Electronics:Wearables and hearables drive 0.3 mm pitch wire-to-board insertion below 50 N where programmable electric systems reduce substrate fracture rates versus legacy pneumatic equipment.
- Medical Devices:Swiss and Irish catheter producers mandate sub-Newton force resolution and full batch traceability under MDR and FDA quality system regulations.
- Aerospace:Military and commercial avionics connectors in titanium and composite housings require specialized tooling for EMI-shielded terminal insertion.
Automotive commands the largest equipment footprint, though Electronics exhibits the steepest expansion trajectory as miniaturization accelerates.
End User:
Customer type determines whether insertion systems are configured for dedicated high-volume lines or flexible contract manufacturing cells.
- OEMs:Captive integration strategies at German and Japanese automotive manufacturers favor standardized electric platforms with centralized MES connectivity and predictive maintenance contracts.
- Tier-1 Suppliers:Continental, Bosch, and Denso operations in Germany and Mexico balance pneumatic legacy assets against selective electric retrofits for EV-dedicated lines.
- Contract Manufacturers:Foxconn and Jabil facilities in India's Noida and Sri City electronics clusters prioritize robotics-based flexible cells for mixed-model mobile phone and component programs.
- Aftermarket Providers:Independent service specialists in Mexico's Baja California corridor are capturing unbundled maintenance contracts as buyers separate equipment procurement from preventive service.
Tier-1 Suppliers account for the majority of current installed base, while Contract Manufacturers are gaining share fastest as production-linked incentives reshape Asian electronics geography.
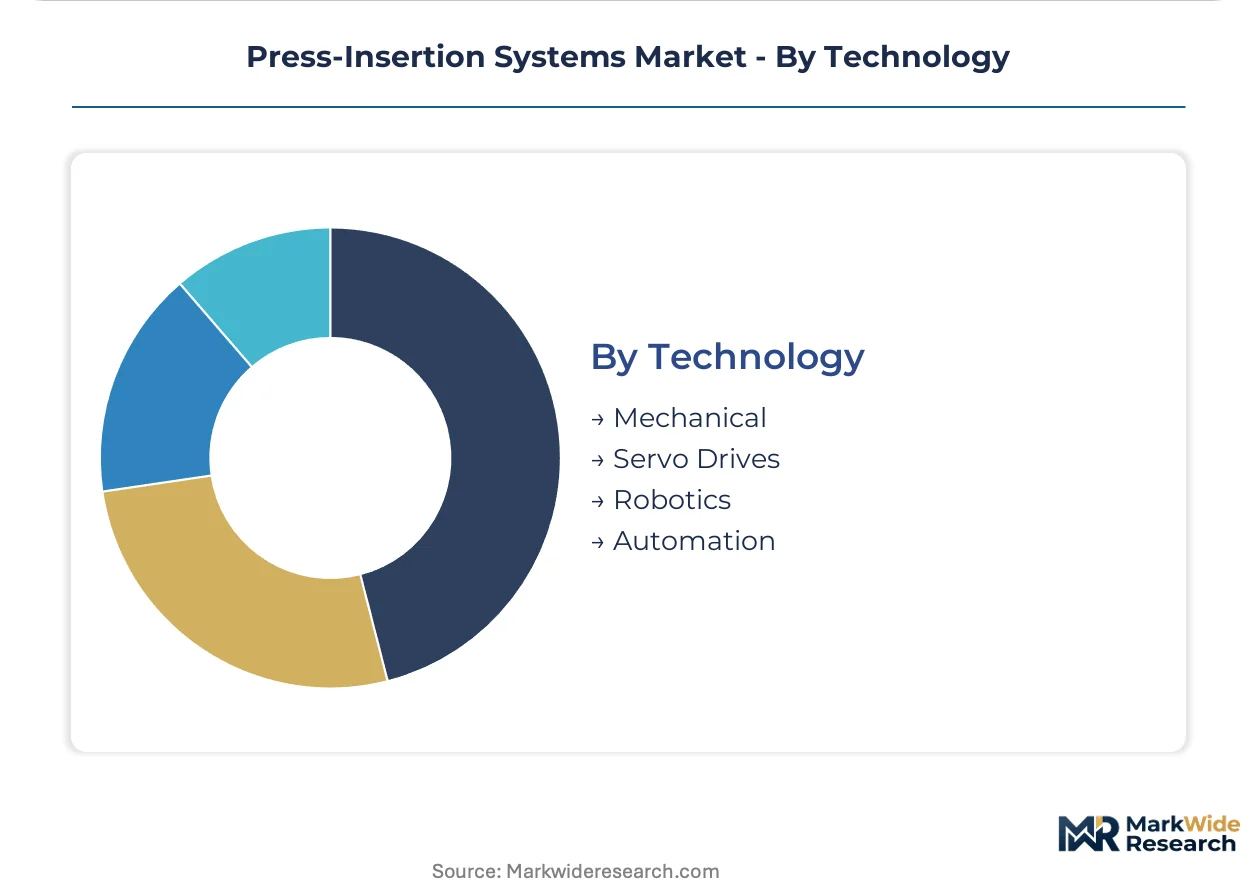
Technology:
Maturity gradients separate proven mechanical architectures from emerging robotics integration requiring mechatronics engineering capabilities scarce in German and Japanese vocational pipelines.
- Servo Drives:Permanent-magnet synchronous motors with encoder feedback enable force-controlled insertion profiles impossible with pneumatic or hydraulic alternatives. Rare-earth magnet supply concentration in China's Jiangxi province creates vulnerability for European and Japanese system builders.
- Robotics:Six-axis collaborative robots with integrated force-torque sensors are retrofitting brownfield automotive plants for mixed-model EV component flexibility, though legacy MES integration barriers persist.
- Automation:Fixed-automation cells with dedicated part handling remain economical for single-SKU high-volume programs in automotive terminal and connector assembly.
- Mechanical:Cam-driven and spring-actuated presses retain niche applications where programmability adds no value and maintenance simplicity dominates.
Servo Drives hold the established technology position, while Robotics is climbing the fastest as contract manufacturers seek flexible cell architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes press-insertion systems differently from other major markets, prioritizing programmable electric platforms for automotive precision over the pneumatic legacy assets still dominant in Mexico's electronics corridors. China's demand concentrates in rare-earth magnet supply chains for servo motors, while India's emerging electronics clusters favor flexible robotics-based cells. Switzerland and Ireland distinguish themselves through sub-Newton medical device applications that other regions have not scaled.
Germany
Automotive OEMs in Stuttgart and Wolfsburg retrofit assembly floors for EV battery pack architectures, pulling demand toward servo-electric systems with real-time force feedback. KBA automotive standards and EU Machinery Directive CE marking requirements compel tier-1 suppliers to replace legacy pneumatic equipment. The manufacturing corridor around Stuttgart anchors precision assembly demand as cell-to-pack terminal insertion forces exceed 30 kN.
China
Domestic servo motor production depends on rare-earth permanent magnet processing concentrated in Jiangxi and Inner Mongolia provinces. SAMR local-type approval under GB standards for industrial automation equipment extends market access lead times by 8-14 months for non-domestic suppliers. Electronics manufacturing clusters in the Yangtze River Delta absorb robotics-based insertion lines for mixed-model mobile phone programs.
India
Production-linked incentives under the PLI scheme for electronics manufacturing draw mobile phone and component assembly investments to Noida and Sri City. BIS certification requirements shape equipment procurement specifications for contract manufacturers. Foxconn and Jabil facilities in these clusters prioritize flexible cells that accommodate rapid product changeovers.
Switzerland
Catheter and implant manufacturers around Solothurn mandate sub-Newton force resolution and full batch traceability under MDR quality system regulations. Swissmedic oversight of medical device manufacturing enforces documentation standards that programmable electric systems satisfy. The precision engineering corridor expands assembly lines for minimally invasive surgical instruments.
Mexico
Contract manufacturers in Baja California's electronics corridor unbundle equipment purchases from captive service agreements, sourcing insertion systems from one vendor and preventive maintenance from regional specialists. Compressed air infrastructure lock-in persists among automotive tier-1 floors, though selective electric retrofits advance for EV-dedicated lines. The region captures aftermarket service revenue fragmentation as buyers separate procurement from maintenance contracts.
Press-Insertion Systems Market Competitive Landscape
Capability concentration sits with precision-engineering specialists; scale advantage sits with diversified industrial conglomerates. The vendor base organizes into three tiers: integrated manufacturing groups with captive electronics supply chains, precision automation specialists with defensible medical device niches, and regional fabricators serving contract manufacturing clusters. Two competitive moves dominate: geographic expansion into India's PLI-driven electronics corridors, and technology licensing partnerships that bridge pneumatic legacy assets with servo-electric retrofits.
Within the precision-specialist tier, Schleuniger AG and TE Connectivity exemplify divergent anchoring strategies. Schleuniger AG occupies a position centered on wire processing equipment for medical device and aerospace applications where force resolution requirements exclude generalist competitors. TE Connectivity leverages connector ecosystem integration to secure recurring service contracts across automotive and electronics client bases. ShinMaywa Industries represents the integrated manufacturing archetype, with Asian electronics supply chain scale providing cost-positioning leverage. Weber Assembly Systems and Autosplice sit within the regional-fabricator cluster, serving contract manufacturers in Mexico and emerging Asian electronics hubs with equipment configurations tuned to local infrastructure constraints.
| Leading Market Players |
|---|
| TE Connectivity |
| Autosplice |
| ShinMaywa Industries |
| Weber Assembly Systems |
| Arburg |
| ASM Assembly Systems |
| Fischer Connectors |
| Schleuniger AG |
| BDM Electronics |
| Others |
Value Network & Pricing Analysis
Undercapacity in European servo motor production is compressing lead times and elevating supplier pricing power for precision electric insertion platforms serving medical device and EV battery assembly lines.
Pricing Analysis
Long-term service contracts dominate revenue capture as buyers unbundle equipment procurement from preventive maintenance agreements. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked medical-grade systems from automotive tier-1 pneumatic assets and manual bench presses for prototype shops. Pricing pressure stems from contract manufacturers in Mexico's Baja California corridor sourcing regional maintenance specialists rather than captive vendor service. Tier-1 automotive suppliers exhibit highest price sensitivity due to compressed capital budgets during EV line retrofits, while Swiss catheter manufacturers accept premium positioning for sub-Newton force resolution.
Supply Chain Analysis
Foxconn and Jabil facilities in India's Noida and Sri City electronics clusters anchor contract-manufacturing capacity for flexible insertion cell deployment. Permanent magnet motors for servo-electric systems draw from rare-earth processing in China's Jiangxi province, precision ball screws from German and Japanese machine tool builders, and force-torque sensors from Swiss and American specialty component houses. Single-source vulnerability concentrates in neodymium magnet supply chains subject to export licensing protocols. Distribution runs through direct OEM relationships for large automotive programs and regional equipment distributors serving contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The press-insertion systems sector faces high-growth disruption as EV battery pack architectures force reengineering of force-control algorithms and real-time feedback systems across automotive assembly floors.
For Market Incumbents: Entrench position through backward integration into servo motor and force sensor production to offset rare-earth supply concentration risks. Secure predictive maintenance contracts with German OEMs before regional service specialists fragment aftermarket revenue. CE marking and MDR compliance investments create switching costs that lock medical device clients into platform ecosystems. For New Entrants and Emerging Players: Build out micro-force system capabilities below 50 N for wearables and hearables assembly where incumbent automotive suppliers lack addressed solutions. India's PLI-driven electronics corridors offer most penetrable geography as Foxconn and Jabil facilities prioritize flexible robotics-based cells. Partner with regional maintenance specialists in Mexico's Baja California corridor to capture unbundled service contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across servo-electric system manufacturing as rare-earth magnet processing and precision machining capabilities concentrate supply. Long-term viability favors precision automation specialists with defensible medical device niches over diversified industrial conglomerates exposed to automotive cyclicality. Monitor neodymium export licensing protocols from China's Jiangxi province as inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | CE marking and EU Machinery Directive compel tier-1 automotive suppliers to replace pneumatic legacy assets. |
| Rare-Earth Magnet Supply Securement | Backward integration into permanent magnet sourcing mitigates concentration risk in China's Jiangxi province. |
| Flexible Robotics Cell Deployment | Contract manufacturers in India's Noida and Sri City clusters prioritize mixed-model EV component programs. |
| Sub-Newton Force System Development | Swiss catheter manufacturers around Solothurn mandate precision unreachable by pneumatic alternatives. |
| Unbundled Service Contract Capture | Regional specialists in Mexico's Baja California corridor fragment traditional vendor revenue streams. |
Research Methodology
Cross-validation between OEM procurement disclosures and tier-1 supplier technical specifications anchors the qualitative findings. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from SEC filings, customs trade data, EU Machinery Directive compliance databases, and automotive production registries. Bottom-up equipment shipment analysis and top-down manufacturing value-added estimates triangulate market sizing.
Calibration against historical penetration curves for servo-electric versus pneumatic architectures shapes the analytical framework across the analysis window. Segmentation dimensions include force range tier, control architecture type, end-use application, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and EV battery assembly line investment trajectories. Forecast inputs incorporate rare-earth magnet supply elasticity and REACH substance restriction implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese servo motor specialists or accelerated pneumatic system obsolescence would shift outcomes. Regulatory delays in SAMR GB certification timelines or neodymium export restrictions represent specific revision risks. Quarterly review of EV battery pack architecture announcements and rare-earth magnet pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Seal Inspection Equipment Market