
 Glass Washer Market | 2026-2036
Glass Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Washer Market Foresight
Pharmaceutical packaging demand is hardening as a primary growth vertical for glass washer manufacturers. Hobart leverages its institutional kitchen heritage to compete in high-throughput beverage manufacturing installations. Winterhalter anchors European demand with precision-engineered rack-type systems built for pharmaceutical compliance. Miele Professional differentiates through laboratory-grade ultrasonic cleaning platforms that sustain premium positioning in research institutions.
Glass washers are electromechanical cleaning systems that deploy heated aqueous solutions, pressurized spray arms, and controlled rinse cycles to remove organic residues and particulate matter from glassware, with operating temperatures typically ranging from 55°C to 85°C depending on soil load and sanitation protocol. Their primary purpose spans commercial kitchens, beverage bottling lines, pharmaceutical packaging facilities, and optical manufacturing plants where substrate cleanliness directly affects product safety or optical performance. Conveyor glass washers dominate volume deployment in hospitality chains and food processing facilities where throughput economics favor continuous-flow architecture. Ultrasonic cleaning technology leads margin capture in pharmaceutical and laboratory segments where validated removal of pyrogens and sub-micron particles commands premium pricing. Fully automatic operation is displacing manual and semi-automatic systems across all end-user categories as labor costs rise and wash-cycle documentation requirements intensify.
The EPA Energy Star program and EU Ecodesign Directive jointly constrain water consumption limits and heating efficiency minimums for commercial glass washing equipment sold in the United States and European Union. NSF International standards and ISO 15883 washer-disinfector specifications govern validation protocols for pharmaceutical and laboratory applications, creating segmented compliance barriers that favor specialized manufacturers over generalist suppliers. FDA 21 CFR Part 11 documentation requirements for pharmaceutical packaging lines further tighten the vendor qualification process. Stakeholders must monitor evolving Ecodesign tier requirements and assess whether captive service networks or third-party validation partnerships offer faster route-to-market advantages in regulated segments.
Market Dynamics
Labor automation mandates and tightening water-energy efficiency thresholds are compressing equipment replacement cycles across hospitality and pharmaceutical end-uses, forcing buyers toward validated automatic systems.
Growth Catalysts
- EU Ecodesign Directive tier escalation:Rising water consumption limits and heating efficiency minimums for commercial dishwashing equipment are accelerating fleet turnover in European foodservice and beverage processing facilities.
- Pharmaceutical packaging validation requirements:FDA 21 CFR Part 11 documentation mandates for pharmaceutical packaging lines are hardening demand for washer-disinfector systems with automated cycle logging and pyrogen removal capabilities.
- Ultrasonic cleaning technology:Sub-micron particle removal capabilities in laboratory and optical manufacturing applications are commanding premium positioning as substrate cleanliness standards tighten.
Market Restraints
- Stainless steel and electronic component input volatility:Supply concentration for precision spray arm assemblies and heating elements in East Asian manufacturing clusters exposes equipment margins to tariff and logistics cost swings.
- Technical limitation in aqueous chemistry compatibility:Heated aqueous systems face residue challenges with certain adhesive compounds and specialty coatings used in pharmaceutical vial and optical lens manufacturing, limiting addressable substrate range.
- Substitution threat from single-use consumables:Pre-sterilized disposable glassware in clinical research and bioprocessing applications is compressing addressable demand in certain laboratory segments.
Strategic Opportunities
- Underpenetrated optical manufacturing clusters in South Korea:Precision lens and display substrate cleaning demand is outpacing domestic ultrasonic system supply, creating import substitution potential for validated European and Japanese equipment suppliers.
- Technology convergence of IoT sensors and predictive maintenance:Connected wash-cycle monitoring and automated detergent dosing systems are opening service-revenue streams and equipment-as-a-service models in multi-site hospitality chains.
- India's PLI scheme for food processing infrastructure:Central government production-linked incentives for cold chain and processing equipment are channeling capital toward automated glass washing installations in beverage bottling and dairy processing facilities.
Industry Challenges
- Certification timeline compression:NSF International and ISO 15883 validation protocols for pharmaceutical and laboratory applications extend vendor qualification cycles, delaying revenue recognition for specialized manufacturers entering regulated segments.
- Capex intensity of conveyor system deployment:Continuous-flow architecture for high-throughput beverage manufacturing requires substantial facility reconfiguration and utility infrastructure upgrades, lengthening sales cycles.
- Integration complexity with legacy MES and SCADA systems:Pharmaceutical packaging lines demand seamless data handoff between washer-disinfectors and manufacturing execution systems, raising engineering service costs and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Washer Market |
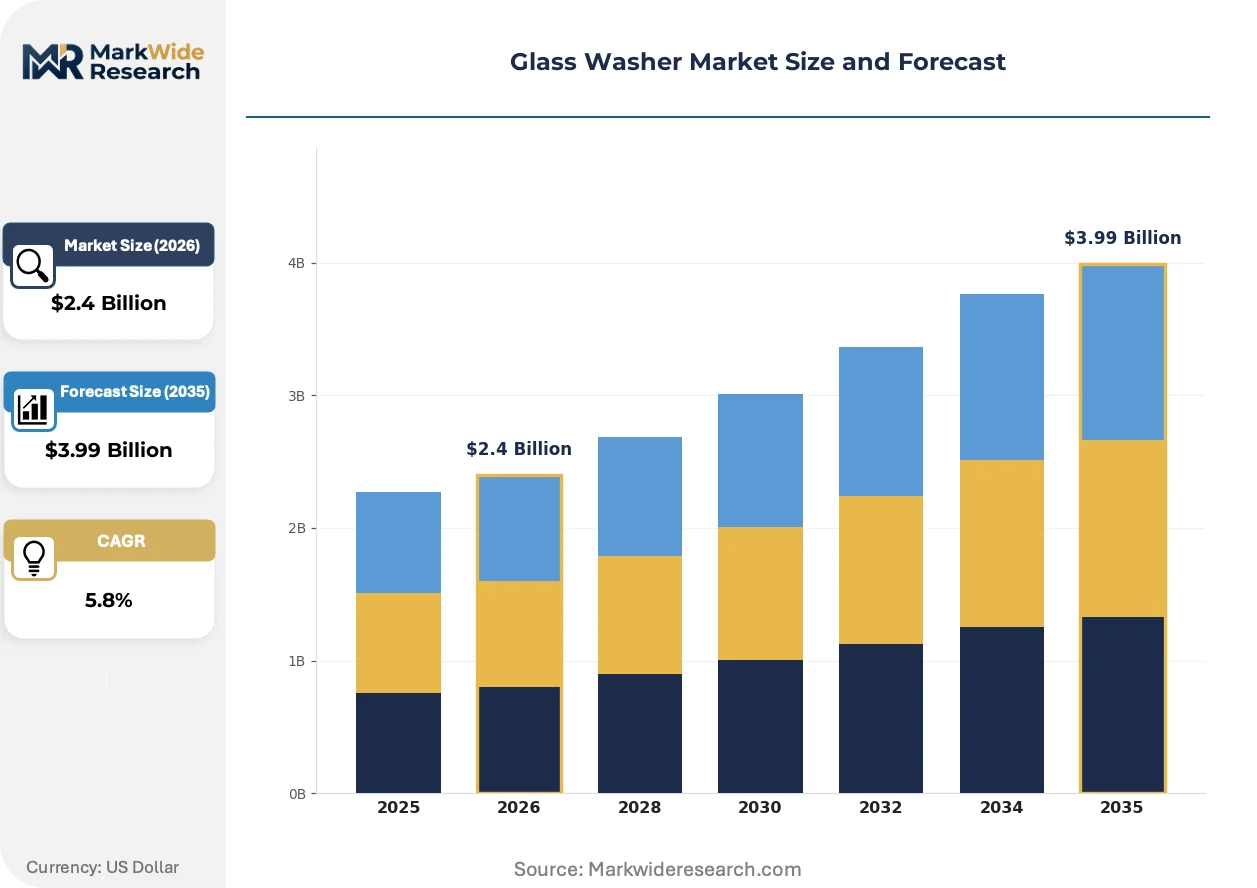
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Glass Washers, Rack Type Glass Washers, Tunnel Glass Washers, Recirculation Glass Washers, Rotary Glass Washers Technology: Manual Operation, Semi-Automatic Operation, Fully Automatic Operation, Ultrasonic Cleaning, High-Pressure Cleaning Application: Commercial Kitchens, Beverage Manufacturing, Pharmaceutical Packaging, Optical Industry, Laboratory Use End User: Hospitality Chains, Pharmaceutical Manufacturers, Optical Equipment Makers, Food Processing Facilities, Research Institutions |
| Companies Covered | Hobart, Ali Group, Fagor Industrial, Jackson Warewashing Systems, Smeg, Winterhalter, Miele Professional, Classeq, Electrolux Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Washer Market Shifts & Advancements
Electromechanical cleaning systems are absorbing digital control layers and aqueous chemistry advances that redefine performance benchmarks and ownership economics across end-use categories.
Ultrasonic transducer arrays paired with precision frequency modulation are absorbing validation requirements for pyrogen and endotoxin removal in pharmaceutical packaging applications. Contract manufacturing organizations and sterile fill-finish facilities are adopting these systems at accelerated pace to meet FDA documentation mandates. This technology is absorbing margin capture from conventional spray-arm systems in segments where substrate cleanliness directly affects patient safety.
The EPA Energy Star program is tightening water consumption limits and heating efficiency minimums for commercial glass washing equipment sold in the United States. Industrial consequence includes accelerated R&D spending on heat recovery systems and low-temperature aqueous chemistry formulations. High-volume hospitality chains and institutional foodservice operators in California and New York are responding with fleet replacement programs ahead of anticipated state-level efficiency mandates.
Buyers in multi-site beverage manufacturing and hospitality operations are consolidating procurement around lifecycle cost metrics rather than upfront equipment price. Distributor and dealer networks are losing ground to direct manufacturer relationships and integrated facility management contracts in this shift. This pattern is most visible in Germany and the United Kingdom, where precision-engineered rack-type systems from specialized European suppliers are displacing generalist equipment through total-cost-of-ownership contracting.
Glass Washer Market Segmentation
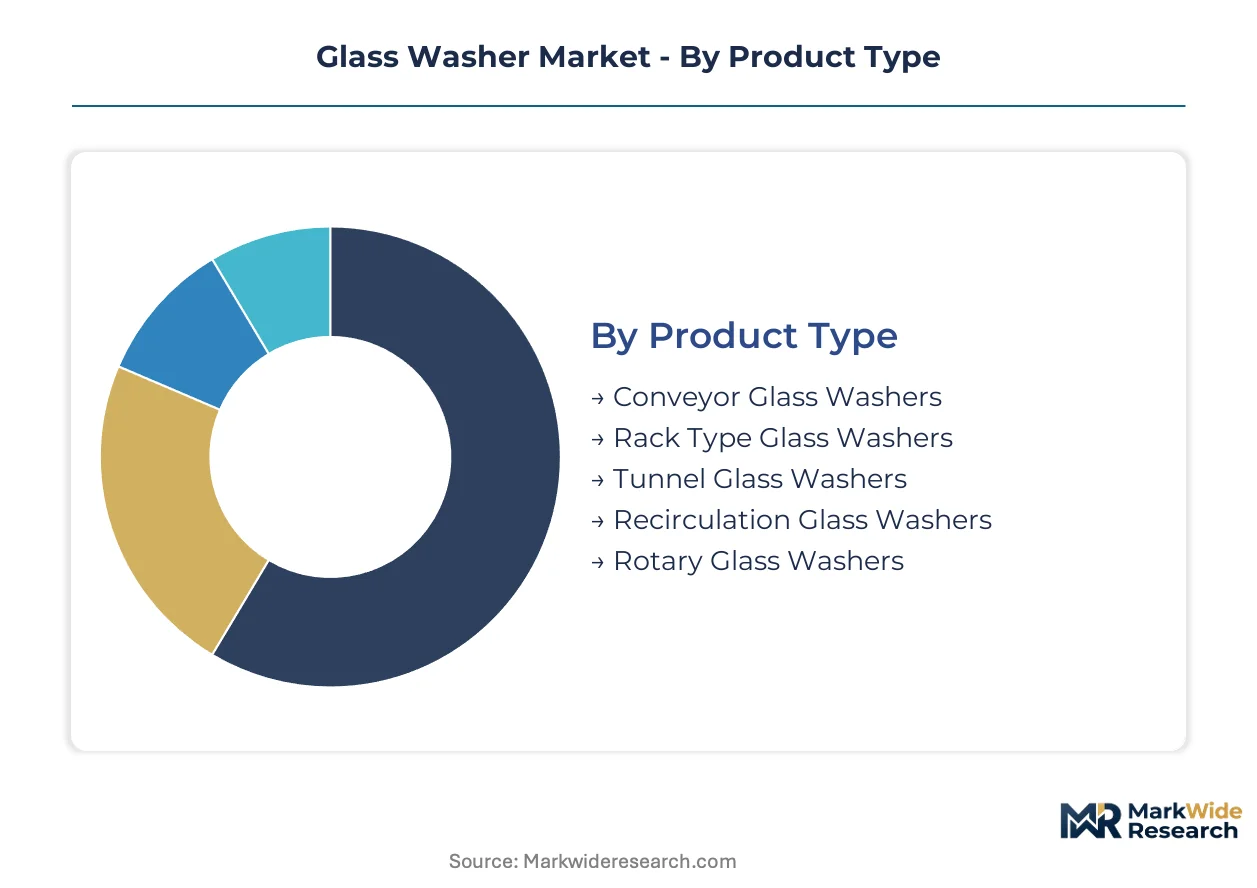
Glass washer segmentation reveals a market bifurcated between high-volume hospitality deployments and precision-validated pharmaceutical installations. Equipment specifications diverge sharply across end-uses, with throughput economics dominating foodservice procurement while contamination protocols govern laboratory and packaging buyer decisions.
Product Type:
Volume throughput separates economy-tier installations from premium precision systems, with continuous-flow architectures commanding hospitality fleets and batch-recirculation designs serving regulated industries.
- Conveyor Glass Washers:Continuous-belt architecture moves glassware through pre-wash, wash, rinse, and dry zones without manual handling. Hospitality chains in the United States and Germany specify these systems for bar and banquet operations where hourly throughput exceeds 2,000 pieces. Labor automation mandates and 24-hour operational requirements cement their position in high-volume foodservice.
- Recirculation Glass Washers:Closed-loop aqueous systems filter and reuse wash water through multiple cycles, cutting consumption by 60-70% versus single-pass designs. Pharmaceutical packaging facilities in Germany and Switzerland deploy these for vial and ampoule cleaning where water validation and pyrogen removal are mandatory. EU Ecodesign Directive tier escalation accelerates replacement of aging single-pass equipment.
- Rack Type Glass Washers:Modular rack systems accommodate variable load configurations for mixed glassware sizes.
- Tunnel Glass Washers:Extended linear chambers handle oversized containers and specialty packaging formats.
- Rotary Glass Washers:Circular indexing tables position glassware for targeted spray or immersion cleaning.
Today's leader: Conveyor Glass Washers. Tomorrow's challenger: Recirculation Glass Washers.
Technology:
Automation intensity tracks labor cost curves and documentation requirements, with manual systems retreating to low-wage markets and ultrasonic platforms capturing premium pharmaceutical validation work.
- Fully Automatic Operation:Programmable logic controllers manage wash cycle parameters, detergent dosing, and temperature profiles without operator intervention. Beverage manufacturing lines in India and Brazil adopt these systems to meet export hygiene standards and reduce headcount. India's PLI scheme for food processing infrastructure subsidizes capital costs for qualifying installations.
- Ultrasonic Cleaning:Piezoelectric transducers generate cavitation bubbles that dislodge sub-micron particles and endotoxins from complex geometries. Research institutions and sterile fill-finish facilities specify these platforms for FDA 21 CFR Part 11 compliance. Frequency-modulated arrays now achieve validated pyrogen removal previously requiring multiple cleaning modalities.
- Semi-Automatic Operation:Operator loads racks but automated systems control wash parameters and cycle sequencing.
- Manual Operation:Hand-fed batch systems persist in small-scale foodservice and emerging market installations.
- High-Pressure Cleaning:Focused spray jets deliver mechanical soil removal for heavily soiled industrial containers.
Manual Operation retains residual share in cost-sensitive segments. Ultrasonic Cleaning climbs the fastest as pharmaceutical validation requirements harden.
Application:
End-use specialization fragments the vendor landscape, with hospitality-focused suppliers lacking the validation infrastructure to serve pharmaceutical and optical manufacturing buyers.
- Commercial Kitchens:High-turnover bar, restaurant, and institutional foodservice operations prioritize speed, reliability, and energy efficiency over contamination protocols. California and New York hospitality operators are replacing fleets ahead of anticipated state-level efficiency mandates tied to EPA Energy Star tightening.
- Pharmaceutical Packaging:Sterile fill-finish lines and contract manufacturing organizations demand washer-disinfector systems with automated cycle logging, pyrogen validation, and seamless MES integration. NSF International and ISO 15883 certification requirements extend vendor qualification cycles, favoring established European specialists.
- Beverage Manufacturing:Bottling and brewing operations balance throughput with label adhesive removal and caustic compatibility.
- Optical Industry:Precision lens and display substrate cleaning requires sub-micron particle control without surface damage.
- Laboratory Use:Research institutions specify versatile platforms accommodating diverse glassware geometries and soil types.
Commercial Kitchens anchor current volume. Pharmaceutical Packaging represents the steepest expansion trajectory as biologics manufacturing capacity expands.
End User:
Procurement consolidation among multi-site operators is shifting purchasing power from distributor networks toward direct manufacturer relationships and integrated facility management contracts.
- Hospitality Chains:Corporate procurement teams standardize equipment specifications across properties to simplify training, maintenance, and supply chain management. Total-cost-of-life contracting now dominates RFP evaluation in Germany and the United Kingdom, displacing upfront price comparisons.
- Pharmaceutical Manufacturers:Quality assurance departments drive vendor selection with validation documentation, audit trails, and change control protocols outweighing capital cost considerations. Integration complexity with legacy SCADA systems raises engineering service costs and technical risk.
- Food Processing Facilities:Dairy and juice processors specify corrosion-resistant construction and sanitary design for CIP compatibility.
- Research Institutions:University and government laboratories balance versatility against capital budget constraints.
- Optical Equipment Makers:Display panel and precision lens manufacturers import specialized European and Japanese ultrasonic systems.
Hospitality Chains dominate unit volume. Pharmaceutical Manufacturers command premium pricing and longest contract durations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters around Stuttgart and Munich anchor global demand for validated pharmaceutical glass washing systems. The country's dominance in sterile fill-finish manufacturing and optical substrate processing concentrates high-margin equipment procurement in Bavaria and Baden-Württemberg.
United States
California and New York hospitality operators are replacing glass washing fleets ahead of anticipated state-level efficiency mandates tied to EPA Energy Star tightening. The FDA's 21 CFR Part 11 documentation requirements for pharmaceutical packaging lines harden demand for automated cycle logging capabilities. Boston's biotech corridor and New Jersey's pharmaceutical belt concentrate washer-disinfector procurement among contract manufacturing organizations.
China
Beverage bottling expansion in the Yangtze River Delta and Pearl River Delta drives conveyor system demand for export hygiene compliance. The country's national pharmaceutical regulator enforces GMP standards that increasingly specify automated cleaning validation. Shanghai and Guangdong province host the fastest-growing installed base of fully automatic glass washing equipment in food processing applications.
India
Dairy and juice processors in Maharashtra and Gujarat specify corrosion-resistant glass washing systems for CIP compatibility under FSSAI sanitary design guidelines. The central government's PLI scheme for food processing infrastructure subsidizes capital costs for qualifying automated installations. Karnataka's beverage manufacturing belt around Bangalore is channeling investment toward continuous-flow architectures.
South Korea
Precision lens and display substrate cleaning demand in the Seoul Capital Area and Busan-Ulsan corridor outpaces domestic ultrasonic system supply. The country's national display industry regulator supports import substitution for validated European and Japanese equipment. Gyeonggi-do province's optical manufacturing clusters are expanding capacity for smartphone camera module and OLED substrate production.
Switzerland
Pharmaceutical packaging facilities in Basel and Zurich deploy recirculation glass washers for vial and ampoule cleaning where water validation and pyrogen removal are mandatory. Swissmedic enforces stringent documentation requirements that extend vendor qualification cycles. The country's sterile fill-finish manufacturing density per capita exceeds all European peers, concentrating premium equipment demand.
Glass Washer Market Competitive Landscape
Strategic partnerships dominate the current landscape as specialized European manufacturers seek validation expertise for pharmaceutical segments. The vendor base organizes around three tiers: diversified kitchen equipment conglomerates with institutional heritage, precision-engineered rack-type specialists serving regulated industries, and laboratory-grade ultrasonic platform providers. Two archetypes define competitive positioning: hospitality-focused suppliers competing on throughput economics, and compliance-oriented specialists capturing pharmaceutical validation premiums. Geographic expansion and technology licensing represent the dominant competitive moves, with European precision engineering firms licensing ultrasonic transducer arrays to Asian fabricators.
Among diversified kitchen equipment conglomerates, Hobart and Electrolux Professional exemplify scale-driven positioning across hospitality chains and institutional foodservice. Winterhalter and Miele Professional occupy the precision-engineered tier, with the former anchoring European pharmaceutical compliance demand and the latter representing laboratory-grade ultrasonic specialization. Ali Group sits within the mid-market consolidation archetype, reflecting Italian manufacturing heritage in commercial foodservice equipment. These five entities collectively span the pricing and validation spectrum from economy-tier hospitality installations to FDA-compliant pharmaceutical packaging lines.
| Leading Market Players |
|---|
| Hobart |
| Ali Group |
| Fagor Industrial |
| Jackson Warewashing Systems |
| Smeg |
| Winterhalter |
| Miele Professional |
| Classeq |
| Electrolux Professional |
| Others |
Supply & Pricing Matrix
Family-owned precision engineering specialists in southern Germany anchor premium pricing discipline through captive control over ultrasonic transducer fabrication and validation documentation workflows. Their ownership structure insulates margin architecture from quarterly earnings pressure, allowing sustained investment in pharmaceutical compliance infrastructure that generalist conglomerates cannot replicate.
Pricing Analysis
Distributor margin compression now runs through European and North American hospitality equipment channels as multi-site operators consolidate procurement around direct manufacturer relationships. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from NSF-certified foodservice installations and unvalidated emerging-market equipment. Price differentiation hinges on certification grade and after-sales service bundling, with pharmaceutical buyers exhibiting minimal price sensitivity compared to hospitality chains facing labor cost compression. Pricing pressure stems from stainless steel input volatility and tariff exposure on East Asian electronic components.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical and beverage manufacturing demand, while distributor networks serve fragmented hospitality and laboratory end-users. Manufacturing concentration centers on Germany, Italy, and China, with precision spray arm assemblies and heating elements drawing from East Asian component clusters. Raw material dependencies span stainless steel grades, piezoelectric ceramics, and programmable logic controllers. Single-source vulnerability for specialized ultrasonic transducers exposes equipment margins to logistics disruption. Distribution runs through authorized service networks for validated pharmaceutical installations and independent dealers for commercial foodservice.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glass washer market functions as a regulatory compounder where EU Ecodesign Directive tier escalation and FDA 21 CFR Part 11 mandates continuously reset equipment replacement cycles and validation thresholds.
For Market Incumbents: Deepen backward integration into ultrasonic transducer production to defend margin architecture against East Asian component volatility. Expand captive validation documentation capacity to compress NSF International and ISO 15883 certification timelines that currently delay revenue recognition. Prioritize MES integration engineering capabilities to capture pharmaceutical packaging line retrofits where legacy SCADA handoff complexity raises technical risk for generalist competitors. For New Entrants and Emerging Players: Digital-channel routes through integrated facility management platforms offer lowest-friction entry into multi-site hospitality chain procurement. Target South Korea's optical manufacturing corridor where precision lens cleaning demand outpaces domestic ultrasonic supply. Focus initial commercialization on recirculation system technology for Indian beverage processing facilities capitalizing on PLI scheme subsidies. Pursue technology licensing partnerships with established European validators rather than building compliance infrastructure independently. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale rack-type specialists possessing pharmaceutical compliance credentials but lacking hospitality scale diversification. Long-term viability favors vendors with dual capability across validated laboratory platforms and high-throughput conveyor architectures. Acquisition candidates should demonstrate installed base density in Germany or Switzerland where sterile fill-finish manufacturing concentration sustains replacement demand. Monitor EU Ecodesign tier implementation velocity as inflection indicator for European fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Transducer Array Licensing | European precision engineers capture royalty streams from Asian fabricators seeking pharmaceutical validation credibility. |
| Predictive Maintenance Platform Launch | IoT-enabled wash-cycle monitoring opens recurring revenue from hospitality chains under labor automation mandates. |
| Backward Integration into Heating Elements | Captive production of precision spray arm assemblies insulates margins from East Asian tariff and logistics volatility. |
| Pharmaceutical Validation Partnership | Third-party documentation alliances accelerate route-to-market for specialized manufacturers entering regulated segments. |
| South Korean Optical Corridor Expansion | Import substitution potential concentrates in Gyeonggi-do province display substrate manufacturing clusters. |
Research Methodology
Direct dialogue with plant engineers at beverage bottling facilities, pharmaceutical packaging quality assurance directors, hospitality chain procurement heads, and aftermarket service technicians grounded qualitative findings in operational reality. Secondary validation drew from EPA Energy Star equipment databases, EU Ecodesign Directive implementation notices, FDA 21 CFR Part 11 guidance documents, and ISO 15883 washer-disinfector specifications. Bottom-up and top-down triangulation reconciled equipment shipment data with end-user capital expenditure disclosures across the analysis window.
Bottom-up modeling aggregated unit economics across product type, technology intensity, application vertical, and end-user procurement archetype segments. Top-down constraints incorporated macroeconomic indicators for capital equipment investment, regulatory compliance cost indices, and labor automation adoption curves. CAGRs derived from segment-level growth rate reconciliation against aggregate market boundary conditions. Industry-specific forecast inputs included pharmaceutical packaging capacity expansion pipelines, hospitality chain property development schedules, and optical manufacturing cluster investment announcements.
The model assumes a particular technology adoption path; alternative pathways for aqueous chemistry substitution or single-use consumable penetration would alter the outlook. Forecasts reflect base-case assumptions regarding Ecodesign tier implementation timing, stainless steel price normalization, and pharmaceutical validation protocol stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Linear Transfer System Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
North America Industrial Centrifuge Market