
 Femtosecond Fiber Lasers Market | 2026-2036
Femtosecond Fiber Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Femtosecond Fiber Lasers Market Foresight
Medical device manufacturers is reorganizing procurement priorities around femtosecond platforms for ophthalmic and dermatological procedures. IPG Photonics Corporation leverages its vertically integrated fiber amplifier architecture to control cost curves across near-infrared product lines. Coherent Corp. sustains technology leadership in passively mode-locked oscillator designs for scientific research customers. TRUMPF SE + Co. KG anchors German industrial demand with systems optimized for precision cutting and drilling workflows.
Femtosecond fiber lasers generate ultrashort optical pulses with durations below one picosecond, typically operating at center wavelengths between 1030 nm and 1560 nm through rare-earth-doped silica fiber gain media. These systems achieve peak powers in the megawatt range while maintaining average power below thermal damage thresholds, enabling cold ablation in materials processing and non-thermal tissue interaction in surgical applications. Near infrared systems dominate current manufacturing revenue streams due to established reliability in metal and semiconductor micromachining, while ultraviolet configurations capture expanding margin pools from medical surgery applications requiring shorter wavelengths for precise tissue interaction. Mode-locked technology leads volume shipments, though hybrid architectures are gaining traction among research institutions seeking tunable pulse parameters.
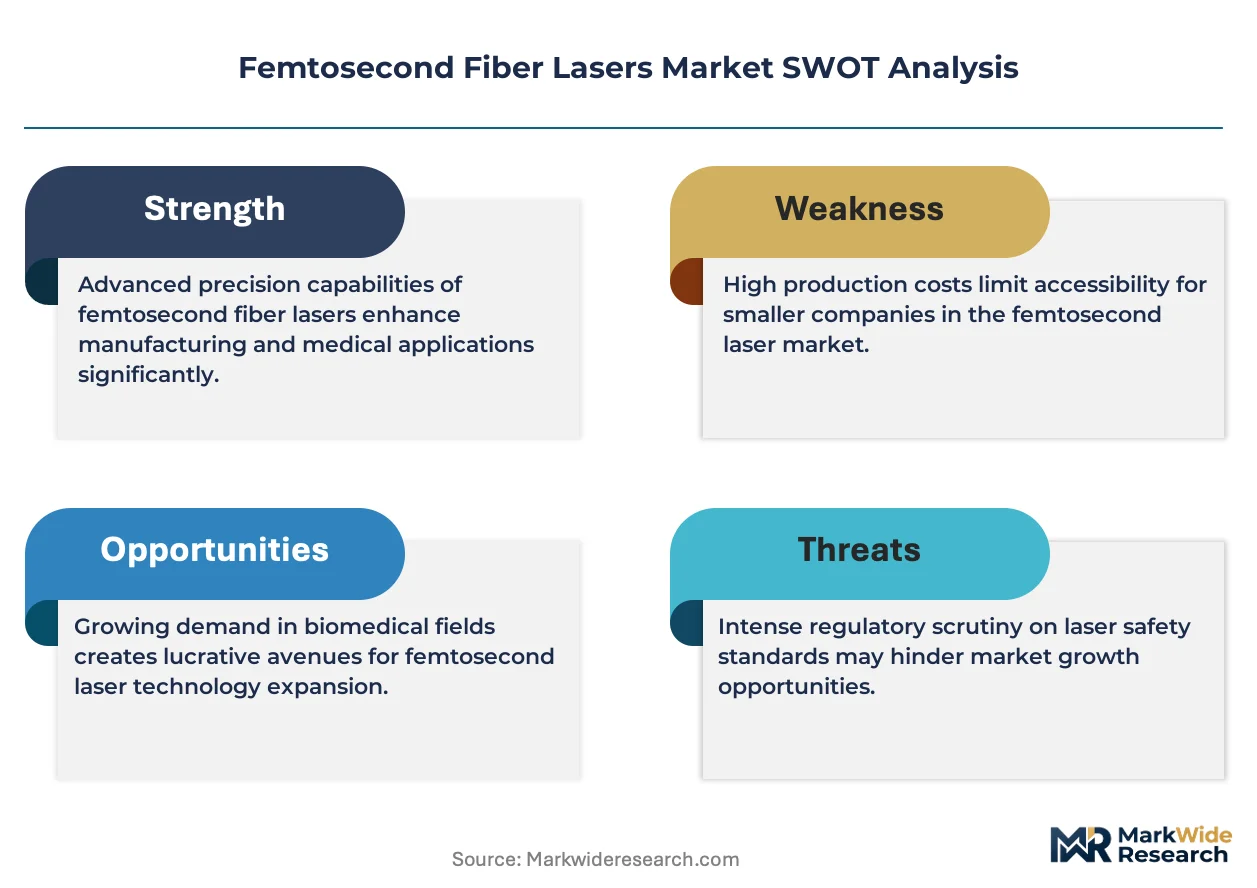
FDA 21 CFR 1040 governs laser product performance standards in the United States, mandating emission limits and safety interlocks that directly shape engineering requirements for medical and industrial systems. IEC 60825-1 provides the international baseline for laser safety classification, with CE marking under the EU Machinery Directive adding conformity assessment layers for European market access. Stakeholders must monitor evolving harmonization between FDA and EU MDR requirements for surgical laser systems, as divergence in electromagnetic compatibility and clinical evidence standards would fragment certification pathways and extend time-to-market for next-generation platforms.
Market Dynamics
Ultrafast pulse generation is converging with semiconductor-style manufacturing economics as rare-earth fiber amplifiers displace bulk solid-state architectures in precision applications. This technological inflection compresses system footprints while elevating thermal management requirements across medical and industrial deployment environments.
Growth Catalysts
- Ophthalmic surgery demand:Corneal refractive procedures and cataract fragmentation protocols are expanding installed base requirements for sub-100 femtosecond pulse systems in ambulatory surgical centers.
- FDA 21 CFR 1040 harmonization:Convergence between US laser safety standards and IEC 60825-1 classification protocols is streamlining multi-jurisdictional product certification timelines for manufacturers.
- German precision manufacturing belt:Stuttgart-to-Munich industrial corridors are anchoring demand for ultraviolet configurations in micromachining workflows serving automotive and electronics supply chains.
Market Restraints
- Pump diode cost volatility:Ytterbium-doped fiber systems depend on gallium arsenide pump sources concentrated among limited semiconductor foundry suppliers.
- Beam delivery complexity:Single-mode fiber preservation of pulse coherence requires specialized hollow-core photonic crystal fiber assemblies with constrained supplier bases.
- CE marking under EU MDR:Extended conformity assessment procedures for surgical laser systems are elongating time-to-revenue for European market entry.
Strategic Opportunities
- India medical device corridors:CDSCO regulatory pathway simplification under Production Linked Incentive schemes is attracting contract manufacturing investment for ophthalmic system assembly.
- Neurostimulation fabrication:Polymer microstructuring for implantable electrode arrays represents an emerging precision ablation application with unmet throughput requirements.
- Hybrid oscillator-amplifier architectures:Convergence of mode-locked seed sources with chirped pulse amplification is enabling tunable parameter platforms for research institutions.
Industry Challenges
- Ultrafast optics engineering scarcity:Specialized expertise in dispersion compensation and nonlinear pulse propagation remains concentrated among limited academic and national laboratory training pipelines.
- Cleanroom assembly infrastructure:Contamination-sensitive fiber splicing and connector termination require capital-intensive controlled environment facilities with extended commissioning cycles.
- IEC 60825-1 classification testing:Extended third-party verification timelines for peak power measurement protocols are compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Femtosecond Fiber Lasers Market |
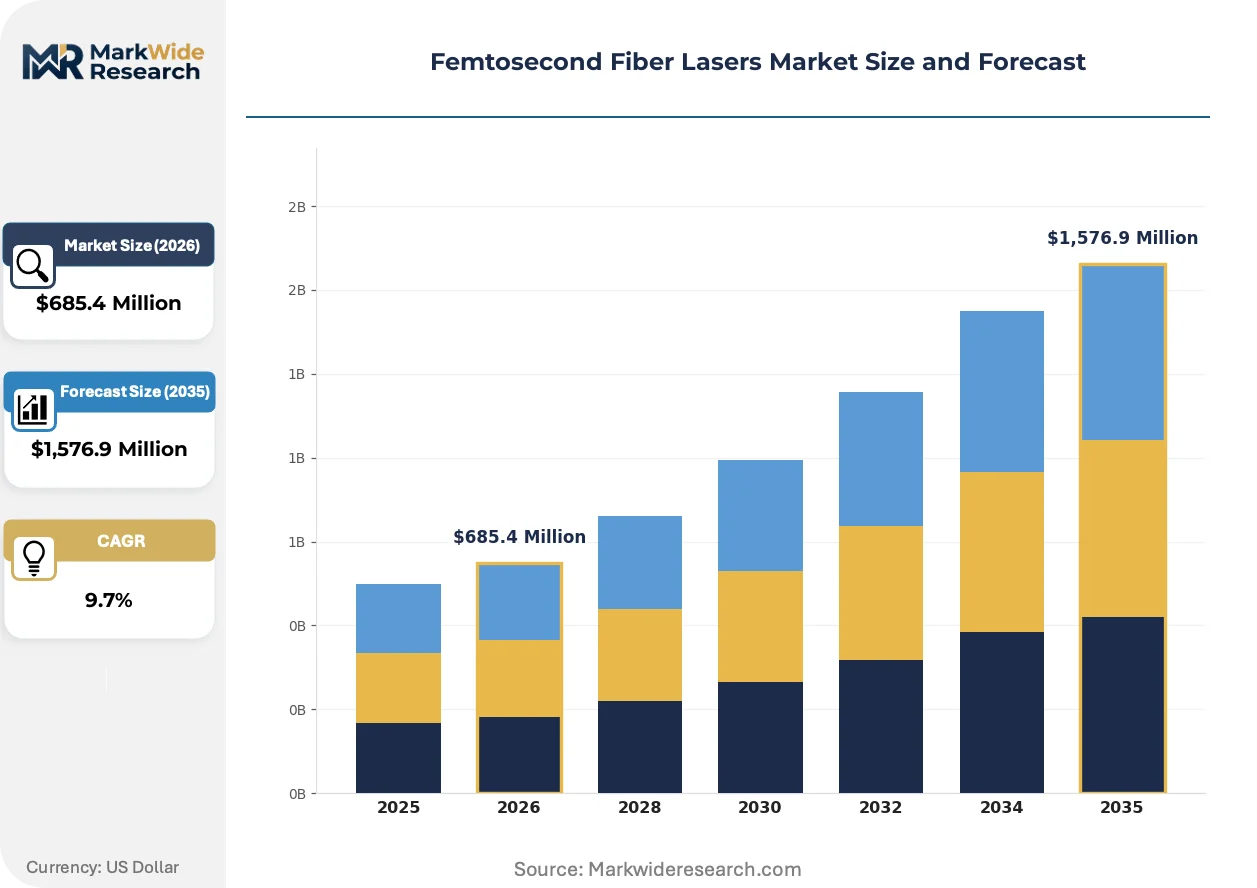
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
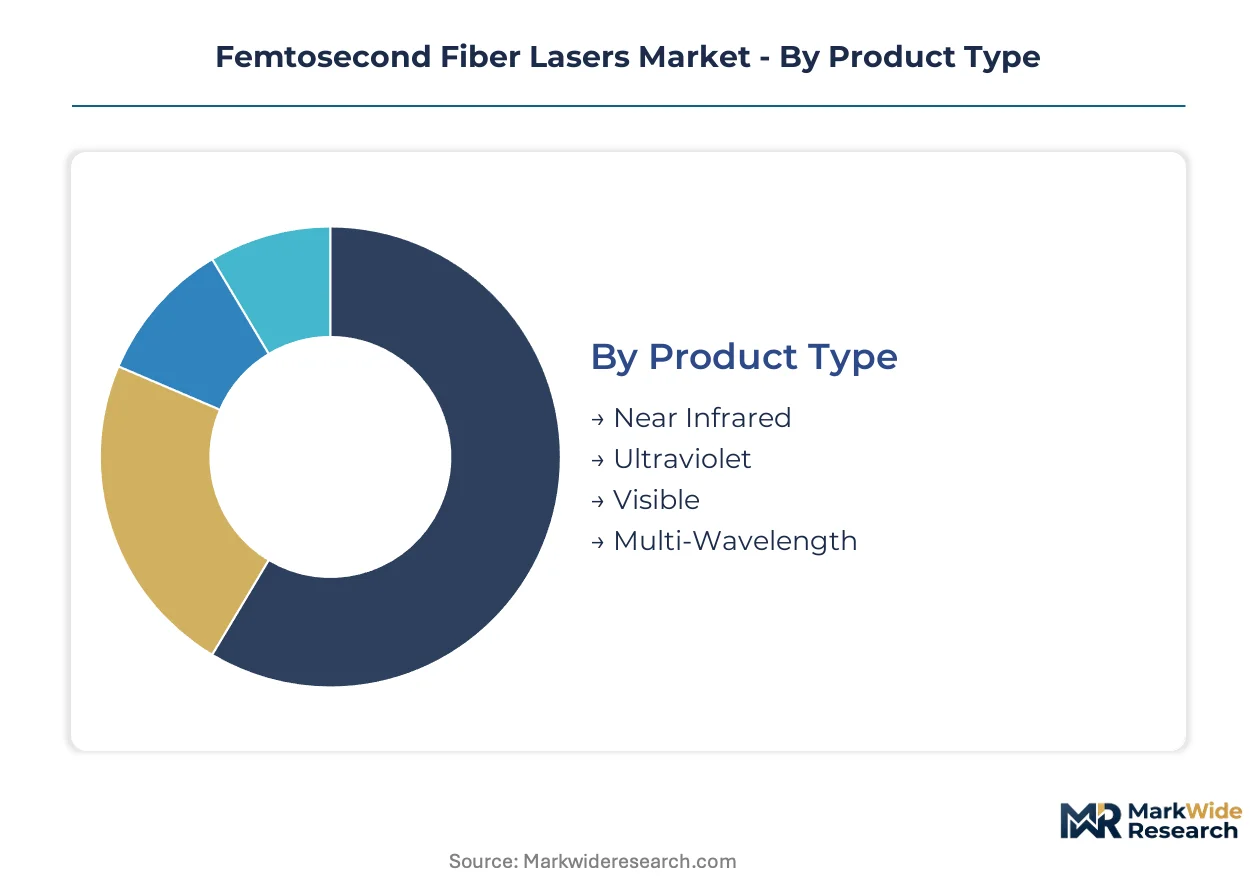
| Segmentation | Product Type: Near Infrared, Ultraviolet, Visible, Multi-Wavelength Technology: Mode-Locked, Passively Mode-Locked, Hybrid, Saturable Absorber Application: Material Processing, Medical Surgery, Scientific Research, Data Communication End User: Manufacturing, Healthcare, Telecommunications, Research Institutions |
| Companies Covered | IPG Photonics Corporation, Coherent Corp., TRUMPF SE + Co. KG, Calmar Laser, Menlo Systems, IMRA America, Inc., EKSPLA, TOPTICA Photonics AG, MKS Instruments Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Femtosecond Fiber Lasers Market Shifts & Advancements
Femtosecond fiber laser engineering is migrating toward integrated photonic subsystems that merge amplification, pulse shaping, and beam conditioning within hermetic packages. This architectural compression is redrawing competitive boundaries between component suppliers and system integrators.
Fiber-coupled semiconductor saturable absorber mirror technology is miniaturizing mode-locking mechanisms into millimeter-scale footprints compatible with handheld surgical consoles. Dermatology clinics and refractive surgery centers in South Korea and Japan are piloting these compact platforms for office-based procedures. The structural consequence is collapsing the traditional distinction between capital equipment and disposable instrument categories, forcing business model recalibration among established suppliers.
EU MDR clinical evidence requirements are elevating post-market surveillance obligations for surgical laser systems marketed in European Economic Area member states. Manufacturers must now maintain systematic literature review protocols and periodic safety update reporting that mirror pharmaceutical vigilance frameworks. Dermatological application segments face the steepest compliance cost escalation as legacy devices require retrospective clinical data generation to maintain CE certification validity.
Hospital procurement departments are consolidating femtosecond laser acquisitions under centralized capital equipment committees rather than decentralized surgical department authority. This purchasing concentration is displacing traditional distributor relationships with direct manufacturer engagement models in tertiary care networks across Texas, California, and New York metropolitan clusters. After-sales service contracts are unbundling from hardware pricing, creating standalone recurring revenue streams that alter lifetime value calculations for vendor sales organizations.
Femtosecond Fiber Lasers Market Segmentation
Femtosecond fiber laser procurement channels diverge sharply by application complexity and regulatory burden. Industrial buyers route through systems integrators for turnkey micromachining cells, while medical customers demand direct manufacturer relationships for FDA-validated surgical platforms.
Product Type:
Channel economics vary substantially across wavelength configurations, with ultraviolet systems commanding premium direct sales channels and near-infrared products flowing through distribution partnerships.
- Near Infrared:Ytterbium-doped fiber amplifiers at 1030-1064 nm deliver megawatt peak powers for metal ablation. Stuttgart-to-Munich manufacturing corridors anchor procurement volume for precision cutting workflows serving automotive supply chains.
- Ultraviolet:Frequency-converted systems at 343-355 nm enable cold ablation of polymers and biological tissue. Ambulatory surgical centers in Texas and California are expanding installed base requirements for corneal refractive procedures.
- Visible:Frequency-doubled green outputs at 515-532 nm address specialized scientific imaging applications. Research institutions in Japan pilot these platforms for nonlinear microscopy.
- Multi-Wavelength:Tunable or dual-output architectures combine fundamental and harmonic generation in single enclosures. Photonics OEMs in South Korea integrate these for flexible manufacturing cells.
Near Infrared dominates installed base. Ultraviolet is where expansion concentrates.
Technology:
Cost tiers stratify sharply by complexity, with passive mode-locking commanding economy positioning and hybrid architectures capturing premium research budgets.
- Mode-Locked:Active modulation via electro-optic or acousto-optic elements delivers stable pulse trains for industrial micromachining. German precision manufacturers specify these for 24/7 production reliability.
- Passively Mode-Locked:Saturable absorber or nonlinear polarization rotation eliminates active components. Scientific research customers prioritize these for lowest timing jitter in spectroscopy applications.
- Hybrid:Combined active-passive architectures enable tunable repetition rates and pulse energies. National laboratories in the United States commission these for multi-experiment flexibility.
- Saturable Absorber:Semiconductor or carbon nanotube-based Q-switching miniaturizes into fiber-coupled packages. Dermatology clinics in Japan pilot handheld surgical consoles built around these mechanisms.
Passively Mode-Locked leads volume shipments. Hybrid is climbing the fastest.
Application:
Customer type determines margin structure, with medical surgery capturing premium pricing and material processing driving scale economics.
- Material Processing:Micromachining of metals, semiconductors, and ceramics through cold ablation. Electronics foundries in Taiwan deploy these for via drilling and thin-film patterning.
- Medical Surgery:Ophthalmic corneal cuts and dermatological tissue ablation with minimized thermal damage. Cataract fragmentation protocols in ambulatory surgical centers are expanding sub-100 femtosecond system procurement.
- Scientific Research:Time-resolved spectroscopy, multiphoton microscopy, and attosecond pulse generation. University consortia in Germany anchor demand for high-repetition-rate oscillator systems.
- Data Communication:Optical time-division multiplexing and high-speed signal processing. Telecommunications infrastructure vendors evaluate these for next-generation backbone upgrades.
Material Processing dominates revenue contribution. Medical Surgery is where margin expansion concentrates.
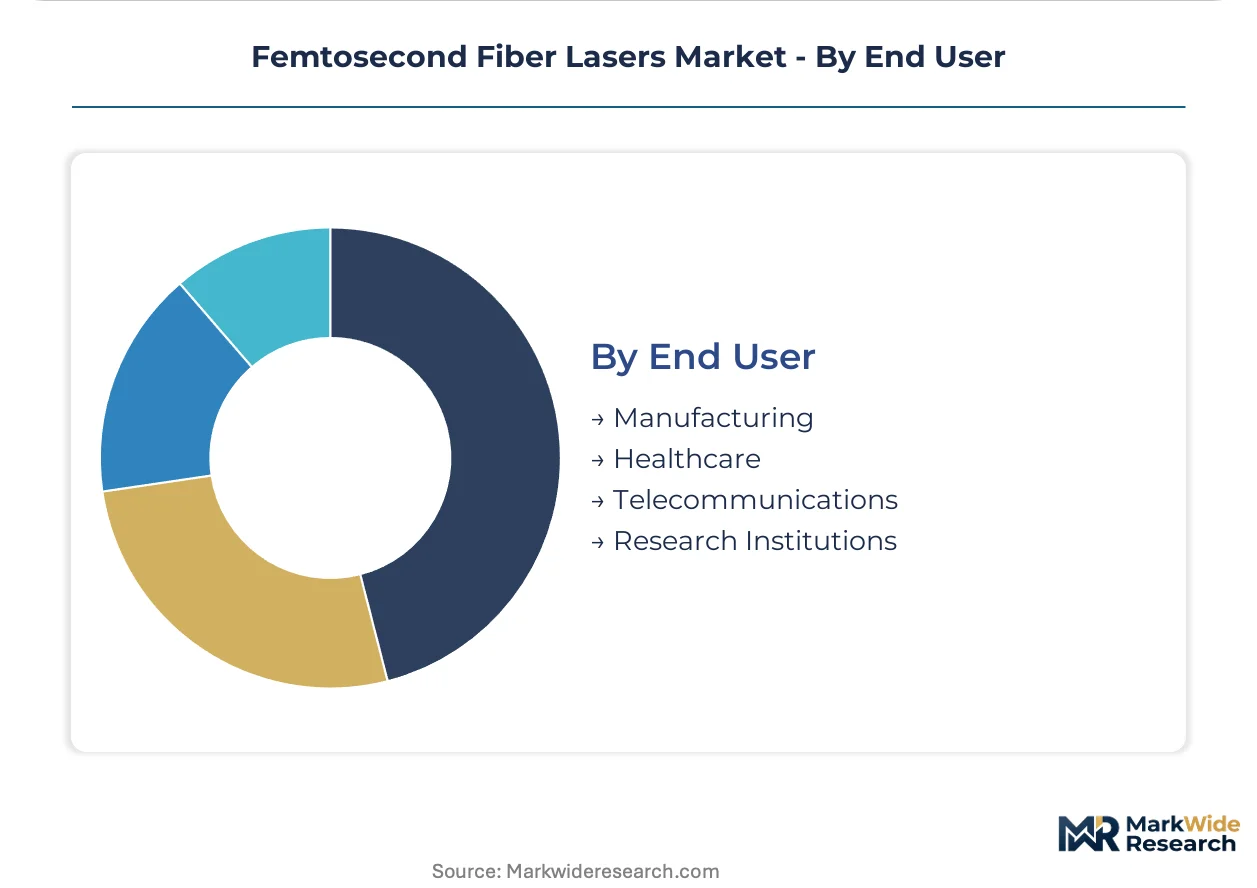
End User:
Supply concentration aligns with geographic clustering of cleanroom assembly infrastructure and specialized technical service capabilities.
- Manufacturing:Precision machining shops and electronics fabricators requiring turnkey micromachining systems. Automotive tier-1 suppliers in Bavaria specify ultraviolet configurations for polymer component trimming.
- Healthcare:Hospital systems and ambulatory surgical centers purchasing FDA-validated surgical platforms. Tertiary care networks in Texas and California are consolidating procurement under centralized capital equipment committees.
- Telecommunications:Network equipment manufacturers and data center operators. Infrastructure deployment in India under Production Linked Incentive schemes is attracting system integrator investment.
- Research Institutions:National laboratories and university photonics departments. Max Planck Institute facilities anchor German demand for custom oscillator-amplifier configurations.
Manufacturing leads unit shipments. Healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers export ultraviolet configurations to medical device OEMs in Texas and California, while South Korean photonics integrators supply multi-wavelength architectures to research consortia in Japan and Germany.
United States
Ambulatory surgical centers in Texas and California are expanding procurement of sub-100 femtosecond systems for corneal refractive procedures. FDA 21 CFR 1040 governs laser product performance standards, mandating emission limits and safety interlocks that shape engineering requirements. Tertiary care networks across metropolitan clusters are consolidating acquisitions under centralized capital equipment committees, displacing traditional distributor relationships.
Germany
The Stuttgart-to-Munich industrial corridor anchors demand for ultraviolet configurations in micromachining workflows serving automotive and electronics supply chains. IEC 60825-1 provides the international baseline for laser safety classification, with CE marking under the EU Machinery Directive adding conformity assessment layers. TRUMPF SE + Co. KG and TOPTICA Photonics AG anchor regional supply chains for precision cutting and drilling applications.
Japan
Dermatology clinics and refractive surgery centers are piloting fiber-coupled semiconductor saturable absorber mirror technology for handheld surgical consoles. METI oversees industrial standards coordination for photonics manufacturing equipment. Research institutions in Kanto and Kansai regions commission high-repetition-rate oscillator systems for nonlinear microscopy applications.
South Korea
Photonics OEMs integrate multi-wavelength tunable architectures into flexible manufacturing cells for electronics fabrication. The national industrial policy supports domestic production of rare-earth fiber amplifier components. Seoul-based system integrators are expanding contract manufacturing capacity for ophthalmic laser console assembly.
India
CDSCO regulatory pathway simplification under Production Linked Incentive schemes is attracting contract manufacturing investment for ophthalmic system assembly. The country's national pharmaceutical regulator is streamlining medical device approval timelines for imported laser platforms. Medical device corridors in Maharashtra and Karnataka are emerging as assembly hubs for ultraviolet surgical systems.
Femtosecond Fiber Lasers Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification depth. The market exhibits tiered concentration with vertically integrated fiber amplifier architects occupying premium positions and component specialists serving research niches. Three archetypes dominate: rare-earth fiber platform owners, mode-locked oscillator designers, and surgical system integrators. M&A activity targets specialized hollow-core photonic crystal fiber capabilities, while capacity expansion concentrates in cleanroom assembly infrastructure for contamination-sensitive fiber splicing.
Within the vertically integrated tier, IPG Photonics Corporation exemplifies captive control over fiber amplifier architecture. Among German precision manufacturers, TRUMPF SE + Co. KG and TOPTICA Photonics AG occupy positions anchored in Stuttgart-to-Munich industrial demand. These three represent distinct competitive vectors: cost curve management, industrial workflow optimization, and scientific research platform leadership.
| Leading Market Players |
|---|
| IPG Photonics Corporation |
| Coherent Corp. |
| TRUMPF SE + Co. KG |
| Calmar Laser |
| Menlo Systems |
| IMRA America, Inc. |
| EKSPLA |
| TOPTICA Photonics AG |
| MKS Instruments Inc. |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with gallium arsenide foundries lock in pump diode supply for ytterbium-doped fiber amplifier manufacturers while freezing cost visibility across near-infrared system production. These arrangements tether pricing power to semiconductor wafer allocation priority under FDA 21 CFR 1040 and IEC 60825-1 certification timelines.
Pricing Analysis
Current-generation passively mode-locked oscillator platforms command 40-60% premiums over prior-generation active modulation systems due to reduced timing jitter specifications for scientific research customers. Three-tier pricing structure across FDA-validated surgical platforms, industrial micromachining cells, and research-grade benchtop systems stratifies by certification grade and after-sales service bundling. Pricing pressure stems from gallium arsenide pump diode cost volatility concentrated among limited semiconductor foundry suppliers. Healthcare procurement committees demonstrate lowest price sensitivity due to reimbursement-protected surgical applications, while electronics foundries exhibit highest sensitivity driving volume negotiations for ultraviolet configurations.
Supply Chain Analysis
Extended lead times for hollow-core photonic crystal fiber assemblies now stretch 16-24 weeks, constraining pulse delivery subsystem availability for mode-locked platform integrators. Rare-earth fiber amplifier manufacturing concentrates in Germany, the United States, and Japan, drawing from ytterbium-doped silica preform suppliers anchored in specialty glass foundries. Gallium arsenide pump diodes, semiconductor saturable absorber mirrors, and polarization-maintaining fiber patchcords constitute critical input dependencies. Single-source vulnerability in photonic crystal fiber fabrication threatens production continuity for medical surgery system OEMs. Distribution runs through direct manufacturer engagement for FDA-validated platforms and systems integrator partnerships for industrial micromachining cells.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Femtosecond fiber laser adoption sits in early-cycle expansion as ambulatory surgical centers accelerate procurement of sub-100 femtosecond systems for cataract fragmentation protocols ahead of full market penetration.
For Market Incumbents: Secure captive supply of gallium arsenide pump diodes through backward integration or long-term offtake agreements to defend margin position against semiconductor foundry concentration. Fortify cleanroom assembly infrastructure in Germany's precision manufacturing belt to preempt emerging South Korean and Indian contract manufacturers from capturing ultraviolet surgical system assembly share. For New Entrants and Emerging Players: After-sales service unbundling from hardware pricing represents a service-layer gap where established suppliers under-serve price-sensitive electronics foundries in Taiwan and South Korea. Target India medical device corridors under CDSCO Production Linked Incentive schemes for ophthalmic system assembly contracts. Pursue partnership-based entry with German automotive tier-1 suppliers seeking localized ultraviolet micromachining cell support. For Investors and Strategic Acquirers: Capital is best deployed toward hollow-core photonic crystal fiber specialists and saturable absorber mirror designers with defensible IP positions across the 5-10 year technology refresh cycle. Acquisition candidates must demonstrate FDA 21 CFR 1040 or CE marking under EU MDR pathway experience. Watch for inflection when hospital procurement committee consolidation in Texas and California metropolitan clusters accelerates direct manufacturer contract awards.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR conformity assessment acceleration compresses time-to-revenue for surgical laser platforms. |
| Backward Integration into Pump Diodes | Gallium arsenide wafer allocation priority secures cost visibility for ytterbium-doped fiber amplifiers. |
| Hospital System Partnership | Direct engagement with Texas and California tertiary care networks displaces distributor relationships. |
| Hollow-Core Fiber Acquisition | Photonic crystal fiber capabilities address beam delivery complexity constraining pulse coherence preservation. |
| India Contract Manufacturing Scale-Up | CDSCO regulatory simplification under Production Linked Incentive schemes attracts ophthalmic assembly investment. |
Research Methodology
A standing panel of femtosecond laser system engineers, ambulatory surgical center procurement directors, FDA regulatory affairs specialists, and German automotive tier-1 manufacturing engineers provided ongoing calibration across primary interview protocols. Secondary validation drew from FDA 510(k) filings, IEC 60825-1 certification databases, EU MDR conformity assessment records, and SEC filings of publicly traded fiber amplifier manufacturers. Bottom-up demand modeling across wavelength configurations, technology architectures, and application segments triangulated against top-down industry revenue estimates.
Consistency checks validated volume and value outputs against external benchmarks including rare-earth fiber amplifier shipment data, pump diode import records, and hospital capital equipment procurement databases. Segmentation dimensions spanned wavelength configuration, mode-locking technology, application complexity, and end-user regulatory burden across the projection horizon. CAGRs were derived from installed base expansion rates, replacement cycles, and penetration assumptions for emerging applications including neurostimulation fabrication. Industry-specific inputs incorporated FDA 21 CFR 1040 harmonization progress and EU MDR clinical evidence requirement evolution.
Forecasts assume regulatory continuity in FDA, EU MDR, and CDSCO regimes; material policy shifts in laser safety classification or medical device approval timelines would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Magnetizing Equipment Market