
 Jet Dispenser Market | 2026-2036
Jet Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Jet Dispenser Market Insights
East Asian precision equipment producers is consolidating around automated micro-dispensing platforms for semiconductor backend assembly. Nordson Corporation leverages its polymer melt delivery heritage to anchor high-throughput jet valve architectures. Musashi Engineering Inc. competes through piezoelectric actuator specialization in sub-nanoliter deposition. Graco Inc. sustains industrial fluid handling scale across automotive adhesive lines.
Jet dispensers are non-contact fluid deposition systems that eject precise micro-volumes through piezoelectric or pneumatic actuation at frequencies exceeding 1,000 Hz, primarily serving electronics packaging, medical device coating, and industrial bonding applications. Air jet technology dominates high-speed electronics manufacturing where throughput outweighs viscosity range, while piezoelectric systems capture premium positioning in pharmaceutical filling where dosing accuracy within one percent drives specification. Electronics manufacturing application pools sit deepest in value terms, though pharmaceutical filling segments widen fastest as aseptic single-use protocols displace traditional peristaltic methods.
FDA 21 CFR Part 11 and EPA VOC emission frameworks constrain material selection and validation protocols for pharmaceutical and industrial jet dispensing deployments in the United States. ISO 13485 quality management and EU MDR traceability requirements elevate barrier-to-entry for medical device fluid deposition suppliers serving European markets. Stakeholders must monitor evolving RoHS substance restrictions and dual-use export control classifications affecting piezoelectric ceramic sourcing before committing to capacity expansion or platform redesign cycles.
Market Dynamics
Semiconductor packaging miniaturization is compressing deposition tolerances below 50 microns, forcing equipment suppliers to recalibrate pneumatic and piezoelectric architectures around sub-nanoliter precision while navigating multi-jurisdictional substance restrictions on piezoelectric ceramics.
Growth Catalysts
- Advanced Packaging Proliferation:Chiplet architectures and 3D stacking in high-performance computing are multiplying bonding points per die, driving throughput requirements beyond 1,500 Hz deposition frequencies in Taiwan and South Korea fabrication facilities.
- EPA VOC Framework Tightening:Industrial adhesive applications in the United States face escalating emission thresholds, accelerating displacement of contact dispensing with closed-loop jet systems that eliminate solvent flash-off.
- Single-Use Biopharma Protocols:Aseptic filling operations are abandoning peristaltic pumps for disposable fluid-path jet dispensers, with FDA 21 CFR Part 11 validation requirements creating specification pull in Massachusetts and North Carolina biotech clusters.
Market Restraints
- Piezoelectric Ceramic Concentration:Lead zirconate titanate supply chains concentrate in Chinese and Japanese specialty ceramic producers, exposing equipment OEMs to dual-use export licensing delays and RoHS substance scrutiny.
- Validation Burden:ISO 13485 medical device quality management and EU MDR traceability mandates extend qualification timelines for pharmaceutical filling deployments to 18-24 months, compressing near-term revenue recognition.
- High-Viscosity Limitation:Pneumatic jet valves face fundamental physics constraints above 500,000 cP, preserving screw-pump dominance in automotive structural adhesive lines where thermal management compounds dominate material selection.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile phone assembly are attracting contract manufacturers to Gujarat and Tamil Nadu, creating greenfield automation specification windows for jet dispensing integrators.
- Battery Cell Bonding:Thermal interface material deposition in cylindrical and prismatic cell assembly is expanding jet dispenser addressable scope beyond traditional electronics, with cylindrical formats in Nevada and Hungary plants driving 2024-2025 equipment trials.
- EU Green Deal Chemistry:REACH authorization requirements for conventional adhesive hardeners are forcing formulation shifts toward UV-curable and moisture-cure chemistries compatible with non-contact deposition, advantaging jet valve architectures in German automotive supply chains.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Fluid dynamics simulation, piezoelectric control firmware, and semiconductor process engineering rarely coexist in single engineering teams, elongating R&D cycles for next-generation valve architectures.
- Legacy MES Integration:Brownfield electronics assembly lines in Malaysia and Mexico run on 1990s-era manufacturing execution systems lacking SECS/GEM connectivity, requiring costly middleware development for jet dispenser data logging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jet Dispenser Market |
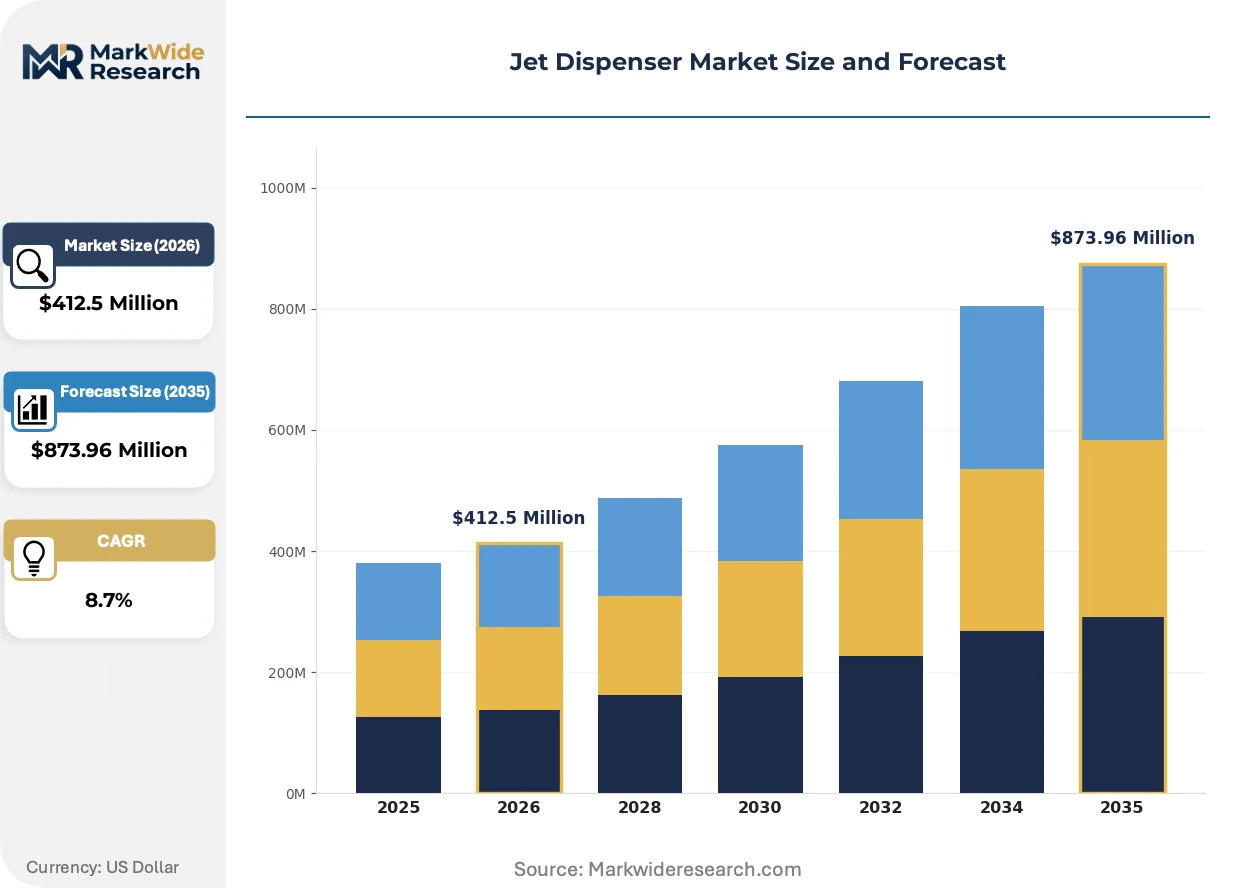
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Jet, Vacuum Jet, Pressure Jet, Hydraulic Jet Technology: Pneumatic, Electronic, Mechanical, Piezoelectric, Electrostatic Application: Pharmaceutical Filling, Food Processing, Inkjet Printing, Cosmetics Dispensing, Electronics Manufacturing End User: Contract Manufacturers, Food & Beverage Producers, Printing Firms, Personal Care Companies |
| Companies Covered | Nordson Corporation, Graco Inc., Musashi Engineering Inc., Illinois Tool Works, Fisnar Inc., Techcon Systems, Asymtek, ITW Dynatec, Protec Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jet Dispenser Market Trends and Innovations
Equipment architectures are bifurcating between speed-optimized pneumatic platforms for consumer electronics volume and precision-optimized piezoelectric systems for pharmaceutical and automotive sensor applications, with software-defined process control emerging as the convergence layer.
Piezoelectric jet valves with real-time droplet imaging feedback are expanding into pharmaceutical filling operations where FDA process analytical technology mandates require 100% dose verification. Contract development and manufacturing organizations in Switzerland and Massachusetts are piloting these systems for high-value biologic formulations. The technology is expanding into applications previously reserved for peristaltic and piston pump technologies, compressing equipment supplier margins through increased specification competition.
REACH authorization procedures for diisocyanate-containing adhesive components entered full enforcement in August 2023, compelling European automotive suppliers to reformulate polyurethane bonding chemistries. Jet dispenser OEMs are responding with heated valve architectures designed for higher-viscosity moisture-cure and UV-acrylic alternatives. German tier-one suppliers face the steepest compliance curves, with BMW and Volkswagen assembly lines in Bavaria and Lower Saxony driving specification urgency.
Electronics contract manufacturers are consolidating procurement authority at headquarters level, displacing regional plant-level equipment specification. Foxconn and Luxshare Precision now mandate approved vendor list compliance for all jet dispensing purchases across Shenzhen, Zhengzhou, and Vietnamese facilities. This concentration is compressing supplier margins through volume-commitment negotiations while elevating technical service and spare parts logistics to primary selection criteria in coastal Chinese manufacturing zones.
Jet Dispenser Market Segmentation
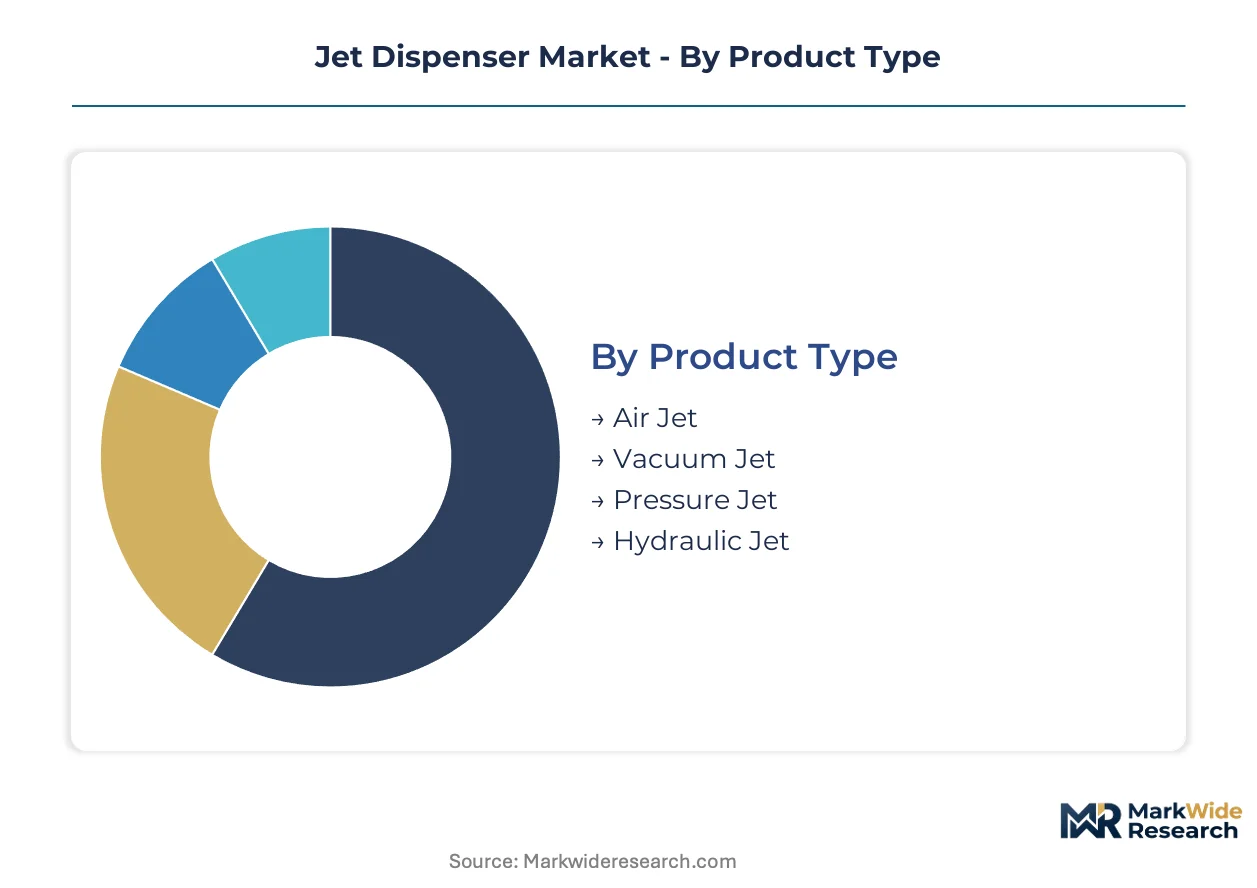
Jet dispenser procurement patterns diverge sharply across deposition physics, automation integration depth, and regulatory exposure. Buyers prioritize throughput frequency in electronics packaging while pharmaceutical operators emphasize dosing precision and validation traceability.
Product Type:
Deposition mechanism determines viscosity range compatibility and maintenance intervals for buyers across semiconductor and industrial adhesive applications.
- Air Jet:Compressed air pulses eject fluid through a nozzle at frequencies exceeding 1,000 Hz, dominating high-speed electronics manufacturing in Taiwan and South Korea where chiplet bonding point density multiplies throughput requirements. Foxconn and Luxshare Precision specify air jet architectures for Shenzhen and Zhengzhou consumer electronics lines.
- Vacuum Jet:Negative pressure aspiration enables gentle handling of shear-sensitive biologics, capturing specification in Massachusetts and North Carolina biotech clusters where FDA 21 CFR Part 11 validation mandates 100% dose verification. CDMOs pilot these systems for high-value therapeutic formulations.
- Pressure Jet:Positive displacement through precision orifices serves mid-viscosity industrial coatings with simpler maintenance protocols.
- Hydraulic Jet:Fluid-driven actuation handles extreme viscosity ranges above 500,000 cP in automotive structural adhesive applications.
Volume sits with Air Jet; growth tilts toward Vacuum Jet.
Technology:
Actuation method separates speed-optimized volume producers from precision-dependent regulated industries.
- Pneumatic:Compressed air-driven valves achieve the highest deposition frequencies, anchoring consumer electronics contract manufacturing where throughput outweighs absolute precision. Malaysian and Mexican brownfield assembly lines favor pneumatic platforms for legacy MES integration compatibility.
- Piezoelectric:Ceramic actuator deformation delivers sub-nanoliter precision within one percent dosing accuracy, commanding premium positioning in pharmaceutical filling where Swissmedic and FDA process analytical technology mandates require real-time droplet imaging feedback. Musashi Engineering specializes in this architecture.
- Electronic:Servo-controlled displacement offers programmable flexibility for multi-material contract manufacturers.
- Mechanical:Cam and spring mechanisms persist in cost-sensitive food processing equipment with lower precision requirements.
- Electrostatic:Charged particle deposition enables conformal coating of complex geometries in automotive sensor packaging.
Revenue concentrates in Piezoelectric; Pneumatic commands unit volume leadership.
Application:
Regulatory intensity and material value per dose create divergent specification priorities across deposition end-uses.
- Electronics Manufacturing:Semiconductor backend assembly demands sub-50 micron tolerances for flip-chip and 3D stacking architectures, driving multi-jet valve configurations in Nevada and Hungary battery cell bonding trials. Thermal interface material deposition for cylindrical lithium-ion formats expands addressable scope beyond traditional die attach.
- Pharmaceutical Filling:Aseptic single-use protocols displace peristaltic pumps, with ISO 13485 and EU MDR traceability requirements extending qualification timelines to 18-24 months. Swiss and Massachusetts CDMOs pilot piezoelectric systems with disposable fluid paths.
- Inkjet Printing:Graphic arts and industrial marking applications prioritize speed over precision in high-volume printing firm operations.
- Cosmetics Dispensing:Personal care companies specify gentle handling for emulsion and serum formulations with visual quality requirements.
- Food Processing:FSSAI and USDA sanitation protocols drive stainless steel construction and clean-in-place compatibility for sauce and topping deposition.
Electronics Manufacturing generates the deepest value pools; Pharmaceutical Filling climbs the fastest.
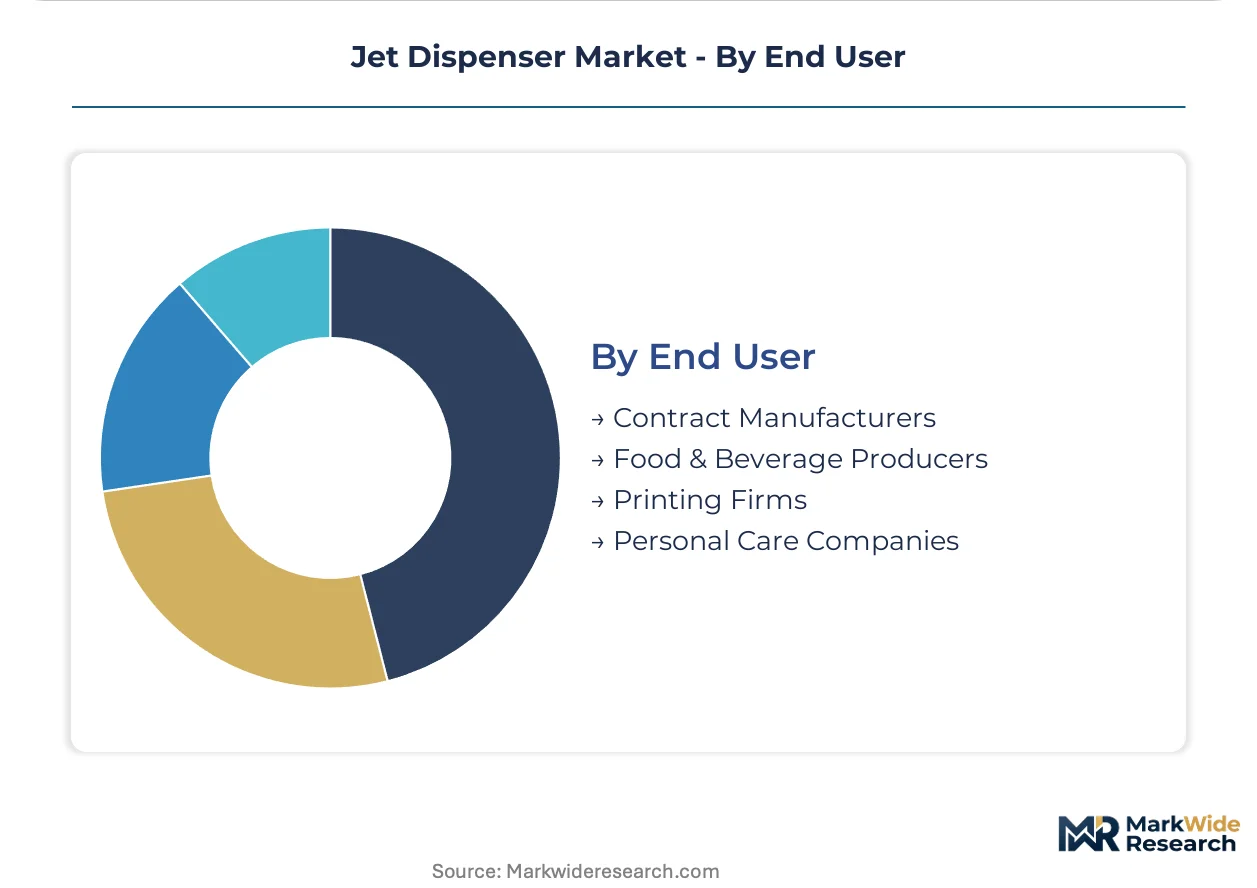
End User:
Procurement centralization and technical service requirements reshape supplier relationships across buyer categories.
- Contract Manufacturers:Electronics assembly specialists consolidate procurement authority at headquarters level, mandating approved vendor list compliance across Shenzhen, Zhengzhou, and Vietnamese facilities. Volume-commitment negotiations compress supplier margins while elevating spare parts logistics to primary selection criteria.
- Personal Care Companies:Cosmetics dispensing demands gentle handling and visual consistency, with European REACH authorization for diisocyanate hardeners forcing formulation shifts toward UV-curable alternatives compatible with non-contact deposition.
- Food & Beverage Producers:Sanitation-grade construction and clean-in-place protocols dominate specification for sauce and topping applications.
- Printing Firms:Graphic arts operations prioritize throughput and ink compatibility over precision in high-volume marking applications.
Contract Manufacturers anchor procurement volume; Personal Care Companies gain specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lead zirconate titanate deposits concentrate in Chinese and Japanese specialty ceramic belts, anchoring piezoelectric actuator supply chains for precision deposition equipment worldwide.
United States
Semiconductor packaging miniaturization and battery cell bonding trials drive equipment specification in Nevada and Arizona fabrication corridors. EPA VOC emission frameworks tighten thresholds for industrial adhesive applications, accelerating closed-loop jet system adoption. Massachusetts and North Carolina biotech clusters pilot disposable fluid-path dispensers for aseptic biopharma filling under FDA 21 CFR Part 11 protocols.
China
Contract manufacturers scale automated assembly lines for consumer electronics and automotive sensors across Shenzhen and Zhengzhou manufacturing zones. Dual-use export licensing requirements on piezoelectric ceramics expose equipment OEMs to supply chain delays. Foxconn and Luxshare Precision consolidate procurement authority at headquarters level, mandating approved vendor list compliance across coastal Chinese facilities and Vietnamese satellite plants.
Germany
Automotive suppliers reformulate polyurethane bonding chemistries to satisfy REACH authorization requirements for diisocyanate-containing hardeners. BMW and Volkswagen assembly lines in Bavaria and Lower Saxony drive specification urgency for heated valve architectures compatible with UV-curable alternatives. German tier-one suppliers face compressed compliance timelines as EU Green Deal chemistry mandates reshape material selection.
South Korea
High-performance computing chiplet architectures multiply bonding points per die, driving throughput requirements beyond 1,500 Hz deposition frequencies in domestic fabrication facilities. National industrial policy supports advanced packaging R&D clusters around Seoul and Pyeongtaek. Samsung and SK Hynix backend assembly operations anchor demand for multi-jet valve configurations serving 3D stacking architectures.
India
PLI scheme incentives for semiconductor and mobile phone assembly attract contract manufacturers to Gujarat and Tamil Nadu, creating greenfield automation specification windows. Central government production-linked incentive structures prioritize domestic electronics manufacturing scale-up. Ahmedabad and Chennai industrial corridors emerge as primary locations for jet dispensing integrator trials through 2024-2025.
Jet Dispenser Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical precision and battery cell bonding specializations. The vendor base stratifies around three maturity levels: heritage fluid handling conglomerates with polymer melt delivery expertise, East Asian precision equipment specialists with piezoelectric actuator depth, and regional automation integrators serving contract manufacturer procurement consolidation. Dominant competitive moves include geographic expansion into India electronics manufacturing zones and portfolio diversification toward thermal interface material deposition for cylindrical lithium-ion formats.
Within the heritage conglomerate tier, Nordson Corporation and Graco Inc. anchor industrial fluid handling scale across automotive adhesive lines and high-throughput electronics manufacturing. Musashi Engineering Inc. exemplifies the East Asian precision specialist archetype, occupying a position defined by piezoelectric actuator specialization. These three entities represent contrasting strategic foundations: polymer melt delivery heritage, industrial dispensing scale, and sub-nanoliter deposition precision respectively.
| Leading Market Players |
|---|
| Nordson Corporation |
| Graco Inc. |
| Musashi Engineering Inc. |
| Illinois Tool Works |
| Fisnar Inc. |
| Techcon Systems |
| Asymtek |
| ITW Dynatec |
| Protec Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Lead zirconate titanate ceramic feedstock pricing volatility cascades through piezoelectric actuator manufacturing into three distinct equipment tiers, with premium piezoelectric systems commanding substantial markups over pneumatic alternatives while contract manufacturer procurement consolidation compresses margins across all categories.
Pricing Analysis
Warranty and service bundling separates premium piezoelectric offerings from unbundled pneumatic platforms, with Swiss and Massachusetts pharmaceutical CDMOs paying for validation support and spare parts logistics while Asian electronics contract manufacturers prioritize capital expenditure minimization. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 13485 medical device compliance adding substantial cost premiums. Pricing pressure stems from Foxconn and Luxshare Precision headquarters-level procurement mandates compressing supplier margins through volume-commitment negotiations. Contract manufacturers exhibit highest price sensitivity due to thin assembly margins, while pharmaceutical operators prioritize dosing precision over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Japanese specialty ceramic producers dominating lead zirconate titanate supply for piezoelectric actuators. Equipment OEMs draw from Taiwan and South Korea for precision machining components, with Malaysia and Mexico hosting final assembly for brownfield electronics integration. Dual-use export licensing delays on piezoelectric ceramics present persistent supply chain risk, compounded by RoHS substance scrutiny on lead-containing formulations. Distribution runs through approved vendor list relationships with headquarters procurement teams at major contract manufacturers, displacing regional plant-level equipment specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FDA 21 CFR Part 11 and EU MDR traceability requirements construct substantial barrier-to-entry moats favoring incumbents with established validation protocols and quality management infrastructure.
For Market Incumbents: Lock in piezoelectric ceramic supply through long-term offtake agreements with Japanese specialty producers, insulating against dual-use export licensing delays while competitors face procurement bottlenecks. Expand technical service capacity in Tamil Nadu and Gujarat to capture PLI scheme-driven greenfield specification windows before emerging entrants establish local presence. Certification investment in ISO 13485 medical device quality management represents the critical defensive lever against precision specialists encroaching from pharmaceutical filling segments.
For New Entrants and Emerging Players: The price-point gap between premium Swissmedic-validated piezoelectric systems and economy pneumatic platforms offers entry space for mid-tier precision offerings targeting Indian electronics manufacturing and battery cell bonding trials. Battery thermal interface material deposition in cylindrical lithium-ion formats presents the most penetrable application expansion, with Nevada and Hungary plants actively evaluating equipment alternatives. A service-heavy go-to-market approach emphasizing spare parts logistics and rapid response technical support differentiates against heritage conglomerates with slower aftermarket infrastructure.
For Investors and Strategic Acquirers: The window for entry favors East Asian precision equipment specialists with captive piezoelectric actuator technology and established pharmaceutical validation track records. Long-term viability hinges on regulatory compliance depth rather than throughput specifications alone, positioning Swiss and Massachusetts CDMO-integrated players for durable competitive positioning. Watch FDA process analytical technology mandate enforcement intensity as the critical inflection signal for pharmaceutical filling equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Ceramics | Captive lead zirconate titanate supply insulates Nordson and Musashi against Japanese export licensing delays. |
| Heated Valve Architecture Development | REACH-compliant UV-curable adhesive compatibility secures German automotive tier-one supplier specifications. |
| Disposable Fluid-Path Platform Launch | FDA 21 CFR Part 11 validation protocols position systems for Massachusetts biotech cluster adoption. |
| Geographic Expansion into Tamil Nadu | PLI scheme incentives attract contract manufacturers requiring localized technical service presence. |
| Real-Time Droplet Imaging Integration | Swissmedic process analytical technology mandates drive specification for 100% dose verification capability. |
Research Methodology
Independent corroboration across equipment OEM technical directors, pharmaceutical CDMO manufacturing executives, and contract manufacturer procurement leads underwrites the qualitative findings, with secondary validation drawing from SEC filings of heritage fluid handling conglomerates, FDA 510(k) premarket notification databases, and ECHA REACH authorization registers. Bottom-up triangulation across pneumatic and piezoelectric valve shipment patterns combines with top-down market sizing to anchor volume and value estimates.
Comparable-period anchoring to historical semiconductor packaging equipment cycles and pharmaceutical filling automation adoption curves shapes the projection framework across the analysis window. Segmentation modeling spans deposition mechanism, actuation technology, application intensity, and regulatory exposure tiers, with CAGRs derived from equipment replacement cycle timing and greenfield capacity expansion announcements. Battery cell bonding trial outcomes and EU Green Deal chemistry mandate enforcement timelines feed into application expansion forecasts.
Underlying measurement precision varies by segment; pharmaceutical filling qualification timelines and regulatory validation protocols carry tighter precision than emerging battery thermal interface material deposition estimates. Forecasts reflect assumptions around PLI scheme incentive continuity, dual-use export licensing processing speeds, and REACH authorization enforcement intensity. Deviation in FDA process analytical technology mandate rollout timing would shift the pharmaceutical filling outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Actuators Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
Pin Insertion Machine Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
ROV Tether Management System Market