
 Quartz Glass Market | 2026-2036
Quartz Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Glass Market Analytics
A capital-intensity divergence between integrated refiners and specialty fabricators is reorganizing competitive tiers in quartz glass supply. Heraeus Holding leverages captive synthetic silica production to sustain margin control across high-purity grades. Momentive Performance Materials anchors North American semiconductor supply chains through Ohio-based refining assets. Shin-Etsu Chemical dominates Asian quartz crucible output for silicon wafer pulling.
Quartz glass consists of silicon dioxide (SiO₂) formed into amorphous, high-purity structures with thermal stability exceeding 1,000°C and optical transmission from ultraviolet through infrared wavelengths; manufacturers produce it via electric fusion of natural crystal or flame hydrolysis of silicon tetrachloride for semiconductor-grade applications. Fused quartz commands the largest value pool due to its irreplaceable role in diffusion furnace tubes and wafer carriers, while quartz tubes capture the fastest expansion trajectory driven by photovoltaic ingot growth. Optical Devices applications concentrate premium pricing power where bubble-free, striation-minimal grades command specification premiums from lithography equipment builders.
REACH compliance in Europe, EPA emissions frameworks in the United States, and China's GB standards under SAMR collectively elevate purity thresholds and environmental compliance costs for producers seeking multi-regional market access. FDA oversight of laboratory equipment and NMPA medical-device registration in China further segment qualification requirements by end-use jurisdiction. Stakeholders must track how semiconductor fab localization policies across East Asia, North America, and Europe redirect demand geography faster than supply capacity can relocate.
Market Dynamics
Semiconductor fab localization policies across East Asia, North America, and Europe are redirecting demand geography faster than supply capacity can relocate, forcing quartz glass producers to qualify new regional supply chains under divergent purity regimes.
Growth Catalysts
- EU REACH substance restrictions:Tightening purity requirements on hazardous substances are locking out lower-grade suppliers and consolidating procurement among certified refiners serving lithography equipment builders.
- Photovoltaic ingot manufacturing:Expansion of monocrystalline silicon pulling operations is accelerating consumption of large-diameter quartz crucibles and thermal insulation components.
- Ohio-based refining clusters:North American semiconductor supply chain reshoring is creating captive demand for domestically produced high-purity fused quartz.
Market Restraints
- Silicon tetrachloride feedstock volatility:Synthetic silica production depends on chlorosilane supply chains concentrated among integrated chemical conglomerates, exposing fabricators to input cost swings.
- East Asian supply concentration:Crucible and diffusion tube manufacturing clusters in China, Japan, and South Korea create geographic vulnerability for buyers seeking supply diversification.
- Natural crystal depletion:Electric fusion grades relying on mined quartz deposits face long-term resource constraints as Brazilian and Madagascan extraction yields decline.
Strategic Opportunities
- India semiconductor mission:The country's PLI scheme for fab construction is opening qualification windows for crucible and wafer carrier suppliers before incumbent Asian producers establish local production.
- Medical device optics:FDA and NMPA registration pathways for surgical laser systems are creating premium demand for bubble-free synthetic silica in fluorescence microscopy and endoscopy.
- Dual carbon compliance:China's MEE emissions frameworks and SAMR efficiency mandates are favoring electric fusion over flame hydrolysis for domestic producers, reshaping technology selection criteria.
Industry Challenges
- High-purity metrology talent scarcity:Bubble detection, striation analysis, and trace metal characterization require specialized technicians that refiners struggle to recruit outside established semiconductor manufacturing clusters.
- Multi-jurisdiction certification timelines:Simultaneous qualification under FDA laboratory equipment rules, REACH substance dossiers, and GB standards extends product launch cycles by 18-24 months.
- Legacy furnace tube replacement cycles:Diffusion equipment in mature fabs operates on 7-10 year replacement intervals, compressing near-term revenue visibility for tube suppliers despite capacity expansion elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Glass Market |
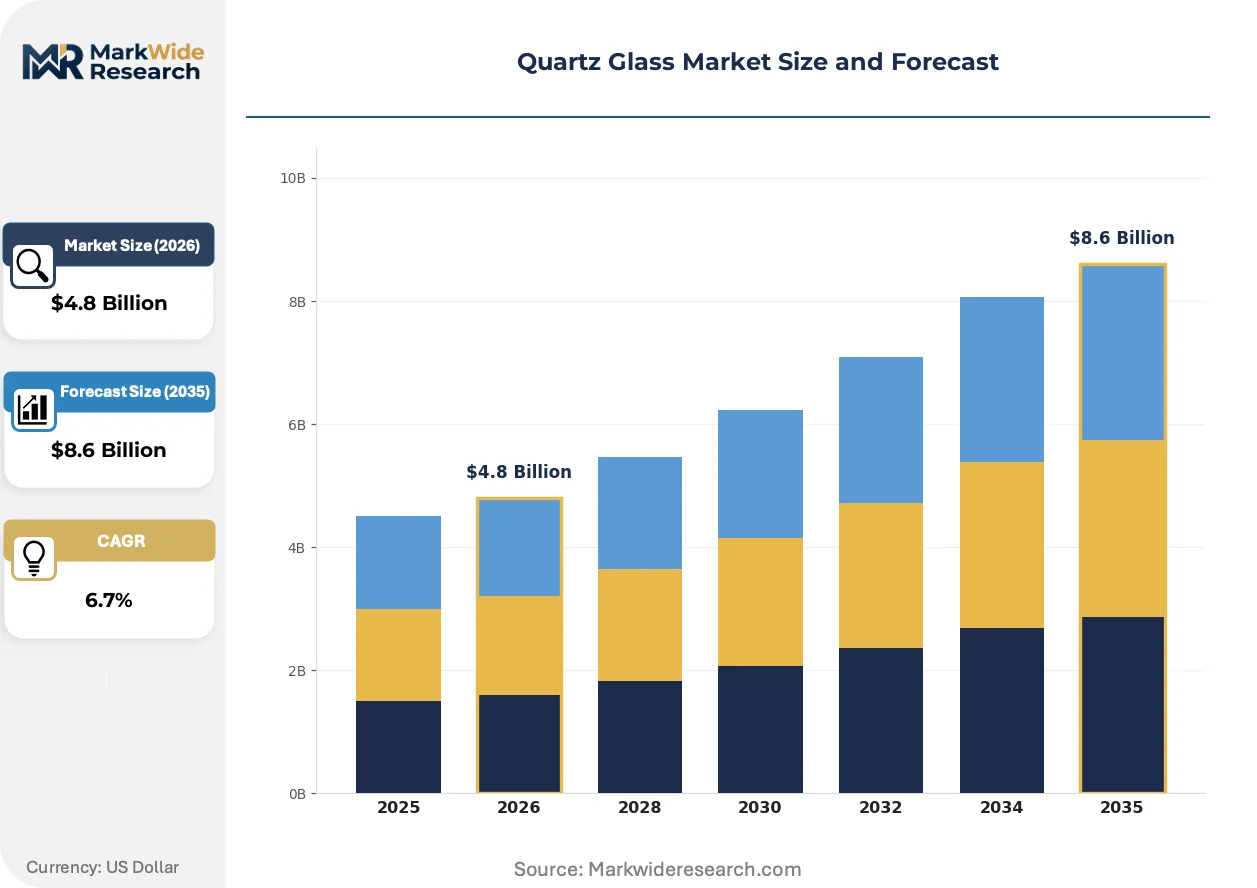
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Quartz, Quartz Rods, Quartz Tubes, Quartz Sheets End Use Industry: Semiconductor, Solar Energy, Telecommunications, Chemical Processing Form: Bulk, Gels, Powders, Discs Application: Optical Devices, Laboratory Equipment, Thermal Insulation, Lighting |
| Companies Covered | Heraeus Holding, Momentive Performance Materials Inc., Shin-Etsu Chemical Co., Ltd., Tosoh Quartz Co., Ltd., Corning Inc., Schott AG, MARUWA, QSIL, Raesch Quarz GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Glass Market Evolving Landscape
Synthetic silica production methods are diverging by end-use purity requirements, while regulatory frameworks fragment compliance pathways and procurement behaviors shift toward regional qualification bundles.
Plasma-enhanced chemical vapor deposition is fragmenting the optical-grade quartz supply base by enabling localized production of lithography-grade material without flame hydrolysis infrastructure. ASML and Nikon lithography equipment builders are qualifying these alternative synthesis routes to reduce dependence on German and Japanese synthetic silica imports. The technology is compressing the historical premium commanded by established flame hydrolysis specialists.
China's GB standards under SAMR are mandating stricter trace metal limits for semiconductor-grade quartz used in domestic 300mm wafer production. Domestic refiners are retrofitting electric fusion furnaces with advanced atmosphere control to meet these specifications, while foreign suppliers face extended conformity assessment timelines. The policy is accelerating technology transfer partnerships between European equipment builders and Chinese material producers.
Buyer consortiums at major memory and logic fabs are consolidating quartz crucible procurement into multi-year specification contracts with volume commitments and embedded price adjustment mechanisms. This behavior is displacing spot-market purchasing and forcing mid-size fabricators to accept margin compression or exit the segment. The shift is most visible in South Korea and Taiwan where Samsung and TSMC procurement organizations dominate supplier selection.
Quartz Glass Market Segmentation
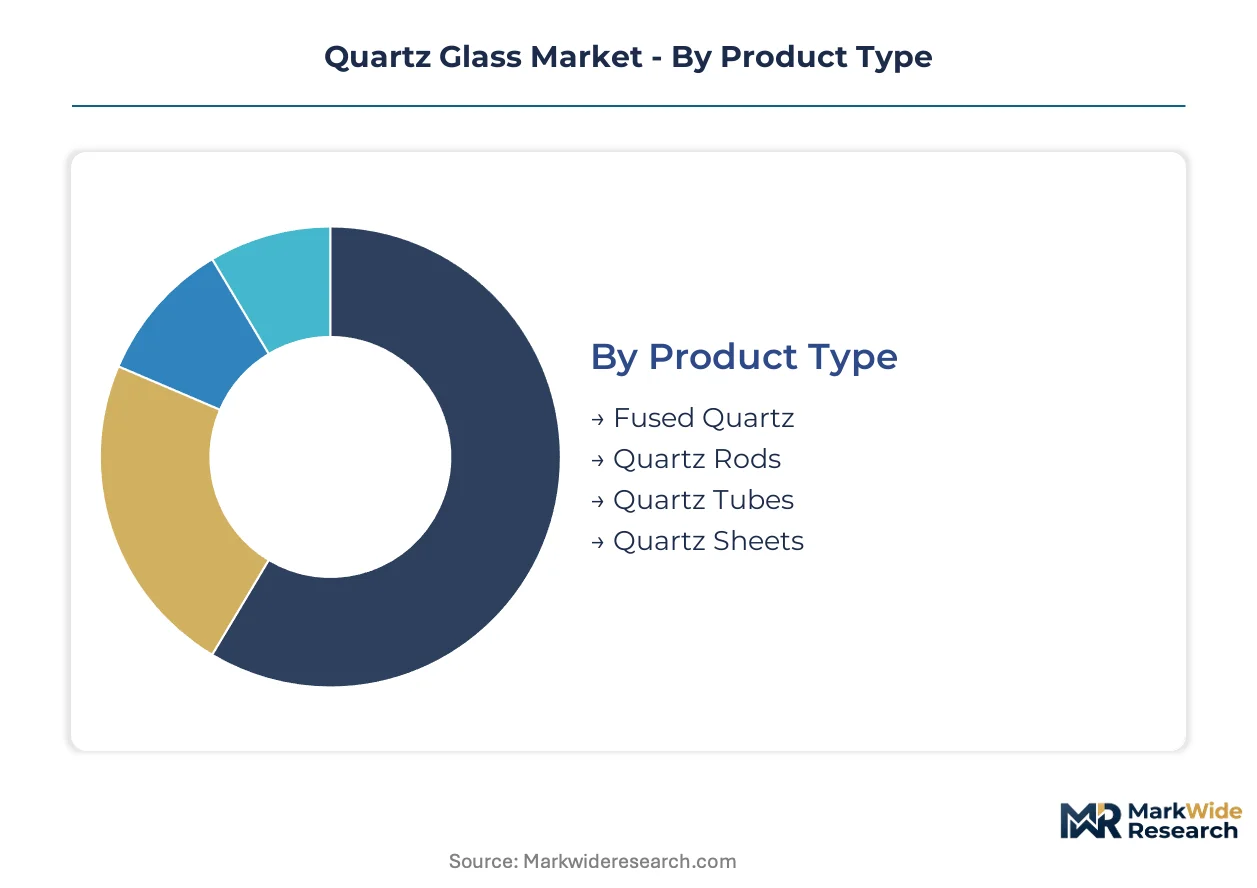
Quartz glass segmentation reflects divergent purity regimes and fabrication methods across semiconductor, solar, and optical end-uses. Each category maps distinct procurement behaviors—crucible buyers prioritize thermal shock resistance, while lithography equipment builders demand striation-free optical grades.
Product Type:
Domestic production clusters in Ohio and Hesse serve North American and European semiconductor fabs, while East Asian supply chains export crucible-grade fused quartz globally.
- Fused Quartz:Electric fusion of natural crystal or flame hydrolysis of silicon tetrachloride yields amorphous SiO₂ with thermal stability exceeding 1,000°C. Diffusion furnace tubes and wafer carriers in South Korean and Taiwanese fabs consume the highest volumes, constrained by Brazilian and Madagascan crystal depletion.
- Quartz Tubes:Large-diameter tubing for photovoltaic ingot pulling commands specification premiums from monocrystalline silicon manufacturers. China's expanding polysilicon capacity is accelerating procurement of thermal insulation-grade tubes.
- Quartz Rods:Solid cylindrical forms serve optical fiber preform feedstocks and precision laboratory stirrers.
- Quartz Sheets:Flat substrates support semiconductor mask blanks and UV-transmissive inspection windows.
Fused Quartz holds the largest share; momentum sits with Quartz Tubes.
End Use Industry:
Customer procurement power concentrates at memory and logic fabs consolidating multi-year specification contracts with embedded price adjustment mechanisms.
- Semiconductor:Lithography equipment builders at ASML and Nikon qualify bubble-free synthetic silica for projection optics and wafer stage components. EU REACH substance restrictions lock out lower-grade suppliers, consolidating procurement among certified German and Japanese refiners.
- Solar Energy:Monocrystalline silicon pulling operations in China's Xinjiang and Inner Mongolia regions drive crucible consumption. Large-diameter quartz crucibles face 7-10 year replacement cycles in mature ingot furnaces.
- Telecommunications:Optical fiber manufacturing consumes high-purity tubes for preform collapse and drawing operations.
- Chemical Processing:Corrosion-resistant vessels and sight glasses serve chlor-alkali and specialty chemical production.
Semiconductor dominates value capture; Solar Energy climbs the fastest.
Form:
Volume economics favor bulk shipments to integrated refiners, while powders and discs command premium pricing in medical device and research applications.
- Bulk:Unformed raw material feeds electric fusion furnaces at Heraeus and Momentive facilities. Ohio-based refining clusters source bulk synthetic silica for captive semiconductor supply chain integration.
- Discs:Precision-machined substrates serve fluorescence microscopy and surgical laser systems requiring FDA and NMPA registration.
- Powders:Fused silica powders fill thermal insulation packages and investment casting molds.
- Gels:Colloidal suspensions enable sol-gel processing of near-net-shape optical components.
Bulk holds the largest share; Discs gain share fastest.
Application:
Specification premiums stratify sharply between laboratory equipment qualification tiers and commodity lighting applications.
- Optical Devices:Bubble-free, striation-minimal grades command the steepest specification premiums from lithography equipment builders. Plasma-enhanced chemical vapor deposition is fragmenting supply by enabling localized production without flame hydrolysis infrastructure.
- Laboratory Equipment:FDA oversight of analytical instruments and China's GB standards under SAMR segment qualification requirements by end-use jurisdiction, extending product launch cycles.
- Thermal Insulation:Felt and board forms surround polysilicon reduction reactors and crystal pullers.
- Lighting:UV and halogen lamp envelopes utilize lower-purity electric fusion grades with relaxed bubble specifications.
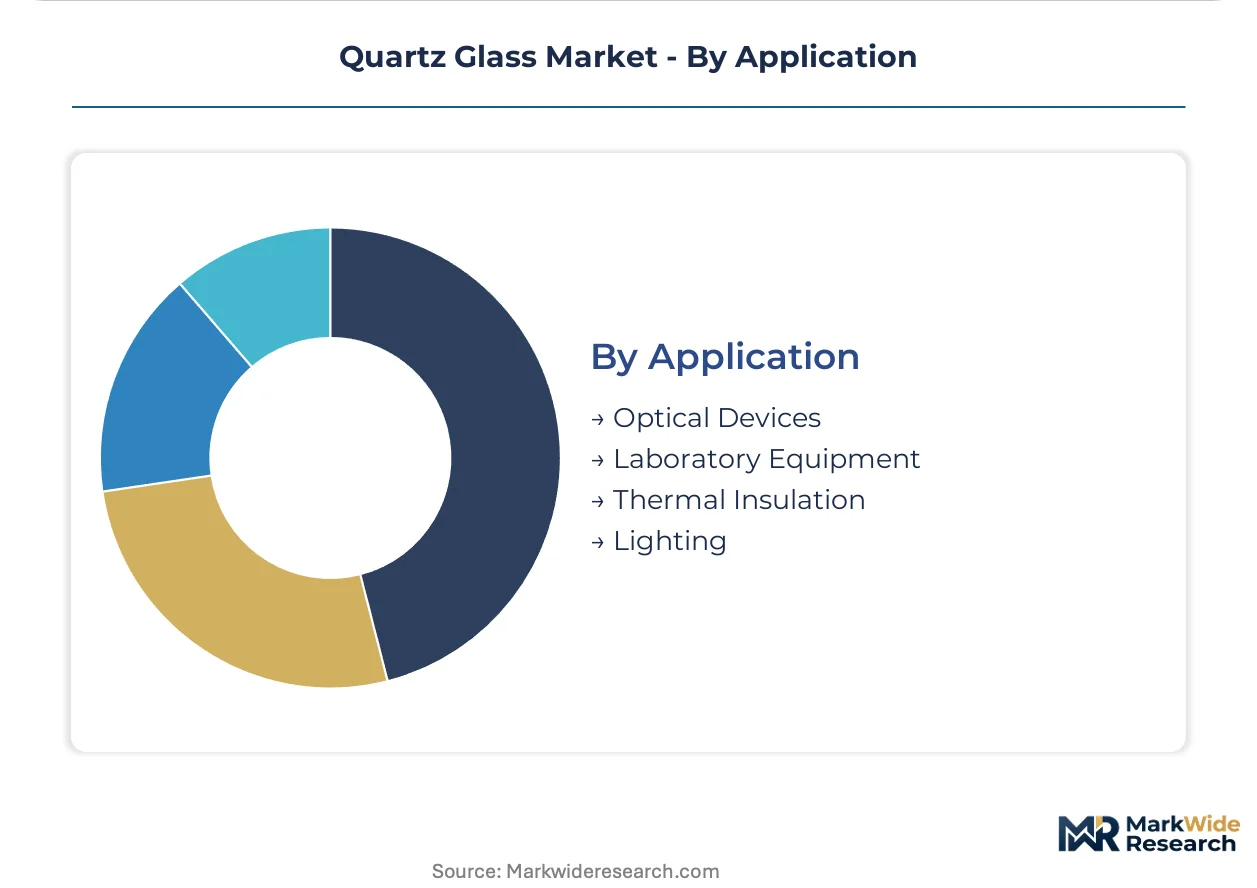
Optical Devices holds the largest share; Laboratory Equipment expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Japanese refiners serving lithography equipment builders, while Chinese fabricators compete on volume for photovoltaic crucibles. This asymmetry shapes procurement patterns across semiconductor and solar supply chains.
United States
Ohio-based refining clusters supply North American semiconductor fabs reshoring production under the CHIPS and Science Act. EPA emissions frameworks govern flame hydrolysis operations, elevating compliance costs for synthetic silica producers. Momentive Performance Materials anchors domestic high-purity fused quartz capacity near Columbus.
Germany
Hesse-based electric fusion facilities serve EU lithography equipment builders with REACH-certified synthetic silica. ECHA substance restrictions under REACH Article 33 tighten trace metal limits, locking out non-compliant imports. Heraeus Holding leverages captive production in Hanau to sustain margin control across premium grades.
China
Xinjiang and Inner Mongolia polysilicon expansion drives crucible consumption for monocrystalline silicon pulling. SAMR GB standards mandate stricter purity thresholds for 300mm wafer production, forcing furnace retrofits. Domestic refiners in Jiangsu and Zhejiang are qualifying under dual carbon compliance frameworks from MEE.
Japan
Kyushu and Nagoya manufacturing clusters produce synthetic silica for semiconductor diffusion tubes and wafer carriers. METI industrial policy supports domestic material security for advanced logic and memory fabs. Shin-Etsu Chemical dominates quartz crucible output from its Gunma and Niigata facilities.
South Korea
Memory and logic fabs in Gyeonggi Province consolidate multi-year quartz procurement contracts with volume commitments. MFDS medical-device registration creates parallel demand for optical-grade discs in surgical laser systems. Domestic fabricators in Cheonan and Icheon supply thermal insulation components for ingot growth furnaces.
Quartz Glass Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where synthetic silica specialists command specification premiums and electric fusion generalists compete on scale. The vendor base concentrates among integrated chemical conglomerates with captive chlorosilane supply and independent fabricators sourcing feedstock spot. Three archetypes dominate: German-Japanese refiners with flame hydrolysis mastery, Chinese volume producers with electric fusion scale, and mid-size specialists serving medical optics niches. Competitive moves center on backward integration into silicon tetrachloride production and regional qualification partnerships with equipment builders.
Among German-based fabricators, Heraeus Holding and Schott AG exemplify the premium-tier archetype with established REACH certification and lithography equipment relationships. Japanese specialists Shin-Etsu Chemical and Tosoh Quartz occupy positions within the crucible and diffusion tube segments, leveraging proximity to Asian semiconductor clusters. Momentive Performance Materials represents the North American reshoring vector, anchoring domestic supply chain qualification efforts. These named entities serve as reference points for understanding how geographic origin and company structure map to competitive positioning without asserting specific strategic actions or market shares.
| Leading Market Players |
|---|
| Heraeus Holding |
| Momentive Performance Materials Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Tosoh Quartz Co., Ltd. |
| Corning Inc. |
| Schott AG |
| MARUWA |
| QSIL |
| Raesch Quarz GmbH |
| Others |
Value Network & Pricing Analysis
Ninety-day qualification timelines for semiconductor-grade quartz crucibles concentrate procurement leverage with buyers who operate multi-year specification contracts, amplifying price pressure on fabricators lacking captive synthetic silica production. This lead-time compression rewards Heraeus and Momentive with integrated refining assets while forcing spot-market suppliers into margin sacrifice.
Pricing Analysis
The customization-premium spread between configured-to-order lithography-grade synthetic silica and standard electric fusion grades exceeds three-to-one, with flame hydrolysis specialists capturing specification premiums from ASML and Nikon while volume producers compete on scale for photovoltaic crucibles. Price differentiation rests on REACH certification tier and bubble-free optical grade, with semiconductor equipment builders least sensitive to cost and solar ingot manufacturers most responsive to volume discounts. Pricing pressure intensifies in crucible segments as Chinese electric fusion capacity expands, compressing margins for non-integrated fabricators dependent on spot silicon tetrachloride feedstock.
Supply Chain Analysis
Strategic stockpile preferences dominate semiconductor procurement, with memory and logic fabs maintaining six-month quartz crucible inventories against supply disruption while solar manufacturers run lean just-in-time programs. Supply concentrates in Germany, Japan, and China, with synthetic silica production drawing from chlorosilane feedstocks anchored in integrated chemical conglomerates. Single-source vulnerability runs through Brazilian and Madagascan natural crystal deposits for electric fusion grades. Distribution runs through direct mill relationships with equipment builders and fab procurement organizations, bypassing traditional distributor channels for high-purity specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quartz glass demand sits in early-cycle expansion as semiconductor fab localization policies across East Asia, North America, and Europe outpace supply capacity relocation, creating qualification windows before incumbent producers establish regional production.
For Market Incumbents: Consolidate backward integration into silicon tetrachloride production to defend margin position against feedstock volatility, while accelerating furnace retrofit investments to meet China's SAMR GB standards before foreign competitors complete conformity assessment. Threat concentration sits with plasma-enhanced chemical vapor deposition challengers fragmenting optical-grade supply. For New Entrants and Emerging Players: Lead with medical device optics as the most penetrable white-space segment, exploiting FDA and NMPA registration pathways that extend incumbent product launch cycles by 18-24 months. Target surgical laser systems and fluorescence microscopy applications where bubble-free synthetic silica commands premium pricing and buyer consolidation remains incomplete. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming quartz glass divisions lacking semiconductor equipment builder relationships. Long-term viability favors synthetic silica specialists with flame hydrolysis mastery over electric fusion generalists facing natural crystal depletion. Watch India's PLI semiconductor mission as the inflection signal—qualification windows for crucible suppliers will narrow as domestic fab construction advances.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Tetrachloride | Captive chlorosilane supply insulates Heraeus and Momentive from feedstock cost swings. |
| Regional Qualification Partnerships | Equipment builder relationships with ASML and Nikon lock in specification premiums. |
| Furnace Retrofit for SAMR Compliance | Atmosphere control upgrades enable Chinese domestic 300mm wafer production access. |
| Medical Device Optics Registration | FDA and NMPA pathways create defensible premium pricing in surgical laser systems. |
| Multi-Year Specification Contracts | Volume commitments with Samsung and TSMC procurement displace spot-market purchasing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and SAMR regulatory disclosures, combining interviews with semiconductor procurement managers, quartz refinery technical directors, and lithography equipment supply chain leads. Bottom-up capacity modeling triangulates against top-down consumption estimates from fab construction pipelines and polysilicon expansion announcements.
Segmentation dimensions modeled include product type, end-use industry, form factor, and application across the analysis window, with CAGRs derived from regression against semiconductor capital expenditure cycles and photovoltaic installation forecasts. Industry-specific inputs capture diffusion furnace tube replacement intervals and crucible consumption rates per gigawatt of monocrystalline silicon capacity.
Forecasts assume regulatory continuity in EU REACH, EPA emissions frameworks, and China's MEE dual carbon compliance; material policy shifts would require re-modeling. Revision becomes warranted when semiconductor fab localization timelines accelerate or polysilicon capacity expansion stalls.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Beam Expanders Market
Optics
Photostimulation Lasers Market
Optics
Optical Lens for Mobile Phone Market
Optics
Optical Profilometer Market
Optics
Polymeric Optical Fiber Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Camera Module Lens Market
Optics
Smart Vision Systems Market
Optics
Acrylic Lenses Market
Optics
Picosecond Lasers Market
Optics
Laser Transmitter Market
Optics
Fiber Optic Amplifier Market
Optics
Fiber Optical Receivers Market
Optics
Optical Microscope Market
Optics
Stroboscope Market
Optics
Optical Wavelength Service Market