
 Chronic Gingivostomatitis Treatment Market | 2026-2036
Chronic Gingivostomatitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Gingivostomatitis Treatment Market Analysis
The divergence between premium biologic therapies and commodity antiseptic rinses is expanding across the Chronic Gingivostomatitis Treatment landscape. Pfizer Inc. leverages its veterinary division's manufacturing scale to dominate distribution in North American specialty clinics. Johnson & Johnson sustains competitive positioning through its human oral care brand equity that transfers into pet owner trust. GlaxoSmithKline PLC differentiates via R&D intensity directed at novel immunomodulatory formulations for refractory feline cases.
Chronic gingivostomatitis denotes a severe, immune-mediated inflammatory condition affecting the oral mucosa of cats, characterized by persistent ulceration, lymphoplasmacytic infiltration, and resistance to conventional antibiotic therapy; its primary commercial purpose centers on alleviating pain, controlling secondary infection, and modulating aberrant immune responses to improve quality of life and reduce euthanasia rates. Systemic medications occupy the largest revenue pool given cyclosporine and corticosteroid dependence in refractory presentations, while laser therapy represents the fastest-growing segment as veterinary dentists invest in CO2 and diode surgical platforms. Topical agents maintain stable demand through chlorhexidine and buprenorphine formulations used in multimodal protocols across dental offices and homecare settings.
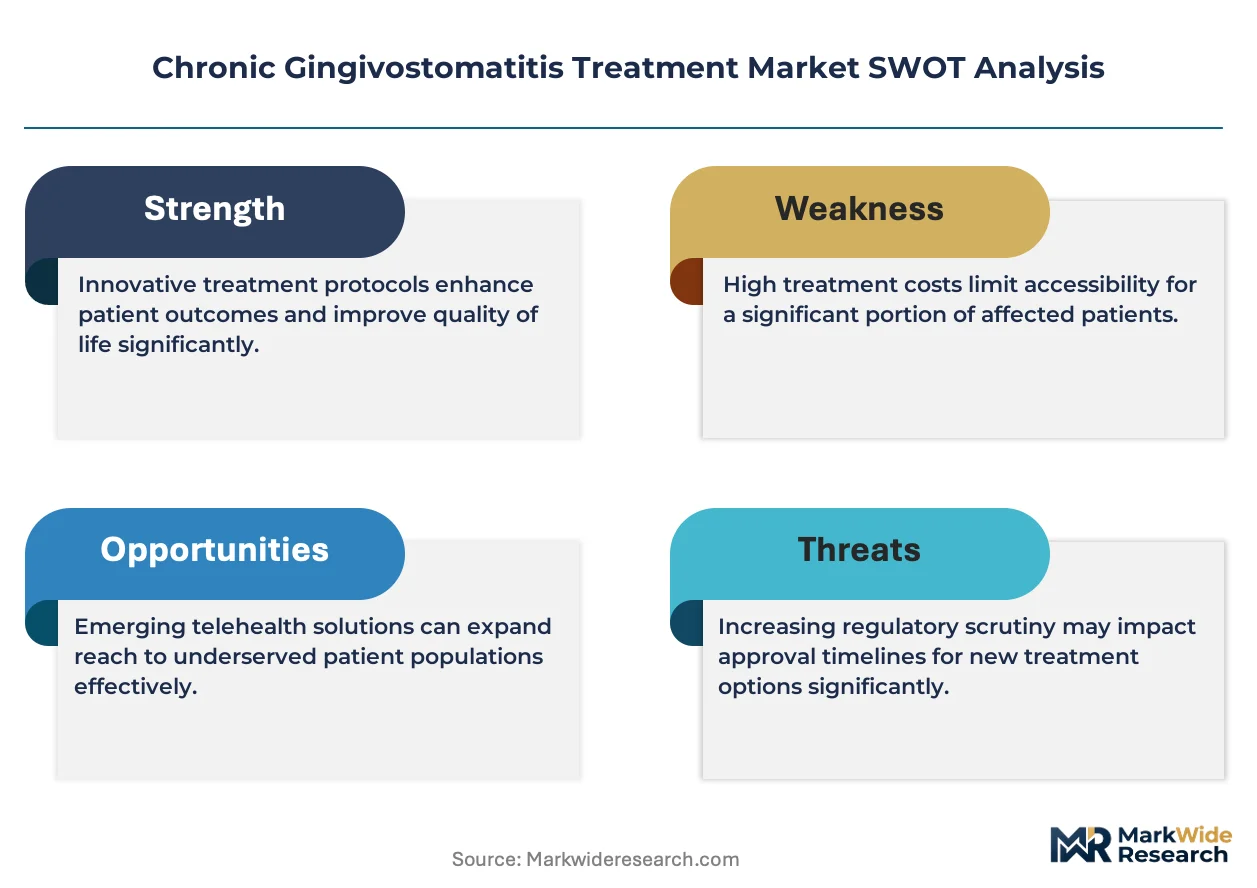
The FDA Center for Veterinary Medicine enforces stringent approval pathways for new animal drugs, shaping product development timelines and limiting market entry to well-capitalized sponsors. The European Medicines Agency's Committee for Medicinal Products for Veterinary Use imposes comparable efficacy and safety benchmarks that filter which formulations achieve cross-border commercialization. Stakeholders must monitor evolving compounding pharmacy regulations and the shift toward evidence-based specialty dentistry credentials as determinants of prescribing authority and reimbursement access.
Market Dynamics
Veterinary dentistry's shift toward laser-based surgical protocols is restructuring treatment hierarchies, compressing reliance on chronic pharmaceutical management while elevating capital equipment investment in specialty feline oral care.
Growth Catalysts
- Specialty Credential Expansion:The American Veterinary Dental College's residency program growth is producing board-certified practitioners capable of performing advanced gingivectomy and caudal mouth extractions that reduce pharmaceutical dependence.
- Pet Insurance Penetration:Rising coverage rates in the United States are removing cost barriers for multimodal therapy combining surgery, immunomodulation, and long-term monitoring.
- Laser Platform Miniaturization:Diode and CO2 surgical units are achieving footprint and cost reductions that enable installation in general practice settings previously limited to academic referral hospitals.
Market Restraints
- Cyclosporine Supply Concentration:Generic immunosuppressant manufacturing for veterinary use concentrates among a limited set of compounding pharmacies subject to API sourcing volatility.
- FDA CVM Approval Timelines:New animal drug applications for feline-specific formulations face multi-year review cycles that deter investment in species-targeted therapeutics.
- Diagnostic Cost Burden:Definitive diagnosis requires histopathology and exclusion of FeLV/FIV, creating upfront cost barriers in price-sensitive owner segments.
Strategic Opportunities
- Telemedicine Integration:Post-operative monitoring and pain assessment protocols are adapting to remote veterinary consultation platforms that extend specialist reach into underserved metropolitan markets.
- Stem Cell Therapy Development:Regenerative medicine applications for immune-mediated oral disease represent an emerging therapeutic class with limited current competition.
- Homecare Formulation Innovation:Transmucosal buprenorphine and palatable chlorhexidine delivery systems are creating compliance advantages in owner-administered maintenance protocols.
Industry Challenges
- Veterinary Dental Specialist Scarcity:The four-year residency requirement and limited program slots constrain workforce expansion needed to meet referral demand.
- Compounding Pharmacy Regulatory Uncertainty:Evolving FDA guidance on bulk substance lists creates compliance risk for clinics dependent on customized cyclosporine formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Gingivostomatitis Treatment Market |
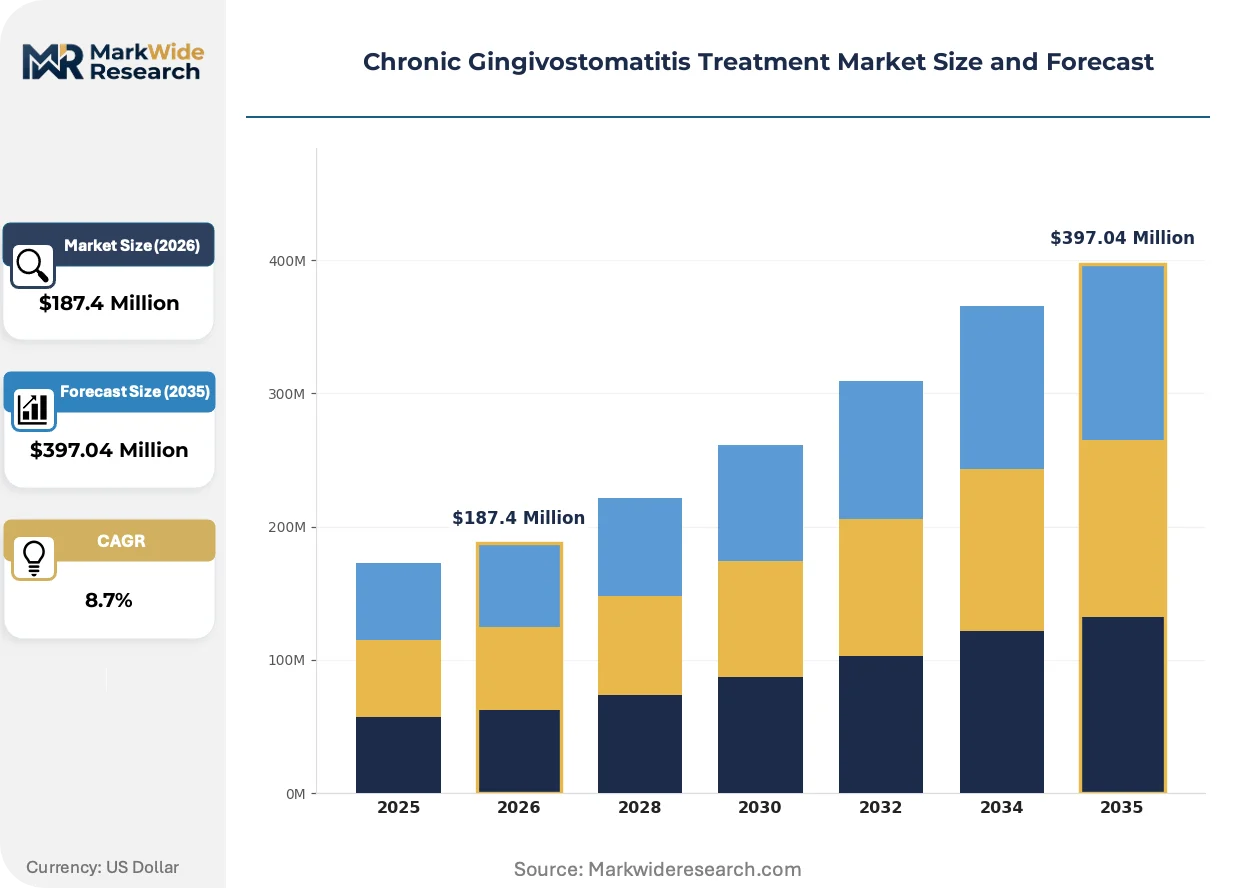
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Topical Agents, Systemic Medications, Laser Therapy, Antimicrobial Mouthwash Administration Route: Oral, Topical, Injections, Inhalation Patient Type: Pediatric, Geriatric, Adult, Immunocompromised Care Setting: Outpatient Clinics, Hospitals, Homecare, Dental Offices |
| Companies Covered | Pfizer Inc., Johnson & Johnson, GlaxoSmithKline PLC, Merck & Co., Inc., Novartis AG, AstraZeneca PLC, Taj Pharmaceuticals Limited, Ciron Pharma, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Gingivostomatitis Treatment Market Emerging Trajectories
Laser technology diffusion is fragmenting treatment protocols across practice types, while regulatory pressure on antimicrobial use and shifting owner expectations are compressing traditional pharmaceutical-centric models.
Photobiomodulation and surgical laser platforms are modularizing access to advanced oral surgery. General practitioners in high-volume metropolitan markets are acquiring diode units for gingivectomy and ulcer ablation. Equipment manufacturers are responding with leasing programs that bypass capital constraints.
The FDA Center for Veterinary Medicine's intensified pharmacovigilance requirements for compounded preparations are elevating manufactured product preference. Clinics are shifting toward FDA-approved transmucosal analgesics and commercially packaged chlorhexidine rinses. Specialty practices with in-house pharmacies are restructuring procurement to emphasize documented chain-of-custody compliance.
Owner expectations for pain-free recovery are compressing follow-up intervals and elevating diagnostic investment. Practices are unbundling post-operative care packages into discrete telehealth and in-person components. Urban markets with high pet insurance penetration are driving adoption of multimodal analgesia protocols previously confined to academic settings.
Chronic Gingivostomatitis Treatment Market Segmentation
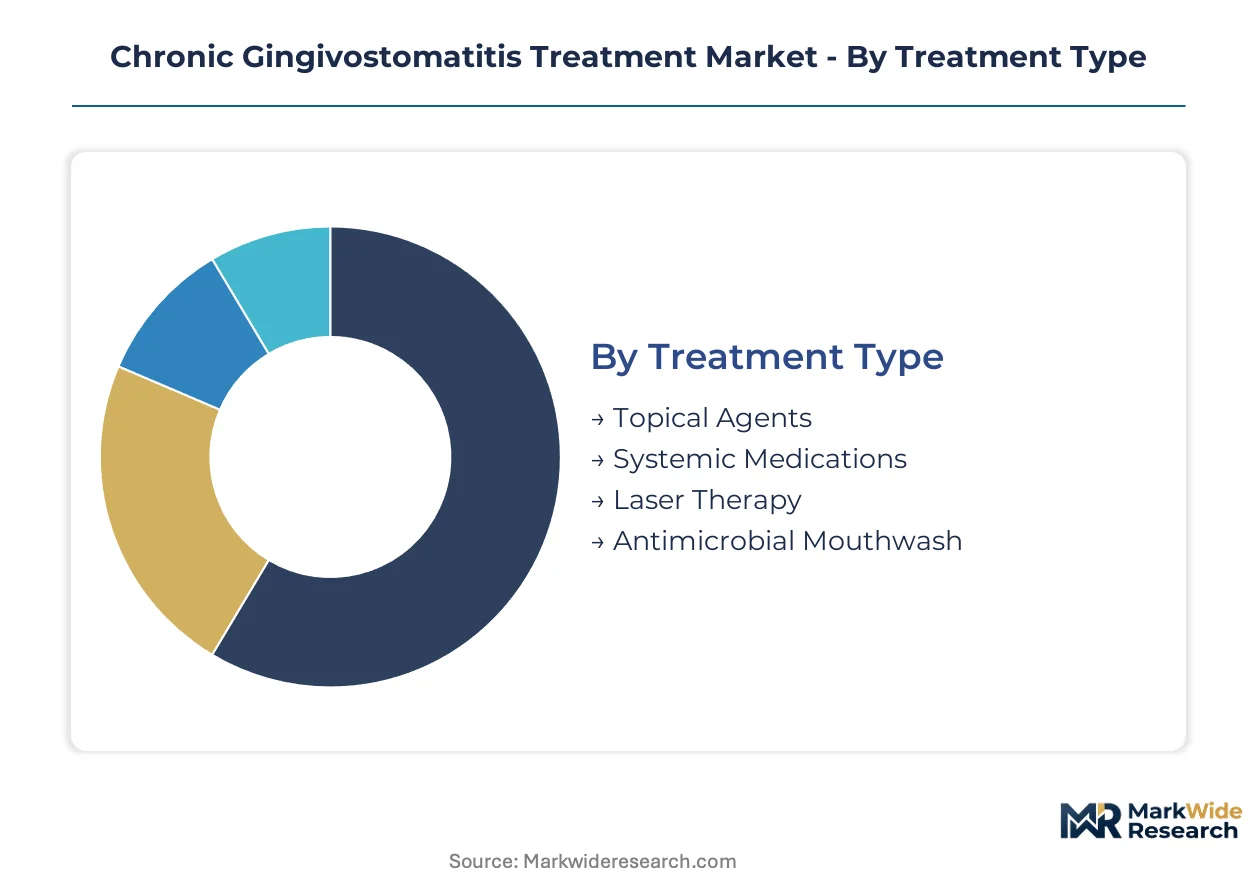
Chronic gingivostomatitis treatment protocols fragment across therapeutic modalities, delivery mechanisms, and care environments. Each segment carries distinct regulatory pathways, reimbursement profiles, and clinical adoption curves that shape commercial strategy.
Treatment Type:
Technology intensity separates pharmaceutical interventions from capital-intensive surgical modalities.
- Systemic Medications:Cyclosporine and corticosteroid formulations dominate refractory case management through immunosuppressive action. Demand concentrates in United States specialty clinics where pet insurance covers chronic pharmaceutical protocols. The FDA Center for Veterinary Medicine's pharmacovigilance requirements elevate manufactured product preference over compounded alternatives.
- Laser Therapy:CO2 and diode surgical platforms enable gingivectomy and ulcer ablation with reduced hemorrhage. Veterinary dentists in metropolitan United States markets are driving platform adoption as equipment manufacturers introduce leasing programs. Diode unit miniaturization is expanding access beyond academic referral centers.
- Topical Agents:Chlorhexidine rinses and transmucosal analgesics support multimodal protocols.
- Antimicrobial Mouthwash:Adjunctive infection control formulations maintain stable demand in dental office settings.
Systemic medications lead on scale; laser therapy leads on momentum.
Administration Route:
Patient compliance and caregiver capability determine route selection in feline populations.
- Oral:Transmucosal buprenorphine formulations achieve rapid absorption through buccal mucosa. United States homecare demand is climbing fastest as owners seek alternatives to pilling-resistant cats.
- Injections:Depot corticosteroid and cyclosporine formulations enable extended dosing intervals in refractory cases. Specialty veterinary dentistry practices rely on injectable protocols for pre- and post-operative management.
- Topical:Direct mucosal application of antiseptic and analgesic compounds.
- Inhalation:Nebulized antimicrobial delivery for upper respiratory co-infections.
Injections lead on scale; oral routes lead on momentum.
Patient Type:
Disease severity and immune status stratify therapeutic intensity across feline life stages.
- Adult:Prime-age cats represent the largest treatment population with established immune-mediated pathology. United States specialty clinics manage these cases through combined surgical and pharmaceutical protocols.
- Geriatric:Age-related immunosenescence and comorbidity burden complicate treatment selection. Renal function monitoring requirements in older cats constrain cyclosporine dosing in United States geriatric populations.
- Pediatric:Juvenile-onset presentations requiring modified dosing protocols.
- Immunocompromised:FeLV/FIV-positive cats with secondary opportunistic infections.
Adult cases lead on scale; geriatric cases lead on momentum.
Care Setting:
Capital equipment requirements and specialist availability concentrate advanced interventions in specific venues.
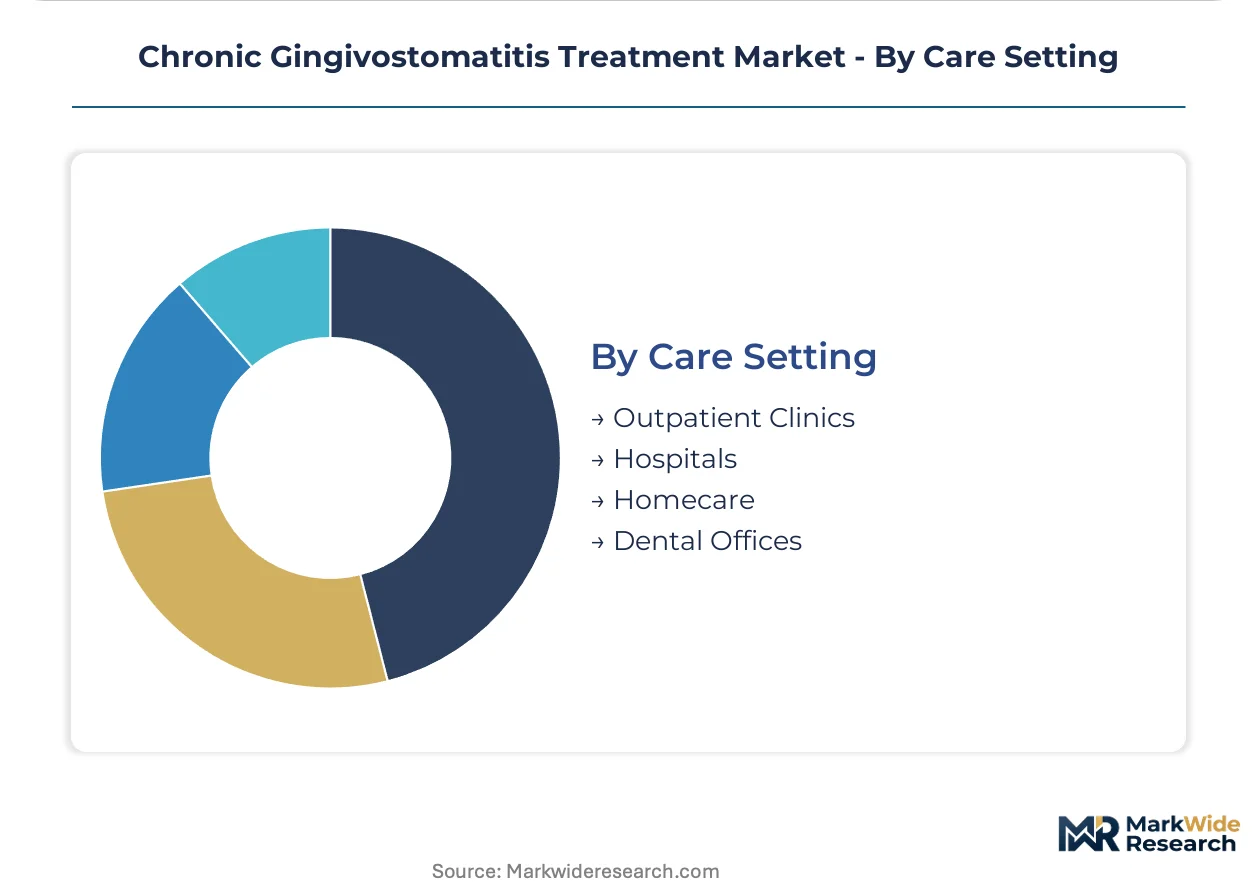
- Dental Offices:Board-certified veterinary dentists perform extractions and laser surgery in equipped facilities. The American Veterinary Dental College's residency growth is expanding specialist capacity in United States urban markets.
- Outpatient Clinics:General practice settings manage maintenance protocols and post-operative monitoring. Telemedicine integration is extending specialist oversight into these venues across United States metropolitan areas.
- Hospitals:Academic referral centers handle complex refractory cases.
- Homecare:Owner-administered maintenance regimens with remote veterinary guidance.
Dental offices lead on scale; outpatient clinics lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified veterinary dentists concentrate in United States metropolitan corridors, while specialist training programs in Europe and Asia-Pacific expand slowly. This geographic asymmetry shapes treatment protocol diffusion and pharmaceutical demand patterns across veterinary markets.
United States
Pet insurance penetration exceeding thirty percent in urban coastal markets removes cost barriers for multimodal feline oral surgery. The FDA Center for Veterinary Medicine enforces pharmacovigilance requirements that elevate manufactured immunosuppressant preference over compounded alternatives. Specialist density peaks in California, New York, and Texas metropolitan clusters where academic referral hospitals anchor regional training networks.
Germany
Small animal dentistry specialization through the European Veterinary Dental College produces practitioners capable of advanced gingivectomy procedures. The European Medicines Agency's Committee for Medicinal Products for Veterinary Use imposes efficacy benchmarks that filter which immunomodulatory formulations achieve commercialization. Berlin and Munich host the densest concentrations of equipped dental suites outside North America.
United Kingdom
Royal College of Veterinary Surgeons credentialing pathways create a controlled specialist pipeline limiting workforce expansion. The Veterinary Medicines Directorate maintains post-Brexit regulatory alignment with EMA safety standards while streamlining national approval timelines. London and southeast England concentrate referral capacity for complex refractory cases requiring combined surgical and pharmaceutical management.
Japan
Feline ownership rates in Tokyo and Osaka metropolitan corridors drive demand for advanced oral care exceeding regional specialist supply. The Ministry of Agriculture, Forestry and Fisheries oversees animal drug approvals through parallel pathways that extend development timelines for foreign sponsors. Yokohama and Nagoya academic veterinary centers perform the majority of laser surgical interventions nationally.
Australia
Specialist veterinary dentistry remains concentrated in Sydney and Melbourne despite geographic dispersal of pet ownership across coastal population centers. The Australian Pesticides and Veterinary Medicines Authority maintains stringent import requirements for immunosuppressive APIs used in compounding. Brisbane and Perth general practices increasingly refer refractory cases eastward due to equipment and expertise gaps.
Chronic Gingivostomatitis Treatment Market Vendor Landscape
Top-tier vendors anchor pharmaceutical manufacturing scale, while regional compounders and equipment lessors occupy fragmented service tiers. Market structure reflects human healthcare conglomerate dominance in active pharmaceutical ingredients, counterbalanced by specialty veterinary distributors controlling clinic-level access. Three archetypes prevail: diversified pharmaceutical majors with veterinary divisions, dedicated animal health specialists, and surgical equipment manufacturers with leasing arms. Competitive dynamics center on portfolio diversification into homecare formulations and strategic partnerships with specialty dental practice networks.
Within the pharmaceutical-major tier, Pfizer Inc. and Johnson & Johnson occupy positions shaped by manufacturing scale and human oral care brand equity respectively. GlaxoSmithKline PLC exemplifies the R&D-intensive archetype targeting novel immunomodulatory pathways. Merck & Co., Inc. and Novartis AG represent European-headquartered conglomerates with veterinary divisions leveraging global distribution infrastructure. Taj Pharmaceuticals Limited and Ciron Pharma anchor Indian-origin supply positions in generic API and compounding feedstock markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| GlaxoSmithKline PLC |
| Merck & Co., Inc. |
| Novartis AG |
| AstraZeneca PLC |
| Taj Pharmaceuticals Limited |
| Ciron Pharma |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
Board-certified veterinary dental specialists concentrate in United States metropolitan corridors, and their scarcity relative to demand spreads pricing tiers from premium specialty clinics to economy general-practice referrals. Labor-cost differentials between residency-trained practitioners and general veterinarians drive service unbundling as owners seek alternatives to bundled surgical packages.
Pricing Analysis
Bundled multimodal protocols separate from unbundled à la carte offerings across the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and equipment access, with American Veterinary Dental College diplomates commanding premium positioning. Pricing pressure stems from pet insurance reimbursement ceilings compressing specialty margins. Price-sensitive general practice owners gravitate toward economy tiers, while insured metropolitan clients absorb premium surgical-laser combinations.
Supply Chain Analysis
Workforce availability constraints in United States pharmaceutical manufacturing and Indian API synthesis shape upstream dependencies. Cyclosporine active pharmaceutical ingredient production concentrates in India, China, and Italy, with formulation finishing in United States and European Union facilities. Raw material sourcing draws from fermentation-derived compounds, synthetic chemical intermediates, and specialized packaging for veterinary dosing. Single-source vulnerability in generic immunosuppressant API supply elevates procurement risk. Distribution runs through veterinary specialty distributors and clinic-direct compounding pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European regulatory pathways compress development timelines relative to FDA Center for Veterinary Medicine review cycles, lowering cost-to-market for sponsors willing to sequence approvals strategically.
For Market Incumbents: Hedge against cyclosporine supply volatility through backward integration into API sourcing or captive supply agreements with Indian manufacturers. Defend position by acquiring laser equipment leasing platforms before general practice saturation erodes referral volumes. Channel control through specialty distributor exclusivity remains the priority lever against generic compounders. For New Entrants and Emerging Players: Capture white space in homecare transmucosal formulations where owner compliance pain points outpace incumbent innovation. Target underserved Australian and Japanese metropolitan markets where specialist density lags pet insurance penetration. A telemedicine-integrated go-to-market angle bypasses capital-intensive clinic buildout. For Investors and Strategic Acquirers: Human pharmaceutical conglomerates with dormant veterinary divisions are the most active acquirer in this space, seeking species-specific immunomodulatory assets. Long-term viability hinges on pipeline depth beyond corticosteroid-cyclosporine dependence. Watch stem cell therapy clinical outcome data as inflection indicator for regenerative medicine platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Center for Veterinary Medicine clearance unlocks manufactured product preference over compounded alternatives. |
| Manufacturing Scale-Up | Commercial batch production of feline-specific cyclosporine formulations reduces API sourcing volatility exposure. |
| Strategic Partnership | Equipment leasing alliances with diode laser manufacturers extend reach into general practice settings. |
| Pipeline Diversification | Novel immunomodulatory mechanisms beyond calcineurin inhibition address refractory case unmet need. |
| Geographic Expansion | Tokyo and Osaka metropolitan corridor entry captures specialist supply-demand imbalance in Japanese feline ownership markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from veterinary dental specialists, compounding pharmacy operators, pet insurance underwriters, and specialty distributor procurement managers. Secondary validation drew from FDA Center for Veterinary Medicine approval databases, EMA Committee for Medicinal Products for Veterinary Use submissions, American Veterinary Dental College residency program records, and pet insurance claims aggregators. Bottom-up procedure volume estimates and top-down pharmaceutical spend analysis were cross-referenced for triangulation.
Segment-weighting approaches distributed value across treatment modality, administration route, patient life stage, and care setting dimensions. CAGRs were derived from procedure growth rates, pharmaceutical pricing trajectories, and equipment installation forecasts across the projection horizon. Modeling incorporated laser platform adoption curves, cyclosporine prescription persistence, and specialist workforce expansion timelines as industry-specific forecast inputs.
Regulatory pathway delays, API supply disruptions, and pet insurance reimbursement policy shifts are the dominant revision risks. Forecasts reflect assumptions regarding FDA review cycle stability and compounding pharmacy enforcement continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
EMEA Dental Service Organization Market
Dental Services
United States Dental Services Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Periodontal Dental Service Market
Dental Services
US Dental Chains Market
Dental Services
Dental Market
Dental Services
Microdontia Treatment Market
Dental Services
Dental Services Market
Dental Services
Dental Service Organization Market
Dental Services
Teledentistry Market
Dental Services
Orthodontic Services Market