
 Mosquito-Borne Diseases Treatment Market | 2026-2036
Mosquito-Borne Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mosquito-Borne Diseases Treatment Market Analytics
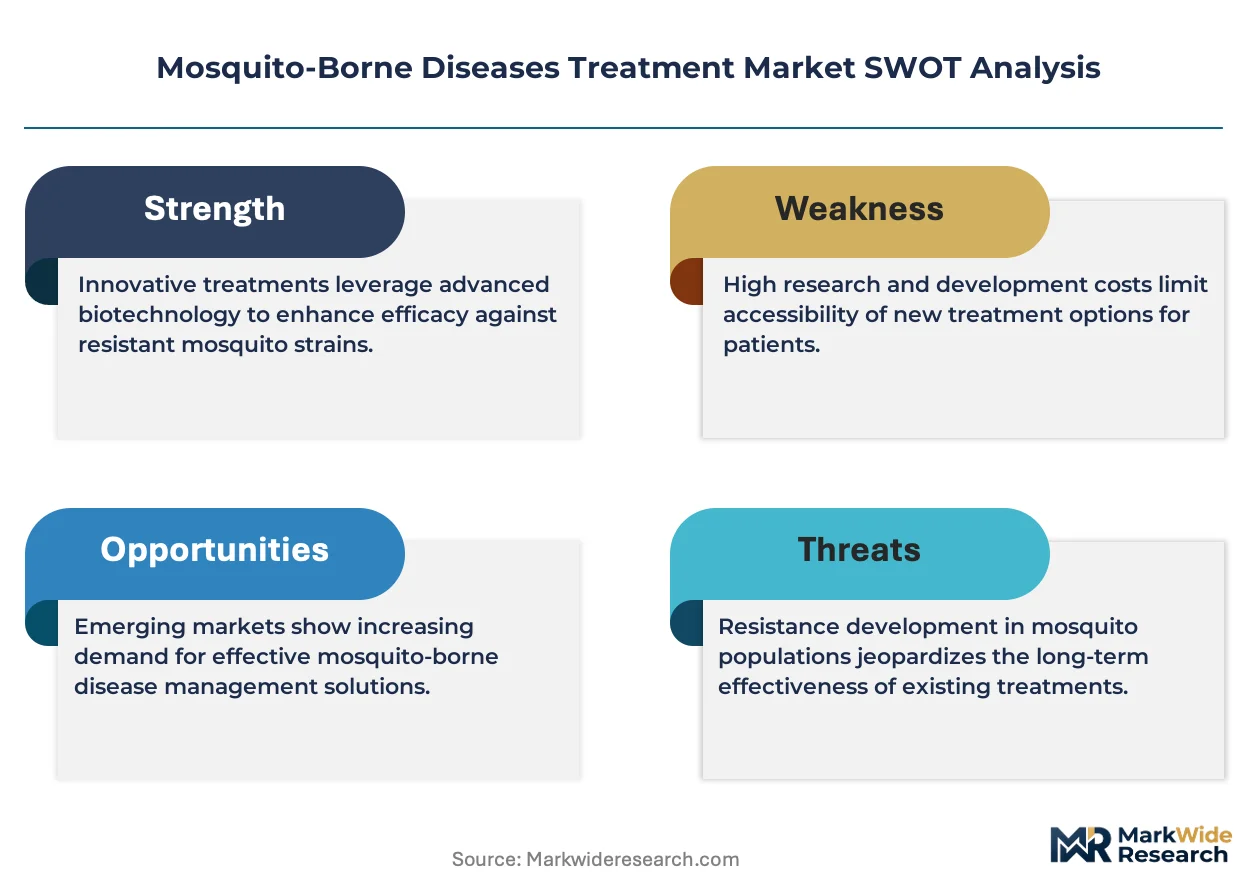
India's vaccine manufacturing corridor is reconfiguring supply dynamics for mosquito-borne disease interventions across tropical markets. Sanofi SA leverages its established yellow fever and dengue vaccine platforms to sustain production scale in European and Latin American distribution networks. Serum Institute of India Pvt Ltd anchors affordable supply commitments through its high-volume fill-finish capacity serving WHO and Gavi procurement channels.
Mosquito-borne diseases treatment encompasses pharmaceutical and biological interventions designed to prevent or manage infections transmitted by Anopheles, Aedes, and Culex vectors, with formulations typically requiring cold-chain stability between two and eight degrees Celsius and sterile manufacturing under GMP Annex 1 guidelines. The primary commercial purpose centers on reducing morbidity and mortality in endemic regions while supporting travel medicine and military prophylaxis in non-endemic markets. Vaccines and antiviral drugs capture the dominant margin pools, with dengue and malaria therapy areas commanding the largest development pipelines due to established disease burden metrics and donor funding visibility. Injectable delivery modes lead in institutional settings, though oral formulations are gaining traction in homecare segments where patient self-administration reduces healthcare system costs.
FDA and EMA stringency around Phase III efficacy endpoints for dengue vaccines shapes development timelines and capital requirements for entrants targeting Western markets. India's CDSCO and the WHO prequalification program jointly determine market access for affordable products distributed through public procurement in endemic countries. Stakeholders must monitor regulatory divergence between stringent-authority approval standards and the accelerated pathways emerging under national priority disease designations in high-burden geographies.
Market Dynamics
The WHO prequalification program is compressing registration timelines for injectable antiviral therapies, pulling procurement decisions toward standardized efficacy endpoints and cold-chain infrastructure investments in endemic regions.
Growth Catalysts
- Gavi procurement commitments:The vaccine alliance's volume guarantees for malaria and dengue immunization programs are de-risking manufacturing scale-up for regional suppliers in South Asia.
- India PLI scheme:Production-linked incentives for pharmaceutical manufacturing are expanding domestic fill-finish capacity for WHO-prequalified injectables targeting African public health systems.
- Vector surveillance digitization:Real-time outbreak monitoring platforms are accelerating treatment deployment timelines and expanding addressable patient populations in Southeast Asian urban corridors.
Market Restraints
- Cold-chain infrastructure gaps:Last-mile refrigeration failures in sub-Saharan Africa are limiting effective distribution of temperature-sensitive biologics requiring two-to-eight-degree stability.
- API concentration in China:Active pharmaceutical ingredient manufacturing for antimalarials clusters in Zhejiang and Jiangsu provinces, creating supply vulnerability during export restriction episodes.
- FDA serostatus testing requirements:The agency's mandatory pre-vaccination screening protocols for dengue immunization are constraining rollout velocity in Western travel medicine segments.
Strategic Opportunities
- Indonesia archipelago expansion:The country's 17,000-island geography and rising dengue burden create demand for heat-stable oral formulations bypassing injection-dependent distribution.
- EMA accelerated assessment pathway:The regulator's priority medicine designation for tropical diseases is shortening time-to-market for novel antiviral candidates targeting European travelers.
- Telemedicine integration:Remote diagnostic platforms are enabling prescriptive authority expansion for community health workers in Brazilian favela networks previously underserved by specialist infrastructure.
Industry Challenges
- GMP Annex 1 sterile manufacturing compliance:The revised EU guidelines on contamination control are forcing facility upgrades costing tens of millions for legacy fill-finish operations.
- Vector resistance monitoring:Anopheles and Aedes insecticide resistance tracking requires specialized entomological expertise scarce in national disease control programs across West Africa.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mosquito-Borne Diseases Treatment Market |
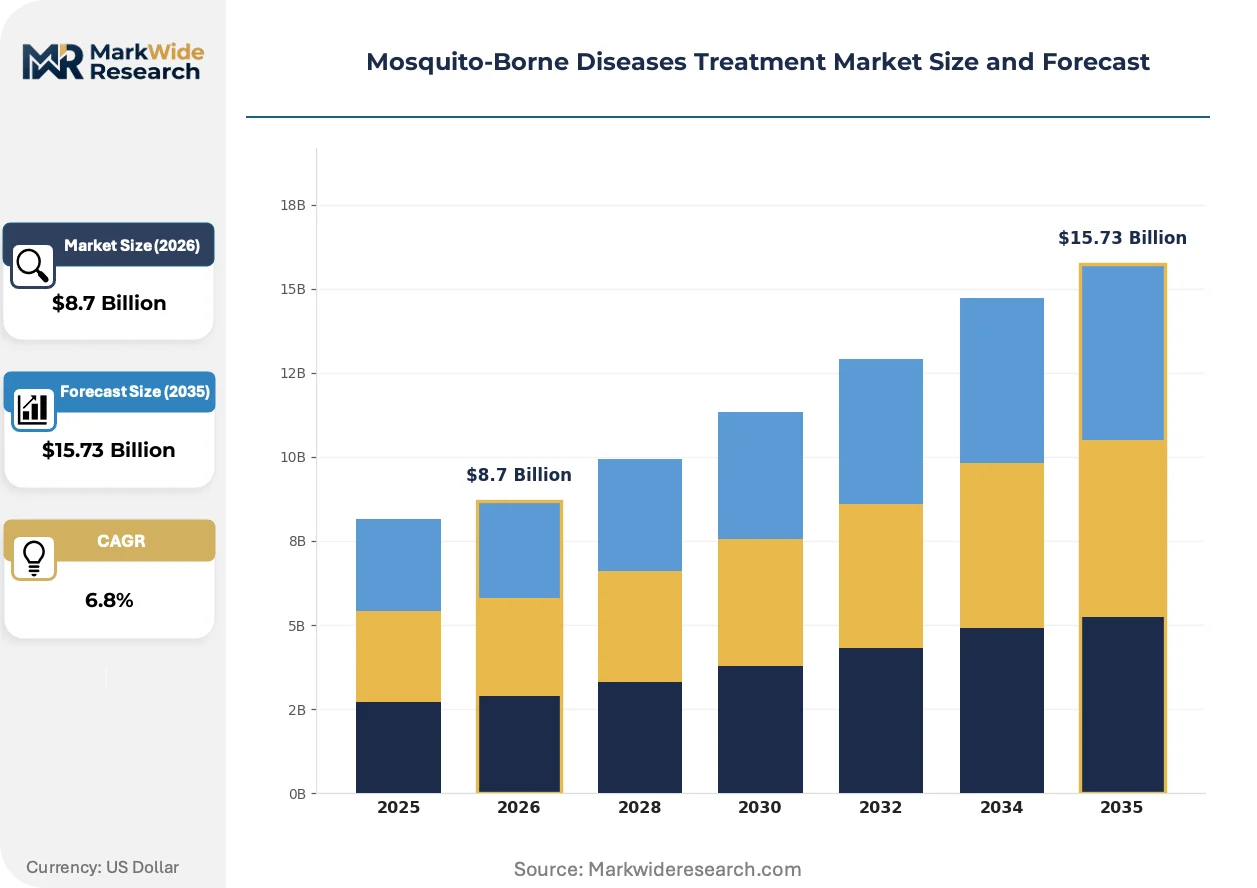
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antiviral Drugs, Insecticides, Diagnostics Therapy Area: Dengue, Zika, Malaria, Chikungunya Delivery Mode: Injectable, Oral, Topical, Intranasal End User: Hospitals, Clinics, Research Institutes, Homecare |
| Companies Covered | Sanofi SA, Pfizer Inc., Merck & Co. Inc., Johnson & Johnson, Novartis AG, GlaxoSmithKline plc, Takeda Pharmaceutical Company Limited, Serum Institute of India Pvt Ltd, Bharat Biotech International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mosquito-Borne Diseases Treatment Market Evolving Landscape
mRNA platform migration is disrupting established adjuvant-based vaccine manufacturing, with developers repurposing COVID-19 production infrastructure toward dengue and malaria candidates.
Self-amplifying RNA formulations are virtualizing the traditional dose-response curve for dengue vaccines, enabling lower antigen loads per immunization. Brazilian public health institutes are piloting these candidates in urban favela networks where cold-chain reliability remains problematic. The technology is virtualizing inventory requirements and expanding the geographic footprint of effective coverage without proportional infrastructure investment.
EMA's PRIME scheme designation for tropical disease therapies is compressing regulatory review timelines from thirty-six to eighteen months for qualifying antiviral candidates. The scheme's rolling data submission protocol allows developers to file efficacy packages incrementally rather than awaiting complete Phase III readouts. West African regulatory harmonization initiatives are adopting EMA assessment reports to accelerate national marketing authorizations.
Hospital procurement committees are consolidating vendor relationships around integrated supply contracts bundling diagnostics, therapeutics, and vector control products. Brazilian SUS purchasing cooperatives are displacing fragmented spot-buying with multi-year framework agreements locking volume commitments and price ceilings. This consolidation is most visible in São Paulo and Minas Gerais state health systems where centralized tendering now covers eighty percent of arbovirus treatment expenditure.
Mosquito-Borne Diseases Treatment Market Segmentation
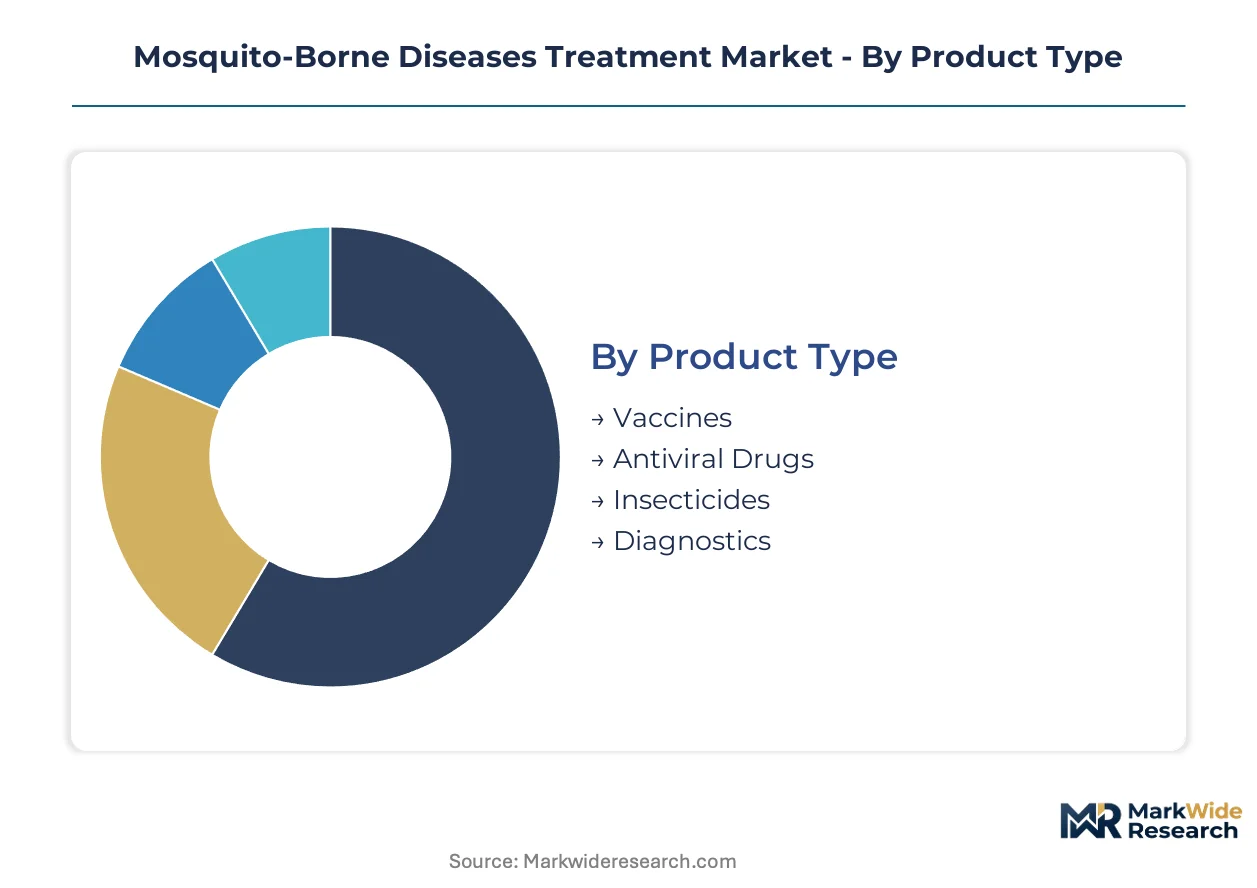
Treatment modality selection in mosquito-borne disease management hinges on cold-chain viability, patient compliance patterns, and procurement channel concentration. Segment boundaries reflect divergent margin structures between institutional tenders and retail pharmacy distribution.
Product Type:
Cost tier stratification separates biological interventions from chemical and diagnostic categories, with manufacturing complexity and regulatory stringency driving margin dispersion.
- Vaccines:Live-attenuated and mRNA formulations require GMP Annex 1 sterile manufacturing and two-to-eight-degree Celsius stability throughout distribution. WHO prequalification programs in India and Gavi procurement corridors in Geneva are consolidating demand around high-volume fill-finish suppliers.
- Antiviral Drugs:Small-molecule therapeutics targeting viral replication enzymes dominate hospital formularies in Brazilian public health systems. API concentration in Zhejiang province creates supply vulnerability during Chinese export restriction episodes.
- Insecticides:Pyrethroid and organophosphate formulations for vector control programs.
- Diagnostics:Rapid antigen detection kits and PCR platforms for outbreak surveillance.
Vaccines command the established base. The steepest expansion runs through antiviral drugs.
Therapy Area:
Application focus varies by vector species and disease burden metrics, with established funding pipelines determining commercial prioritization.
- Dengue:Tetravalent vaccine development targets all four serotypes simultaneously, with FDA serostatus testing requirements constraining rollout in Western travel medicine segments. Brazilian urban corridors and Indonesian archipelago networks are piloting heat-stable formulations bypassing cold-chain dependencies.
- Malaria:Plasmodium falciparum and vivax species drive antimalarial R&D through established donor funding visibility. Sub-Saharan African procurement via Global Fund mechanisms anchors volume commitments for artemisinin-based combination therapies.
- Zika:Congenital syndrome prevention programs in Latin American maternity networks.
- Chikungunya:Arthralgia management protocols in Indian Ocean region outbreak response.
Malaria commands the established base. Dengue is climbing the fastest.
Delivery Mode:
Volume concentration shifts toward patient-administered formats as healthcare system cost pressures intensify.
- Injectable:Intravenous and intramuscular formulations dominate institutional settings requiring precise dosing control. Hospital procurement committees in São Paulo and Minas Gerais state health systems are consolidating vendor relationships around multi-year framework agreements.
- Oral:Tablet and capsule formats enable homecare self-administration, reducing specialist infrastructure requirements. Indonesian archipelago geography is driving demand for heat-stable oral antivirals bypassing injection-dependent distribution across 17,000 islands.
- Topical:Repellent creams and lotions for personal protection in endemic regions.
- Intranasal:Mucosal delivery platforms under evaluation for pediatric immunization.
Injectable formats command the established base. Oral delivery is gaining share fastest.
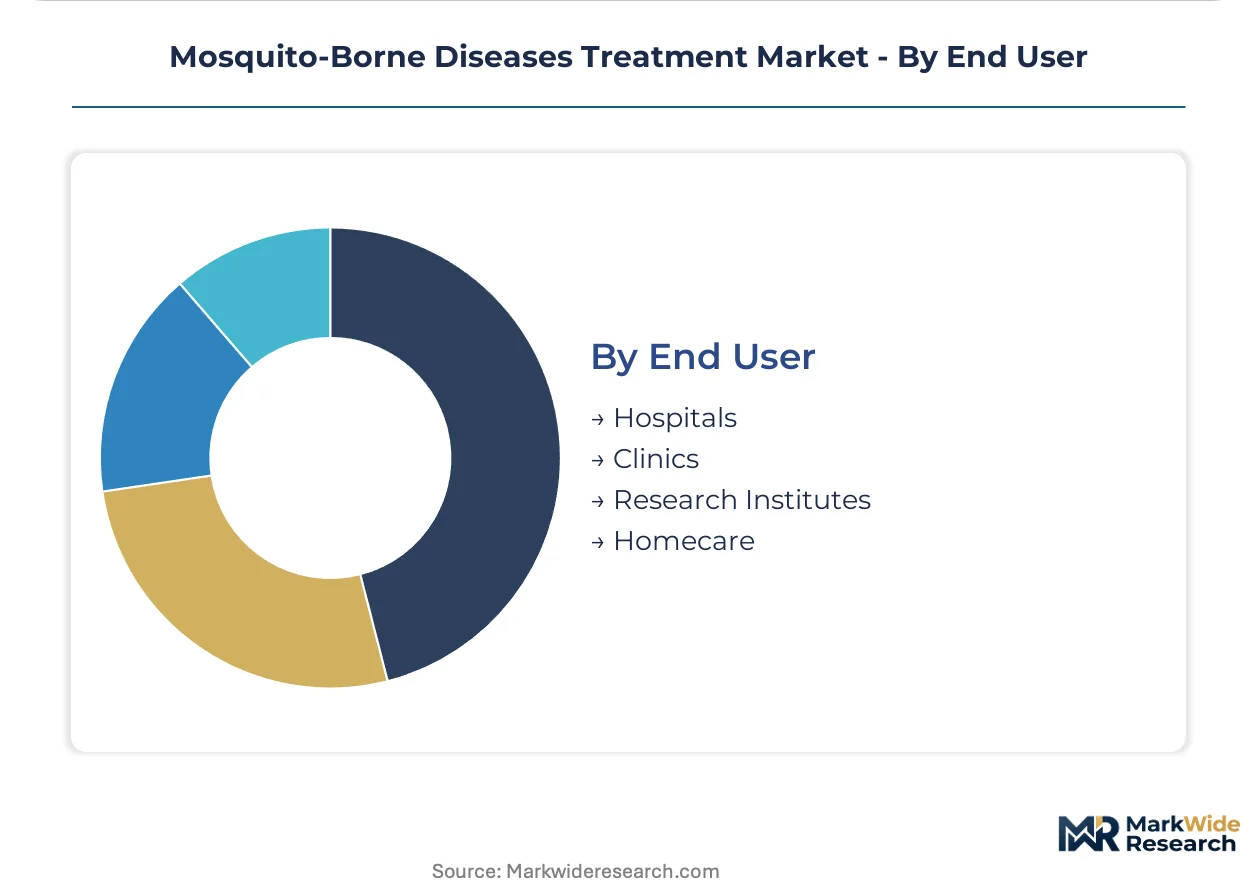
End User:
Customer type determines procurement channel structure and pricing negotiation leverage.
- Hospitals:Tertiary care centers with centralized pharmacy and cold-chain infrastructure. Brazilian SUS purchasing cooperatives are displacing fragmented spot-buying with integrated supply contracts bundling diagnostics, therapeutics, and vector control products.
- Clinics:Primary care facilities with limited refrigeration capacity.
- Research Institutes:Field trial sites and vector surveillance laboratories.
- Homecare:Patient-directed administration supported by telemedicine platforms in Brazilian favela networks.
Hospitals command the established base. Homecare segments show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fill-finish capacity for WHO-prequalified injectables clusters in South Asia, with Indian manufacturers anchoring supply commitments for African public health systems. European and Latin American distribution networks sustain production scale through established vaccine platforms.
India
Domestic vaccine manufacturing and government immunization programs are creating substantial volume commitments for regional suppliers. CDSCO and the WHO prequalification program jointly determine market access for affordable products distributed through public procurement. The Pune and Hyderabad clusters concentrate high-volume fill-finish operations serving Gavi procurement channels.
Brazil
Urban favela networks and SUS purchasing cooperatives are consolidating procurement around integrated supply contracts. ANVISA regulatory frameworks govern product registration for arbovirus treatments. São Paulo and Minas Gerais state health systems anchor centralized tendering covering eighty percent of treatment expenditure.
United States
FDA serostatus testing requirements for dengue immunization constrain rollout velocity in travel medicine segments. The agency's Phase III efficacy endpoint stringency shapes development timelines for Western market entrants. Boston and Maryland biotech corridors concentrate clinical trial infrastructure for tropical disease candidates.
Indonesia
The 17,000-island geography and rising dengue burden create demand for heat-stable oral formulations bypassing injection-dependent distribution. National priority disease designations under the health ministry accelerate regulatory pathways for novel antivirals. Java-based manufacturing facilities pilot self-amplifying RNA candidates for archipelago coverage.
Germany
EMA accelerated assessment pathways and PRIME scheme designations compress regulatory review timelines for tropical disease therapies. The regulator's rolling data submission protocol allows incremental filing of efficacy packages. Frankfurt and Munich anchor cold-chain logistics hubs serving European distribution networks.
Mosquito-Borne Diseases Treatment Market Competitive Landscape
Multinational vaccine platforms and regional fill-finish specialists split the market between premium-tier Western distribution and affordable supply channels. Consolidation pressures intensify as procurement committees bundle diagnostics, therapeutics, and vector control products under multi-year framework agreements. Two strategic archetypes dominate: established pharmaceutical conglomerates with validated manufacturing infrastructure, and high-volume regional suppliers leveraging production-linked incentive schemes. Competitive moves center on capacity expansion in WHO-prequalified facilities and technology licensing for heat-stable formulation platforms.
Within the multinational tier, Sanofi SA and Takeda Pharmaceutical Company Limited exemplify platform-based competition through established yellow fever and dengue vaccine franchises. Serum Institute of India Pvt Ltd anchors the regional specialist archetype, occupying a position defined by high-volume fill-finish capacity and Gavi procurement integration. These three entities represent the structural divide between Western market access requirements and endemic-region affordability mandates.
| Leading Market Players |
|---|
| Sanofi SA |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Johnson & Johnson |
| Novartis AG |
| GlaxoSmithKline plc |
| Takeda Pharmaceutical Company Limited |
| Serum Institute of India Pvt Ltd |
| Bharat Biotech International Limited |
| Others |
Value Network & Pricing Analysis
Undercapacity in Indian fill-finish facilities is compressing supplier margins while amplifying pricing power for WHO-prequalified manufacturers serving Gavi procurement channels. Utilization rates above ninety percent in Pune and Hyderabad clusters are forcing buyers into longer-term offtake commitments with price escalation clauses.
Pricing Analysis
WHO prequalification status dictates the pricing tier structure across procurement corridors, separating premium-tier Western suppliers from standard-tier regional manufacturers and economy-tier local formulators. Price differentiation rests on GMP Annex 1 certification grade and cold-chain reliability guarantees. Pricing pressure stems from Gavi volume guarantees consolidating demand around high-volume suppliers. Public health systems in sub-Saharan Africa exhibit the highest price sensitivity, while Western travel medicine segments absorb premium pricing for serostatus-compliant dengue vaccines.
Supply Chain Analysis
Extended payment terms from Brazilian SUS purchasing cooperatives are squeezing working capital for API suppliers in Zhejiang and Jiangsu provinces. Active pharmaceutical ingredient manufacturing draws from Chinese chemical intermediates, Indian fermentation capacity, and European specialty solvent suppliers. Single-source vulnerability concentrates in artemisinin derivative precursors facing export restriction episodes. Distribution runs through Frankfurt and Mumbai cold-chain hubs serving institutional procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across therapy areas and delivery modes is creating specialist niches as procurement committees displace fragmented spot-buying with integrated supply contracts.
For Market Incumbents: Harden cold-chain infrastructure partnerships in sub-Saharan Africa to defend against heat-stable oral formulation entrants targeting Indonesian archipelago distribution. Consolidate vendor relationships around multi-year framework agreements bundling diagnostics, therapeutics, and vector control products. Prioritize GMP Annex 1 facility upgrades to meet EU contamination control guidelines and sustain WHO prequalification status.
For New Entrants and Emerging Players: Establish a beachhead in Indonesian oral antiviral segments where archipelago geography frustrates injection-dependent distribution. Target Brazilian favela homecare networks underserved by specialist infrastructure through telemedicine-integrated prescriptive platforms. Lead with heat-stable formulation licensing from self-amplifying RNA developers to bypass incumbent cold-chain advantages.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional fill-finish specialists with Gavi procurement integration and production-linked incentive backing. Long-term viability favors manufacturers with validated mRNA platform migration capability and WHO prequalification track records. Watch for EMA PRIME scheme designations as inflection indicators for regulatory pathway compression and accelerated European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Accelerates registration timelines in African public health procurement corridors. |
| Heat-Stable Formulation Licensing | Enables archipelago coverage without proportional cold-chain infrastructure investment. |
| GMP Annex 1 Facility Upgrade | Ensures compliance with EU contamination control guidelines for sterile manufacturing. |
| Integrated Supply Contracting | Bundles diagnostics, therapeutics, and vector control for Brazilian SUS cooperatives. |
| mRNA Platform Migration | Repurposes COVID-19 production infrastructure toward dengue and malaria candidates. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and WHO prequalification databases. Bottom-up demand modeling triangulated against top-down procurement volume aggregates from Gavi and Global Fund disclosure records.
Scenario-bracketing around regulatory approval velocity and cold-chain infrastructure deployment framed the analytical envelope across the projection horizon. Segmentation dimensions included treatment modality, therapy area, delivery mode, and end-user procurement channel. CAGRs were derived from epidemiological burden projections cross-referenced with immunization program scale-up schedules and donor funding visibility timelines.
Stress conditions across API export restriction episodes, vector resistance emergence rates, and Gavi commitment renewal cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and procurement consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Pyomyositis Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Q Fever Market