
 Measles Market | 2026-2036
Measles Market Size, Share, and Industry Trends Forecast 2026-2036
Measles Market Foresight
Premium measles-mumps-rubella combination vaccines and standalone commodity doses is rebalancing as procurement bodies split tender awards by cold-chain capability and price point. Merck & Co., Inc. leverages its long-standing MMR franchise and domestic manufacturing footprint to sustain institutional contracts across North America. Serum Institute of India Pvt. Ltd. anchors global supply of affordable measles-containing vaccines through WHO-prequalified facilities serving Gavi-eligible markets.
Measles represents a highly contagious paramyxovirus infection characterized by fever, cough, coryza, conjunctivitis, and maculopapular rash, with the live-attenuated vaccine typically administered in two doses achieving seroconversion rates exceeding 95 percent after the second dose. The product type dimension shows vaccines commanding the dominant value pool due to preventive program scale, while diagnostics segments compete on point-of-care molecular test speed and field-deployable serology platforms. Delivery mode preferences concentrate around subcutaneous administration for first-dose campaigns in resource-limited settings, with intramuscular formats gaining traction in adolescent and adult catch-up programs.
FDA and WHO prequalification frameworks govern lot release, stability testing, and post-marketing surveillance for measles vaccines distributed through UNICEF procurement channels. The EU Green Deal and REACH-aligned cold-chain sustainability requirements are forcing manufacturers to evaluate non-HFC refrigerant alternatives for transport and storage infrastructure. Stakeholders must monitor mRNA platform transfer agreements and technology hub licensing decisions that could redistribute manufacturing geography across the forecast horizon.
Market Dynamics
mRNA platform transfer agreements and WHO prequalification standards are redrawing manufacturing geography while cold-chain sustainability mandates force refrigerant transitions across transport networks.
Growth Catalysts
- Sub-Saharan immunization scale-up:Gavi alliance procurement commitments are expanding vaccine volumes through national routine immunization programs and supplemental campaigns.
- EU Green Deal cold-chain mandates:REACH-aligned F-Gas Regulation phase-downs are accelerating adoption of non-HFC refrigerant infrastructure for last-mile distribution.
- Point-of-care molecular diagnostics:Field-deployable RT-PCR and LAMP platforms are enabling outbreak confirmation without centralized laboratory capacity.
Market Restraints
- Serum protein supply concentration:Bovine serum albumin and human albumin inputs for cell culture media face supplier bottlenecks in South America and Oceania.
- Stability testing timelines:WHO prequalification lot-release protocols require 24-month real-time stability data before procurement eligibility.
- Lyophilization capacity scarcity:Freeze-dryer manufacturing slots for heat-stable vaccine formulations concentrate among European and Indian contract service providers.
Strategic Opportunities
- Microarray patch delivery:Dissolvable microneedle arrays eliminate cold-chain requirements and enable community health worker administration in rural Indonesia and Nigeria.
- Technology hub licensing:WHO mRNA technology transfer hubs in South Africa and Senegal offer localized fill-finish capacity for regional supply security.
- Adult catch-up segmentation:Intramuscular presentation preferences among adolescent and healthcare worker cohorts create differentiated SKU demand in Brazil and Mexico.
Industry Challenges
- Qualified person scarcity:WHO-prequalified release pharmacovigilance expertise concentrates among aging specialists in European and Indian regulatory affairs departments.
- Legacy vial format integration:Multi-dose vial presentation requirements conflict with single-dose prefilled syringe automation investments at fill-finish facilities.
- Seroconversion surveillance gaps:Population-level immunity monitoring infrastructure remains underdeveloped in conflict-affected regions of Sudan and Yemen.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Measles Market |
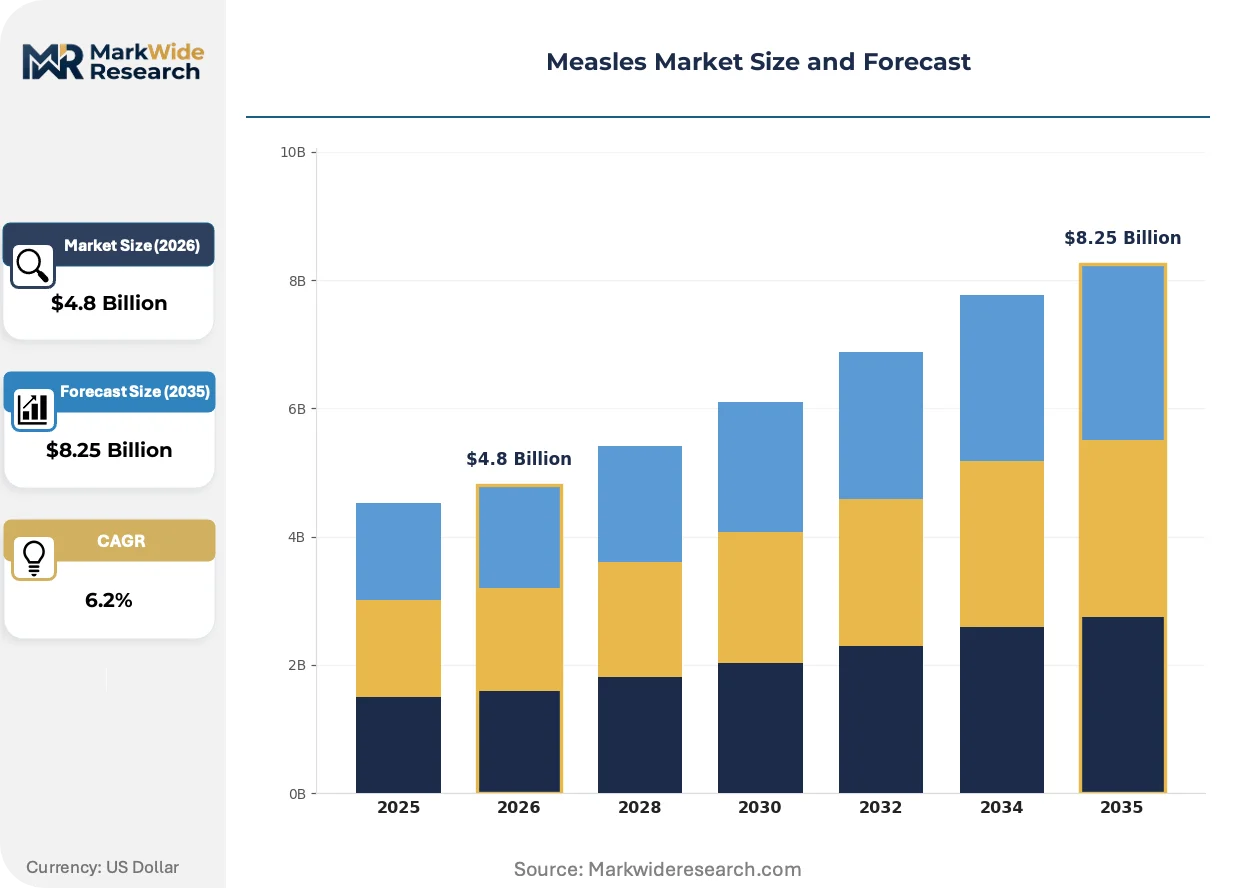
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibodies, Diagnostics, Therapeutics Delivery Mode: Intramuscular, Subcutaneous, Oral, Intrapulmonary End User: Hospitals, Clinics, Labs, Health Centers Age Group: Children, Adults, Adolescents, Seniors |
| Companies Covered | Merck & Co., Inc., GSK, Serum Institute of India Pvt. Ltd., Sanofi, Biological E. Limited, Sinovac Biotech, Indian Immunologicals Limited, Zydus Lifesciences Limited, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Measles Market Shifts & Advancements
Platform technology transitions and delivery format diversification are compressing traditional manufacturing hierarchies while procurement bodies split awards by technical capability tiers.
Lyophilized heat-stable measles vaccine formulations are consolidating market share among procurement bodies operating in tropical climates with unreliable cold-chain infrastructure. UNICEF and PAHO tenders now specify 40°C stability thresholds that exclude standard liquid presentations. This technical specification is consolidating supplier pools toward manufacturers with validated freeze-drying suites and alternative stabilizer chemistries.
WHO prequalification pathway revisions introduced in 2023 are compressing timeline uncertainty for combination vaccine developers seeking MMR-varicella and MMRV presentations. The streamlined stability waiver provisions reduce redundant clinical bridging studies when monovalent components hold existing prequalification. Indian and South Korean manufacturers are restructuring dossier submissions to exploit this regulatory efficiency.
Diagnostic procurement is fragmenting between centralized reference laboratories and decentralized point-of-care platforms. National health ministries in Kenya and Bangladesh are splitting IgM serology contracts between high-throughput ELISA hubs and rapid lateral flow field kits. This bifurcation is creating parallel vendor ecosystems with distinct service and training requirements.
Measles Market Segmentation
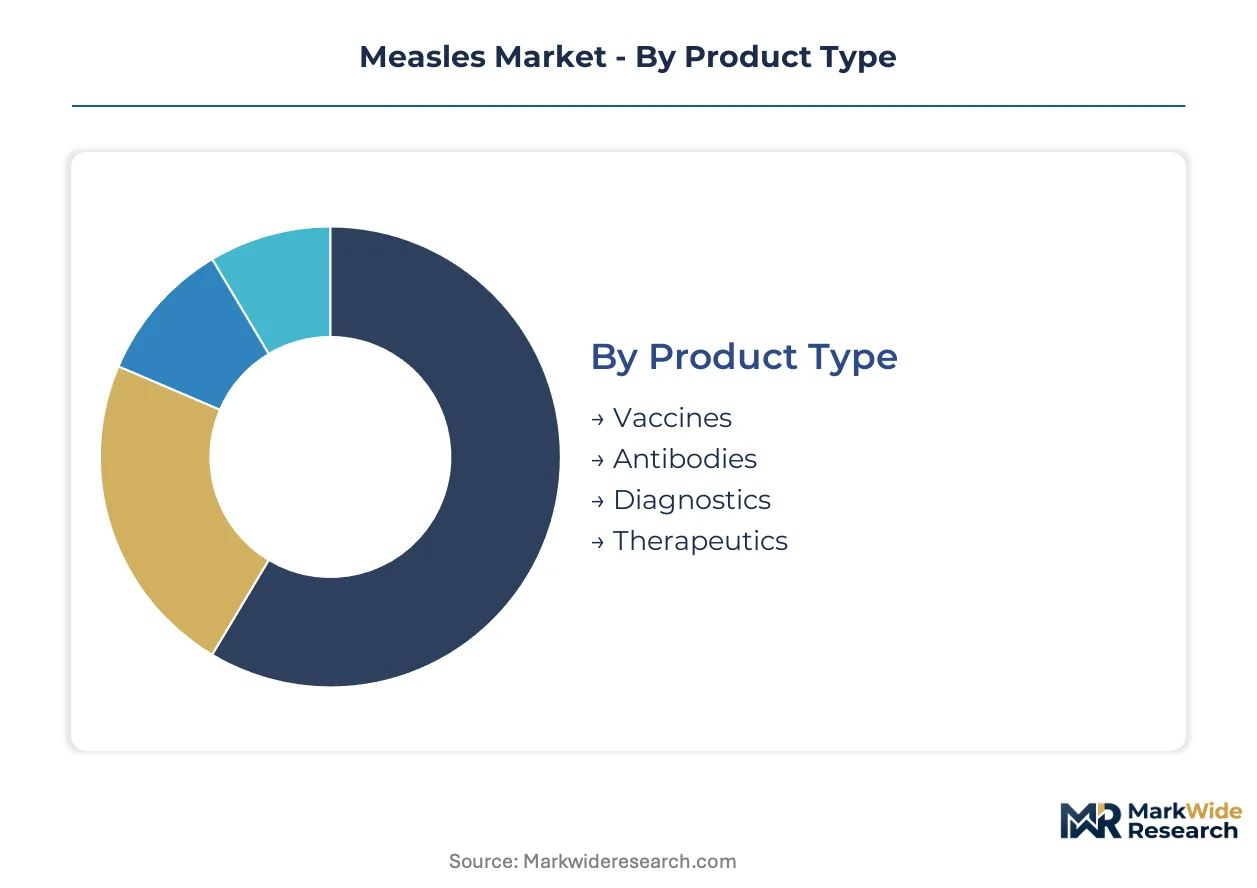
Measles market segmentation reflects divergent technical requirements across prevention, detection, and treatment modalities. Procurement bodies split awards by cold-chain capability, administration setting, and patient immunological status.
Product Type:
Upgrade cycles differentiate between legacy live-attenuated platforms and emerging molecular formats, with procurement bodies rebalancing portfolios based on stability profiles and delivery infrastructure.
- Vaccines:Live-attenuated formulations dominate procurement volumes through WHO prequalification pathways. UNICEF tenders concentrate in India and sub-Saharan Africa where national routine immunization programs scale first-dose and second-dose coverage campaigns.
- Diagnostics:Point-of-care molecular platforms and field-deployable serology tests compete on outbreak confirmation speed. Kenya and Bangladesh split contracts between centralized ELISA hubs and rapid lateral flow kits for community health worker deployment.
- Antibodies:Post-exposure prophylaxis immunoglobulin serves immunocompromised patients and non-responders to vaccination. Hospital pharmacy procurement in Brazil and Mexico maintains stockpiles for outbreak containment.
- Therapeutics:Supportive care agents and antiviral adjuncts address severe complications in hospitalized cases. Clinical demand concentrates in conflict-affected regions with underdeveloped surveillance infrastructure.
Vaccines sit at the top of the volume ranking, with Diagnostics climbing the fastest as decentralized testing infrastructure expands.
Delivery Mode:
Cost tiers separate cold-chain-dependent presentations from heat-stable alternatives, with procurement premiums attaching to field-deployable formats.
- Subcutaneous:Standard first-dose administration in resource-limited settings through multi-dose vial presentations. Gavi alliance procurement favors this route for community health worker campaigns in Nigeria and Indonesia.
- Intramuscular:Adolescent and adult catch-up programs prefer prefilled syringe formats. Brazil and Mexico health ministries specify this presentation for healthcare worker and traveler immunization.
- Oral:Experimental mucosal delivery platforms eliminate needle requirements and cold-chain constraints. Early-phase development targets last-mile distribution gaps in tropical climates.
- Intrapulmonary:Aerosolized vaccine delivery via nebulizer targets respiratory mucosal immunity. Clinical trials evaluate suitability for mass campaign settings with limited injection supply.
Subcutaneous administration retains the highest procurement volumes, though Intramuscular formats are gaining share fastest among adolescent cohorts.
End User:
Application requirements fragment between centralized cold-chain hubs and decentralized community access points.
- Health Centers:Frontline immunization posts handle routine first-dose administration in rural India and sub-Saharan Africa. Solar-powered refrigeration investments expand reach beyond grid-connected facilities.
- Hospitals:Tertiary facilities manage severe measles complications and post-exposure prophylaxis. Urban referral networks in Brazil and Mexico concentrate specialized pediatric and infectious disease capacity.
- Clinics:Private and public outpatient settings deliver catch-up immunization to adolescents and adults. Urban middle-income demand in India drives differentiated SKU procurement.
- Labs:Centralized reference laboratories and point-of-care platforms split diagnostic confirmation workflows. Kenya's national health ministry bifurcates IgM serology contracts between high-throughput hubs and field kits.
Health Centers represent the largest addressable base by volume, with Labs expanding most quickly as molecular diagnostic procurement accelerates.
Age Group:
Customer type determines presentation preferences, dosing schedules, and procurement channel selection.
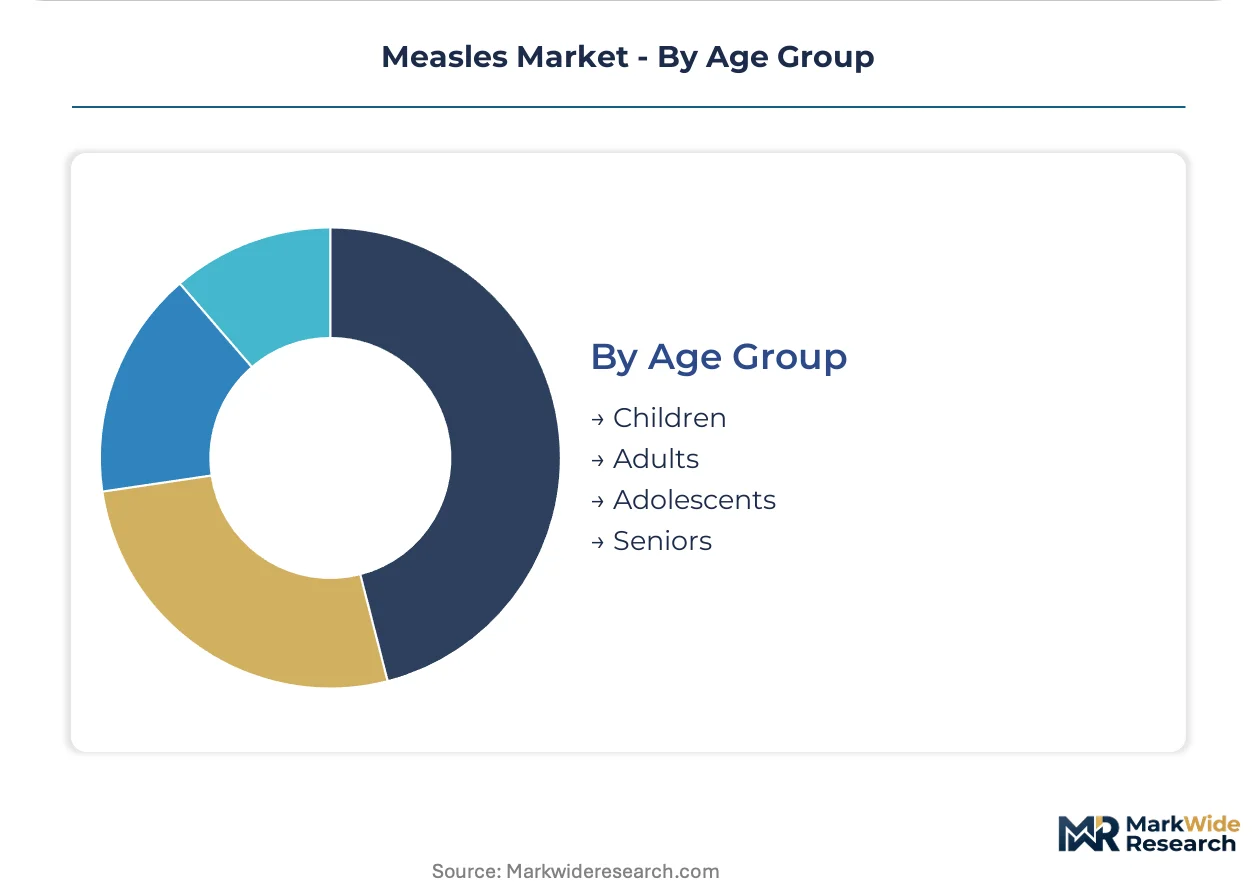
- Children:Two-dose primary series targets seroconversion rates exceeding 95 percent after dose two. National routine immunization programs in Gavi-eligible countries concentrate procurement here.
- Adolescents:Catch-up campaigns address immunity gaps in cohorts missed during infancy. Intramuscular prefilled syringe preferences create differentiated demand in Brazil and Mexico.
- Adults:Healthcare worker immunization and traveler health requirements drive occupational health procurement. Occupational medicine clinics in India specify combination MMR presentations.
- Seniors:Revaccination and post-exposure prophylaxis for immunocompromised elderly. Hospital-based procurement concentrates in tertiary referral centers with infectious disease specialization.
Children constitute the dominant volume segment, with Adolescents showing the steepest expansion trajectory as catch-up programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified regulatory affairs specialists concentrate in European and Indian manufacturing hubs, anchoring WHO prequalification capacity for vaccine release. This talent distribution shapes where lot-release testing and stability validation clusters geographically.
United States
FDA governs lot-release protocols for measles vaccines distributed through domestic immunization programs. The agency's Center for Biologics Evaluation and Research maintains stringent post-marketing surveillance requirements. Maryland-based regulatory consultants support manufacturers navigating accelerated approval pathways for combination presentations.
India
CDSCO oversees domestic licensing while WHO-prequalified facilities in Pune and Hyderabad supply Gavi-eligible markets. Serum Institute of India anchors global volume through WHO-prequalified campuses. The country's PLI scheme for pharmaceuticals incentivizes fill-finish capacity expansion for export commitments.
Germany
EMA's centralized marketing authorization procedure governs measles vaccine distribution across EU member states. REACH-aligned F-Gas Regulation mandates non-HFC refrigerant transitions for cold-chain transport. Bavaria hosts specialized lyophilization contract manufacturers serving heat-stable formulation demand.
Brazil
ANVISA regulates vaccine importation and lot release for national immunization program procurement. Adult catch-up campaigns in São Paulo and Rio de Janeiro drive intramuscular prefilled syringe preferences. The Ministry of Health splits tenders between imported MMR combinations and domestic fill-finish partnerships.
South Africa
WHO mRNA technology transfer hubs in Cape Town and Durban offer regional fill-finish capacity for supply security. The South African Health Products Regulatory Authority streamlines emergency use pathways during outbreak response. Local biomanufacturing clusters attract technology licensing agreements from platform developers.
Measles Market Competitive Landscape
Top-tier vendors anchor WHO-prequalified supply chains, while mid-tier regional manufacturers compete on price-point positioning for national tender awards. The vendor base stratifies across three capability tiers: multinational innovators with combination vaccine franchises, emerging market specialists with Gavi-anchored volume, and regional fill-finish operators serving domestic immunization programs. Two dominant competitive moves define current positioning: technology licensing agreements for mRNA platform transfer and lyophilization capacity investments for heat-stable presentations.
Among established multinational developers, Merck & Co., Inc. and GSK occupy positions representing long-standing MMR franchise holders with institutional contract penetration. Serum Institute of India Pvt. Ltd. exemplifies the emerging market specialist archetype, anchoring affordable volume through WHO-prequalified manufacturing campuses. These three entities collectively represent the competitive spectrum from premium combination presentations to commodity dose supply.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GSK |
| Serum Institute of India Pvt. Ltd. |
| Sanofi |
| Biological E. Limited |
| Sinovac Biotech |
| Indian Immunologicals Limited |
| Zydus Lifesciences Limited |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
mRNA platform transfer agreements and lyophilization capacity investments are simultaneously compressing production economics and redistributing manufacturing geography toward WHO technology hubs in South Africa and Senegal. This dual transition concentrates cost advantages among manufacturers with validated freeze-drying suites while fragmenting pricing power across regional fill-finish operators.
Pricing Analysis
Bundled cold-chain logistics and unbundled commodity dose procurement split tender awards between premium combination presentations and standalone measles vaccines. Three-tier pricing structure across WHO-prequalified, domestically licensed, and non-regulated economy tiers reflects certification grade and stability profile differentiation. Pricing pressure stems from Gavi alliance volume commitments favoring lowest-cost qualified suppliers. National immunization programs in sub-Saharan Africa exhibit highest price sensitivity, while private clinic procurement in Brazil and Mexico tolerates premium intramuscular prefilled syringe formats.
Supply Chain Analysis
Direct-to-government procurement channels handle national immunization program demand through UNICEF and PAHO consolidated tenders, while private distributor networks serve clinic and hospital pharmacy segments. Manufacturing concentrates in India, Germany, and South Korea for WHO-prequalified bulk drug substance and fill-finish capacity. Bovine serum albumin, human albumin, and specialized cell culture media constitute critical raw material dependencies. Single-source vulnerability in lyophilization equipment manufacturing creates bottleneck risk for heat-stable formulation production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The measles market functions as a stable compounder anchored by Gavi alliance procurement commitments that sustain predictable volume flows regardless of economic cycles.
For Market Incumbents: Acquire lyophilization capacity and qualified regulatory affairs expertise to defend against emerging market specialists capturing WHO prequalification share. Serum Institute of India's volume dominance and technology hub licensing in South Africa threaten traditional MMR franchise holders. Backward integration into cell culture media production mitigates serum protein supply bottlenecks from South American and Oceanian suppliers. For New Entrants and Emerging Players: EU Green Deal F-Gas Regulation phase-downs in Germany and REACH-aligned jurisdictions open a window for non-HFC refrigerant infrastructure specialists to capture cold-chain logistics premiums. White-space targets include microarray patch delivery platforms for last-mile distribution in rural Indonesia and Nigeria, and adult catch-up segmentation in Brazil and Mexico. Go-to-market through technology hub licensing agreements with WHO mRNA transfer facilities in Senegal and South Africa accelerates regional procurement eligibility. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fill-finish operators with WHO prequalification pathways but limited lyophilization capacity. Long-term viability hinges on 5-10 year immunization program commitments from Gavi alliance and national government procurement bodies. Signal to watch: technology hub licensing announcements from platform developers that redistribute manufacturing geography and compress incumbent margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Heat-stable formulations meeting UNICEF 40°C thresholds capture tropical climate procurement. |
| WHO mRNA Technology Hub Licensing | South African and Senegalese fill-finish partnerships enable regional supply security commitments. |
| Non-HFC Cold-Chain Infrastructure Investment | REACH-aligned refrigerant transitions satisfy EU Green Deal mandates for last-mile distribution. |
| Microarray Patch Delivery Development | Dissolvable microneedle arrays eliminate cold-chain requirements for community health worker deployment. |
| Adult Catch-Up SKU Differentiation | Intramuscular prefilled syringe formats capture healthcare worker and traveler immunization premiums in Brazil. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vaccine manufacturing executives, regulatory affairs specialists at WHO-prequalified facilities, national immunization program managers, and cold-chain logistics operators with secondary validation against FDA filings, EMA centralized procedure submissions, UNICEF procurement databases, and Gavi alliance commitment documents. Bottom-up volume modeling and top-down value triangulation anchored forecast outputs.
Segment-weighting approaches distributed value across product type, delivery mode, end user, and age group dimensions, with regional regulatory clusters and cold-chain capability tiers as cross-cutting analytical layers. CAGRs were derived from trend extrapolation of procurement volume commitments and price point trajectories across the projection horizon. Industry-specific inputs included WHO prequalification timeline data, lyophilization capacity utilization rates, and F-Gas Regulation compliance cost curves.
Revisions become necessary when mRNA platform transfer agreements accelerate, WHO prequalification standards shift, or conflict-affected regions disrupt seroconversion surveillance infrastructure. Forecasts reflect documented assumptions about Gavi alliance funding continuity and national routine immunization program scale-up trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Hepatitis C Market