
 Middle East Ultrasound Devices Market | 2026-2036
Middle East Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Ultrasound Devices Market Foresight
MOHAP's updated medical device technical standards for the UAE is decoupling procurement from legacy 2D-only platforms. GE Healthcare leverages its installed base across Saudi tertiary hospitals to sustain service revenue streams. Koninklijke Philips anchors its regional position through specialized cardiology ultrasound configurations. Siemens Healthineers differentiates via AI-integrated elastography systems that comply with emerging Gulf Cooperation Council harmonization frameworks.
Middle East ultrasound devices are electromechanical imaging systems operating at frequencies between 2 and 18 MHz, utilizing piezoelectric transducers to generate real-time anatomical visualizations for diagnostic and interventional guidance. Cart-based systems dominate hospital procurement budgets across the Gulf states due to superior thermal management and multi-probe connectivity for abdominal and obstetric workflows. Portable segments are capturing expanded share in home care and rural clinic deployments where power infrastructure constraints limit full-size system adoption. Doppler technology leads revenue contribution in cardiology applications, while 3D imaging commands premium positioning in maternal-fetal medicine suites.
SFDA in Saudi Arabia, MOHAP in the UAE, and the country's national pharmaceutical regulator in Qatar enforce divergent registration pathways that fragment market access timelines for new device submissions. CE marking under EU MDR serves as a de facto quality benchmark that Gulf procurement committees reference during tender evaluations, creating a regulatory hierarchy favoring manufacturers with prior European clearance. Stakeholders must monitor harmonization progress across Gulf Cooperation Council technical committees to anticipate consolidated conformity requirements that would reshape competitive entry barriers.
Market Dynamics
MOHAP's technical standards decoupling procurement from legacy 2D-only platforms is compressing replacement cycles across UAE hospital networks. This regulatory pivot is accelerating capital redeployment toward AI-integrated elastography and 3D imaging configurations that satisfy updated Gulf Cooperation Council harmonization frameworks.
Growth Catalysts
- SFDA Registration Pathway Modernization:Saudi Arabia's streamlined device approval timelines are reducing market entry barriers for Doppler-equipped cart-based systems targeting cardiology departments.
- Obstetric Workflow Digitization:Maternal-fetal medicine suites across Qatar and Kuwait are prioritizing 3D imaging platforms with automated biometric measurement capabilities.
- Rural Electrification Programs:Grid stabilization investments in Oman and Jordan are enabling portable ultrasound deployment to previously power-constrained clinic networks.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Transducer manufacturing depends on rare-earth element processing concentrated in East Asian supply chains, exposing procurement to geopolitical disruption.
- Divergent Registration Pathways:SFDA, MOHAP, and Qatar's national pharmaceutical regulator maintain non-harmonized technical documentation requirements that fragment submission timelines.
- Trained Sonographer Scarcity:Interpretive expertise for elastography and advanced Doppler modes remains concentrated in tertiary hospital clusters across Riyadh and Dubai.
Strategic Opportunities
- Home Care Channel Expansion:Portable system vendors can capture unmet demand in Saudi Arabia's remote northern provinces where hospital density remains below Gulf averages.
- AI-Augmented Workflow Convergence:Integration of real-time image optimization algorithms with cloud-based PACS architectures creates differentiation in high-volume screening programs.
- GCC Harmonization Tailwind:Pending unified technical standards across Gulf Cooperation Council jurisdictions would consolidate conformity assessment costs for multi-country tenders.
Industry Challenges
- CE Marking Dependency:Gulf procurement committees reference EU MDR clearance as a de facto quality benchmark, forcing manufacturers to maintain parallel European regulatory infrastructure regardless of regional sales concentration.
- Legacy System Integration Friction:Hospital IT departments in established Saudi tertiary networks face complexity when bridging new AI-enabled platforms to decade-old PACS architectures.
- Service Technician Certification Bottlenecks:Manufacturer-authorized training programs for probe calibration and thermal management maintenance are not scaling to match installed base growth rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Ultrasound Devices Market |
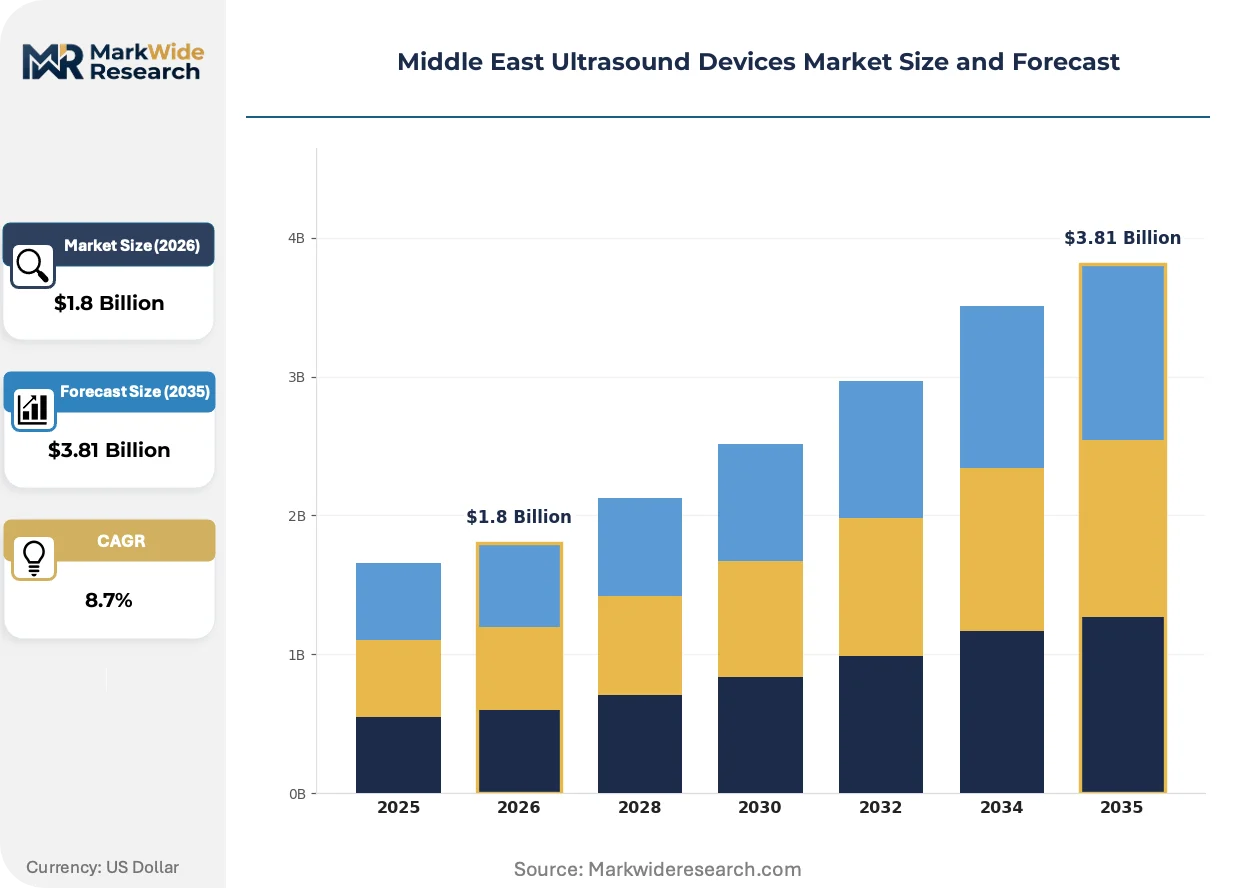
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Portable, Handheld, Tabletop, Cart-based End User: Hospitals, Clinics, Diagnostic Centers, Home Care Technology: 2D, 3D, Doppler, Elastography Application: Obstetrics, Cardiology, Abdominal, Musculoskeletal |
| Companies Covered | GE Healthcare, Koninklijke Philips, Siemens Healthineers, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd, Samsung Electronics Co., Ltd, Hitachi, Ltd., Esaote SpA, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Ultrasound Devices Market Shifts & Advancements
AI-integrated elastography is compressing diagnostic timelines across cardiology and hepatology workflows. Three convergent developments are restructuring competitive positioning: computational imaging unification, regulatory harmonization acceleration, and procurement model evolution toward managed equipment services.
Shear wave elastography is unifying tissue stiffness quantification with conventional B-mode imaging in single acquisition sequences. Cardiology departments at tertiary hospitals in Dubai and Riyadh are adopting these systems at replacement-cycle pace rather than waiting for full depreciation. This technology is unifying previously separate diagnostic steps, compressing examination duration and reducing sonographer time per patient.
Gulf Cooperation Council technical committees are advancing framework harmonization that would consolidate SFDA, MOHAP, and Qatar regulatory requirements into unified conformity pathways. This industrial consequence reduces submission documentation duplication for manufacturers targeting multi-country hospital procurement. Cart-based system categories with existing European CE marking under EU MDR are best positioned to leverage transitional recognition mechanisms during implementation.
Managed equipment service contracts are displacing traditional capital purchase models in UAE and Saudi hospital networks. Group purchasing organizations are consolidating device selection authority and bundling maintenance, training, and upgrade rights into multi-year agreements. This shift is most visible in Dubai's health authority networks, where total-cost-of-ownership metrics now dominate tender evaluation over upfront acquisition price.
Middle East Ultrasound Devices Market Segmentation
Ultrasound device procurement across the Middle East fragments across four distinct dimensions, each carrying divergent margin profiles and regulatory exposure. Understanding these fault lines reveals where capital deployment concentrates and where replacement cycles compress.
Device Type:
Capital intensity peaks with cart-based configurations requiring dedicated electrical infrastructure and climate-controlled installation bays, while portable variants demand far lower upfront commitment.
- Cart-based:Full-size systems integrate multi-probe switching, advanced thermal management, and dedicated GPU arrays for real-time 3D rendering. Saudi tertiary hospitals in Riyadh and Jeddah anchor procurement volume, driven by SFDA-mandated technical standards that disqualify legacy platforms from new tenders.
- Portable:Battery-powered units with simplified probe interfaces target deployment scenarios with unreliable grid access. Rural electrification programs across Oman's interior provinces and Jordan's northern governorates are unlocking demand previously constrained by power infrastructure gaps.
- Handheld:Smartphone-tethered probes prioritize extreme mobility for point-of-care triage in emergency departments.
- Tabletop:Mid-size fixed installations balance imaging depth with spatial footprint constraints in smaller clinic settings.
Most installed capacity flows through cart-based systems. Expansion is steepest in portable configurations.
End User:
Procurement authority concentrates differently across customer types, with hospitals wielding consolidated tender power while home care channels fragment across distributed purchasing decisions.
- Hospitals:Multi-departmental acquisition committees evaluate total-cost-of-ownership metrics over five-to-seven-year depreciation horizons. UAE health authority networks in Dubai and Abu Dhabi are shifting toward managed equipment service contracts that bundle devices, maintenance, and training.
- Diagnostic Centers:Specialized imaging facilities prioritize throughput-optimized workflows with automated measurement protocols. Qatar's expanding private diagnostic chains are standardizing on Doppler-equipped platforms for cardiac stress testing volumes.
- Clinics:Smaller patient volumes drive preference for tabletop systems with reduced service contract dependencies.
- Home Care:Post-acute monitoring applications in Saudi Arabia's remote northern provinces are emerging as a deployment frontier for portable Doppler systems.
Procurement volume concentrates in hospital networks. The steepest adoption trajectory is appearing in home care channels.
Technology:
Technical sophistication tiers separate premium positioning from commodity procurement, with AI-augmented modalities commanding substantial price premiums over conventional imaging.
- Doppler:Frequency-shift detection enables hemodynamic assessment and cardiac valve evaluation. Cardiology departments across Kuwait's specialized cardiac centers are replacing 2D-only platforms at accelerated depreciation schedules to capture flow quantification capabilities.
- Elastography:Shear wave propagation measurement quantifies tissue stiffness for liver fibrosis staging and lesion characterization. Tertiary hepatology units in Dubai are adopting these systems as standard-of-care for chronic liver disease monitoring.
- 3D:Volume reconstruction from sequential 2D slices supports maternal-fetal medicine applications with automated biometric extraction.
- 2D:Conventional B-mode imaging persists in budget-constrained procurement but faces exclusion from updated MOHAP technical specifications.
Revenue contribution concentrates in Doppler-equipped systems. Elastography is climbing the fastest as a share of new capital deployment.
Application:
Clinical workflow requirements dictate divergent probe configurations and software licensing structures, with obstetrics and cardiology commanding distinct premium tiers.
- Obstetrics:Maternal-fetal medicine suites require specialized curved-array probes and automated biometric measurement packages. 3D imaging platforms with nuchal translucency calculation algorithms are becoming standard in Qatar's premium private maternity hospitals.
- Cardiology:Phased-array probes and continuous-wave Doppler capabilities support transesophageal and transthoracic echocardiography protocols. Saudi Arabia's expanding cardiac surgery centers are driving concentrated demand for high-frame-rate systems.
- Abdominal:General-purpose convex probes serve multi-organ screening applications across emergency department triage workflows.
- Musculoskeletal:High-frequency linear probes enable superficial tissue and joint evaluation in sports medicine and rheumatology practices.
Procedure volume concentrates in obstetrics applications. Cardiology is expanding most quickly as a share of technology-specific procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trained sonographers and biomedical engineers concentrate in Riyadh, Dubai, and Doha, anchoring regional procurement sophistication and driving technology adoption curves across tertiary hospital networks.
Saudi Arabia
Cardiac surgery center expansion and maternal-fetal medicine digitization propel cart-based system demand. SFDA registration pathway modernization compresses approval timelines for Doppler-equipped platforms. Riyadh and Jeddah tertiary clusters are replacing legacy 2D systems at accelerated depreciation schedules.
United Arab Emirates
Dubai Health Authority networks are shifting procurement toward managed equipment service contracts with bundled maintenance terms. MOHAP technical standards now exclude 2D-only platforms from new hospital tenders. Abu Dhabi's Sheikh Khalifa Medical City anchors premium 3D imaging deployment for obstetrics workflows.
Qatar
Private diagnostic chain expansion and premium maternity hospital construction drive specialized ultrasound configuration demand. The national pharmaceutical regulator maintains distinct technical documentation requirements that fragment submission timelines. Doha's Hamad Medical City cluster standardizes on automated biometric measurement platforms.
Kuwait
Specialized cardiac center investments and cardiology department upgrades prioritize phased-array probe systems. Grid stabilization programs enable consistent power supply for high-frame-rate imaging equipment. Kuwait City's specialized cardiac institutes are deploying continuous-wave Doppler capabilities for stress testing volumes.
Oman
Rural electrification investments unlock portable ultrasound deployment to previously power-constrained interior provinces. Remote clinic network expansion creates demand for battery-powered units with simplified probe interfaces. Muscat's tertiary referral hospitals coordinate procurement for satellite clinic equipment standards.
Middle East Ultrasound Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology integration strategies. The vendor base consolidates around three tiers: integrated imaging conglomerates with full modality portfolios, specialized ultrasound pure-plays with probe manufacturing expertise, and diversified electronics manufacturers leveraging component scale. Dominant competitive moves include AI algorithm licensing partnerships and managed equipment service contract bundling that displaces traditional capital purchase models.
Among integrated imaging conglomerates, GE Healthcare and Koninklijke Philips exemplify the full-modality archetype with established installed bases across Saudi tertiary networks. Siemens Healthineers occupies a differentiated position through elastography system specialization. Shenzhen Mindray Bio-Medical Electronics Co., Ltd represents the emerging market challenger archetype with cost-optimized portable configurations targeting rural electrification frontiers.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd |
| Samsung Electronics Co., Ltd |
| Hitachi, Ltd. |
| Esaote SpA |
| Others |
Supply & Pricing Matrix
AI-integrated elastography manufacturing is compressing production economics while concentrating probe component sourcing among East Asian rare-earth processors, simultaneously elevating R&D amortization burdens and tightening vendor bargaining power across Gulf procurement committees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies according to CE marking tier and after-sales service bundling intensity. Price differentiation stems from Gulf Cooperation Council harmonization compliance costs and volume scale in multi-hospital tenders. Margins are tightening due to managed equipment service contract proliferation in Dubai Health Authority networks. Diagnostic centers exhibit highest price sensitivity; tertiary cardiology departments show lowest.
Supply Chain Analysis
Direct-to-hospital channels handle bulk procurement from Saudi tertiary networks while distributor-mediated routes serve Oman's rural clinic expansion. Transducer manufacturing draws from China, Japan, and South Korea for piezoelectric crystal processing. Rare-earth element concentration in East Asian supply chains creates single-source vulnerability. Distribution runs through manufacturer-authorized service partnerships with thermal management certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-augmented workflow bundles where software licensing economics outpace hardware depreciation curves.
For Market Incumbents: Acquire probe calibration and thermal management service capabilities to defend against Shenzhen Mindray Bio-Medical Electronics Co., Ltd's cost-optimized portable configurations. Build backward integration into rare-earth element sourcing to mitigate East Asian supply concentration. Secure MOHAP pre-approval status for 3D imaging platforms ahead of unified Gulf Cooperation Council technical standards. For New Entrants and Emerging Players: Begin with handheld and portable segments in Saudi Arabia's remote northern provinces where hospital density sits below Gulf averages. Target home care channels for post-acute Doppler monitoring applications. Pursue group purchasing organization partnership routes rather than direct hospital sales. For Investors and Strategic Acquirers: Valuations sit cheapest among ultrasound pure-plays with probe manufacturing expertise but limited AI algorithm portfolios. Five-to-ten year viability hinges on elastography system adoption curves in tertiary hepatology units. Monitor SFDA registration pathway modernization velocity as inflection signal for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Gulf procurement committees reference EU MDR clearance as de facto quality benchmark for tender eligibility. |
| Hospital System Partnership | Managed equipment service contracts in Dubai Health Authority networks displace traditional capital purchase models. |
| Software Companion Development | Real-time image optimization algorithms integrated with cloud-based PACS architectures create differentiation in screening programs. |
| Reimbursement Strategy | National health insurance frameworks in Saudi Arabia and UAE increasingly influence device selection criteria. |
| Probe Manufacturing Scale-Up | Vertical control over piezoelectric transducer production reduces exposure to East Asian rare-earth supply volatility. |
Research Methodology
Multiple input streams — hospital procurement database analysis, Gulf Cooperation Council regulatory filing review, and biomedical engineer interview programs — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged hospital purchasing committees, GPO contracts managers, SFDA registration specialists, and tertiary cardiology department heads. Secondary validation drew from MOHAP technical standards documentation, SFDA device approval records, and EU MDR conformity assessment databases. Bottom-up installed base enumeration and top-down healthcare expenditure allocation were triangulated.
Data-stream reconciliation across device type, end user, technology, and application dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from replacement cycle compression rates and rural electrification program timelines. Modeled inputs included SFDA registration pathway modernization velocity, MOHAP technical specification update schedules, and managed equipment service contract penetration rates.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare-earth supply chains and divergence from anticipated Gulf Cooperation Council harmonization timelines. Forecasts reflect assumptions regarding grid stabilization investment continuity and sonographer training program scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implant Handpiece Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Pathology Devices Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Memory Implants Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Endoscope Reprocessing Device Market