
 Global Intravenous Infusion Pump Market | 2026-2036
Global Intravenous Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intravenous Infusion Pump Market Foresight
Software-defined dosing algorithms and remote monitoring subscriptions is expanding what hospitals purchase beyond hardware alone. Becton, Dickinson and Company leverages its installed base to sustain recurring revenue from connectivity modules. Fresenius Kabi AG anchors its position through specialization in infusion therapy systems for critical care environments. Baxter competes by extending service contracts that bundle preventive maintenance with regulatory compliance support.
An intravenous infusion pump is an electromechanical medical device that delivers fluids, medications, or nutrients into a patient's circulatory system through an intravenous route with programmable flow rates ranging from 0.1 to 999 milliliters per hour and pressure sensing capabilities to detect occlusions. Its primary purpose is to ensure precise, controlled administration of therapeutic agents in clinical settings where manual flow regulation would risk dosage errors. Volumetric infusion pumps occupy the largest share of product type demand due to their versatility across high-acuity hospital departments, while ambulatory pumps represent the fastest-expanding category as home healthcare protocols gain reimbursement traction. Smart pump technology with dose error reduction software commands premium positioning and captures disproportionate margin pools relative to conventional microprocessor-controlled alternatives.
The FDA enforces 510(k) premarket notification requirements that shape device design standards and clinical validation protocols for infusion pump manufacturers seeking US market access. The EU Medical Device Regulation mandates stricter post-market surveillance and clinical evidence thresholds, compelling redesign cycles that favor established players with dedicated regulatory affairs infrastructure. China's NMPA accelerates review pathways for domestically manufactured Class III devices, altering competitive dynamics for multinational entrants. Stakeholders must monitor how divergent cybersecurity requirements across FDA, EMA, and NMPA jurisdictions reshape development roadmaps and regional product configurations.
Market Dynamics
Software-defined dosing algorithms and wireless connectivity modules are compressing hardware replacement cycles while expanding recurring revenue streams beyond device sales into subscription-based monitoring services.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter post-market surveillance mandates accelerate hospital upgrades to smart pump platforms with integrated dose error reduction systems.
- Ambulatory care expansion:Home healthcare reimbursement protocols in Germany and Japan are displacing stationary hospital administration with portable infusion systems.
- China's NMPA accelerated review pathways:Domestic Class III device approvals compress time-to-market for locally manufactured pumps serving tier-two hospital networks.
Market Restraints
- Semiconductor supply concentration:Microcontroller sourcing dependencies in Taiwan create production volatility for precision flow control systems.
- FDA 510(k) clinical validation requirements:Pre-market notification timelines extend 12-18 months for novel connectivity features, favoring incumbents with established regulatory infrastructure.
- Manual infusion alternatives:Gravity drip systems retain cost advantage in low-acuity settings across India and Southeast Asia, limiting premium pump penetration.
Strategic Opportunities
- Brazil's ANVISA harmonization with IMDRF:Streamlined conformity assessment pathways reduce entry barriers for multinational manufacturers in Latin America's largest hospital market.
- Oncology infusion protocol standardization:Chemotherapy administration guidelines in France and Australia are creating demand for multi-channel pumps with bi-directional EMR integration.
- Remote patient monitoring convergence:Telehealth platform integration with ambulatory pumps enables real-time adherence tracking for home-based parenteral nutrition patients.
Industry Challenges
- Cybersecurity engineering talent scarcity:FDA's 2023 guidance on premarket cybersecurity submissions requires specialized firmware validation expertise that outpaces available workforce supply.
- Legacy EMR integration complexity:Hospital information system heterogeneity forces pump manufacturers to maintain multiple HL7 interface configurations, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intravenous Infusion Pump Market |
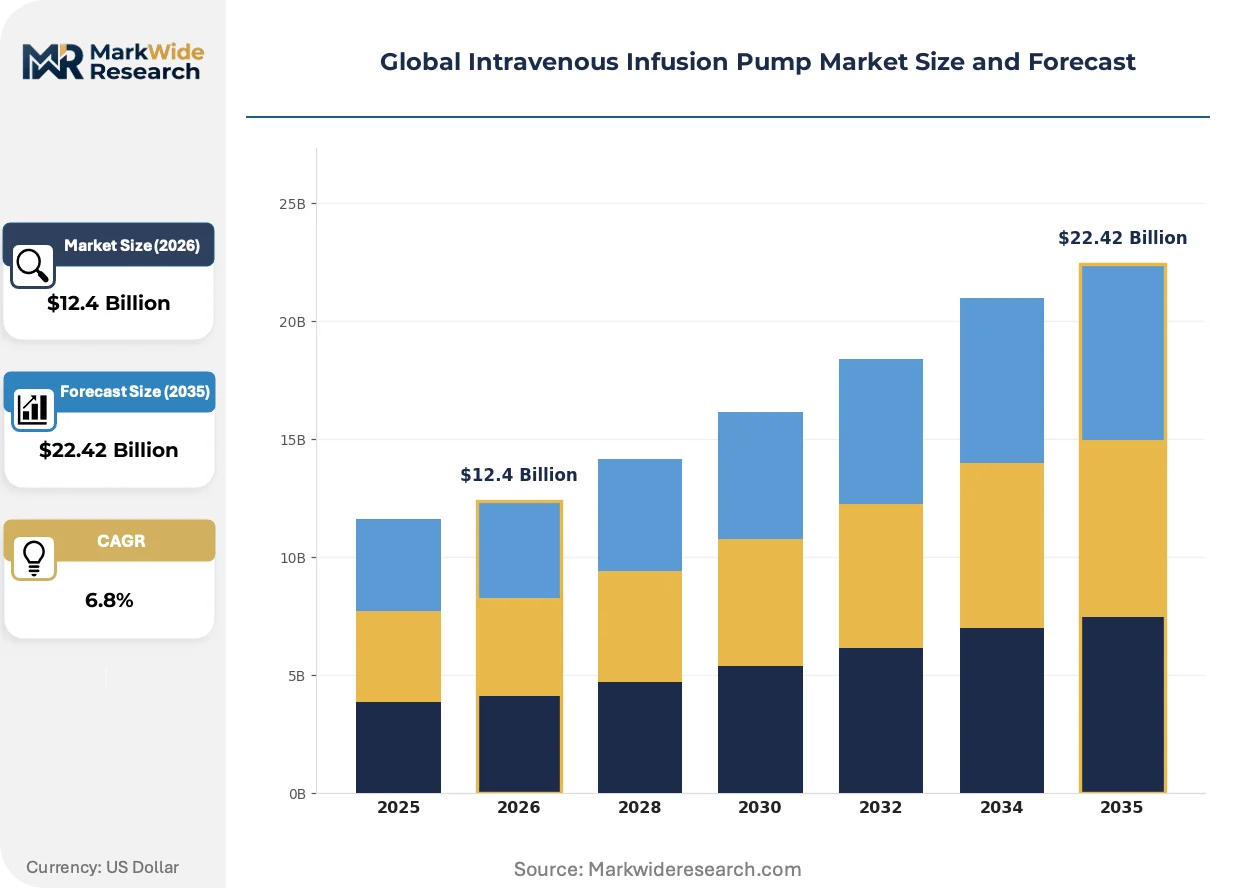
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric Infusion Pumps, Syringe Pumps, Ambulatory Pumps, Elastomeric Pumps, PCA Pumps Therapy Area: Oncology, Critical Care, Anesthesia, Pediatrics, General Surgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Home Healthcare Providers, Rehabilitation Centers Technology: Smart Pumps, Wireless Connectivity, Microprocessor-Controlled, Battery Operated, Alarm Systems |
| Companies Covered | Becton, Dickinson and Company, Baxter, B. Braun Melsungen AG, ICU Medical, Inc., Fresenius Kabi AG, Medtronic, Terumo Corporation, Smiths Medical, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intravenous Infusion Pump Market Shifts & Advancements
Algorithmic control systems and cloud-connected device architectures are displacing standalone electromechanical platforms, redistributing value capture toward software and data services across acute and ambulatory care settings.
Closed-loop infusion systems with physiologic sensor feedback are electrifying anesthesia and intensive care workflows by automating titration responses to patient vital signs. Academic medical centers in the United States and Switzerland are piloting these platforms for insulin and vasopressor delivery. The technology is compressing nursing labor allocation per infusion episode while elevating liability exposure for algorithmic decision failures.
China's NMPA cybersecurity technical review guidelines for connected medical devices mandate encryption protocols and vulnerability disclosure procedures that reshape firmware development roadmaps. Domestic manufacturers in Shenzhen and Beijing are accelerating compliance investments to capture tier-three hospital procurement tenders. Multinational entrants face parallel certification requirements that extend product localization timelines by 8-12 months.
Hospital purchasing consortia in the United Kingdom and Netherlands are unbundling preventive maintenance contracts from device acquisition, forcing pump manufacturers to compete on service pricing transparency. Third-party ISO 13485-certified service providers are capturing 15-20% of installed base maintenance volumes. This disintermediation is most pronounced in National Health Service supply frameworks where total cost of ownership metrics dominate vendor selection.
Global Intravenous Infusion Pump Market Segmentation
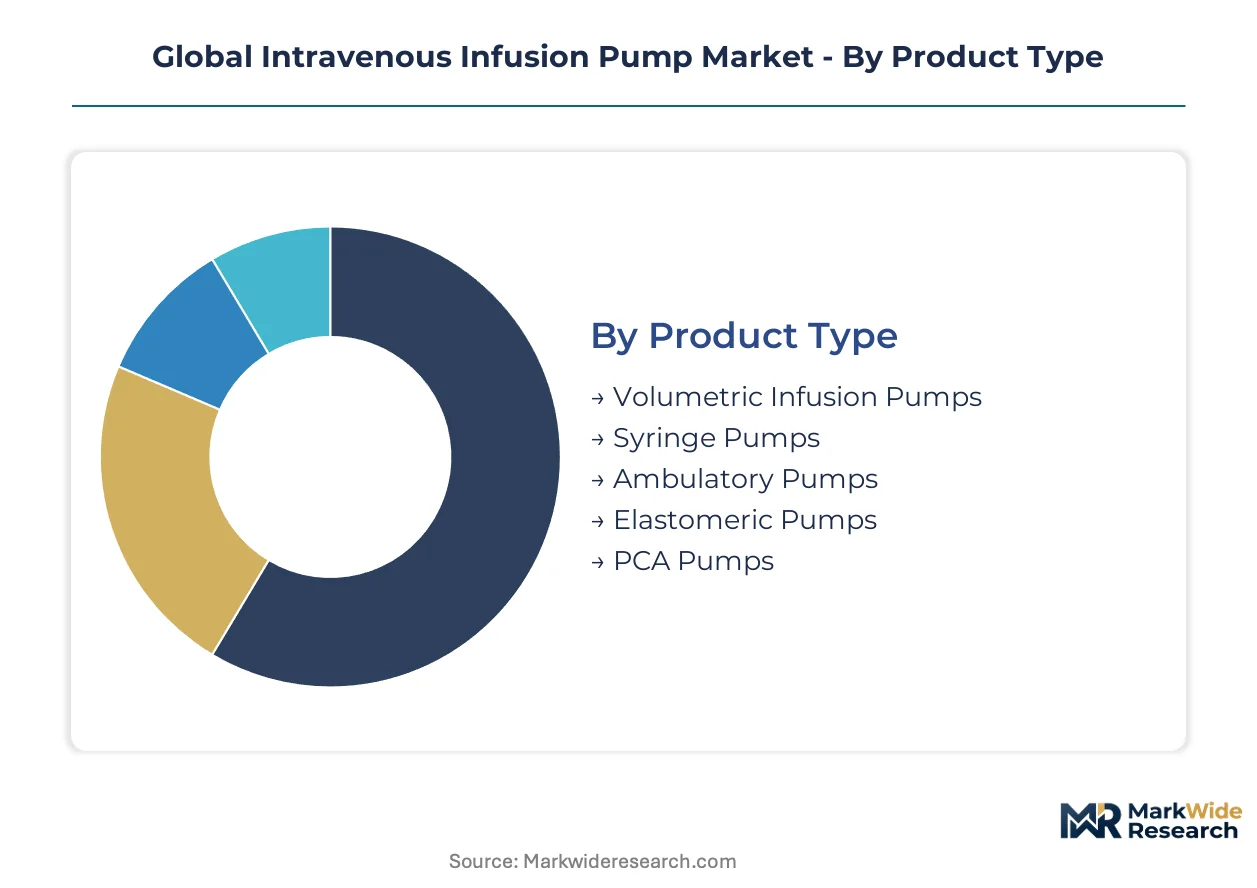
Infusion pump segmentation reflects divergent clinical workflows across acute and ambulatory settings. Product architecture and connectivity requirements vary sharply between high-acuity hospital departments and decentralized home care environments.
Product Type:
Standalone electromechanical units dominate surgical suites, while portable platforms embed into patient mobility protocols outside hospital walls.
- Volumetric Infusion Pumps:These large-volume devices deliver fluids from 1 to 999 milliliters per hour through peristaltic or cassette-based mechanisms. Demand concentrates in United States academic medical centers and German tertiary hospitals where multi-channel configurations support simultaneous medication delivery. FDA 510(k) premarket notification requirements for software updates extend replacement cycles for this category.
- Ambulatory Pumps:Battery-powered wearable units weighing under 500 grams enable continuous infusion during patient mobility. Home healthcare reimbursement protocols in Japan and Germany are accelerating placement volumes for parenteral nutrition and chemotherapy administration outside institutional settings.
- Syringe Pumps:Precision devices for low-volume, high-accuracy delivery in neonatal and anesthesia applications.
- Elastomeric Pumps:Disposable balloon reservoirs for single-use chemotherapy and antibiotic infusion in outpatient settings.
- PCA Pumps:Patient-controlled analgesia systems with programmed lockout intervals for post-operative pain management.
Volume placements concentrate in Volumetric Infusion Pumps; the faster expansion belongs to Ambulatory Pumps.
Therapy Area:
Clinical specialization dictates pump specification requirements across therapeutic domains.
- Oncology:Multi-channel smart pumps with dose error reduction software support complex chemotherapy protocols requiring sequential drug administration. France and Australia have issued standardized infusion guidelines that mandate bi-directional EMR integration for this segment.
- Critical Care:Closed-loop systems with physiologic sensor feedback automate vasopressor and insulin titration in intensive care units. Academic medical centers in Switzerland and the United States are piloting these platforms to compress nursing labor allocation.
- Anesthesia:Syringe pumps with pharmacokinetic modeling for target-controlled infusion during surgical procedures.
- Pediatrics:Micro-volume delivery systems with flow rates as low as 0.1 milliliters per hour for neonatal patients.
- General Surgery:Standard infusion platforms for perioperative fluid and antibiotic administration.
Critical Care generates the highest average selling prices; Oncology is climbing the fastest on protocol standardization.
End User:
Procurement authority and reimbursement pathways segment demand across institutional hierarchies.
- Hospitals:Centralized purchasing departments negotiate enterprise-wide contracts covering smart pump fleets with connectivity modules. China's tier-two hospital networks are expanding procurement volumes as NMPA accelerates Class III device review pathways for domestic manufacturers.
- Home Healthcare Providers:Specialized agencies managing reimbursement claims for portable infusion systems under Germany's statutory health insurance and Japan's long-term care insurance. Remote patient monitoring convergence is creating subscription revenue opportunities for device vendors.
- Ambulatory Surgery Centers:Cost-sensitive facilities prioritizing single-channel pumps with simplified user interfaces.
- Specialty Clinics:Oncology and pain management centers with therapy-specific equipment requirements.
- Rehabilitation Centers:Post-acute facilities transitioning patients from hospital-based to home-based infusion.
Hospital procurement maintains volume leadership; Home Healthcare Providers show the steepest expansion trajectory on reimbursement traction.
Technology:
Software and connectivity layers are redistributing value capture from hardware toward data services.
- Smart Pumps:Dose error reduction software with drug libraries and clinical decision support commands premium positioning. EU MDR post-market surveillance mandates are accelerating hospital upgrades to these platforms across German and United Kingdom facilities.
- Wireless Connectivity:Wi-Fi and cellular modules enabling remote monitoring, automatic documentation, and predictive maintenance subscriptions. NMPA cybersecurity technical review guidelines for connected devices are reshaping firmware development roadmaps for manufacturers targeting China.
- Microprocessor-Controlled:Conventional platforms with basic flow rate programming without network integration.
- Battery Operated:Power systems enabling ambulatory and transport applications.
- Alarm Systems:Occlusion, air-in-line, and end-of-infusion detection with configurable alert thresholds.
Smart Pumps dominate margin pools; Wireless Connectivity is gaining share fastest on recurring revenue model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China and Germany while consumption spreads across hospital networks in the United States, Japan, and Western Europe. Domestic manufacturers in Shenzhen and Beijing scale output for ambulatory pumps as foreign multinationals retain premium smart pump positions in tertiary care markets.
United States
FDA 510(k) premarket notification requirements extend 12-18 month timelines for connectivity-enabled devices, entrenching incumbents with established regulatory infrastructure. Academic medical centers in Boston and the Research Triangle pilot closed-loop infusion systems for insulin and vasopressor delivery. Hospital purchasing consortia unbundle preventive maintenance from device acquisition, forcing service pricing transparency.
Germany
EU Medical Device Regulation post-market surveillance mandates accelerate hospital upgrades to smart pump platforms with dose error reduction software. Statutory health insurance reimbursement protocols expand home healthcare placements for portable infusion systems. Industrial clusters in Baden-Württemberg host precision flow control component suppliers serving domestic and export pump manufacturers.
China
NMPA accelerates Class III device review pathways for domestically manufactured pumps, compressing time-to-market for tier-two hospital networks. Cybersecurity technical review guidelines for connected devices mandate encryption protocols reshaping firmware development. Shenzhen and Beijing manufacturers expand production capacity for ambulatory and home healthcare segments.
Japan
METI long-term care insurance frameworks reimburse portable infusion systems for home-based parenteral nutrition patients. PMDA regulatory harmonization with IMDRF standards streamlines conformity assessment for multinational entrants. Tokyo and Osaka metropolitan hospitals concentrate demand for multi-channel smart pumps with bi-directional EMR integration.
Brazil
ANVISA harmonization with IMDRF reduces entry barriers for multinational manufacturers in Latin America's largest hospital market. Manual gravity drip systems retain cost advantage in low-acuity settings, limiting premium pump penetration outside tertiary centers. São Paulo and Rio de Janeiro anchor procurement volumes for surgical suite volumetric pumps.
Global Intravenous Infusion Pump Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the infusion pump value chain. Established medical technology conglomerates with dedicated regulatory affairs infrastructure dominate premium smart pump segments, while specialized component fabricators supply precision flow control systems. Three archetypes prevail: diversified multinationals leveraging installed bases for recurring connectivity revenue, regional champions capturing domestic procurement tenders through regulatory proximity, and contract manufacturers scaling ambulatory pump output for private-label distributors. Consolidation pressure intensifies through service contract bundling and third-party maintenance disintermediation.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Baxter occupy positions exemplifying the installed-base monetization archetype, converting hardware placements into recurring revenue streams through connectivity modules and preventive maintenance subscriptions. Fresenius Kabi AG represents the specialized infusion therapy focus, anchoring critical care system demand through therapy-specific platform development. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies the domestic regulatory acceleration archetype in China, leveraging NMPA pathway advantages to capture tier-two and tier-three hospital procurement volumes.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Baxter |
| B. Braun Melsungen AG |
| ICU Medical, Inc. |
| Fresenius Kabi AG |
| Medtronic |
| Terumo Corporation |
| Smiths Medical |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Microcontroller sourcing from Taiwan and South Korea feeds through three pricing tiers for precision flow control systems, with FDA 510(k) certification costs separating premium smart pump configurations from standard microprocessor-controlled alternatives in hospital procurement decisions.
Pricing Analysis
Cost-down pressure on standard volumetric pumps accelerates as Chinese domestic manufacturers expand tier-two hospital market share. Three-tier pricing structure across premium, standard, and economy levels reflects FDA cybersecurity validation burden, software subscription bundling, and regional service coverage depth. Semiconductor supply constraints prop pricing stability in premium smart pump segments where dose error reduction software commands recurring revenue premiums. Ambulatory pump buyers in home healthcare channels exhibit highest price sensitivity; academic medical centers purchasing closed-loop systems show lowest.
Supply Chain Analysis
ISO 13485 certification and FDA quality system regulation compliance gate entry for precision flow sensor and peristaltic mechanism suppliers concentrated in Germany, Switzerland, and Japan. Microcontroller supply draws from Taiwan semiconductor foundries; medical-grade polymer tubing sources from US and German specialty chemical producers; battery cell supply rests on South Korean and Japanese manufacturers. Single-source vulnerability concentrates in advanced flow sensor MEMS fabrication. Distribution runs through hospital GPO contracts, regional medical device distributors, and direct-to-provider service models for smart pump fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication capacity constraints for medical-grade microcontrollers prop pricing power in premium pump segments, with FDA cybersecurity engineering talent scarcity extending product development timelines and entrenching incumbent positions.
For Market Incumbents: Acquire cybersecurity firmware validation capabilities to defend against third-party service provider disintermediation of preventive maintenance contracts. Capture backward integration into precision flow sensor MEMS fabrication to reduce Taiwan foundry dependency. Consolidate service pricing transparency advantages as NHS and Dutch hospital consortia unbundle maintenance from device acquisition.
For New Entrants and Emerging Players: Capture Brazil's ANVISA-IMDRF harmonization window for streamlined multinational entry into Latin America's largest hospital market. Target China's tier-three hospital networks where NMPA accelerated review pathways favor domestic regulatory proximity. Lead with ambulatory pump subscription models bundling remote monitoring for home-based parenteral nutrition patients.
For Investors and Strategic Acquirers: NMPA cybersecurity technical review guideline publication is the leading indicator that Chinese domestic manufacturer compliance investments will accelerate tier-two and tier-three hospital procurement capture. Five-to-ten year viability frames around software-defined dosing algorithm platforms with recurring connectivity revenue streams. Target acquisition archetype: regional champions with established regulatory affairs infrastructure in underserved geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Premarket Submission | 510(k) pathway compliance enables US market access for connectivity-enabled smart pump platforms. |
| CE Marking Pathway Under EU MDR | Post-market surveillance mandates accelerate hospital upgrade cycles to dose error reduction systems. |
| Hospital System Partnership | Enterprise-wide fleet contracts with GPOs lock in preventive maintenance subscription revenue streams. |
| Software Companion Development | Remote monitoring applications for ambulatory pumps enable real-time adherence tracking subscriptions. |
| Reimbursement Strategy | Statutory health insurance protocol alignment in Germany and Japan drives home healthcare placement volume. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for triangulation with primary interviews across hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at infusion pump manufacturers. FDA 510(k) premarket notification databases, NMPA Class III device approval registries, EU MDR notified body certificates, and hospital procurement contract disclosures supplied segmentation validation. Bottom-up unit placement modeling and top-down therapy area spend analysis reconciled through cross-reference.
Data-stream reconciliation across volumetric, ambulatory, syringe, and elastomeric pump product types combined with therapy area segmentation in oncology, critical care, anesthesia, and pediatrics throughout the forecast period. CAGRs derived from installed base replacement cycle analysis, reimbursement protocol expansion trajectories, and connectivity module attach rate projections. Smart pump software subscription revenue and preventive maintenance contract pricing informed recurring revenue modeling.
The model holds under stable semiconductor supply conditions and continued FDA cybersecurity guidance enforcement; deviation in Taiwan foundry output or EU MDR implementation timelines would shift volume and value projections. Forecasts reflect assumptions around reimbursement expansion for home healthcare infusion and NMPA domestic manufacturer preference policies. A model refresh is warranted upon material change in FDA premarket review timelines or cybersecurity technical workforce availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Australia Medtech Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Vaginal Specula Market
Medical Devices
Mediastinoscope Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Biologic Injectors Market
Medical Devices
Small Bone and Joint Devices Market