
 Global Cell Analysis Instruments Market | 2026-2036
Global Cell Analysis Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Analysis Instruments Market Intelligence
Recurring revenue from proprietary reagents and consumables is tilting the profit pool away from one-time instrument sales. This shift favors companies with strong portfolios in both hardware and life science consumables. Thermo Fisher Scientific leverages its extensive reagent catalog to create a sticky ecosystem. Becton, Dickinson and Company sustains its market position through specialization in flow cytometry systems and associated assays.
Cell analysis instruments are automated systems designed for the quantitative and qualitative characterization of cells. These systems often integrate optical detection, such as fluorescence microscopy or laser-based scattering, to measure cellular properties at high throughput. Within product types, flow cytometers command a significant share due to their versatility in immunology and oncology research. Among end users, pharmaceutical companies and academic research institutes represent the primary buyers, driven by their need for high-content screening in drug discovery.
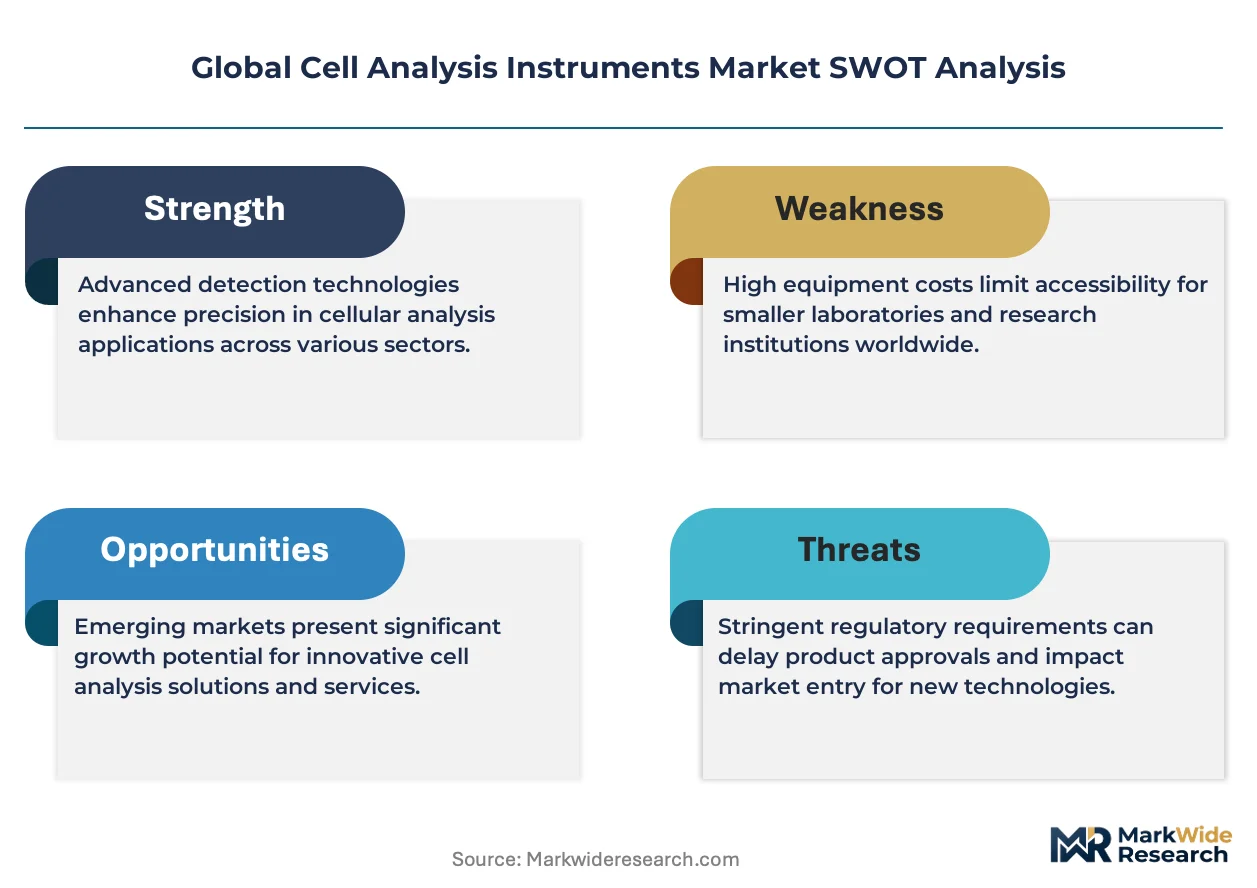
Regulatory frameworks for clinical diagnostics, overseen by bodies like the US FDA and the European Medicines Agency, influence instrument design and validation requirements. In China, NMPA standards for medical devices create specific market access hurdles for compliant manufacturers. Stakeholders must therefore navigate evolving in-vitro diagnostic regulations to ensure future product viability and market access.
Market Dynamics
The central dynamic shaping the cell analysis instruments market is the strategic pivot from one-time capital equipment sales to a recurring revenue model. This transition is driven by proprietary consumables and reagents, creating sticky ecosystems that favor established vendors with integrated hardware and life science portfolios.
Growth Catalysts
- Microfluidics Integration:Advances in microfluidic technologies are enabling the development of instruments with higher throughput and single-cell resolution, supporting complex applications in genomics and proteomics research.
- Pharmaceutical R&D Investment:Escalating investment in drug discovery and biologics development by large pharmaceutical companies drives sustained demand for high-content screening and flow cytometry systems for efficacy and toxicity testing.
- Government Life Science Initiatives:National policies, such as those promoting biotechnology hubs in China, are accelerating infrastructure development and creating concentrated pockets of demand for advanced cell analysis instrumentation in academic and research institutes.
Market Restraints
- High Capital Outlay:The substantial initial purchase price of sophisticated systems, such as high-content imaging platforms and multi-laser flow cytometers, remains a significant barrier for academic labs and small biotechnology firms with limited budgets.
- Proprietary Consumable Ecosystems:Vendor lock-in through proprietary reagents and software restricts user flexibility and can lead to high long-term operational costs, discouraging adoption by cost-sensitive end users.
- Complex Regulatory Pathways:Navigating disparate regulatory requirements for clinical diagnostic use, such as those from the US FDA, the European Medicines Agency, and China's NMPA, adds significant cost and time to product development and market entry.
Strategic Opportunities
- Expansion into Clinical Diagnostics:Adapting research-use-only instruments for in-vitro diagnostic (IVD) applications, particularly in oncology and immunology, opens a large, regulated market for validated, high-value systems and assays.
- AI and Machine Learning Integration:Incorporating artificial intelligence algorithms for automated image analysis and data interpretation can unlock deeper biological insights from complex datasets, creating significant value-add and product differentiation.
- Targeting Emerging Research Hubs:Expanding commercial and service operations in nascent life science clusters in countries like India and Brazil provides access to new customer bases before market saturation.
Industry Challenges
- Data Management and Analysis Bottlenecks:The massive datasets generated by high-throughput instruments create significant challenges in data storage, processing, and bioinformatics, requiring specialized infrastructure and expertise that many labs lack.
- Lack of Inter-Platform Standardization:The absence of universal standards for assays and data formats across different instrument platforms hinders the ability to compare and validate research findings, creating friction in collaborative projects.
- Specialized Talent Scarcity:Operating and maintaining advanced cell analysis systems, along with interpreting their complex outputs, demands highly trained personnel, and a shortage of such talent can limit instrument utilization and market growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Analysis Instruments Market |
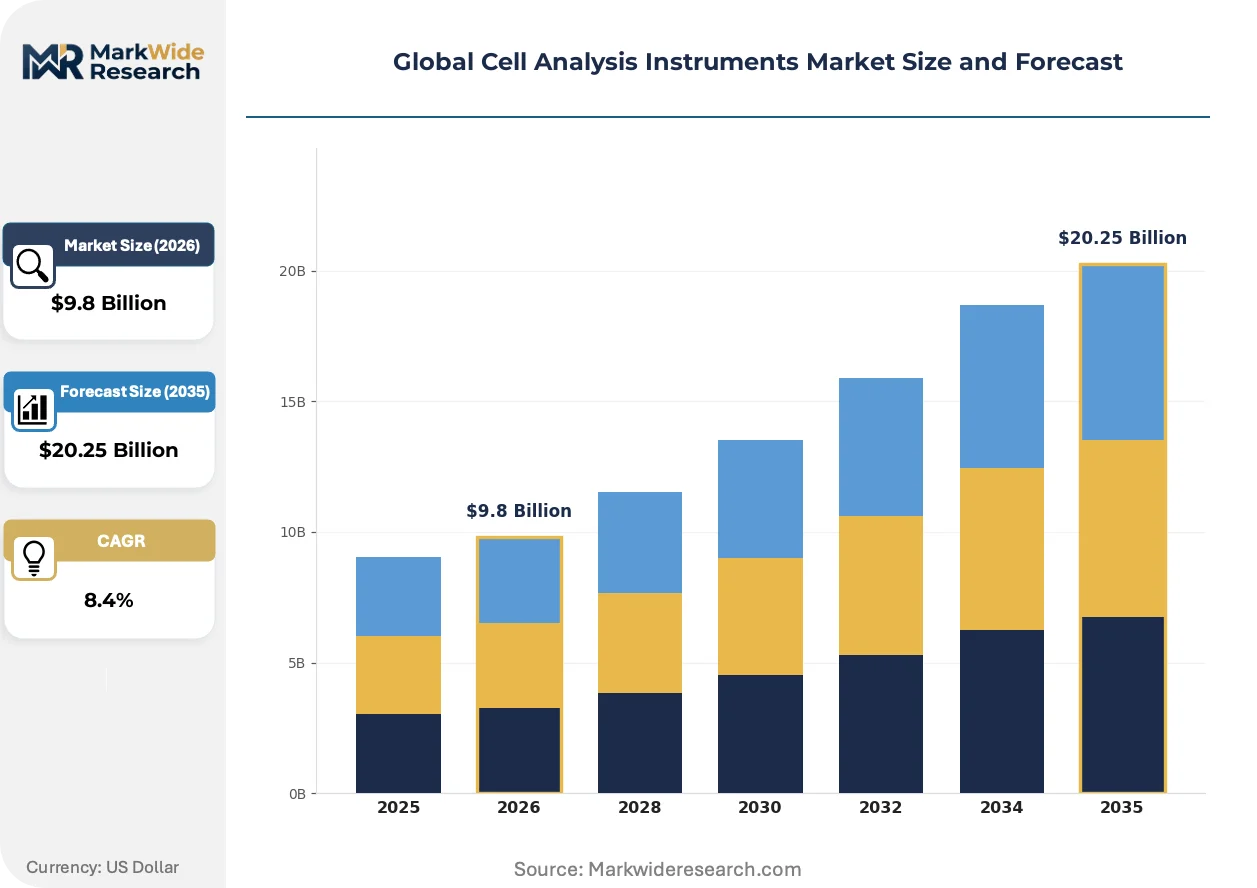
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometers, Image Cytometers, Cell Counters, Cell Analyzers Technology: Fluorescence, Impedance, Microfluidics, Spectroscopy, Brightfield Microscopy Application: Drug Discovery, Genomics, Toxicology, Cell Biology Research, Immunology End User: Pharmaceutical Companies, Academic Research Institutes, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Danaher Corporation, Merck KGaA, Agilent Technologies, Bio-Rad Laboratories, Sartorius AG, Miltenyi Biotec, Revvity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Analysis Instruments Market Strategic Shifts & Innovations
Automation and data integration are defining the next generation of cell analysis instruments. The market is shifting toward systems that not only acquire cellular data at unprecedented scale and resolution but also incorporate software tools to streamline analysis and interpretation.
Spatial biology platforms provide a method for analyzing cellular composition within the context of tissue architecture. Academic researchers and biopharma companies focused on oncology and neurodegenerative disease are the primary adopters. Analysis is migrating from studying dissociated cells in suspension to understanding cellular interactions and heterogeneity in their native microenvironment.
The European Union's In Vitro Diagnostic Regulation (IVDR) is elevating compliance burdens for manufacturers. This framework mandates more rigorous clinical evidence and post-market surveillance for instruments intended for diagnostic use. Consequently, companies targeting the European clinical market must now allocate greater resources to regulatory affairs and quality management systems to achieve and maintain CE marking.
A clear behavioral shift is occurring away from direct capital purchases toward reagent rental agreements and subscription-based access models. This disrupts the traditional sales process, with instrument placement now often contingent on minimum consumable purchase commitments. This trend is most visible within budget-constrained academic core facilities and biotech startups in the United States and Europe.
Global Cell Analysis Instruments Market Segmentation
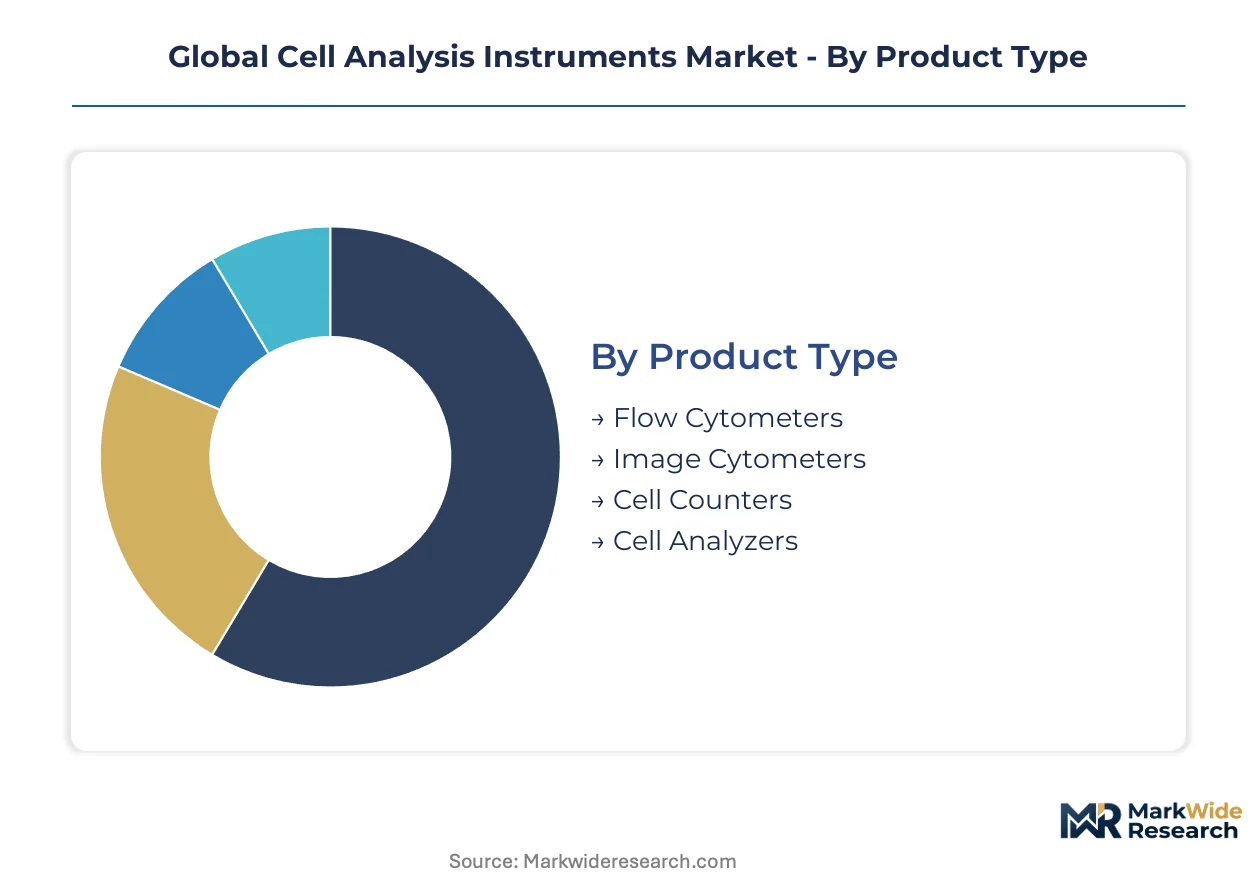
Understanding the segmentation of the global cell analysis instruments market reveals the diverse technological preferences and application-specific demands driving industry growth. This granular view highlights where innovation and investment are most concentrated, guiding strategic product development and market entry efforts for manufacturers.
Product Type:
Product type differentiation defines the primary functional capabilities available for cellular characterization.
- Flow Cytometers:These systems rapidly analyze and sort cells suspended in a fluid stream, employing laser light and detectors to measure multiple cellular properties simultaneously. Demand concentrates in immunology and oncology research within large pharmaceutical companies for high-throughput screening.
- Image Cytometers:Integrating advanced microscopy with automated image analysis, these instruments capture high-resolution images of cells and quantify morphological or fluorescent markers. Academic research institutes utilize image cytometers for complex phenotypic screening in drug discovery workflows.
- Cell Counters:These devices provide rapid enumeration of cells in a sample, often used for basic cell culture monitoring and viability assessments.
- Cell Analyzers:This broad category encompasses instruments designed for various cellular assays, including viability, proliferation, and apoptosis, often featuring integrated detection methods.
Flow Cytometers holds installed capacity. Image Cytometers is rotating up the share rankings.
Technology:
Technological approaches underpin the precision and data richness of cell analysis systems.
- Microfluidics:This technology manipulates small fluid volumes within micro-channels, enabling single-cell analysis, high-throughput screening, and reduced reagent consumption. Pharmaceutical R&D investment drives microfluidics adoption for complex genomics applications.
- Fluorescence:Utilizing fluorescent probes to label specific cellular components, this technique allows for sensitive and specific detection of biological molecules and cellular processes. Academic research institutes widely employ fluorescence for high-content screening.
- Impedance:This method measures changes in electrical resistance as cells pass through a small aperture, providing label-free cell counting and size distribution data.
- Spectroscopy:Employing light interaction with cells to analyze their biochemical composition, spectroscopy offers non-invasive characterization of cellular states.
- Brightfield Microscopy:A fundamental optical technique that illuminates samples with white light, brightfield microscopy provides basic morphological information about cells and tissues.
Microfluidics technology drives innovation. Fluorescence remains a foundational technique.
Application:
End-use applications dictate the specific analytical requirements and instrument configurations.
- Drug Discovery:This application involves screening compounds, identifying therapeutic targets, and evaluating drug efficacy and toxicity using cell-based assays. Pharmaceutical companies consistently invest in cell analysis instruments for accelerating their drug pipelines.
- Immunology:Focused on studying the immune system, this application utilizes cell analysis to characterize immune cell populations, analyze cytokine production, and monitor immune responses. Academic research institutes drive demand for advanced flow cytometry systems in immunology.
- Genomics:This application involves studying an organism's entire genome, including gene expression, DNA sequencing, and genetic variations at the cellular level.
- Toxicology:Assessing the adverse effects of chemical substances on biological systems, toxicology relies on cell analysis for cytotoxicity testing and mechanistic studies.
- Cell Biology Research:A broad field investigating cellular structure, function, and behavior, cell biology research uses instruments for basic science discoveries and hypothesis testing.
Drug Discovery applications command substantial investment. Genomics research exhibits expanding demand.
End User:
Customer type segments reflect varied purchasing power and research objectives across the market.
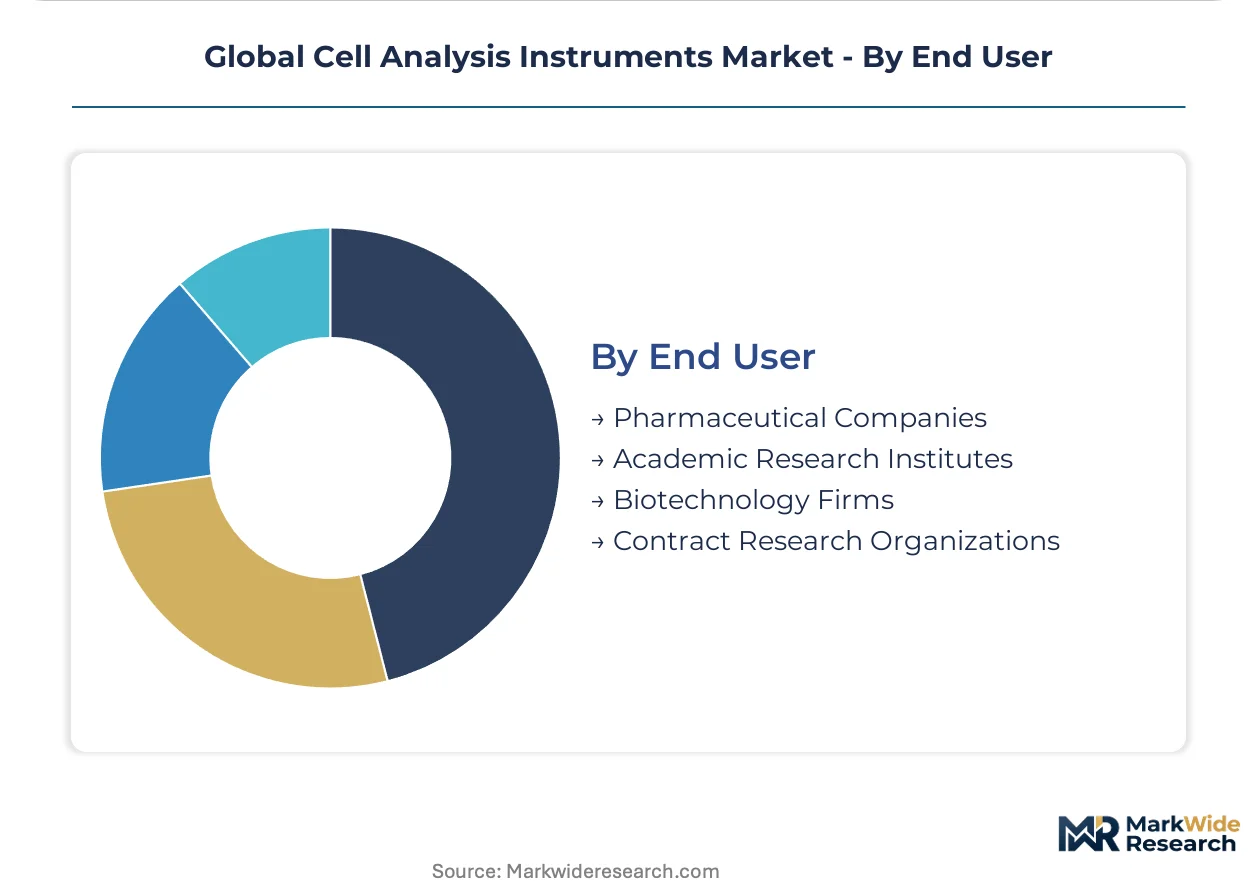
- Pharmaceutical Companies:These large enterprises invest heavily in cell analysis instruments for drug development, clinical trials, and quality control processes. Escalating R&D investment drives sustained demand for high-content screening and flow cytometry systems.
- Academic Research Institutes:Universities and government-funded research centers utilize cell analysis instruments for fundamental biological research, disease mechanisms, and educational purposes. Government life science initiatives in China are accelerating infrastructure development in these institutes.
- Biotechnology Firms:These companies focus on developing innovative biological products and technologies, requiring advanced cell analysis for research and product development.
- Contract Research Organizations:CROs provide outsourced research services to pharmaceutical and biotechnology companies, utilizing cell analysis instruments for various client projects.
Pharmaceutical companies represent a core revenue base. Biotechnology firms are expanding their instrument fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for cell analysis instruments varies significantly by region, reflecting diverse funding models and market maturity. While some geographies prioritize direct capital equipment purchases, others are rapidly adopting reagent rental and subscription-based access models. This shift particularly impacts budget-constrained academic and biotech sectors in established markets.
United States
Large pharmaceutical companies and academic research institutes drive substantial demand for cell analysis instruments. The US FDA influences instrument design and validation requirements for clinical diagnostics. Research clusters in the Boston-Cambridge area continue to expand, fostering innovation in high-throughput screening.
China
Government initiatives promoting biotechnology hubs accelerate demand for advanced cell analysis instrumentation. NMPA standards for medical devices create market access hurdles for compliant manufacturers. Life science hubs in the Yangtze River Delta region are rapidly developing, attracting investment in cutting-edge research.
Germany
Academic research institutes and leading pharmaceutical companies in Germany maintain consistent demand for sophisticated cell analysis systems. The European Union's IVDR elevates compliance burdens for diagnostic instruments. Research and development activities in the Munich area are strong, focusing on advanced microscopy.
India
Emerging research hubs across India are investing in cell analysis instruments to support pharmaceutical R&D and academic pursuits. The country's national pharmaceutical regulator, CDSCO, influences product validation for medical devices. Biotechnology parks in Bangalore are expanding, creating new opportunities for advanced cell characterization.
Brazil
Expanding academic research institutes and biotechnology firms in Brazil drive demand for advanced cell analysis systems. ANVISA, the national health surveillance agency, regulates medical devices and in-vitro diagnostics. Research centers in São Paulo actively adopt high-throughput screening technologies for drug discovery.
Global Cell Analysis Instruments Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a nuanced competitive landscape for cell analysis instruments. The market exhibits a tiered structure, with established global players alongside specialized technology providers. Key strategic archetypes include integrated solution providers, niche technology innovators, and regional specialists. Dominant competitive moves involve strategic partnerships for technology co-development and portfolio diversification into recurring revenue streams.
Integrated solution providers, such as Thermo Fisher Scientific Inc., exemplify the strategy of leveraging extensive reagent catalogs to create sticky customer ecosystems, a critical factor in the shift towards recurring revenue models. Becton, Dickinson and Company occupies a strong position as a specialized player, particularly in flow cytometry systems and associated assays, demonstrating the value of deep expertise in specific product types. Danaher Corporation, a diversified science and technology conglomerate, represents a model for broad market presence through a portfolio of specialized life science brands, often acquiring innovative technologies to expand its reach. These firms collectively navigate the market's pivot from capital equipment sales to integrated hardware and consumable offerings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Sartorius AG |
| Miltenyi Biotec |
| Revvity |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta region, a rapidly developing life science hub, increasingly influences global pricing for advanced cell analysis instruments by concentrating manufacturing capacity. This concentration creates specific pricing dynamics for integrated hardware and consumable offerings.
Pricing Analysis
Subscription-based access and reagent rental agreements define the predominant pricing model for cell analysis instruments, displacing traditional capital purchases. Price differentiation stems from proprietary reagent compatibility and regulatory compliance status for clinical diagnostics. Operational costs face upward pressure from vendor lock-in through proprietary consumables and software. Academic labs and small biotechnology firms exhibit the highest price sensitivity, while large pharmaceutical companies prioritize performance and integration.
Supply Chain Analysis
Manufacturing for key cell analysis components concentrates in East Asia, particularly China and South Korea, with specialized optical and microfluidic chip production in the United States. The supply chain relies on a few critical suppliers for high-precision lasers and advanced sensor technologies. A structural risk involves single-source vulnerability for certain proprietary detection modules. Direct sales channels and specialized distributors manage downstream delivery to pharmaceutical companies and academic research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell analysis instruments market represents a service-attach opportunity, with recurring revenue from proprietary reagents and consumables expanding faster than initial hardware sales. This shift redefines long-term value creation for market participants.
For Market Incumbents:Harden proprietary consumable ecosystems by continuously innovating reagent portfolios and software analytics. Integrate artificial intelligence for automated data analysis, countering the threat of data management bottlenecks. Expand into regulated in-vitro diagnostic applications to leverage existing instrument platforms for new revenue streams. This strategy reinforces market position against emerging specialized technology providers.
For New Entrants and Emerging Players:Pursue niche opportunities in spatial biology platforms or AI-driven image analysis, targeting unmet needs in oncology and neurodegenerative research. Focus on emerging research hubs in countries like India and Brazil, which represent the most penetrable geographies. A flexible reagent rental model can overcome high capital outlay barriers for academic labs and small biotechnology firms. This approach enables market entry with lower initial customer commitment.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among integrated solution providers leveraging extensive consumable catalogs, indicating strong long-term viability. Target niche technology innovators specializing in microfluidics or AI-driven data analysis for strategic acquisitions. These firms offer differentiation and strengthen recurring revenue streams. The signal to watch is the successful commercialization of research-use-only instruments adapted for regulated clinical diagnostic applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Clinical Diagnostics | Expands market access for validated systems beyond research-use-only applications. |
| Technology Co-development for AI and Machine Learning | Unlocks deeper biological insights from complex datasets, enhancing product differentiation. |
| Geographic Expansion into Emerging Research Hubs | Accesses new customer bases in nascent life science clusters before market saturation. |
| Investment in Regulatory Pathway Compliance | Ensures product viability and market access for diagnostic instruments in key regions. |
| Reinforcement of Proprietary Consumables Ecosystem | Creates sticky customer relationships and shifts the profit pool towards recurring revenue models. |
Research Approach
The analysis maps cell analysis instrument product types, technologies, and applications, each validated through extensive primary interviews with industry stakeholders. This includes pharmaceutical R&D executives, academic principal investigators, and biotechnology firm founders. Secondary data from US FDA filings, European Medicines Agency guidelines, and NMPA standards complemented these insights. Bottom-up market sizing and top-down validation ensure robust data triangulation.
The forecast framework holds assumptions regarding stable R&D investment and consistent regulatory evolution over the projection horizon. Volume and value outputs reflect a comprehensive analytical approach, modeling segmentation across product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates derive from historical trends and projected technological adoption, with key inputs from drug discovery pipeline advancements and government life science initiatives.
Macroeconomic conditions sit as an overlay; deviation in global R&D funding or geopolitical stability would shift the trajectory of these forecasts. Forecasts reflect current assumptions, acknowledging potential revisions from unforeseen regulatory shifts. Quarterly review of R&D spending and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Laboratory Furnaces Market