
 Global Laboratory Hoods and Enclosure Market | 2026-2036
Global Laboratory Hoods and Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Hoods and Enclosure Market Foresight
North American fume hood manufacturers is pivoting toward modular cleanroom-compatible designs to serve expanding cell therapy production. Thermo Fisher Scientific leverages its integrated life sciences platform to bundle containment with analytical workflows. Labconco anchors the academic and government lab channel through specialized chemical fume hood lines. Esco Micro Pte. Ltd. dominates biosafety cabinet exports across Asia-Pacific with region-specific certifications.
Laboratory hoods and enclosures are ventilated cabinet systems engineered to capture, contain, and exhaust hazardous vapors, particulates, or biological agents through controlled airflow barriers, typically operating at face velocities between 80 and 120 feet per minute to protect personnel and experimental integrity. Their primary purpose is to isolate dangerous materials during research, manufacturing, or testing while maintaining environmental separation and operator safety. Chemical fume hoods sustain the largest installed base across pharmaceutical research and chemical synthesis applications, reflecting decades of standardization in wet chemistry workflows. Biosafety cabinets command premium pricing tiers due to HEPA and ULPA filtration requirements in pathogen handling, with Class II Type A2 configurations representing the dominant specification. Ductless fume hoods are gaining share in environmental testing and food safety analysis where mobility and infrastructure flexibility outweigh traditional ducted exhaust advantages.
EPA emissions guidelines, OSHA laboratory ventilation standards, and ISO 14644 cleanroom classifications collectively determine hood performance benchmarks, installation compliance costs, and market access thresholds for equipment vendors. The EU AI Act and REACH chemical restrictions are beginning to influence filtration media selection and sensor integration requirements for units sold into European pharmaceutical research and environmental testing facilities. Stakeholders must monitor evolving filter disposal regulations and real-time airflow monitoring mandates as containment equipment becomes subject to predictive maintenance and digital compliance auditing.
Market Dynamics
The transition from ducted to ductless filtration architectures constitutes the dominant structural force reshaping procurement patterns, as facilities seek to eliminate infrastructure retrofit costs and comply with tightening EPA emissions benchmarks without building modifications.
Growth Catalysts
- Biologics manufacturing scale-up:Cell therapy production facilities in the United States and Germany require Class II biosafety cabinet installations at triple the density of traditional pharmaceutical research labs.
- REACH chemical restrictions:The EU's evolving filtration media standards force replacement cycles that accelerate equipment refresh rates across European environmental testing laboratories.
- Dual carbon goals:China's MEE efficiency mandates drive adoption of variable air volume controls and heat recovery systems in new academic research complexes.
Market Restraints
- HEPA filter supply concentration:Production of certified filtration media concentrates among three specialized suppliers in Germany and Japan, creating input bottlenecks during certification audits.
- Cleanroom infrastructure lock-in:Existing ISO 14644-certified facilities face sunk-cost barriers when evaluating ductless alternatives that require airflow recalculation.
- Substitution by isolator technology:Closed isolator systems for aseptic processing capture containment budgets that previously flowed to open-front biosafety cabinets.
Strategic Opportunities
- India's PLI scheme for pharmaceuticals:Domestic manufacturing incentives attract contract research organizations building containment infrastructure in Hyderabad and Bangalore clusters.
- Sensor-embedded predictive maintenance:Real-time airflow monitoring converges with digital compliance auditing to create subscription-based service revenue streams.
- Modular cleanroom-compatible designs:Cell therapy producers demand reconfigurable containment that integrates with isolator workflows rather than standalone installations.
Industry Challenges
- Certified field service technician scarcity:HEPA filter replacement and airflow calibration require specialized training that outpaces vocational program output in Asia-Pacific expansion markets.
- Legacy building HVAC integration:Retrofitting ductless units into facilities with fixed exhaust infrastructure demands structural engineering coordination that extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Hoods and Enclosure Market |
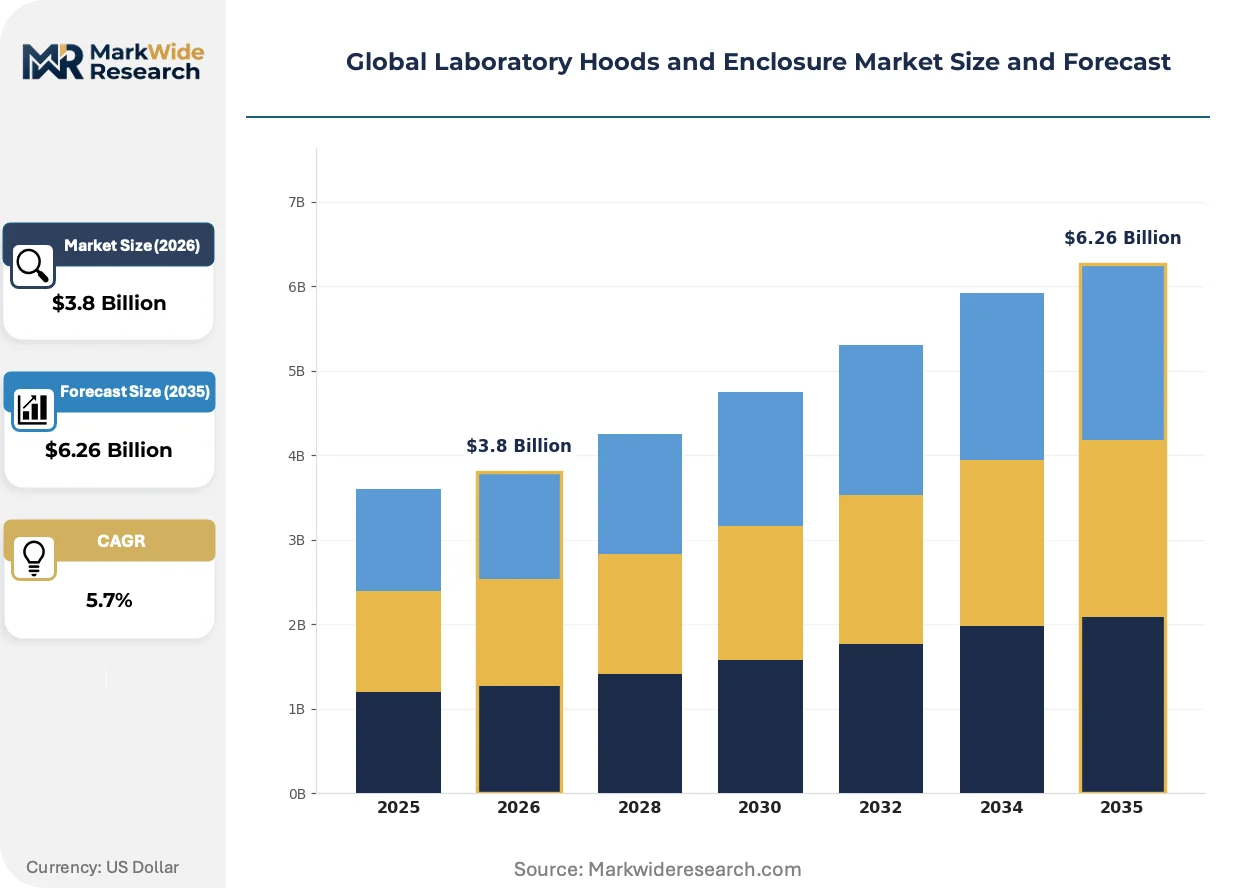
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
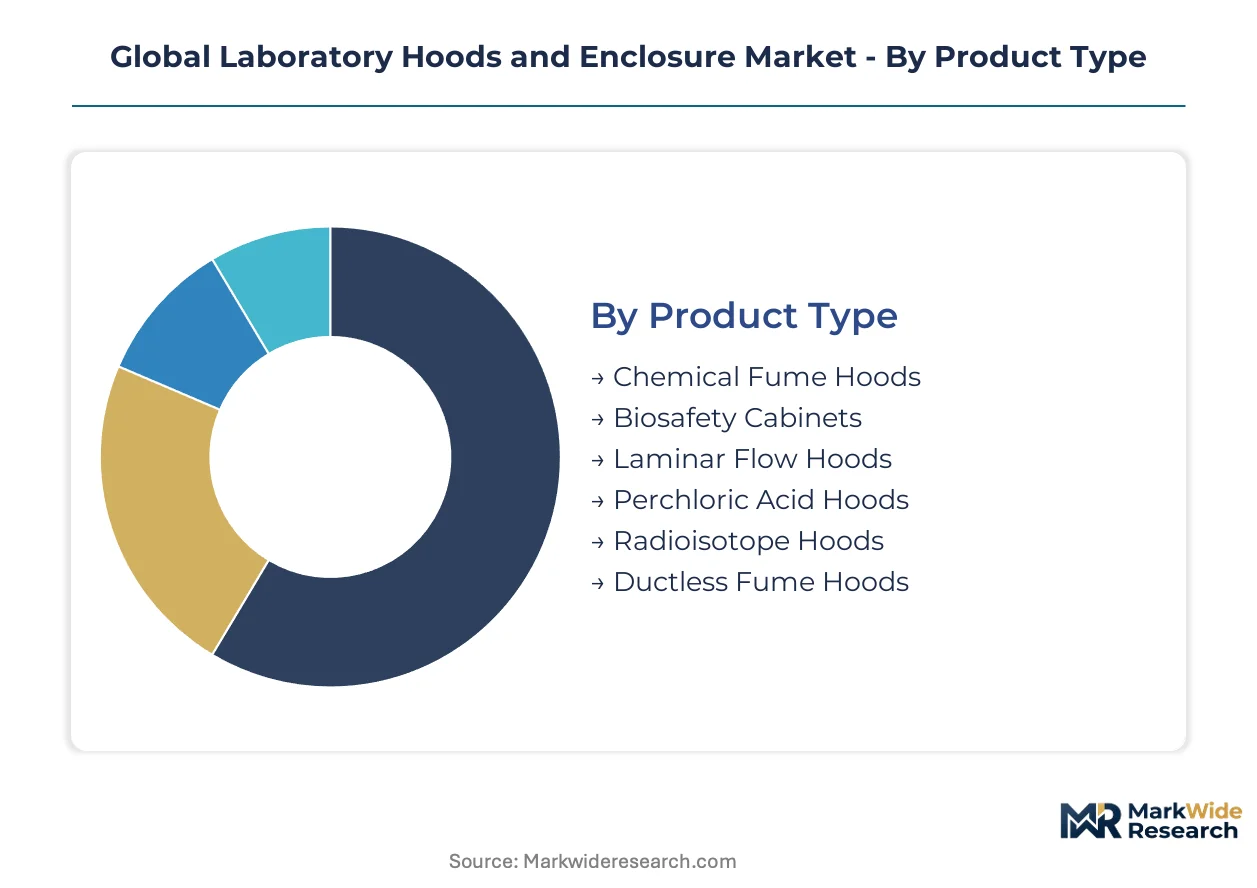
| Segmentation | Product Type: Chemical Fume Hoods, Biosafety Cabinets, Laminar Flow Hoods, Perchloric Acid Hoods, Radioisotope Hoods, Ductless Fume Hoods Technology: HEPA Filtration, ULPA Filtration, Variable Air Volume, Constant Air Volume, Recirculating, Powered Exhaust Application: Pharmaceutical Research, Environmental Testing, Food Safety Analysis, Forensic Laboratories, Chemical Synthesis, Quality Control Labs End User: Academic Institutions, Biotechnology Firms, Contract Research Organizations, Diagnostic Centers, Chemical Manufacturers, Government Labs |
| Companies Covered | Thermo Fisher Scientific Inc., Labconco, Esco Micro Pte. Ltd., Kewaunee International Group, AirClean Systems, Inc., Mott Manufacturing Ltd., Nuaire, WALDNER Holding SE & Co. KG, Terra Universal, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Hoods and Enclosure Market Shifts & Advancements
Digital airflow verification and connected containment systems are displacing manual inspection protocols across pharmaceutical and academic installations, embedding compliance documentation directly into equipment operation.
Carbon-activated filtration media with real-time saturation monitoring is absorbing volatile organic compound loads previously managed through external exhaust ducting. Biotechnology manufacturers in the United States and Germany deploy these systems to avoid building penetration permits. The technology is absorbing capital budgets that would otherwise fund HVAC infrastructure expansion.
The EU AI Act's risk classification framework now extends to laboratory equipment with embedded diagnostic algorithms, requiring conformity assessments for smart hoods with automated sash positioning. European pharmaceutical research facilities face documentation burdens that favor established vendors with notified body relationships. Class II biosafety cabinets with integrated airflow AI represent the most affected product category.
Consolidated procurement through integrated life sciences platform providers displaces standalone equipment purchasing in large pharmaceutical accounts. Thermo Fisher Scientific and similar conglomerates bundle containment with analytical workflows, compressing vendor counts at major research institutions. This concentration is most visible in United States academic medical centers and contract development organizations.
Global Laboratory Hoods and Enclosure Market Segmentation
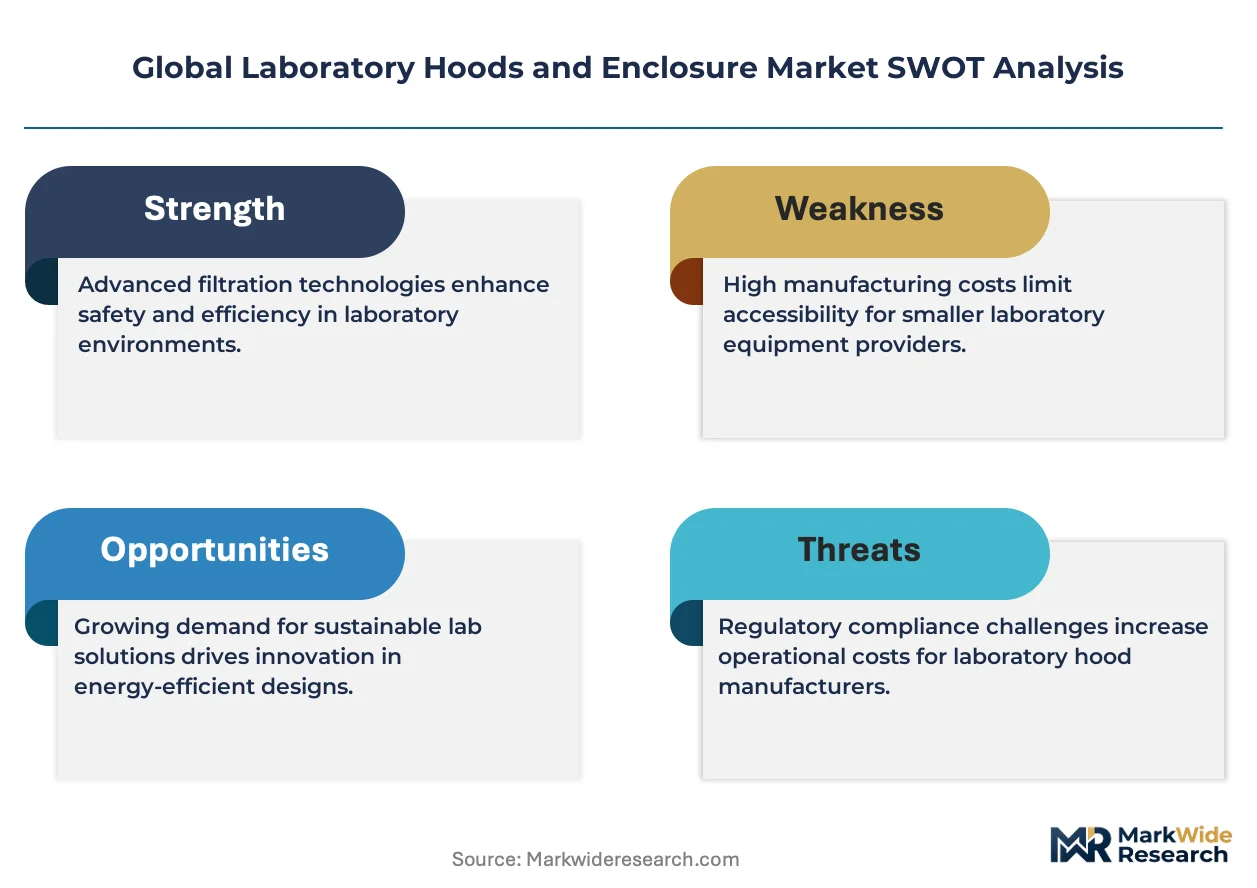
Laboratory hood procurement decisions diverge sharply across user archetypes, with pharmaceutical manufacturers prioritizing containment validation while academic buyers weigh capital efficiency against retrofit flexibility. Understanding these segment-specific trade-offs clarifies why vendor positioning strategies must align with distinct technical and commercial requirements rather than pursuing uniform market penetration.
Product Type:
Facility infrastructure constraints and hazard class protocols determine which hood architecture buyers can deploy, creating stark differences in average transaction value and replacement frequency.
- Chemical Fume Hoods:Ducted exhaust systems with sash-controlled face velocities between 80-120 feet per minute dominate wet chemistry workflows across pharmaceutical research and academic institutions. Demand concentrates in Germany and the United States where legacy building stock sustains ducted infrastructure preference, though EPA emissions compliance is extending replacement cycles.
- Biosafety Cabinets:HEPA-filtered containment enclosures with unidirectional airflow protect personnel and product during pathogen handling, with Class II Type A2 configurations representing the dominant specification. Cell therapy production facilities in the United States install these at triple the density of traditional pharmaceutical labs, driven by FDA guidance on aseptic processing.
- Laminar Flow Hoods:Product protection systems filter supply air to ISO Class 5 standards for sterile preparation workflows in hospital pharmacies and diagnostic centers.
- Perchloric Acid Hoods:Specialized wash-down ducting prevents explosive perchlorate salt accumulation in materials science and geological testing applications.
- Radioisotope Hoods:Lead-shielded containment with HEPA exhaust filtration serves nuclear medicine research and radiopharmaceutical manufacturing.
- Ductless Fume Hoods:Carbon-activated filtration units with real-time saturation monitoring eliminate building penetration requirements for environmental testing and food safety laboratories.
Chemical fume hoods lead volumes today; ductless fume hoods are gaining share fastest.
Technology:
Energy efficiency mandates and certification audit requirements are reconfiguring technology adoption curves, with premium filtration media and intelligent airflow controls commanding price premiums.
- HEPA Filtration:99.97% efficiency at 0.3 micron particles represents the baseline containment standard for biosafety cabinets and cleanroom-adjacent applications. China's MEE efficiency mandates are accelerating variable air volume integration with HEPA systems in new academic research complexes.
- ULPA Filtration:99.999% efficiency at 0.12 micron particles serves semiconductor and advanced therapy manufacturing where particulate control exceeds pharmaceutical requirements. Germany's Fraunhofer Institute clusters and South Korean biologics facilities drive specification intensity.
- Variable Air Volume:Demand-responsive airflow modulation reduces HVAC energy consumption by 30-50% compared to constant volume systems.
- Constant Air Volume:Fixed airflow rates maintain simplicity in legacy facilities without building automation infrastructure.
- Recirculating:Filtered air return eliminates external exhaust requirements for non-toxic particulate applications.
- Powered Exhaust:Auxiliary blower systems overcome duct resistance in facilities with inadequate central HVAC capacity.
HEPA filtration anchors installed base economics; ULPA filtration is climbing the fastest.
Application:
Regulatory scrutiny intensity and contamination consequence severity create tiered willingness-to-pay across application segments, with human therapeutic applications commanding validation investments that environmental testing cannot justify.
- Pharmaceutical Research:Multi-hood installations support lead optimization through clinical candidate selection, with containment redundancy requirements for cytotoxic and potent compound handling. United States contract development organizations and German biotech clusters represent the densest demand concentration.
- Environmental Testing:Mobile ductless configurations serve field sampling and water quality analysis where laboratory infrastructure is distributed. India's Central Pollution Control Board laboratory expansion and United States EPA contract labs are scaling procurement.
- Food Safety Analysis:Pathogen detection workflows require Class II biosafety containment for Salmonella and Listeria screening in regulatory and industrial laboratories.
- Forensic Laboratories:Fume hoods protect analysts during drug chemistry and toxicology sample processing for law enforcement agencies.
- Chemical Synthesis:Process development and scale-up activities in agrochemical and specialty chemical manufacturing.
- Quality Control Labs:Incoming material testing and finished product release testing in pharmaceutical and chemical production.
Pharmaceutical research captures the largest revenue pool; environmental testing is expanding most quickly.
End User:
Budget authority structures and procurement sophistication vary dramatically across end user types, with consolidated life sciences platforms displacing standalone equipment purchasing in the largest accounts.
- Academic Institutions:Capital budget constraints and shared equipment models favor ductless and recirculating configurations that minimize facilities coordination. United States National Institutes of Health funding cycles and China's Double First Class university initiative are driving replacement waves.
- Biotechnology Firms:Venture-backed and publicly traded cell therapy developers prioritize rapid containment deployment with validation documentation for FDA pre-IND interactions. Boston, San Francisco, and Basel clusters represent concentrated demand.
- Contract Research Organizations:Flexible capacity expansion requirements favor modular cleanroom-compatible designs that can be reconfigured between projects.
- Diagnostic Centers:Clinical laboratory improvement amendments compliance drives standardized biosafety cabinet specifications.
- Chemical Manufacturers:Process safety management regulations mandate containment for hazardous reaction monitoring.
- Government Labs:Federal research facilities and public health laboratories with multi-year capital planning horizons.
Academic institutions lead unit volumes; biotechnology firms are driving specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States containment infrastructure investment outpaces German procurement velocity, while Chinese academic expansion reshapes Asia-Pacific equipment flows. Facility retrofit cycles and biologics manufacturing scale-up create divergent demand profiles across these three markets.
United States
Cell therapy production facilities in Boston and San Francisco drive Class II biosafety cabinet installations at triple traditional pharmaceutical lab density. FDA guidance on aseptic processing mandates containment redundancy for cytotoxic compound handling. NIH funding cycles sustain replacement waves across academic medical centers and National Laboratory complexes.
Germany
Fraunhofer Institute clusters and BASF-Leverkusen chemical synthesis operations sustain chemical fume hood demand despite REACH-driven filtration media replacement cycles. ECHA evolving standards accelerate equipment refresh across environmental testing laboratories. Baden-Württemberg biotech corridor scales modular cleanroom-compatible containment for mRNA manufacturing.
China
Double First Class university initiative and MEE efficiency mandates converge to drive variable air volume adoption in new academic research complexes. Dual carbon goals enforce heat recovery system integration. Yangtze River Delta pharmaceutical clusters in Shanghai and Suzhou deploy containment infrastructure for domestic biologics manufacturing.
India
PLI scheme pharmaceutical manufacturing incentives attract contract research organizations building containment infrastructure. CDSCO regulatory alignment requirements drive validation-documentation intensity. Hyderabad and Bangalore clusters concentrate biosafety cabinet procurement for export-oriented biologics production.
Japan
PMDA quality management system inspections elevate containment validation requirements for domestic pharmaceutical manufacturers. METI energy efficiency standards accelerate VAV retrofit adoption in legacy facilities. Kansai pharmaceutical corridor and Tokyo academic complexes sustain premium-tier equipment demand.
Global Laboratory Hoods and Enclosure Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold certification-intensive segments. Market structure consolidates around integrated life sciences platforms and regional fabrication specialists. Three archetypes dominate: conglomerate bundlers, regional certification holders, and modular cleanroom integrators. Competitive moves center on strategic partnerships for digital compliance auditing and capacity expansion in Asia-Pacific certification facilities.
Within the conglomerate bundler tier, Thermo Fisher Scientific Inc. represents integrated platform positioning. Labconco and Esco Micro Pte. Ltd. exemplify regional specialists with distinct channel anchoring—Labconco occupies academic and government laboratory positioning, while Esco Micro sits within Asia-Pacific biosafety cabinet export flows. Kewaunee International Group anchors mid-market fabrication scale. WALDNER Holding SE & Co. KG represents European precision manufacturing heritage. These five entities collectively illustrate the geographic and structural segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Labconco |
| Esco Micro Pte. Ltd. |
| Kewaunee International Group |
| AirClean Systems, Inc. |
| Mott Manufacturing Ltd. |
| Nuaire |
| WALDNER Holding SE & Co. KG |
| Terra Universal, Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between HEPA and ULPA filtration tiers manifests in both equipment pricing and component sourcing strategies, with German and Japanese media suppliers commanding premium positions while Chinese fabricators compete on variable air volume integration costs. Buyers in pharmaceutical research segments absorb these premiums for FDA-validated containment, whereas academic institutions negotiate standard-tier pricing with extended service bundling.
Pricing Analysis
Distributor margins of 15-25% separate OEM direct pricing from end-user acquisition costs across most procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with ULPA-filtered biosafety cabinets commanding substantial premiums over HEPA-based chemical fume hoods. Cost compression in standard-tier ductless units is intensifying because Chinese manufacturers are scaling carbon-activated filtration production. Academic institutions exhibit highest price sensitivity, while cell therapy developers prioritize validation documentation over capital efficiency.
Supply Chain Analysis
Freight costs for fully assembled containment equipment run 8-12% of landed value for intercontinental shipments from Germany and Japan to North American pharmaceutical clusters. HEPA and ULPA filtration media production concentrates in Germany, Japan, and the United States, with certified media drawing from specialized glass microfiber suppliers in Bavaria and Osaka prefectures. Single-source vulnerability in HEPA certification audits creates bottlenecks during facility commissioning waves. Distribution runs through life sciences platform providers and specialized laboratory equipment distributors serving academic and government channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by cell therapy manufacturers specifying Class II Type A2 biosafety cabinets with integrated airflow AI and predictive maintenance capabilities. Premium specification demand is displacing commodity procurement in pharmaceutical accounts.
For Market Incumbents: To counter closed isolator technology capturing aseptic processing budgets, defend biosafety cabinet positioning through modular cleanroom-compatible designs that integrate with isolator workflows rather than compete as standalone installations. Prioritize backward integration into HEPA filter certification capabilities to reduce supply bottlenecks during customer commissioning cycles. For New Entrants and Emerging Players: Begin with India's PLI scheme pharmaceutical clusters in Hyderabad and Bangalore, where CDSCO regulatory alignment requirements have outpaced certified field service technician availability. Target environmental testing laboratories scaling ductless fume hood procurement for mobile field sampling applications. Establish go-to-market partnerships with regional distributors holding existing academic and government laboratory relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor-embedded predictive maintenance capabilities converge with digital compliance auditing requirements, favoring vendors with notified body relationships under the EU AI Act. Long-term viability centers on subscription-based service revenue streams rather than equipment transaction margins. Target acquisition archetypes include regional certification holders with Asia-Pacific fabrication capacity. Monitor CDSCO and PMDA inspection intensity as inflection indicators for validation-documentation premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Predictive Maintenance Development | Creates recurring revenue streams from pharmaceutical accounts requiring FDA-compliant airflow documentation. |
| Asia-Pacific Certification Facility Expansion | Reduces lead times for Esco Micro and regional competitors serving China's Double First Class university initiative. |
| Modular Cleanroom-Compatible Design Launch | Addresses cell therapy producer demand for reconfigurable containment integrating with isolator workflows. |
| Carbon-Activated Filtration Media Scale-Up | Captures environmental testing and food safety laboratory budgets shifting from ducted to ductless architectures. |
| Digital Compliance Auditing Platform Partnership | Aligns with EU AI Act conformity assessment requirements for smart hoods with automated sash positioning. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged laboratory equipment procurement managers at pharmaceutical manufacturers, containment validation specialists at contract research organizations, facilities directors at academic medical centers, and aftermarket service heads at regional distributors. Secondary sources included EPA emissions guidelines, OSHA laboratory ventilation standards, ISO 14644 cleanroom classifications, EU AI Act documentation requirements, and customs records for filtration media trade flows. Bottom-up unit demand estimates triangulated against top-down market sizing from capital expenditure disclosures.
Rate-of-change decomposition across the analysis window separated replacement cycle dynamics from net capacity expansion in biologics manufacturing. Segmentation dimensions modeled include product type, filtration technology tier, application intensity, and end-user procurement sophistication. CAGRs derived from weighted average of historical replacement patterns and forward-looking regulatory compliance deadlines. Industry-specific forecast inputs incorporated NIH funding cycle phasing and China's MEE efficiency mandate implementation timelines.
Several conditions sit outside the modeled scope, including potential REACH filtration media standard revisions, abrupt HEPA supply disruptions from certification audit backlogs, and substitution acceleration by closed isolator technology. Forecasts reflect assumptions about regulatory enforcement continuity and capital commitment stability across pharmaceutical research budgets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Global Blood Collection Tubes Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Microplate Luminometer Market