
 Automated Nucleic Acid Extraction Systems Market | 2026-2036
Automated Nucleic Acid Extraction Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Nucleic Acid Extraction Systems Market Outlook
Aftermarket service revenue is narrowing as a margin pool migration between instrument sales and recurring consumables reshapes vendor economics. Thermo Fisher Scientific leverages its installed base of KingFisher platforms to sustain high-margin reagent pull-through across clinical and research accounts. QIAGEN anchors its competitive position through integrated workflow solutions that span extraction through downstream analysis. Roche Diagnostics dominates in high-throughput hospital laboratories where walk-away automation reduces technician hands-on time.
Automated nucleic acid extraction systems are electromechanical platforms that isolate DNA or RNA from biological samples using magnetic bead separation, silica membrane filtration, or microfluidic channel processing, typically completing runs in 15–60 minutes with sample inputs from 10 µL to 10 mL. These systems serve clinical diagnostics, forensic genomics, and pharmaceutical research by standardizing yield purity and reducing cross-contamination risk compared to manual methods. Magnetic bead-based extraction occupies the largest installed base due to scalability and compatibility with diverse sample matrices, while microfluidic approaches represent the fastest-growing segment as point-of-care molecular testing expands. Research applications generate substantial demand from academic and government laboratories, though clinical diagnostics commands premium pricing through regulatory-validated workflows.
FDA clearance pathways for in vitro diagnostic devices shape product development timelines and clinical adoption thresholds for automated extraction platforms in the United States. ISO 13485 quality management requirements and EU IVDR conformity standards govern market access for European manufacturers, while China's NMPA registration process creates distinct certification burdens for imported systems. Stakeholders must monitor evolving harmonization between regional premarket review criteria as multiplexed assay panels and CRISPR-based diagnostics place new demands on extraction fidelity and throughput specifications.
Market Dynamics
Magnetic bead-based extraction platforms are consolidating laboratory workflows as clinical diagnostic volumes surge and FDA validation requirements tighten, compressing the competitive window for unvalidated manual methods.
Growth Catalysts
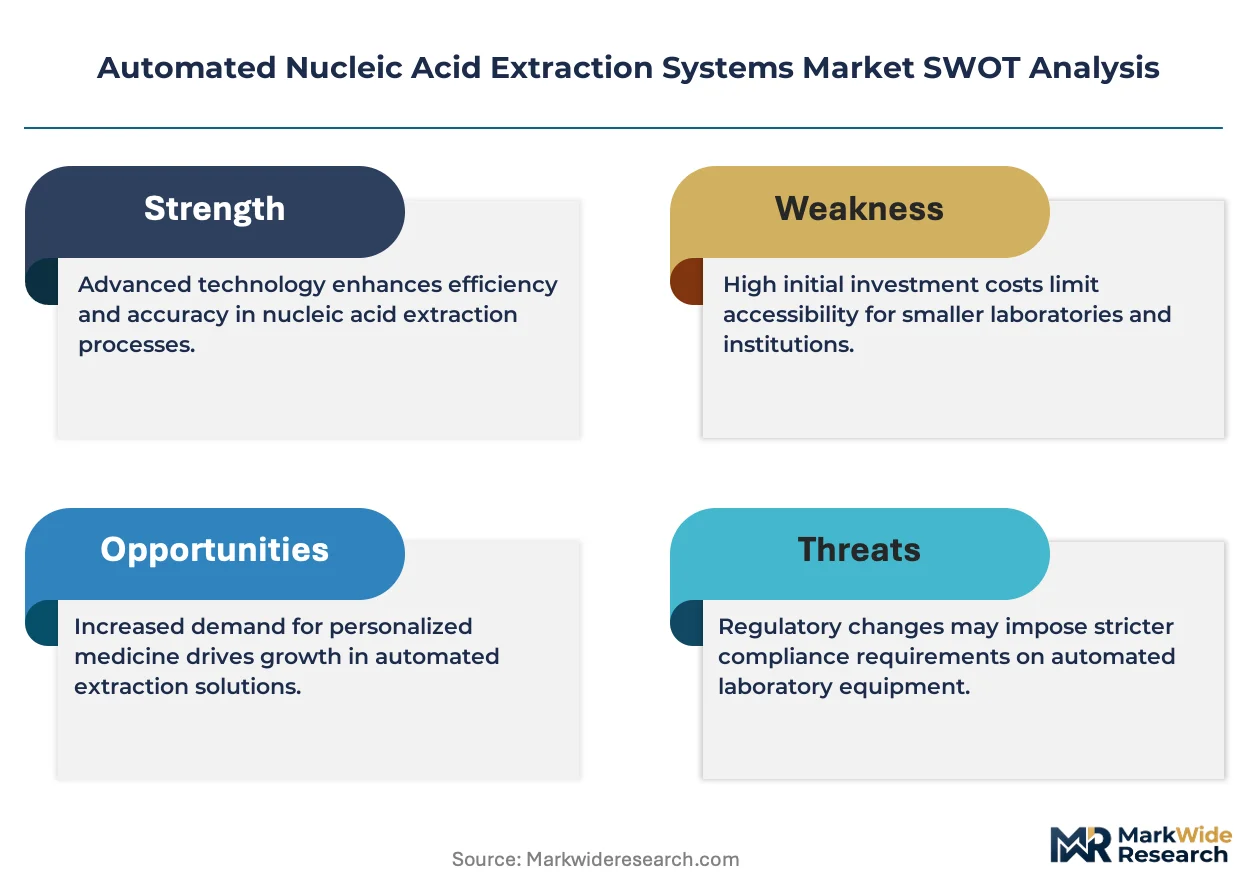
- IVDR Conformity Deadlines:European laboratories are accelerating automated platform procurement to meet EU IVDR traceability mandates for diagnostic workflows.
- Multiplexed Assay Expansion:CRISPR-based diagnostics and expanded respiratory panels require extraction fidelity that only automated magnetic bead systems deliver at scale.
- Forensic Genomics Backlogs:Government crime laboratories in the United States are modernizing infrastructure to clear DNA processing queues.
Market Restraints
- Reagent Supply Concentration:Proprietary magnetic bead chemistries from single-source suppliers create vulnerability for mid-sized clinical laboratories.
- Capital Equipment Cycles:Hospital capital expenditure committees extend replacement timelines for extraction platforms beyond typical seven-year depreciation schedules.
- Manual Protocol Persistence:Low-throughput research settings retain silica column methods due to per-sample cost advantages below fifty extractions monthly.
Strategic Opportunities
- Point-of-Care Microfluidics:Miniaturized cartridge-based systems are penetrating urgent care and pharmacy clinic networks where central lab turnaround times fail.
- India CDSCO Streamlining:Recent regulatory harmonization efforts reduce import certification timelines for automated nucleic acid platforms.
- Pharmaceutical Biobanking:Contract research organizations are integrating extraction systems into sample management infrastructure for longitudinal biomarker studies.
Industry Challenges
- Cross-Platform Integration:Laboratory information management systems require custom middleware development to connect extraction outputs with downstream sequencing pipelines.
- Technician Specialization Gaps:Clinical laboratories face recruitment friction for personnel trained in both wet chemistry automation and quality control documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Nucleic Acid Extraction Systems Market |
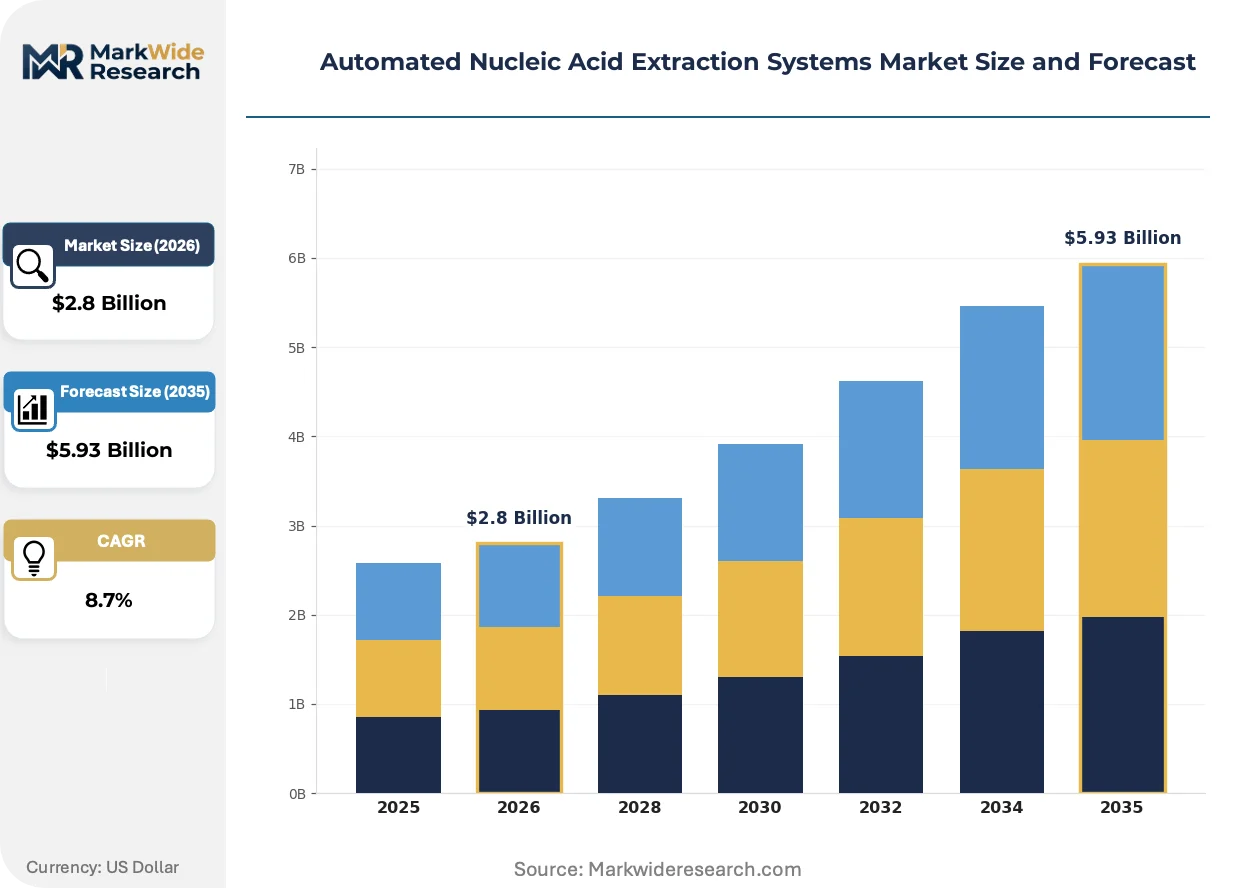
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Bead-Based, Column-Based, Microfluidic, Electrochemical Application: Clinical Diagnostics, Forensic Analysis, Research Applications, Food Safety Testing End User: Hospitals, Blood Banks, Research Laboratories, Diagnostics Companies Technology: Automated Liquid Handling, Robotics, Software Integration, Thermal Cycling |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Roche Diagnostics, Analytik Jena, Promega Corporation, PerkinElmer, Tecan Group, Bioneer Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Nucleic Acid Extraction Systems Market Strategic Shifts
Workflow compression and regulatory precision are redefining competitive advantage across extraction platform categories. Vendors are racing to collapse manual intervention points while anticipating evolving premarket submission requirements.
Microfluidic cartridge architectures are collapsing the physical footprint and sample-to-answer time for nucleic acid extraction. Point-of-care molecular testing networks in pharmacy chains and urgent care clinics are adopting these systems to bypass central laboratory logistics. The structural consequence is collapsing the traditional boundary between sample collection sites and diagnostic processing infrastructure.
EU IVDR technical documentation requirements are forcing manufacturers to revalidate legacy extraction protocols with expanded clinical performance data. This regulatory burden disproportionately affects mid-tier instrument vendors lacking dedicated regulatory affairs teams. European notified bodies are extending review timelines, compressing product launch windows and favoring established players with prior MDR submission experience.
Service unbundling is fragmenting traditional instrument-reagent bundling contracts. Hospital procurement departments are negotiating extraction consumables separately from platform hardware, pressuring vendor margin structures. This behavior is most pronounced in United States integrated delivery networks where group purchasing organizations consolidate laboratory supply negotiations across multiple member facilities.
Automated Nucleic Acid Extraction Systems Market Segmentation
Automated nucleic acid extraction systems fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct procurement patterns, margin structures, and competitive dynamics that shape vendor positioning.
Product Type:
Extraction chemistry fundamentally determines throughput ceiling, sample compatibility, and regulatory validation burden across laboratory workflows.
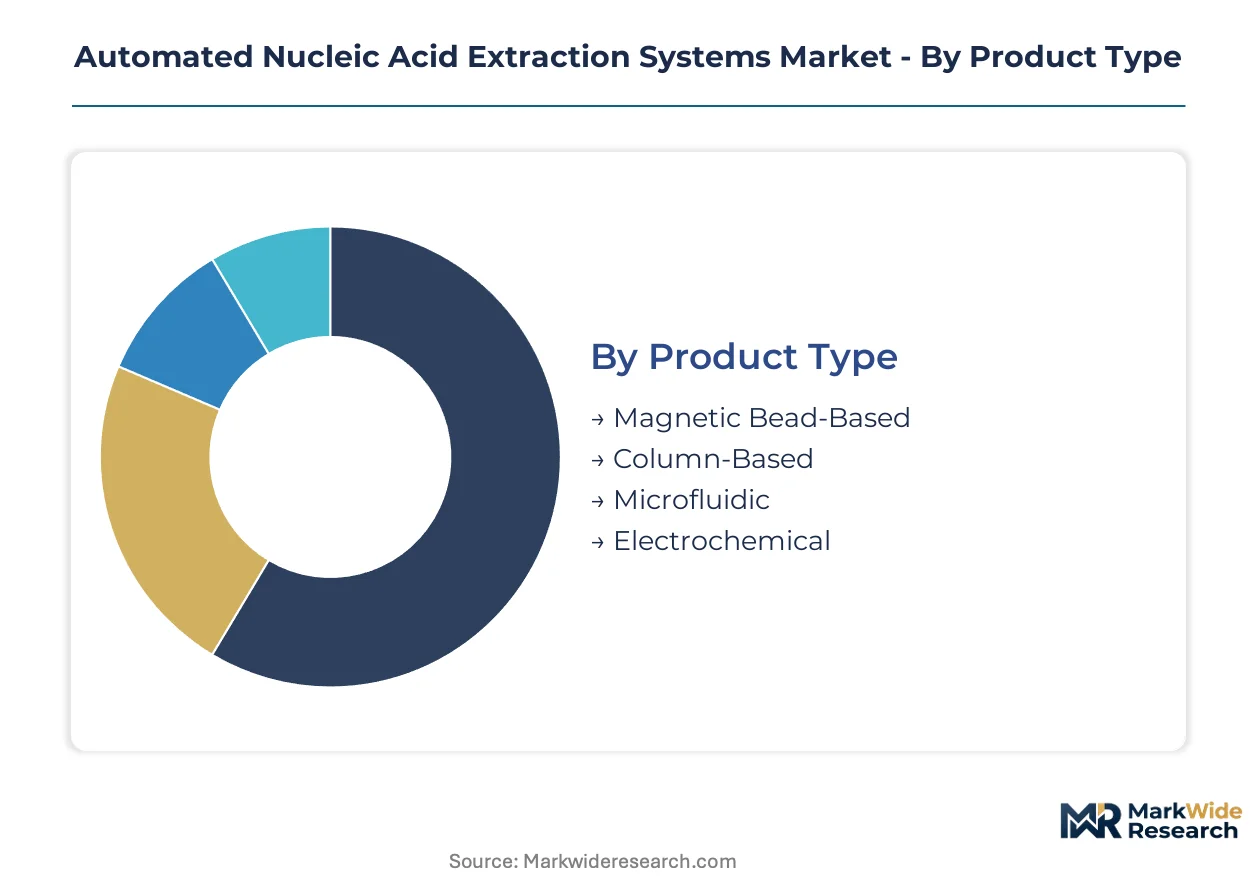
- Magnetic Bead-Based:Silica-coated paramagnetic particles bind nucleic acids through reversible charge interactions, enabling high-purity yields from blood, tissue, and viral transport media. Hospital clinical laboratories in the United States deploy these platforms for respiratory panel and oncology liquid biopsy workflows where FDA-cleared protocols reduce validation overhead.
- Microfluidic:Cartridge-integrated microchannels process microliter-scale samples through pressure-driven or electroosmotic flow, collapsing extraction time to under fifteen minutes. Urgent care networks and pharmacy clinic chains adopt these systems where central lab logistics create unacceptable turnaround delays for point-of-care infectious disease testing.
- Column-Based:Silica membrane spin columns rely on centrifugal force for buffer exchange, retaining cost advantages in research settings with monthly extraction volumes below fifty samples.
- Electrochemical:Voltage-driven nucleic acid release from functionalized electrodes eliminates magnetic bead reagent costs, finding niche adoption in resource-constrained field diagnostics.
The dominant share belongs to Magnetic Bead-Based systems, while Microfluidic architectures are closing the gap fastest.
Application:
Regulatory stringency and sample complexity create divergent performance requirements across use cases.
- Clinical Diagnostics:In vitro diagnostic workflows demand extraction fidelity for PCR, NGS, and CRISPR-based assays with documented traceability under FDA 21 CFR Part 820 quality system regulations. Hospital central laboratories command premium pricing for pre-validated extraction modules that compress time-to-result for sepsis and oncology panels.
- Research Applications:Academic and government laboratories prioritize flexibility across sample types over regulatory documentation, accepting manual intervention points that clinical settings reject.
- Forensic Analysis:CODIS-compliant DNA processing requires extraction systems with documented contamination controls and chain-of-custody protocols for evidence admissibility.
- Food Safety Testing:Pathogen detection from complex matrices—meat, produce, environmental swabs—drives demand for robust lysis chemistry compatible with automated platforms.
Clinical Diagnostics commands the largest revenue pool, though Research Applications sustain the broadest installed base across geographies.
End User:
Capital allocation authority and workflow integration requirements differentiate procurement behavior across customer categories.
- Hospitals:Integrated delivery networks negotiate multi-year service contracts bundling extraction platforms with downstream sequencing infrastructure, prioritizing walk-away automation that reduces FTE requirements in high-throughput molecular pathology departments.
- Research Laboratories:Principal investigators weigh per-sample reagent costs against instrument depreciation, frequently retaining manual column methods for grant-funded projects with irregular sample flow.
- Diagnostics Companies:Contract manufacturers and reference laboratories scale extraction capacity to support commercial assay production, demanding platforms with open-system architectures that accommodate custom buffer formulations.
- Blood Banks:Nucleic acid testing for transfusion-transmitted infections requires high-reliability systems with redundant sample tracking and automated flagging of hemolyzed or insufficient-volume donations.
Hospitals anchor instrument revenue through capital replacement cycles, while Diagnostics Companies generate the steepest consumable pull-through per installed unit.
Technology:
Mechanical and digital subsystems determine extraction reproducibility and interoperability with laboratory information management infrastructure.
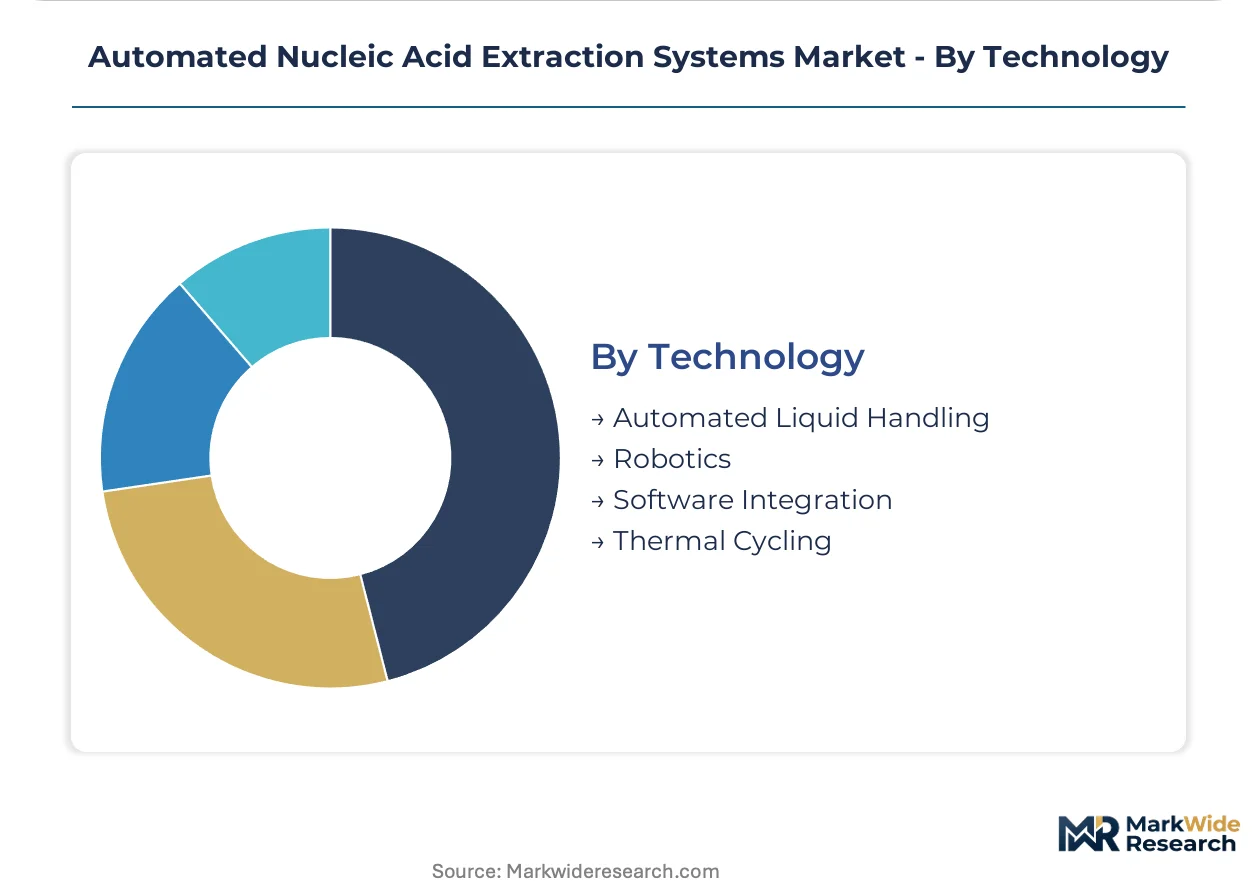
- Automated Liquid Handling:Precision pipetting modules with sub-microliter accuracy standardize reagent addition and wash steps, forming the mechanical foundation of high-throughput extraction platforms deployed in reference laboratories.
- Software Integration:Middleware connectivity to LIMS and electronic medical record systems enables sample tracking from accessioning through result reporting, a mandatory capability for CAP-accredited clinical laboratories.
- Robotics:Gantry-based or articulated arm systems manipulate labware across temperature-controlled stations, reducing technician exposure to infectious samples in biosafety level-3 facilities.
- Thermal Cycling:Integrated heating and cooling blocks execute lysis and elution temperature protocols, with Peltier-based systems dominating over resistive heaters for energy efficiency in continuous-operation settings.
Automated Liquid Handling captures the dominant technology share, while Software Integration is expanding most quickly as interoperability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital laboratories exhibit the lowest price elasticity, absorbing premium extraction platforms where FDA-cleared workflows compress validation timelines. Indian diagnostic chains and Chinese tier-two hospitals display acute sensitivity to per-sample reagent costs, driving procurement toward open-system architectures with competitive consumable sourcing.
United States
Hospital central laboratories and integrated delivery networks command walk-away automation for high-throughput molecular pathology, with respiratory panel and oncology liquid biopsy volumes surging. FDA 21 CFR Part 820 quality system regulations and ongoing guidance updates for in vitro diagnostic devices elevate validation standards. The Boston-Cambridge biotech corridor and Research Triangle Park anchor concentrated demand from academic medical centers and CRO biobanking operations.
Germany
University hospital networks and private reference laboratories drive replacement of legacy manual protocols ahead of EU IVDR conformity deadlines. EMA and notified body oversight of companion diagnostics creates stringent documentation requirements for extraction fidelity in precision oncology workflows. The Munich-Stuttgart industrial belt hosts dense clusters of diagnostics manufacturers integrating automated platforms into commercial assay production lines.
China
NMPA registration processes for imported systems create certification burdens that domestic manufacturers exploit through accelerated local approval pathways. NMPA and MIIT oversight of medical device quality management shapes competitive access for multinational vendors. Shanghai and Suzhou biotech parks concentrate demand from pharmaceutical R&D facilities and emerging contract research organizations scaling nucleic acid testing capacity.
India
Private diagnostic chains and government reference laboratories expand automated extraction capacity to handle rising molecular testing volumes for infectious disease surveillance. CDSCO streamlining of import certification timelines reduces barriers for multinational platform vendors. The Mumbai-Pune pharmaceutical corridor and Bengaluru biotech cluster anchor concentrated procurement from CROs and academic research institutions.
Japan
Hospital clinical laboratories and blood bank networks prioritize high-reliability systems with redundant sample tracking for transfusion-transmitted infection screening. PMDA and METI oversight of medical device manufacturing standards governs market access for extraction platform vendors. The Osaka-Kobe medical device manufacturing belt and Tokyo-Yokohama metropolitan area concentrate demand from precision medicine initiatives and aging-population diagnostics programs.
Automated Nucleic Acid Extraction Systems Market Competitive Environment
Capability concentration sits with diversified life science conglomerates possessing integrated workflow portfolios; scale advantage sits with specialized diagnostics manufacturers with dedicated installed bases. The vendor landscape organizes into three tiers: diversified platform conglomerates with global service networks, mid-sized specialists with regional regulatory expertise, and emerging microfluidic innovators targeting point-of-care decentralization. Dominant competitive moves include strategic partnerships between instrument manufacturers and assay developers, plus geographic expansion through distributor networks in underpenetrated Asian markets.
Among diversified life science conglomerates, Thermo Fisher Scientific, QIAGEN, and Roche Diagnostics occupy positions exemplifying distinct competitive archetypes. Thermo Fisher Scientific represents the installed-base-leverage model, QIAGEN anchors the integrated-workflow positioning, and Roche Diagnostics exemplifies high-throughput hospital laboratory dominance. These three entities collectively illustrate how vendor economics migrate between instrument sales and recurring consumables pull-through across clinical and research account segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Roche Diagnostics |
| Analytik Jena |
| Promega Corporation |
| PerkinElmer |
| Tecan Group |
| Bioneer Corporation |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Suzhou's precision manufacturing corridor anchors magnetic bead reagent production capacity, concentrating supply-side leverage among domestic Chinese producers who dictate pricing tiers for mid-sized clinical laboratories in India and Southeast Asia. This geographic clustering amplifies vendor pricing power for proprietary extraction chemistries while compressing margins for instrument manufacturers competing on open-system architectures.
Pricing Analysis
Aftermarket service contracts and multi-year reagent subscription tiers drive lifetime value for extraction platform vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance status and throughput specifications, with hospital integrated delivery networks absorbing premium tiers while research laboratories gravitate toward economy configurations. Pricing pressure stems from group purchasing organization consolidation across United States health systems. Diagnostics companies exhibit acute price sensitivity due to per-sample cost accounting, whereas blood bank networks prioritize reliability over unit economics.
Supply Chain Analysis
Contract manufacturing for precision liquid handling modules concentrates among specialized EMS providers in Germany, Japan, and the United States. Neodymium-iron-boron magnetic beads, silica membrane substrates, and thermoplastic cartridge housings constitute critical input dependencies. Single-source vulnerability for rare-earth magnet supply creates exposure to export restriction volatility. Distribution runs through authorized distributor networks in regulated markets and direct procurement channels for high-volume reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA-cleared protocol libraries and ISO 13485 quality system documentation create switching costs that lock hospital laboratories into incumbent vendor ecosystems.
For Market Incumbents: Entrench position through backward integration into magnetic bead chemistry production, eliminating third-party reagent margin leakage. Deepen regulatory moats by accelerating EU IVDR technical documentation for legacy platform portfolios. Emerging microfluidic innovators threaten point-of-care decentralization; counter by embedding extraction modules into automated sequencing pipelines that hospital LIMS infrastructure already supports. For New Entrants and Emerging Players: Build out open-system architectures targeting Indian diagnostic chains and Chinese tier-two hospitals where per-sample reagent cost sensitivity exceeds brand loyalty. Pharmacy clinic networks represent the most penetrable end-use segment for cartridge-based microfluidic platforms. Pursue CDSCO and NMPA registration pathways ahead of FDA submission to compress time-to-revenue in cost-sensitive geographies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized diagnostics manufacturers with captive installed bases over diversified life science conglomerates facing portfolio complexity drag. Five-to-ten year viability hinges on consumable pull-through sustainability rather than instrument replacement cycles. Acquisition target archetype: regional regulatory specialists with established notified body relationships in Europe. Signal to watch: consolidation of group purchasing organization contracts around single-source reagent agreements as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Extraction Module | Clears hospital laboratory procurement pathways under 21 CFR Part 820 quality system requirements. |
| EU IVDR Technical Documentation Completion | Enables continued market access as notified body review timelines extend for legacy protocols. |
| Hospital System Partnership Agreement | Locks multi-year consumable commitments through integrated delivery network group purchasing structures. |
| Software Companion Development for LIMS Integration | Reduces middleware friction that currently delays extraction-to-sequencing pipeline connectivity. |
| Reimbursement Strategy for Point-of-Care Testing | Secures CPT code alignment for microfluidic cartridge-based infectious disease panel workflows. |
Study Parameters
The analysis maps magnetic bead-based, microfluidic, column-based, and electrochemical extraction sub-sectors, each validated through laboratory directors, biomedical engineers, hospital procurement managers, and GPO contracts specialists. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU IVDR technical documentation databases, hospital procurement records, and SEC instrument revenue disclosures. Bottom-up instrument shipment tracking and top-down reagent consumption modeling triangulate market sizing across the projection horizon.
Assumptions held fixed include regulatory pathway timelines for FDA clearance and EU IVDR conformity, while variables included hospital capital expenditure committee replacement cycles and point-of-care testing adoption curves. Segmentation dimensions modeled encompass product chemistry type, application workflow, end-user category, and regional regulatory cluster. CAGRs derive from regression analysis against molecular testing volume growth and instrument replacement elasticity. Forecast inputs incorporate multiplexed assay panel expansion rates and forensic genomics backlog clearance timelines.
Practitioners should monitor NMPA import certification streamlining, CDSCO harmonization progress, and group purchasing organization contract consolidation for early signals of competitive access shifts. Forecasts reflect assumptions about sustained hospital laboratory automation investment and point-of-care network penetration. Quarterly review of notified body review timeline extensions, rare-earth magnet export policy adjustments, and respiratory panel reimbursement coding is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market